
 Passenger Ferries Market | 2026-2036
Passenger Ferries Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Ferries Market Analysis
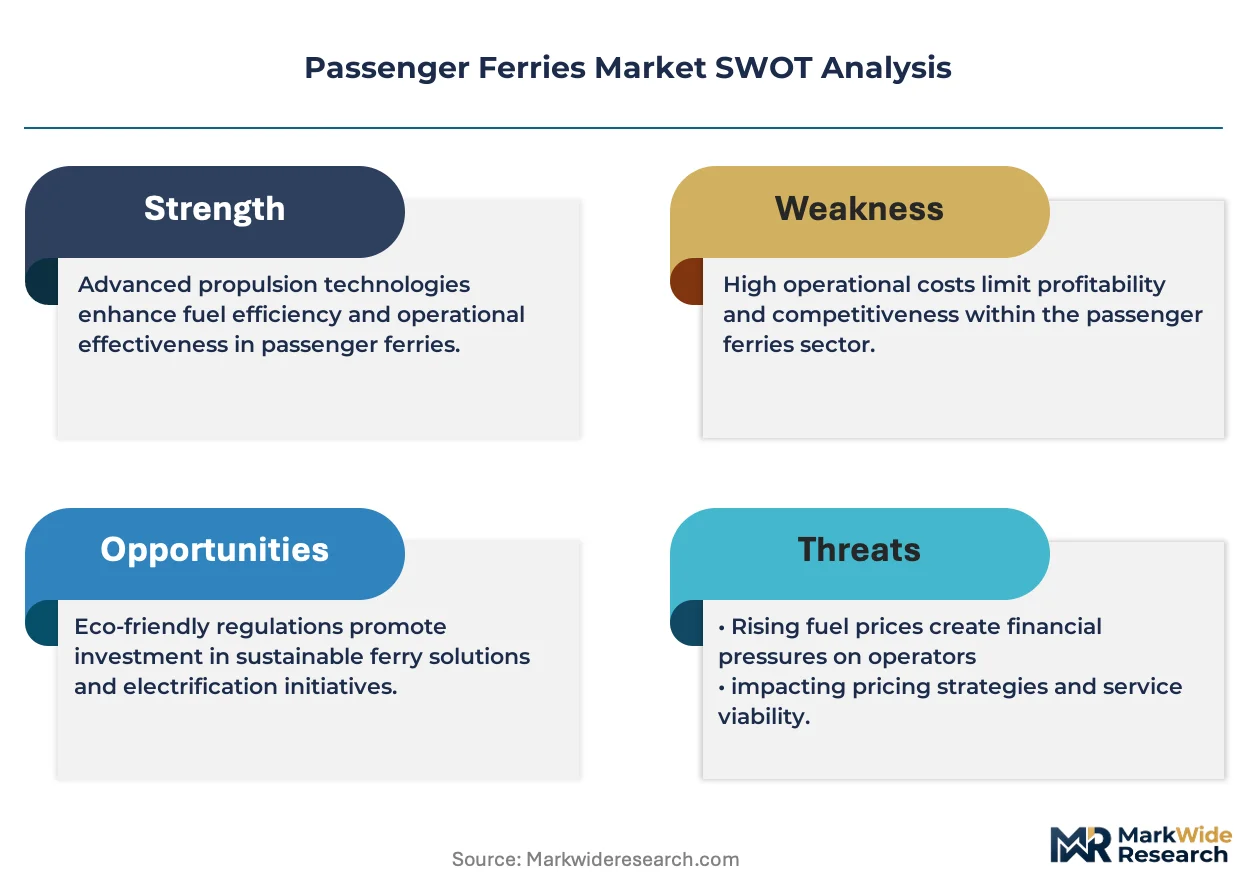
IMO 2023 carbon intensity regulations is rebalancing capital allocation toward dual-fuel propulsion systems. DFDS leverages its North European route density to sustain high vessel utilization rates. Stena Line anchors its competitive position through integrated port-terminal ownership. Grimaldi Group specializes in rolling cargo-passenger hybrid operations across Mediterranean corridors.
Passenger ferries are motorized vessels designed to transport people, vehicles, and cargo across water on fixed routes, typically ranging from 30 to 200 meters in length with hull forms optimized for harbor maneuverability and sea state resilience. Their primary commercial purpose is to provide scheduled maritime connectivity where bridge or tunnel infrastructure is economically or physically impractical. Conventional ferries still dominate total fleet tonnage but carry thinner margins due to fuel exposure, while hybrid ferries command premium positioning as port authorities in Copenhagen, Amsterdam, and Vancouver impose escalating emissions tariffs. High-speed ferries occupy a niche growth tier on routes under 100 nautical miles where time savings justify elevated ticket pricing.
The European Maritime Safety Agency enforces design and equipment standards under the EU Ship Recycling Regulation and MDR-linked conformity protocols, while the US Coast Guard administers passenger vessel certification under 46 CFR subchapter T. Indonesia's Ministry of Transportation mandates domestic build requirements through cabotage-linked licensing, shaping fleet procurement for operators like PT ASDP Indonesia Ferries. Stakeholders must weigh retrofit timelines against newbuild delivery slots as fuel technology pathways remain unsettled.
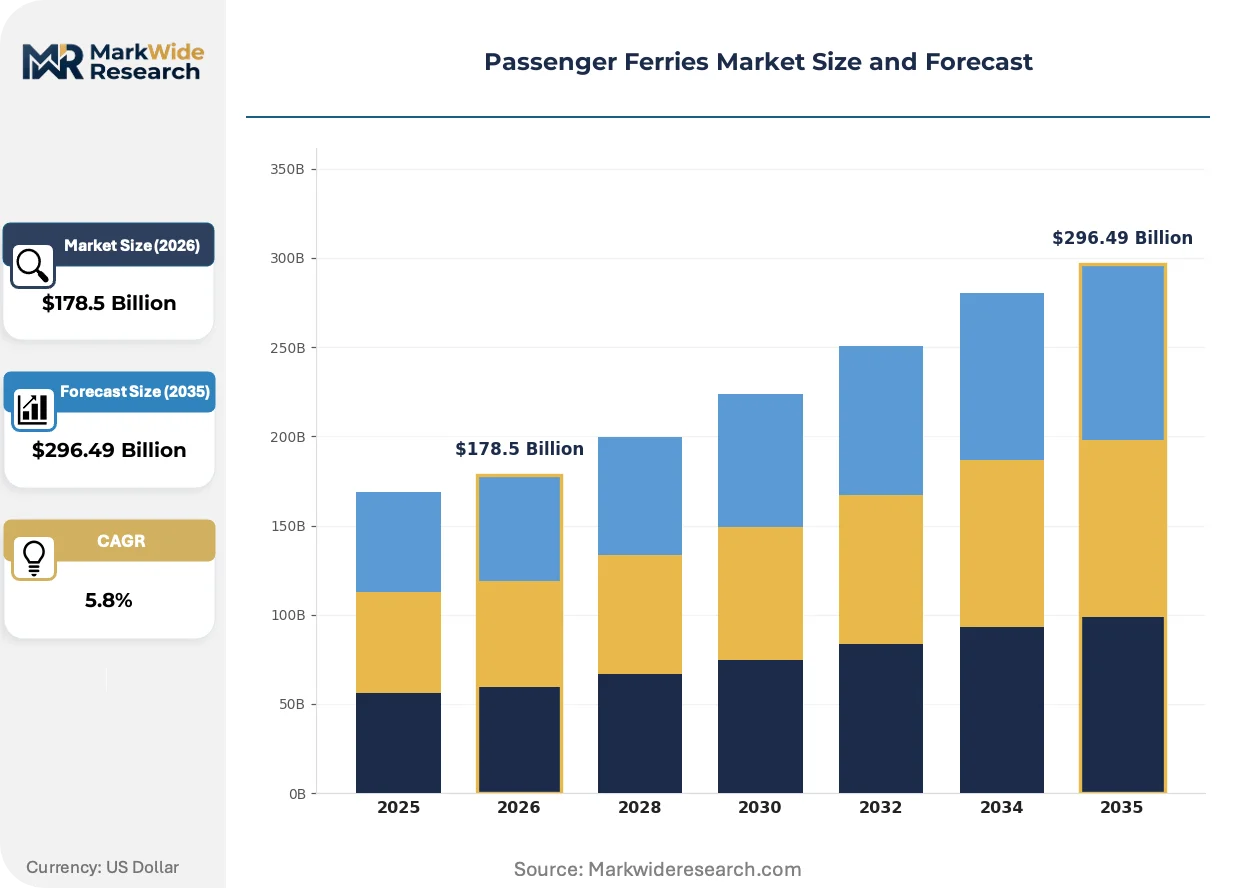
Market Dynamics
The EU Green Deal's marine fuel standards are compressing retrofit timelines while Indonesian archipelagic demand pulls newbuild orders toward dual-fuel configurations. Fleet operators face simultaneous pressure to decarbonize existing tonnage and expand capacity on high-density island corridors.
Growth Catalysts
- EU Green Deal marine fuel standards:Mandates under the F-Gas Regulation and linked decarbonization frameworks are compelling operators to accelerate vessel replacement cycles.
- Island-hopping tourism corridors:Southeast Asian archipelagic routes in Indonesia and the Philippines are generating concentrated fleet demand from domestic and international carriers.
- Dual-fuel propulsion systems:LNG-ammonia hybrid engine technology is reducing carbon intensity metrics while preserving operational flexibility across variable route lengths.
Market Restraints
- Marine-grade steel price volatility:Hull construction material costs fluctuate with energy-intensive smelting input prices, squeezing newbuild margins.
- Engine manufacturer concentration:Specialized dual-fuel propulsion system supply concentrates among a limited set of European and Asian powertrain integrators.
- Battery energy density limitations:Current lithium-ion configurations cannot support full-electric operations on routes exceeding fifty nautical miles without unacceptable weight penalties.
Strategic Opportunities
- Indonesia's domestic build incentives:Cabotage-linked licensing requirements create protected demand for locally constructed vessels serving ASDP Indonesia Ferries routes.
- Port-terminal integration:Copenhagen, Amsterdam, and Vancouver port authorities are implementing escalating emissions tariffs that reward captive terminal ownership.
- Ammonia bunkering infrastructure:Early-mover investment in zero-carbon fuel supply chains at North European hub ports is securing preferential berthing access.
Industry Challenges
- Marine engineer skill scarcity:Dual-fuel system maintenance and ammonia handling protocols require specialized certification programs that outpace current training pipeline capacity.
- Retrofit yard slot congestion:Limited drydock availability at Southeast Asian and Mediterranean facilities is extending vessel downtime during emissions compliance upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Ferries Market |
| Market Size in 2026 | $178.5 Billion |
| Market Size in 2035 | $296.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Cruise Ferries, High-Speed Ferries, Conventional Ferries, Hybrid Ferries Service Type: Scheduled Services, Charter Services, Emergency Services, Tourist Services Passenger Capacity: Under 100, 100-300, 301-600, Over 600 Fuel Type: Diesel, LNG, Electric, Hybrid |
| Companies Covered | DFDS, BC Ferries, Stena Line, Brittany Ferries, Attica Group, Grimaldi Group, PT ASDP Indonesia Ferries, Austal, Tallink Grupp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Ferries Market Emerging Trajectories
Propulsion technology divergence is fragmenting fleet standardization as operators place parallel bets on ammonia, methanol, and hybrid-electric pathways. Regulatory jurisdictions are racing to establish certification precedents that will lock in dominant fuel technologies for the 2035-2040 replacement wave.
Hybrid-electric propulsion architectures are rewriting operational economics on short-sea routes. Copenhagen's port authority mandates are accelerating adoption among Baltic Sea operators. The technology is compressing fuel cost exposure while extending vessel service intervals through reduced mechanical wear.
REACH-linked marine fuel certification protocols are restructuring supplier qualification requirements. EU MDR conformity assessments now extend to fuel system components, adding documentation burdens. Mediterranean route operators are consolidating procurement to reduce compliance transaction costs.
Route-specific charter contracts are displacing traditional vessel ownership models in Southeast Asian corridors. Indonesian domestic operators are leasing tonnage from Singapore-based fleet managers to match seasonal demand swings. This pattern is most visible on Bali-Lombok and Java-Sumatra trunk routes where traffic fluctuates with religious holiday calendars.
Passenger Ferries Market Segmentation
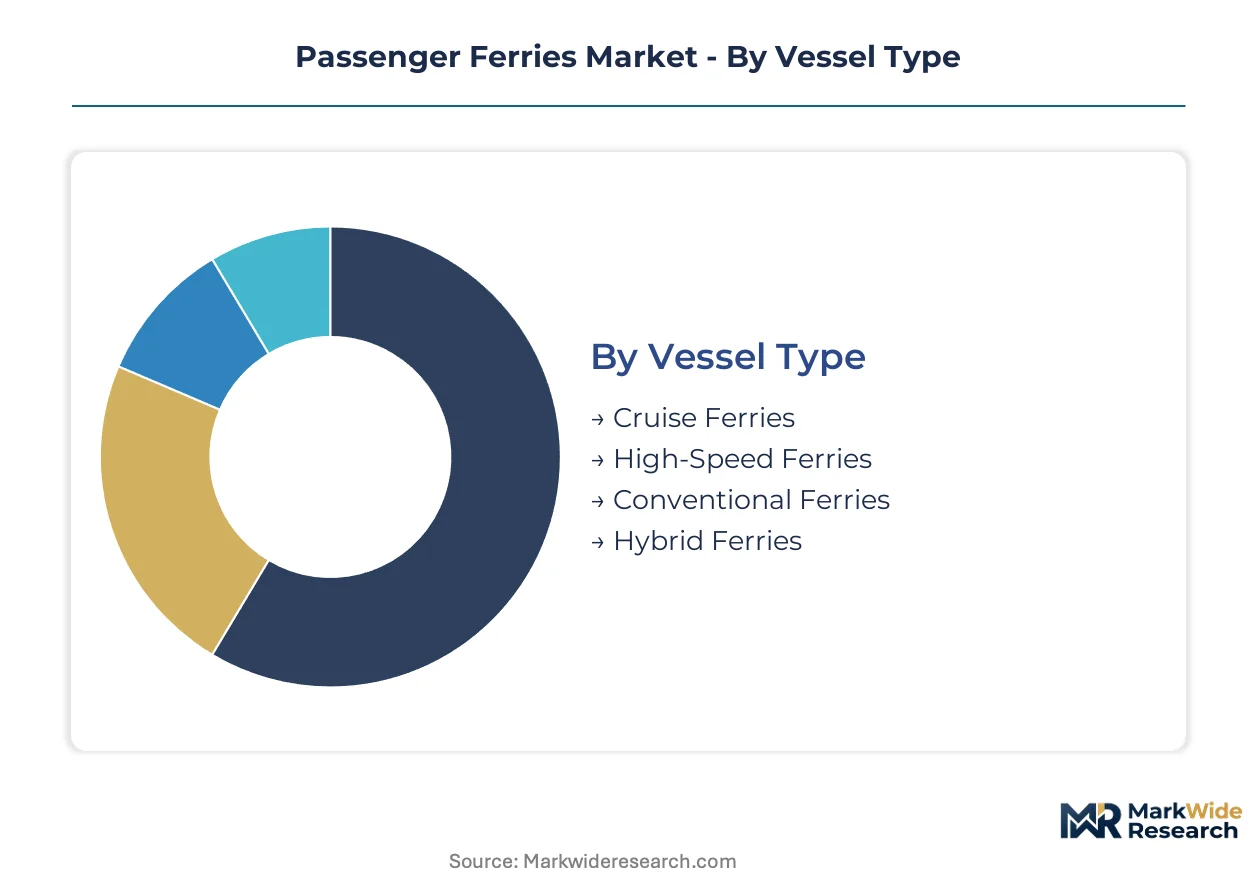
Passenger ferry segmentation reveals how vessel economics fragment across route distance, port infrastructure maturity, and regulatory pressure gradients. Operators configure fleet mix against specific corridor characteristics rather than deploying standardized platforms.
Vessel Type:
Standardization dominates hull architecture at the low end, while premium tiers demand heavy customization for route-specific seakeeping and passenger amenity loads.
- Cruise Ferries:These vessels integrate overnight accommodation, entertainment facilities, and vehicle decks for routes exceeding twelve hours. Baltic Sea corridors between Finland and Sweden concentrate demand, driven by leisure travel substitution for short-haul aviation.
- High-Speed Ferries:Lightweight aluminum or composite hulls with waterjet propulsion sustain speeds above thirty-five knots on routes under one hundred nautical miles. Greek island clusters and Indonesia's Bali-Lombok strait represent dense deployment zones where time savings command ticket premiums.
- Conventional Ferries:Steel-hulled workhorses optimized for harbor maneuverability and heavy-weather resilience across variable sea states. Indonesian archipelagic trunk routes and Mediterranean short-sea corridors absorb the largest fleet volumes.
- Hybrid Ferries:Battery-diesel or battery-LNG electric architectures reduce fuel exposure and emissions profile. Copenhagen, Amsterdam, and Vancouver port tariffs are accelerating adoption on subsidized municipal routes.
Leading the category by volume: Conventional Ferries. Expanding most quickly: Hybrid Ferries.
Service Type:
Contract structure determines capital intensity exposure, with ownership models fragmenting between integrated operators and third-party fleet managers across different route economics.
- Scheduled Services:Fixed-route, fixed-timetable operations with published tariffs and advance booking systems. DFDS and Stena Line anchor their business models on this structure, extracting utilization efficiency through route density.
- Charter Services:Vessels deployed under temporary contract to match seasonal demand swings or specific event logistics. Indonesian operators lease tonnage from Singapore-based managers during Ramadan and Eid travel peaks.
- Emergency Services:Standby vessels maintained for disaster response, medical evacuation, or infrastructure failure backup. Philippines' coast guard and Indonesian disaster mitigation agencies maintain dedicated fleets.
- Tourist Services:Purpose-built or converted vessels for scenic coastal routes, wildlife viewing, or heritage harbor circuits. Norway's fjord corridors and Croatia's Dalmatian coast support specialized operators.
Dominant by revenue: Scheduled Services. Steepest expansion trajectory: Tourist Services.
Passenger Capacity:
Scale economies in vessel construction create sharp cost-per-seat inflection points that shape procurement decisions across different route density profiles.
- Under 100:Compact vessels serving thin-density routes, harbor shuttles, or last-mile island connections. Greek minor islands and Indonesia's outer archipelago feeder routes concentrate this segment.
- 100-300:Mid-scale platforms balancing capital efficiency against frequency flexibility. Mediterranean secondary routes and Baltic Sea seasonal services favor this configuration.
- 301-600:High-volume workhorses for major strait crossings and trunk corridor substitution. Java-Sumatra and Sicily-mainland Italy routes deploy this scale intensively.
- Over 600:Maximum-scale vessels amortizing construction cost across dense, high-frequency corridors. English Channel operators and Helsinki-Tallinn routes justify this capacity tier.
Highest unit volume: 100-300 capacity tier. Gaining share fastest: Under 100.
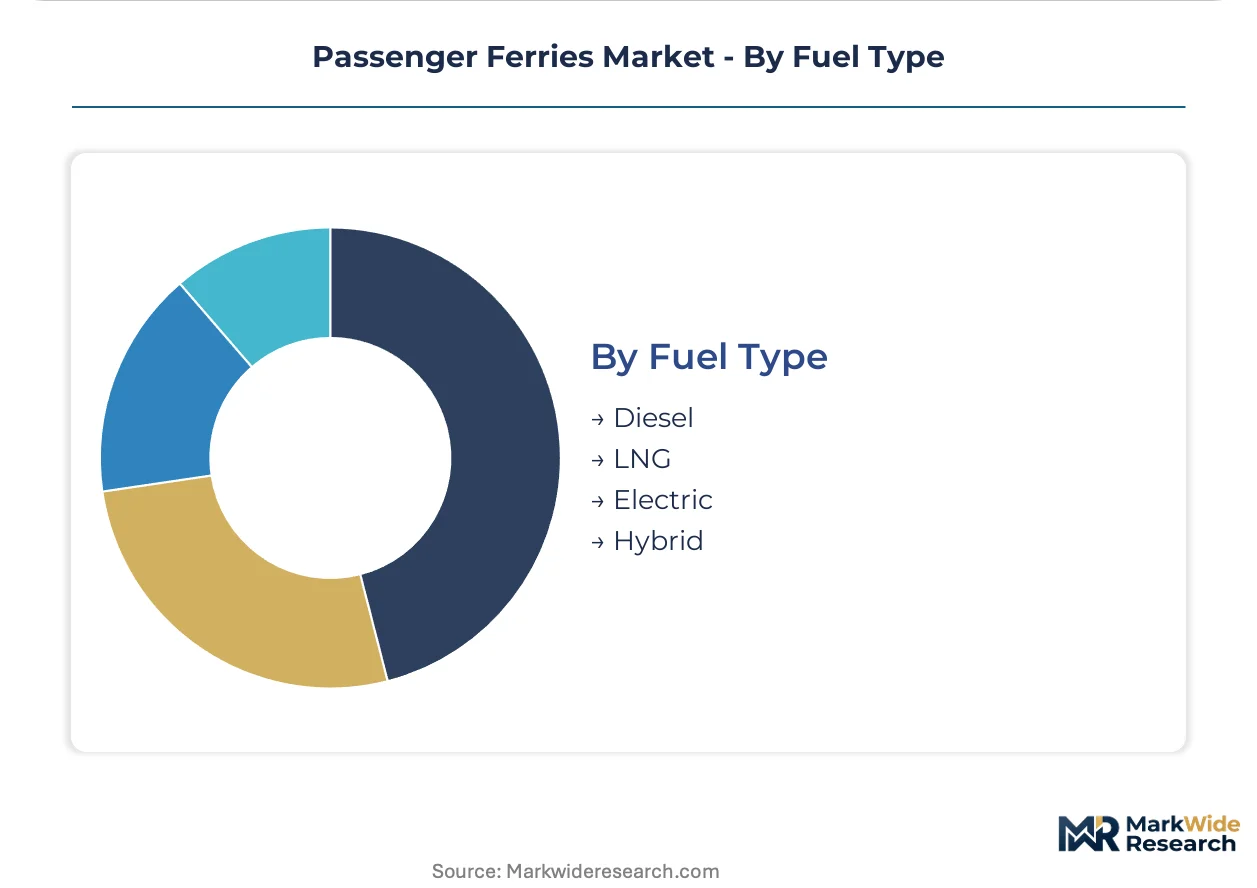
Fuel Type:
Technology pathway uncertainty is fragmenting procurement standards as operators place parallel bets against evolving EU Green Deal and IMO carbon intensity mandates.
- Diesel:Mature infrastructure and lowest capital cost maintain residual demand, though margins compress under escalating emissions tariffs. Legacy fleet retention dominates in Southeast Asian markets with limited bunkering alternatives.
- LNG:Established dual-fuel engine platforms with measurable carbon intensity reduction and existing bunkering infrastructure at North European hub ports. Baltic and North Sea operators lead deployment.
- Electric:Full-battery configurations constrained to routes under fifty nautical miles by energy density limitations. Norwegian fjord routes and Danish domestic services pioneer this architecture.
- Hybrid:Diesel-electric or LNG-electric systems optimizing load profiles across variable operating conditions. Copenhagen port mandates and Amsterdam emissions tariffs accelerate adoption.
Installed base leader: Diesel. Climbing the fastest: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's archipelagic corridors concentrate the heaviest fleet demand, while EU Green Deal mandates reshape vessel procurement across North European routes. Regulatory divergence between these poles fragments capital allocation strategies.
Indonesia
Java-Sumatra and Bali-Lombok trunk routes absorb the largest newbuild volumes, driven by religious holiday travel peaks and inter-island commerce. The Ministry of Transportation enforces cabotage-linked domestic build requirements through licensing protocols. Surabaya's shipyard cluster processes the majority of ASDP Indonesia Ferries orders under these protected procurement rules.
Germany
Baltic Sea corridor density between Kiel and Scandinavian ports sustains high-frequency service requirements. The EU F-Gas Regulation and linked MDR conformity protocols mandate dual-fuel propulsion retrofits. Hamburg's port-terminal complex anchors Grimaldi Group's rolling cargo-passenger hybrid operations.
Denmark
Copenhagen port authority emissions tariffs compress conventional ferry margins and accelerate hybrid-electric adoption. The EU Green Deal marine fuel standards enforce escalating carbon intensity benchmarks. DFDS leverages its North European route density from Copenhagen terminals to sustain utilization rates above regional averages.
Canada
British Columbia's island-hopping tourism routes and coastal indigenous community connectivity generate specialized vessel demand. Transport Canada administers passenger vessel certification under domestic marine safety regulations. Vancouver's port authority implements emissions tariffs that mirror Copenhagen's tariff structure, rewarding low-carbon fleet investments.
Greece
Aegean island cluster connectivity depends on high-speed ferry services where time savings justify premium ticket pricing. The European Maritime Safety Agency enforces design standards under EU Ship Recycling Regulation protocols. Piraeus serves as Attica Group's operational hub for Cyclades and Dodecanese route networks.
Passenger Ferries Market Vendor Landscape
North European operators anchor one tier; Southeast Asian specialists hold protected domestic positions under cabotage regimes. Market structure fragments across three strategic tiers: integrated route-density players, state-linked domestic operators, and hybrid-focused municipal service providers. Competitive moves concentrate on port-terminal integration and dual-fuel propulsion partnerships. Operators defend position through captive terminal ownership and early ammonia bunkering infrastructure commitments.
Within the integrated route-density tier, DFDS and Stena Line exemplify operators leveraging geographic concentration for utilization efficiency. PT ASDP Indonesia Ferries occupies a protected position under Indonesia's domestic build incentives, serving archipelagic corridors with limited foreign competition. Grimaldi Group represents the rolling cargo-passenger hybrid specialization, operating across Mediterranean corridors where vehicle freight subsidizes passenger service economics.
| Leading Market Players |
|---|
| DFDS |
| BC Ferries |
| Stena Line |
| Brittany Ferries |
| Attica Group |
| Grimaldi Group |
| PT ASDP Indonesia Ferries |
| Austal |
| Tallink Grupp |
| Others |
Supply Flow & Price Mechanics
Marine engineer concentration in North European shipyard clusters widens pricing spreads between premium dual-fuel vessels and conventional tonnage. Labor-cost differentials between German and Indonesian yard labor feed tiered vessel pricing that separates EU-compliant newbuilds from cabotage-protected domestic orders.
Pricing Analysis
Volume-heavy conventional ferry operators trade margin for utilization while hybrid-electric specialists capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates LNG-ammonia hybrid configurations from diesel legacy fleets and basic diesel-electric retrofits. Price differentiation rests on EU MDR certification grade and port emissions tariff exposure. Cost compression in standard-tier diesel ferries is intensifying because marine-grade steel volatility squeezes newbuild margins. State-linked Indonesian operators show lowest price sensitivity due to protected domestic build incentives, while Greek island-hopping charter services face acute ticket-price elasticity.
Supply Chain Analysis
Direct-to-operator channels handle fleet-scale procurement for integrated route-density players like DFDS and Stena Line, while broker-mediated spot contracting serves Southeast Asian seasonal charter demand. Geographic supply concentration centers on South Korean engine manufacturing, Chinese hull steel production, and European powertrain integration. Raw material dependencies draw from marine-grade steel plate, specialized dual-fuel engine blocks, and lithium-ion battery modules. Single-source vulnerability in ammonia-compatible propulsion systems from MAN Energy Solutions and Wärtsilä concentrates supply risk. Distribution runs through shipyard-direct contracting for newbuilds and Singapore-based fleet managers for secondary-market tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drydock slot scarcity at Southeast Asian and Mediterranean retrofit yards props vessel pricing power by extending compliance-driven replacement timelines. Fleet operators face simultaneous pressure to decarbonize and expand, yet yard capacity constraints limit supply response.
For Market Incumbents: Cement terminal ownership advantages at Copenhagen, Amsterdam, and Vancouver through early ammonia bunkering infrastructure commitments. Secure captive drydock partnerships at Surabaya and Hamburg to lock retrofit slots ahead of EU Green Deal enforcement waves. Vertical integration into port-terminal assets defends margin position against emissions-tariff exposure. For New Entrants and Emerging Players: Digital freight-forwarding platforms offer the lowest-friction entry path into Indonesian archipelagic charter markets. Target thin-density feeder routes in Indonesia's outer islands where ASDP Indonesia Ferries coverage gaps persist. White-space exists in hybrid-electric tourist vessels for Norway's fjord corridors and Croatia's Dalmatian coast. For Investors and Strategic Acquirers: Re-rating potential sits with dual-fuel retrofit specialists given IMO carbon intensity enforcement tightening. Long-term viability favors operators with locked yard capacity and port-terminal integration across the 2035 replacement wave. Watch ammonia bunkering infrastructure commitments at North European hub ports as inflection signal for technology pathway lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Propulsion Retrofit | EU F-Gas Regulation compliance preserves route access at Copenhagen and Amsterdam terminals. |
| Port-Terminal Integration | Captive ownership at Hamburg and Piraeus secures preferential berthing under escalating emissions tariffs. |
| Ammonia Bunkering Infrastructure | Early-mover investment at North European hubs locks fuel supply chain for 2035 fleet replacement. |
| Domestic Build Partnership | Surabaya shipyard alliances satisfy Indonesia's cabotage licensing for ASDP Indonesia Ferries procurement. |
| Hybrid-Electric Platform Development | Battery-diesel architectures meet Copenhagen port mandates while reducing mechanical wear costs. |
Methodological Framework
Independent corroboration across fleet operator procurement directors, marine engineering consultants, and port authority planning officers underwrites the qualitative findings. Primary interviews with shipyard project managers, dual-fuel engine manufacturer technical leads, and Indonesian Ministry of Transportation licensing officials combined with secondary validation. Secondary sources span Lloyd's Register vessel databases, IMO GHG strategy filings, EU MDR conformity assessment records, and customs trade data on marine-grade steel imports. Bottom-up vessel deployment counts triangulate against top-down route revenue estimates.
Rate-of-change decomposition separates volume growth in Indonesian archipelagic corridors from value uplift in EU-mandated dual-fuel retrofits across the analysis window. Segmentation dimensions modeled include vessel type, service contract structure, passenger capacity tier, and fuel technology pathway. CAGRs derive from fleet replacement cycle analysis against regulatory enforcement timelines. Industry-specific inputs incorporate EU Green Deal marine fuel standard phase-in schedules and Indonesia's religious holiday travel peak patterns.
The model holds under steady regulatory enforcement and stable marine steel pricing; deviation in IMO carbon intensity benchmark acceleration or ammonia engine certification delays would shift replacement timelines. Forecasts reflect documented assumptions on yard capacity expansion and dual-fuel engine manufacturer output scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Europe Maritime Information Market