
 Cofferdam Market | 2026-2036
Cofferdam Market Size, Share, and Industry Trends Forecast 2026-2036
Cofferdam Market Insights
Aging marine construction workforce capacity is collapsing across North American port authorities, forcing contractors toward prefabricated cofferdam systems that reduce field welding hours. DEEP EXCAVATION leverages proprietary shoring software to anchor its competitive position in deep-water foundation projects. JF BRENNAN sustains dominance through in-house dive teams that control installation quality across inland waterway contracts. ESC GROUP differentiates via European manufacturing scale that supplies sheet pile cells to African and Southeast Asian hydropower developers.
A cofferdam is a temporary or permanent watertight enclosure built within or across a body of water to create a dry work environment for construction, repair, or inspection activities; steel sheet pile configurations typically interlock through rolled Larssen or Frodingham sections driven to depths exceeding 15 meters to resist hydrostatic pressure and soil loading. Rigid cofferdams occupy the mature revenue core, with steel cellular designs commanding premium pricing on bridge pier projects where deflection tolerance sits below 25 millimeters. Flexible PVC and inflatable cofferdams represent the fastest-expanding material category, as polymer formulations improve puncture resistance for shallow-water pipeline maintenance where mobilization speed outweighs structural permanence.
OSHA Subpart P excavation standards and the U.S. Army Corps of Engineers EM 1110-2-1913 govern dewatering and worker access protocols, while EU CE marking under the Construction Products Regulation mandates structural steel conformity for permanent marine installations in European waters. EPA Section 404 permitting constrains wetland cofferdam deployment timelines, pushing contractors toward modular systems that minimize sediment disturbance during installation and removal. Stakeholders must monitor evolving coastal resilience funding allocations and pre-position fabrication capacity before federal infrastructure appropriation cycles compress bid-to-mobilization windows.
Market Dynamics
Hurricane resilience programs across Gulf Coast states are compressing replacement cycles for aging temporary water barriers, while municipal contractors face collapsing marine construction workforce capacity that pushes adoption toward prefabricated systems reducing field welding hours.
Growth Catalysts
- Bridge rehabilitation mandates:Federal infrastructure appropriations prioritize waterfront infrastructure renewal, accelerating cofferdam deployment for pier reconstruction projects.
- EPA Section 404 permitting constraints:Wetland protection requirements push contractors toward modular systems that minimize sediment disturbance during installation and removal cycles.
- Polymer formulation advances:Improved puncture resistance in flexible PVC and inflatable cofferdam materials expands shallow-water pipeline maintenance applications where speed outweighs permanence.
Market Restraints
- Steel input cost volatility:Larssen and Frodingham section prices fluctuate with global scrap metal markets, compressing margins on cellular cofferdam projects.
- European manufacturing concentration:Sheet pile cell supply for African and Southeast Asian hydropower developers routes through limited continental fabrication capacity.
- Deflection tolerance limitations:Bridge pier projects demanding sub-25 millimeter deflection exclude flexible polymer alternatives from premium structural applications.
Strategic Opportunities
- Gulf Coast state replacement cycles:Hurricane resilience programs in Louisiana, Texas, and Florida create sustained demand for certified flood-prone installation systems.
- Dive team integration models:In-house underwater installation quality control offers differentiation across inland waterway contracts.
- EU CE marking convergence:Construction Products Regulation structural steel conformity mandates open permanent marine installation opportunities in European waters.
Industry Challenges
- Field welding skill scarcity:Aging marine construction workforce capacity forces contractors toward prefabricated systems despite higher material costs.
- Bid-to-mobilization compression:Federal infrastructure appropriation cycles demand pre-positioned fabrication capacity before funding allocations finalize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cofferdam Market |
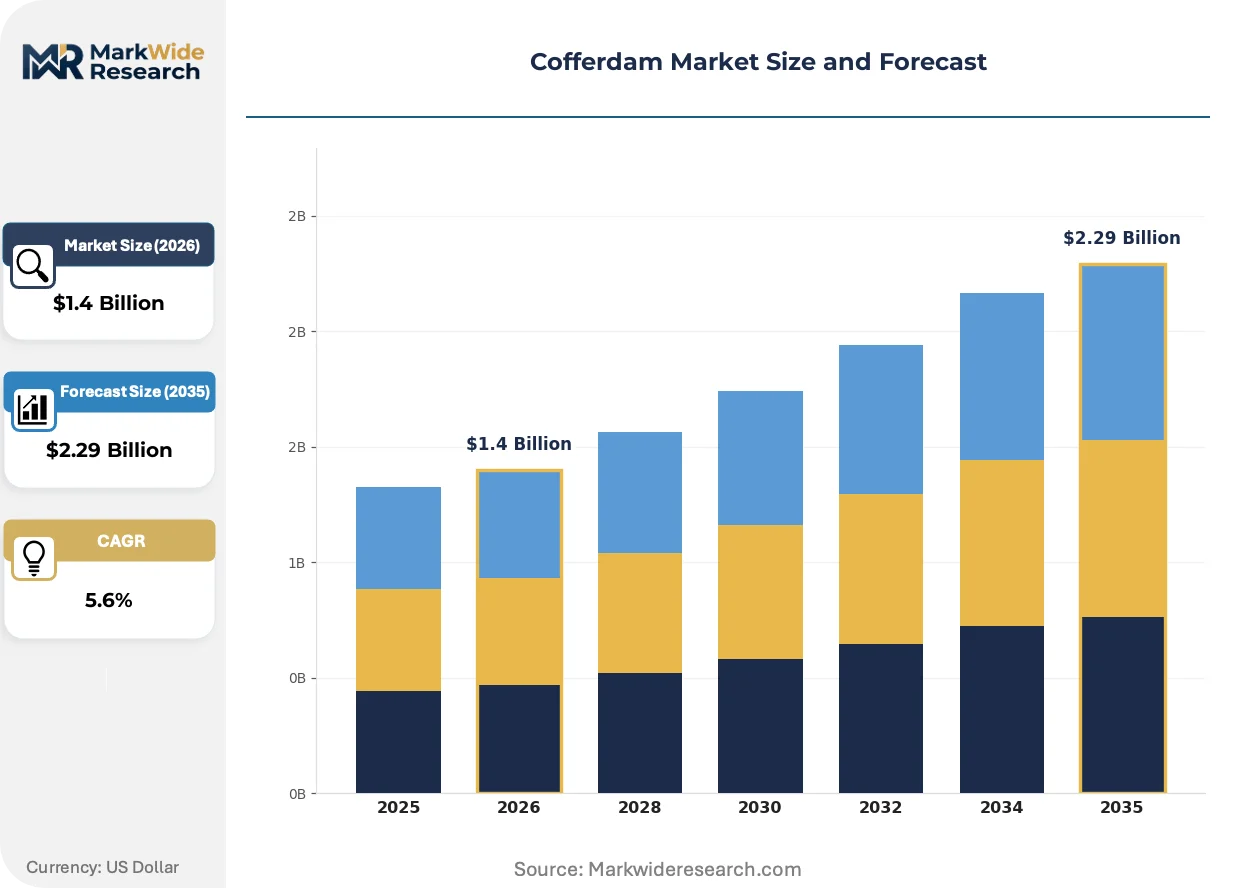
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Cofferdams, Flexible Cofferdams, Hybrid Cofferdams, Inflatable Cofferdams Material: Steel, Aluminum, PVC, Concrete Application: Construction, Marine Works, Repair Works, Drainage Deployment Mode: Temporary, Permanent, Modular, Standardized |
| Companies Covered | DEEP EXCAVATION, KEYMAY Industries, Dam-It Dams, JF BRENNAN, Megasecur, Portadam, ESC GROUP, AquaDam, Layfield, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cofferdam Market Trends and Innovations
Material science advances and regulatory tightening are reshaping competitive positioning across temporary water barrier systems, with polymer technologies challenging steel dominance in shallow-water applications.
High-strength polymer membrane formulations are displacing conventional steel sheet piles in pipeline maintenance and utility repair contracts. Municipal contractors facing compressed mobilization windows adopt inflatable cofferdam systems that deploy without heavy pile-driving equipment. The technology is displacing rigid cellular designs in applications where deflection tolerance exceeds 50 millimeters and installation speed determines contract awards.
OSHA Subpart P excavation standards and the U.S. Army Corps of Engineers EM 1110-2-1913 manual revisions tighten dewatering and worker access protocols for flood-prone installations. Contractors must now document certified material performance under hydrostatic pressure exceeding 15 meters depth. Bridge pier specialists are responding by investing in proprietary shoring software that validates structural calculations against updated federal requirements.
Service unbundling is fragmenting traditional design-build contracts into separate engineering, fabrication, and installation procurements. Port authorities and municipal agencies now bid cofferdam components independently, forcing suppliers to compete on discrete capabilities rather than integrated project delivery. This pattern concentrates most visibly in Gulf Coast states where hurricane resilience programs demand rapid contractor qualification and flexible mobilization schedules.
Cofferdam Market Segmentation
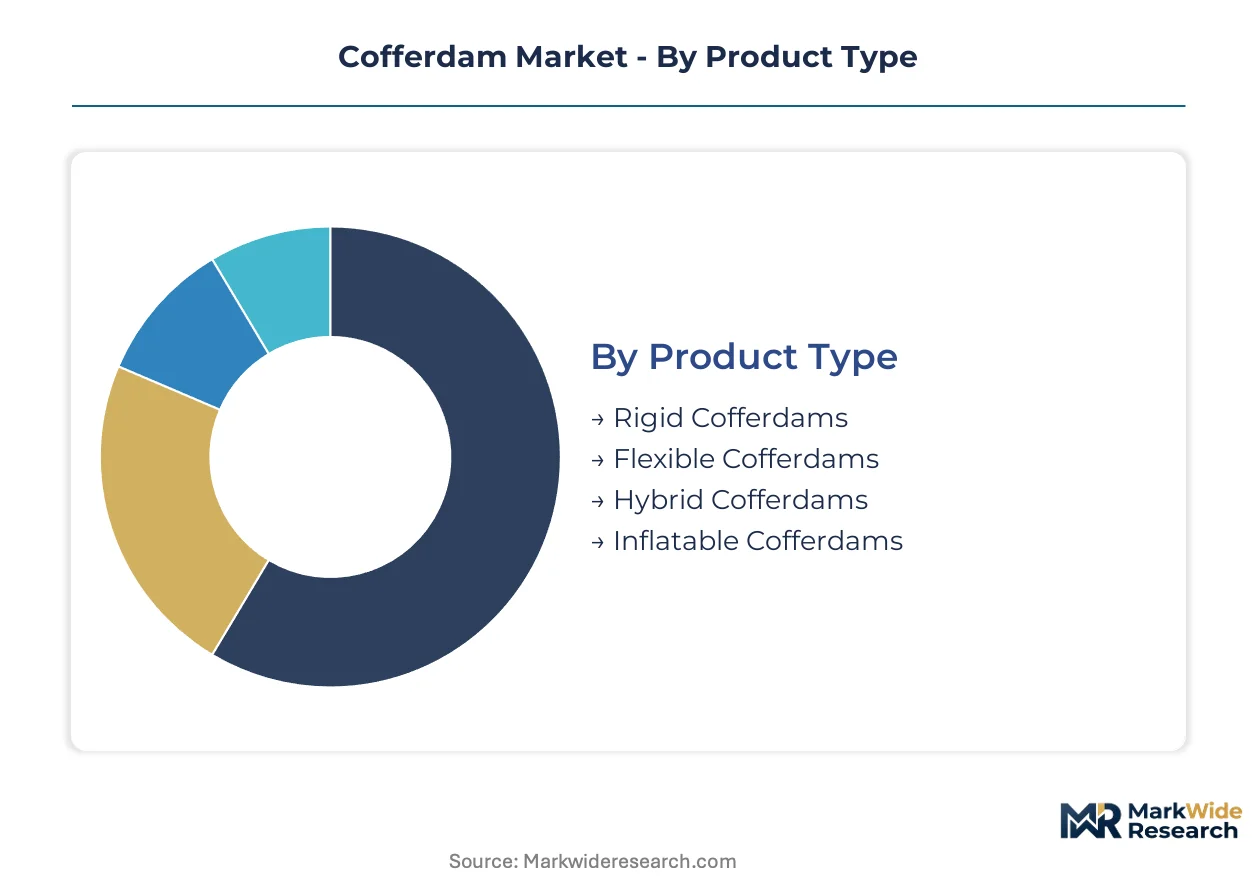
Cofferdam procurement patterns diverge sharply across structural permanence requirements and hydrostatic load conditions. Contractors segment specifications by deflection tolerance, mobilization speed, and regulatory certification tiers rather than material alone.
Product Type:
Flexible and inflatable configurations exert the strongest substitution pressure on legacy rigid systems in shallow-water maintenance contracts.
- Rigid Cofferdams:Steel cellular and sheet pile configurations interlock through Larssen or Frodingham sections driven beyond 15 meters. Bridge pier reconstruction in Louisiana and Texas demands these systems where deflection tolerance sits below 25 millimeters.
- Flexible Cofferdams:High-strength polymer membranes deploy without pile-driving equipment, compressing mobilization windows for municipal pipeline maintenance. Gulf Coast contractors adopt these for hurricane resilience programs requiring rapid installation cycles.
- Hybrid Cofferdams:Composite steel-polymer designs balance structural rigidity with weight reduction for intermediate depth applications.
- Inflatable Cofferdams:Pressurized fabric tubes seal against uneven substrates for emergency flood barrier deployment.
Rigid cofferdams anchor the volume base while flexible configurations gain share at the steepest rate.
Material:
Cost tier stratification separates premium structural grades from commodity alternatives in procurement specifications.
- Steel:Larssen and Frodingham sheet pile sections dominate permanent marine installations requiring CE marking conformity under EU Construction Products Regulation. Scrap metal price volatility compresses margins on cellular projects.
- Aluminum:Lightweight alloys reduce crane capacity requirements for temporary inland waterway deployments where transport costs dominate project economics.
- PVC:Improved puncture resistance formulations expand shallow-water utility repair applications.
- Concrete:Precast gravity walls serve permanent flood control structures with design lives exceeding 50 years.
Steel commands the premium tier while PVC climbs fastest in shallow-water maintenance contracts.
Application:
Customer type segmentation reveals divergent technical specifications between public infrastructure agencies and private utility operators.
- Construction:Deep foundation projects require certified dewatering protocols under OSHA Subpart P and U.S. Army Corps of Engineers EM 1110-2-1913.
- Marine Works:Port authorities specify proprietary shoring software validation for hydrostatic pressure calculations.
- Repair Works:In-house dive teams control installation quality across aging waterfront infrastructure renewal.
- Drainage:EPA Section 404 permitting constraints push contractors toward modular systems minimizing sediment disturbance.
Construction absorbs the largest contract value while repair works expands most quickly amid bridge rehabilitation mandates.
Deployment Mode:
Supply concentration in European fabrication capacity shapes availability timelines for permanent versus temporary specifications.
- Temporary:Rapid-mobilization designs dominate hurricane resilience replacement cycles across Gulf Coast states.
- Permanent:CE-marked structural steel conformity opens European marine installation opportunities.
- Modular:Component standardization enables pre-positioned fabrication capacity before federal infrastructure appropriation finalization.
- Standardized:Catalog specifications accelerate contractor qualification in fragmented municipal procurement.
Modular systems anchor procurement volume growth while standardized configurations penetrate fastest in service-unbundled contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Gulf Coast contractors prioritize rapid-mobilization inflatable systems for hurricane resilience programs, while European port authorities specify CE-marked steel cellular designs for permanent marine installations requiring sub-25 millimeter deflection tolerance.
United States
Louisiana, Texas, and Florida drive replacement cycles for aging temporary water barriers through state-level hurricane resilience funding. OSHA Subpart P excavation standards and U.S. Army Corps of Engineers EM 1110-2-1913 revisions tighten material certification requirements for flood-prone installations. Bridge rehabilitation mandates across municipal contracts in Houston and New Orleans accelerate steel sheet pile deployment for pier reconstruction projects demanding certified dewatering protocols.
Germany
North Sea and Baltic port authorities specify permanent marine installations with design lives exceeding 50 years. EU CE marking under the Construction Products Regulation mandates structural steel conformity for sheet pile cells serving offshore wind foundation projects. Industrial clusters in Hamburg and Bremen concentrate fabrication capacity for hydropower developers across African and Southeast Asian export markets.
China
Yangtze River Delta infrastructure agencies deploy hybrid steel-polymer designs for intermediate-depth bridge foundations. GB standards and MIIT regulations govern temporary water barrier specifications for inland waterway navigation projects. Shanghai and Ningbo manufacturing bases supply modular cofferdam components compressing bid-to-mobilization windows for municipal contractors.
Netherlands
Randstad region water management authorities lead adoption of flexible PVC systems for shallow-water pipeline maintenance where speed outweighs structural permanence. REACH compliance and ECHA substance restrictions shape polymer formulation advances improving puncture resistance. Rotterdam port infrastructure renewal contracts specify proprietary shoring software validation for hydrostatic pressure calculations exceeding 15 meters depth.
United Arab Emirates
Dubai and Abu Dhabi coastal development projects specify aluminum lightweight alloys reducing crane capacity requirements for temporary marine deployments. MOHAP construction product regulations align with EU technical standards for waterfront infrastructure materials. Fabrication clusters in Jebel Ali Free Zone pre-position capacity for rapid mobilization across Gulf Cooperation Council bridge and port contracts.
Cofferdam Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around fabrication scale and in-house installation capabilities. The upper tier commands premium pricing on permanent marine installations through captive dive teams and proprietary engineering software. Mid-tier specialists compete on rapid mobilization for temporary deployments. Dominant competitive moves include backward integration into polymer membrane manufacturing and strategic partnerships with municipal contractors facing compressed workforce capacity.
Among North American contractors, DEEP EXCAVATION and JF BRENNAN occupy positions exemplifying the integrated-leader archetype through combined engineering and installation capabilities. ESC GROUP represents the European manufacturing-scale archetype, anchoring supply routes for export-intensive hydropower developers. These three companies illustrate how geographic origin and structural integration define competitive positioning across rigid cellular and flexible polymer system categories.
| Leading Market Players |
|---|
| DEEP EXCAVATION |
| KEYMAY Industries |
| Dam-It Dams |
| JF BRENNAN |
| Megasecur |
| Portadam |
| ESC GROUP |
| AquaDam |
| Layfield |
| Others |
Pricing and Supply Chain Analysis
Polymer membrane substitution for Larssen steel sections in shallow-water pipeline contracts simultaneously redistributes fabrication toward Southeast Asian polymer compounders and compresses pricing premiums previously anchored to European steel mill capacity. This displacement dynamic fragments historical supply geography while forcing rigid system suppliers to defend margin position through certification bundling rather than material scarcity alone.
Pricing Analysis
Project-based contracting dominates cofferdam procurement, with municipal agencies issuing fixed-price tenders for bridge rehabilitation and hurricane resilience programs. Price differentiation rests on U.S. Army Corps of Engineers EM 1110-2-1913 certification tier and in-house dive team availability, with premium pricing attaching to contractors documenting sub-25 millimeter deflection tolerance validation. Cost compression in rigid cellular systems is intensifying because scrap metal volatility erodes margin buffers on steel sheet pile projects. Municipal contractors facing compressed workforce capacity exhibit highest price sensitivity, while offshore wind developers in the North Sea demonstrate lowest sensitivity due to 50-year design life requirements.
Supply Chain Analysis
Inventory lead times for Larssen and Frodingham sections extend from European mill capacity concentrated in Germany and the Netherlands, while polymer membrane feedstocks draw from Chinese and South Korean petrochemical complexes. Raw material dependencies center on structural steel scrap, high-density polyethylene resin, and aluminum alloy billet. Single-source vulnerability concentrates in European sheet pile cell fabrication serving African and Southeast Asian hydropower export markets. Distribution runs through port authority procurement frameworks and municipal contractor pre-qualification systems that segment temporary from permanent installation specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cofferdam market sits in early-cycle recovery following federal infrastructure appropriation acceleration, with bridge rehabilitation mandates and Gulf Coast hurricane resilience programs providing cyclical uplift through sustained replacement demand.
For Market Incumbents: Shield fabrication margin position by securing captive polymer membrane supply through backward integration into Southeast Asian compounding capacity. Accelerate proprietary shoring software certification against evolving OSHA Subpart P revisions to lock out modular competitors bidding on fragmented municipal contracts. Prioritize pre-positioned steel inventory in Louisiana and Texas ahead of compressed bid-to-mobilization windows.
For New Entrants and Emerging Players: CE marking fast-track for structural steel conformity opens permanent marine installation opportunities in EU waters where incumbent European fabricators face capacity constraints on offshore wind foundation projects. Target flexible PVC deployment for shallow-water utility repair across Randstad region water management authorities, where speed specifications outweigh deflection tolerance requirements. Pursue partnership structures with municipal contractors collapsing under aging workforce scarcity to bypass direct fabrication investment.
For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors vertically integrated contractors combining in-house dive teams with proprietary engineering validation. Long-term viability over the coming decade rests on exposure to cyclical federal infrastructure appropriations and secular coastal resilience spending. Acquisition target archetype: mid-scale specialists with certified EM 1110-2-1913 project portfolios and Gulf Coast state procurement relationships. Monitor EPA Section 404 permitting velocity as inflection indicator for modular system substitution rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Manufacturing | Captive membrane supply secures margin control against petrochemical price volatility in flexible system categories. |
| Proprietary Shoring Software Certification | Validation against U.S. Army Corps of Engineers EM 1110-2-1913 creates procurement preference on bridge pier contracts. |
| In-House Dive Team Expansion | Direct installation quality control differentiates bids across inland waterway contracts where workforce scarcity intensifies. |
| Pre-Positioned Fabrication Capacity | Gulf Coast steel inventory positioning captures compressed mobilization windows under hurricane resilience program timelines. |
| EU CE Marking Pathway Investment | Structural steel conformity under Construction Products Regulation unlocks permanent marine installation revenue in North Sea markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with marine construction contractors, port authority engineering directors, municipal procurement officers, and polymer membrane manufacturing specialists. Secondary validation drew from U.S. Army Corps of Engineers technical manual revisions, EPA Section 404 permitting databases, EU Construction Products Regulation conformity assessments, and customs trade data tracking Larssen section import flows. Bottom-up project pipeline enumeration was triangulated against top-down infrastructure appropriation allocation analysis.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type segmentation, material grade tier, application intensity, and deployment mode permanence. CAGRs were derived from regression analysis against federal funding cycle phasing and coastal resilience program authorization patterns. Industry-specific inputs included hurricane replacement cycle velocity, marine construction workforce attrition rates, and polymer formulation puncture resistance advancement curves.
Underlying assumptions cover sustained federal infrastructure appropriation levels and stable scrap metal price corridors, with deviation risk concentrated in EPA permitting timeline volatility and European mill capacity utilization swings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Ship Port Infrastructure Market