
 Singapore Transportation Infrastructure Construction Market | 2026-2036
Singapore Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Transportation Infrastructure Construction Market Analytics
The gap between premium rail systems and conventional road construction is broadening in Singapore. Woh Hup Holdings Pte Ltd leverages its heavy engineering pedigree to dominate complex underground station contracts. Lum Chang Holdings Limited anchors its portfolio in integrated design-build rail packages. Obayashi Singapore Private Limited differentiates through Japanese precision standards applied to tunnel boring operations.
Singapore transportation infrastructure construction encompasses the planning, engineering, and assembly of mobility assets including rail networks, roadways, bridges, and aviation facilities, typically executed under design-and-build contracts with stringent durability specifications for tropical climates. The primary purpose is sustaining island-wide connectivity while supporting trade logistics and commuter throughput. Rail systems command the deepest margin pools due to long-term maintenance contracts bundled with initial construction. Road construction remains mature with predictable volumes tied to population distribution shifts. Geosynthetics represent the fastest-growing material category as landfill scarcity drives demand for soil reinforcement alternatives.
Singapore's Building and Construction Authority enforces CONQUAS quality benchmarks that shape contractor eligibility and project award criteria. The Land Transport Authority mandates rail-specific safety certifications that filter market access for specialized construction firms. LTA's car-lite policy framework redirects public funding from road expansion toward transit-oriented infrastructure. Stakeholders must monitor how the Jurong Region Line and Cross Island Line procurement cycles reshape contractor capacity allocation across overlapping project timelines.
Market Dynamics
The Land Transport Authority's car-lite policy framework is redirecting public capital from road expansion toward rail-dominant infrastructure, compressing contractor capacity allocation across overlapping megaproject timelines.
Growth Catalysts
- Jurong Region Line procurement cycle:The LTA's network extension mandate is releasing sequential station packages that sustain multi-year contractor backlogs. Underground station contracts absorb the deepest engineering resources.
- Greater Southern Waterfront port relocation:The PSA terminal move is unlocking 2,000 hectares for transit-oriented redevelopment, requiring complete transport corridor reconfiguration.
- Geosynthetics adoption:Singapore's landfill scarcity is accelerating soil reinforcement alternatives in embankment and retaining wall construction, displacing conventional fill materials.
Market Restraints
- Specialized tunnel boring machine dependency:Singapore's granite geology demands slurry TBMs with limited regional lessor availability, concentrating supply risk with Japanese and German equipment fleets.
- Skilled tunnelling workforce scarcity:The Workforce Development Agency's compressed training pipelines cannot match LTA's simultaneous Cross Island Line and Jurong Region Line labour demands.
- CONQUAS quality benchmark escalation:The Building and Construction Authority's tightening defect-free requirements are extending project handover timelines and compressing margin recovery windows.
Strategic Opportunities
- Integrated digital delivery mandates:LTA's building information modelling requirements for rail projects are creating first-mover advantage for contractors with captive BIM capabilities.
- Smart mobility infrastructure convergence:Autonomous vehicle readiness specifications are fusing with station design standards, opening systems-integration contracts beyond traditional civil scope.
- Long-term maintenance bundling:Rail systems' 30-year asset management contracts are shifting contractor revenue models toward lifecycle service provision.
Industry Challenges
- Cross Island Line environmental clearance timelines:The Nature Society Singapore's Central Catchment alignment objections are injecting uncertainty into contractor scheduling and resource deployment.
- Concurrent megaproject coordination:LTA's overlapping Jurong Region Line and Cross Island Line phases are fragmenting specialist subcontractor availability across competing prime contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Transportation Infrastructure Construction Market |
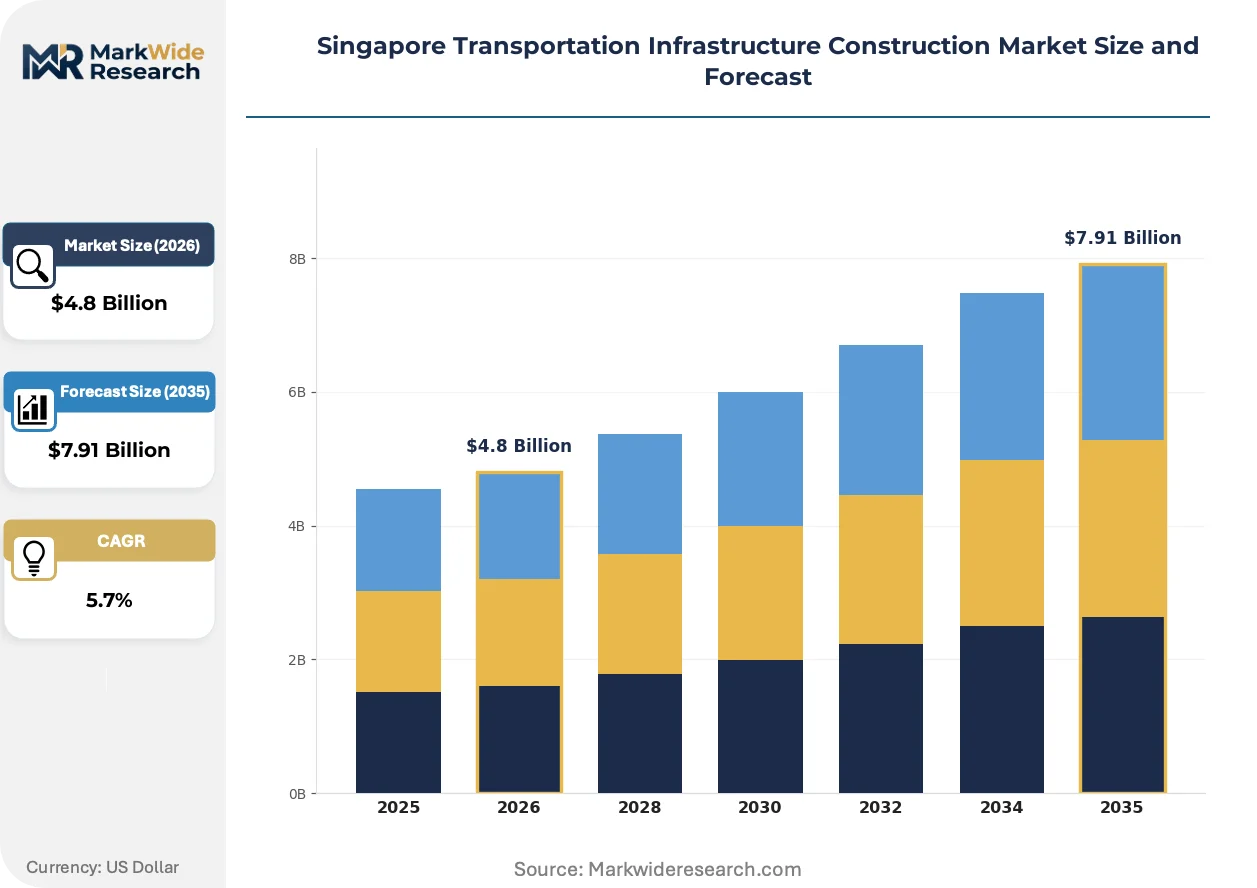
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Road Construction, Bridge Development, Rail Systems, Airport Expansion Material Used: Steel, Concrete, Asphalt, Geosynthetics Service Type: Design Engineering, Construction Management, Maintenance, Inspection End User: Government Agencies, Private Developers, Public Transport Authorities, Contractors |
| Companies Covered | Woh Hup Holdings Pte Ltd, Koh Brothers Building & Civil Engineering Contractor Pte Ltd, Obayashi Singapore Private Limited, Jurong Engineering Limited, CSC Holdings Limited, Tiong Seng Group, Hyundai Engineering & Construction Co Ltd, Lum Chang Holdings Limited, Shimizu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Transportation Infrastructure Construction Market Evolving Landscape
Digital construction methodologies are compressing project delivery timelines while LTA's technical specifications accelerate material substitution and automation integration across the contractor base.
Hybrid precast segmental construction is consolidating market share in elevated viaduct packages. LTA's design-and-build contractors are adopting factory-cast box girders with match-cast jointing to compress on-site labour exposure. The method is consolidating schedule risk away from weather-dependent cast-in-situ operations toward controlled manufacturing environments.
Singapore's Building and Construction Authority has mandated CONQUAS quality benchmarks that now incorporate digital defect tracking. Contractors must deploy automated concrete strength monitoring and real-time rebar inspection systems to maintain eligibility for LTA rail tenders. Underground station packages face the steepest compliance cost escalation as waterproofing warranties extend to 15 years.
Asset-as-a-service procurement models are displacing traditional design-bid-build rail contracts. LTA's bundled construction-plus-maintenance tenders are forcing contractors to internalize 30-year lifecycle cost modelling. The shift is most visible in the Thomson-East Coast Line extension phases, where maintenance obligation pricing now determines award outcomes.
Singapore Transportation Infrastructure Construction Market Segmentation
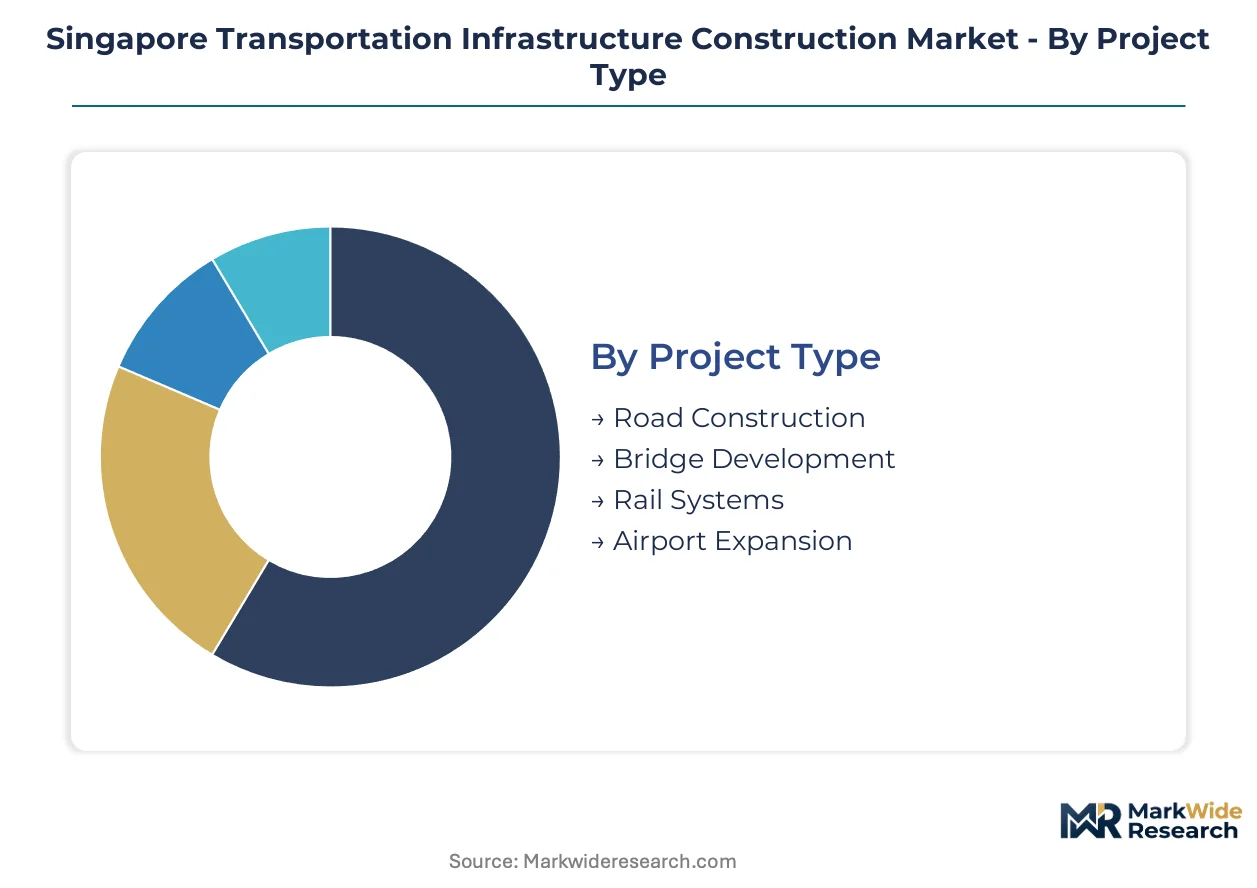
Construction activity across Singapore's transport sector fragments along project complexity and procurement authority lines. Segment boundaries determine contractor qualification tiers, material specification mandates, and maintenance obligation structures that shape long-term revenue capture.
Project Type:
Rail systems impose the deepest engineering specifications among mobility assets, with underground station packages demanding specialized tunnelling capabilities that filter contractor eligibility.
- Rail Systems:Underground stations and elevated viaducts absorb the deepest capital allocation under LTA network extension mandates. Cross Island Line and Jurong Region Line procurement cycles concentrate demand in the central catchment and western corridor, with slurry TBM operations limiting contractor pools to firms with captive equipment partnerships.
- Road Construction:Expressway widening and arterial upgrades follow predictable volumes tied to population distribution shifts in Tampines and Punggol. LTA's car-lite policy compresses greenfield road expansion, redirecting activity toward junction enhancement and bus priority corridor retrofits.
- Bridge Development:Precast segmental construction dominates viaduct packages across Marina South and Woodlands crossing projects.
- Airport Expansion:Changi Terminal 5 and cargo precinct development concentrate specialized aviation-grade concrete and M&E integration demands.
Mature deployment sits with road construction. Newer deployment is concentrated in rail systems.
Material Used:
Material substitution patterns track landfill scarcity and tropical durability requirements that reshape procurement specifications across the Building and Construction Authority's CONQUAS framework.
- Geosynthetics:Soil reinforcement alternatives displace conventional fill in embankment and retaining wall construction. Pulau Semakau landfill constraints accelerate geogrid and geotextile adoption for the Greater Southern Waterfront reclamation and transport corridor reconfiguration.
- Concrete:High-performance mixes with automated strength monitoring dominate underground station packages. Real-time rebar inspection systems and 15-year waterproofing warranties extend quality compliance costs most steeply in Thomson-East Coast Line extension phases.
- Steel:Weathering-grade structural sections anchor elevated viaduct superstructures across island-wide MRT networks.
- Asphalt:Polymer-modified binders sustain heavy-duty pavement layers in port relocation corridor reconfigurations.
Volume concentration rests with concrete. Specification intensity is climbing fastest in geosynthetics.
Service Type:
Procurement model evolution is bundling construction and lifecycle obligations, compressing the distinction between initial delivery and long-term asset management.
- Construction Management:Design-and-build rail contracts integrate BIM mandates that filter contractor eligibility. LTA's building information modelling requirements for underground stations create first-mover advantage for firms with captive digital delivery capabilities.
- Maintenance:Thirty-year asset management contracts now determine rail tender award outcomes. Thomson-East Coast Line extension phases embed lifecycle cost modelling that shifts revenue toward service provision rather than one-time construction margins.
- Design Engineering:Hybrid precast segmental specifications consolidate factory-cast box girder adoption for schedule risk transfer.
- Inspection:Automated defect tracking systems satisfy CONQUAS digital compliance mandates for quality benchmark eligibility.
Revenue stability favors maintenance. Margin expansion concentrates in construction management.
End User:
Procurement authority distribution shapes contract scale, technical specification intensity, and payment security structures across the contractor base.
- Public Transport Authorities:LTA dominates rail and major road procurement with bundled construction-plus-maintenance tenders. Car-lite policy frameworks redirect public funding from road expansion toward transit-oriented infrastructure, concentrating megaproject scale in single-client relationships.
- Government Agencies:Housing Board and national development ministry contracts anchor predictable civil works volumes in new town transport integration.
- Private Developers:Integrated transport hub and transit-oriented development packages in Marina South and Jurong Lake District concentrate design-build rail-station interface contracts.
- Contractors:Specialist subcontractor availability fragments across overlapping Jurong Region Line and Cross Island Line prime contractor demands.
Contract scale peaks with public transport authorities. Specification flexibility is widest among private developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Southern Waterfront corridor anchors Singapore's transport infrastructure investment gravity, where port relocation is catalyzing complete mobility network reconfiguration across 2,000 hectares of reclaimed territory.
Central Region
The Central Catchment area concentrates Cross Island Line tunneling activity where granite geology demands specialized slurry TBM deployment. Singapore's Land Transport Authority mandates 15-year waterproofing warranties for underground stations, compressing contractor eligibility to firms with proven geotechnical track records. The Thomson-East Coast Line extension phases dominate capital allocation in this corridor.
Western Corridor
Jurong Region Line procurement cycles are absorbing peak contractor capacity across Tuas and Jurong Lake District nodes. Singapore's Building and Construction Authority enforces CONQUAS quality benchmarks that filter design-and-build tender participation. The Jurong Innovation District and port relocation logistics hub are driving integrated transport hub development.
Northern Gateway
Woodlands crossing projects and cross-border connectivity to Malaysia are sustaining elevated viaduct construction volumes. Singapore's car-lite policy framework redirects public funding from road expansion toward rail-dominant infrastructure in this corridor. The North-South Corridor bus priority retrofit contracts anchor predictable civil works demand.
Marina South
Precast segmental construction dominates elevated viaduct packages across the Greater Southern Waterfront reclamation zone. Singapore's landfill scarcity is accelerating geosynthetics adoption for soil reinforcement in embankment works. The Marina South transport corridor reconfiguration is bundling station construction with transit-oriented development interfaces.
Singapore Transportation Infrastructure Construction Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Singapore's rail construction segment, where bundled construction-plus-maintenance tenders favor firms with captive equipment partnerships and lifecycle service capabilities. The contractor base concentrates around three strategic archetypes: heavy engineering specialists with tunnelling pedigrees, integrated design-build operators with BIM capabilities, and precision-focused international players with equipment alliances. Market consolidation is accelerating through joint venture formations on megaproject bids and backward integration into precast manufacturing.
Among Singapore-based heavy engineering contractors, Woh Hup Holdings Pte Ltd and Lum Chang Holdings Limited occupy positions within the integrated design-build tier, while Obayashi Singapore Private Limited represents the precision-focused international archetype with Japanese engineering standards. These anchors exemplify how contractor eligibility filters toward firms with simultaneous Cross Island Line and Jurong Region Line resource deployment capacity.
| Leading Market Players |
|---|
| Woh Hup Holdings Pte Ltd |
| Koh Brothers Building & Civil Engineering Contractor Pte Ltd |
| Obayashi Singapore Private Limited |
| Jurong Engineering Limited |
| CSC Holdings Limited |
| Tiong Seng Group |
| Hyundai Engineering & Construction Co Ltd |
| Lum Chang Holdings Limited |
| Shimizu Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between CONQUAS-compliant contractors and conventional civil operators manifests in both bid pricing and procurement channel structures. Premium rail packages command elevated margins through bundled maintenance obligations, while commodity road work compresses returns across fragmented subcontractor networks.
Pricing Analysis
Value-based pricing anchored to 30-year asset management outcomes dominates LTA's bundled construction-plus-maintenance tenders. Price differentiation separates firms with captive BIM capabilities and slurry TBM partnerships from conventional design-bid-build operators. Pricing pressure intensifies in road construction as car-lite policy redirects public capital toward rail-dominant infrastructure. Private developers exhibit lowest price sensitivity for transit-oriented development interface contracts, while government agencies enforce strict cost benchmarking on standardized civil packages.
Supply Chain Analysis
Warehouse-distribution layers for tunnel boring equipment concentrate through regional hubs in Japan and Germany given limited regional lessor availability. Slurry TBM fleets, high-performance concrete admixtures, and geosynthetic soil reinforcement materials draw from concentrated supply bases. Single-source vulnerability runs through specialized Japanese and German equipment manufacturers. Distribution runs through prime contractor-controlled procurement channels with direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive precast manufacturing and equipment partnerships determine eligibility for megaproject awards.
For Market Incumbents: Cement tunnelling pedigree advantages through exclusive slurry TBM lessor alliances and backward integration into precast segmental manufacturing. Defend against emerging design-build specialists by locking in Jurong Region Line and Cross Island Line capacity allocation. Prioritize CONQUAS digital compliance investment to maintain LTA tender eligibility. For New Entrants and Emerging Players: BIM-native delivery platforms offer the most penetrable wedge for rail station packages where LTA mandates create first-mover advantage. Target inspection and automated defect tracking subcontracts as lower-barrier entry points. Pursue joint venture formations with established heavy engineering contractors to access megaproject qualification tiers. For Investors and Strategic Acquirers: Re-rating potential sits with integrated design-build operators given LTA's bundled tender evolution and maintenance obligation bundling. Long-term viability favors firms with simultaneous Cross Island Line and Jurong Region Line resource deployment capacity. Monitor Jurong Innovation District transport hub procurement cycles as inflection indicator for contractor backlog visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precast Manufacturing | Factory-cast box girder adoption transfers schedule risk from weather-dependent site operations to controlled environments. |
| Slurry TBM Equipment Partnership | Exclusive lessor alliances filter eligibility for granite geology underground station contracts under LTA specifications. |
| BIM Capability Captive Development | Digital delivery mandates create first-mover advantage for rail tender participation against conventional civil operators. |
| Maintenance Obligation Bundling | Thirty-year asset management contracts shift revenue models toward lifecycle service provision beyond construction margins. |
| Geosynthetics Supply Chain Control | Pulau Semakau landfill constraints accelerate soil reinforcement material adoption in Greater Southern Waterfront reclamation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for Singapore's transportation infrastructure construction market. Primary interviews with LTA procurement officers, project directors at heavy engineering contractors, and Workforce Development Agency training specialists combined with Building and Construction Authority CONQUAS compliance databases and Land Transport Authority tender announcements. Bottom-up project pipeline aggregation triangulated against top-down construction sector output estimates.
Data-stream reconciliation across the analysis window applied project-type segmentation by delivery complexity, material substitution patterns, and procurement model evolution. Modeled dimensions included rail systems versus road construction, geosynthetics versus conventional fill, and bundled maintenance versus standalone construction. CAGRs derived from capital allocation trajectories under LTA's car-lite policy framework and network extension mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Cross Island Line environmental clearance delays or slurry TBM equipment availability shocks. Forecasts reflect documented assumptions around Jurong Region Line phasing and port relocation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Global Transportation Infrastructure Market