
 Europe Transportation Infrastructure Construction Market | 2026-2036
Europe Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Transportation Infrastructure Construction Market Foresight
Market Context
Europe transportation infrastructure construction is rebalancing between premium sustainable builds and commodity maintenance contracts as carbon targets harden. Strabag SE leverages its Alpine tunneling expertise to dominate complex geotechnical segments. VINCI SA anchors French high-speed rail and airport concessions through long-term operational partnerships. Ferrovial SA competes aggressively on UK and Spanish toll road renewals with integrated asset-management models.
Technical Definition and Segment Structure
Europe transportation infrastructure construction encompasses the engineering, materials procurement, and assembly of roadways, bridges, railways, and airports using concrete, steel, asphalt, and composite formulations to achieve specified load-bearing capacities and design lifespans. Concrete formulations with supplementary cementitious materials now constitute the dominant material type by volume, though steel competes in long-span bridge applications where tensile strength requirements exceed fifty kilonewtons per square meter. Roadways and railways absorb the majority of public capital allocation, while airport construction commands the highest margin pools due to stringent safety certification and specialized MEP integration. Sustainable construction methods, including low-carbon concrete and modular pre-fabrication, represent the fastest-expanding segment as member states transpose EU Green Deal obligations into national procurement rules.
Regulatory Frame and Outlook
The EU Green Deal, F-Gas Regulation, and national transpositions of the CSRD are reshaping contractor qualification criteria, mandating embodied carbon disclosure and circular material sourcing for publicly funded projects. ECHA REACH compliance now extends to construction chemical additives, limiting admixture formulations and elevating R&D costs for material suppliers. Stakeholders must monitor how the EU AI Act and forthcoming infrastructure resilience standards alter predictive maintenance contracting and digital twin deployment requirements across member state procurement frameworks.
Market Dynamics
The EU Green Deal's carbon budgeting mandates are compressing project timelines and forcing contractors to requalify procurement frameworks around embodied carbon disclosure, fundamentally restructuring how public infrastructure contracts are awarded across member states.
Growth Catalysts
- EU Green Deal procurement rules:National transpositions now mandate low-carbon concrete and circular material sourcing for publicly funded road and rail projects, redirecting capital toward sustainable construction specialists.
- Urban rail modernization:France, Germany, and Spain are accelerating tunnel and bridge renewal programs to extend asset lifespans and accommodate electrified rolling stock.
- Modular pre-fabrication:Factory-controlled concrete curing and steel assembly are compressing on-site construction windows and reducing weather-related delays in Alpine and Nordic geographies.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production faces carbon cost pass-throughs under EU ETS phase-out mechanisms, squeezing margins on fixed-price public contracts.
- ECHA REACH compliance:Construction chemical admixture formulations now require extended toxicity testing, lengthening R&D cycles for material suppliers and limiting formulation flexibility.
- Geotechnical labor scarcity:Specialized tunneling engineers concentrate in Alpine regions, creating bidding bottlenecks for complex underground segments outside Austria and Switzerland.
Strategic Opportunities
- Polish and Romanian highway corridors:EU cohesion funds are financing last-mile motorway connections where design-build-operate concessions remain underpenetrated by integrated asset managers.
- Digital twin integration:Predictive maintenance contracting is converging with BIM-enabled project delivery, opening recurring revenue streams beyond construction completion.
- F-Gas Regulation retrofit mandates:Airport HVAC and fire suppression system upgrades create captive demand for contractors with MEP certification and refrigerant handling licenses.
Industry Challenges
- CSRD disclosure alignment:Contractors must integrate embodied carbon tracking across tier-two material suppliers, forcing supply chain reconfiguration and data system investments.
- EU AI Act compliance:Automated quality control and safety monitoring systems face algorithmic transparency requirements, complicating deployment of computer-vision inspection tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Transportation Infrastructure Construction Market |
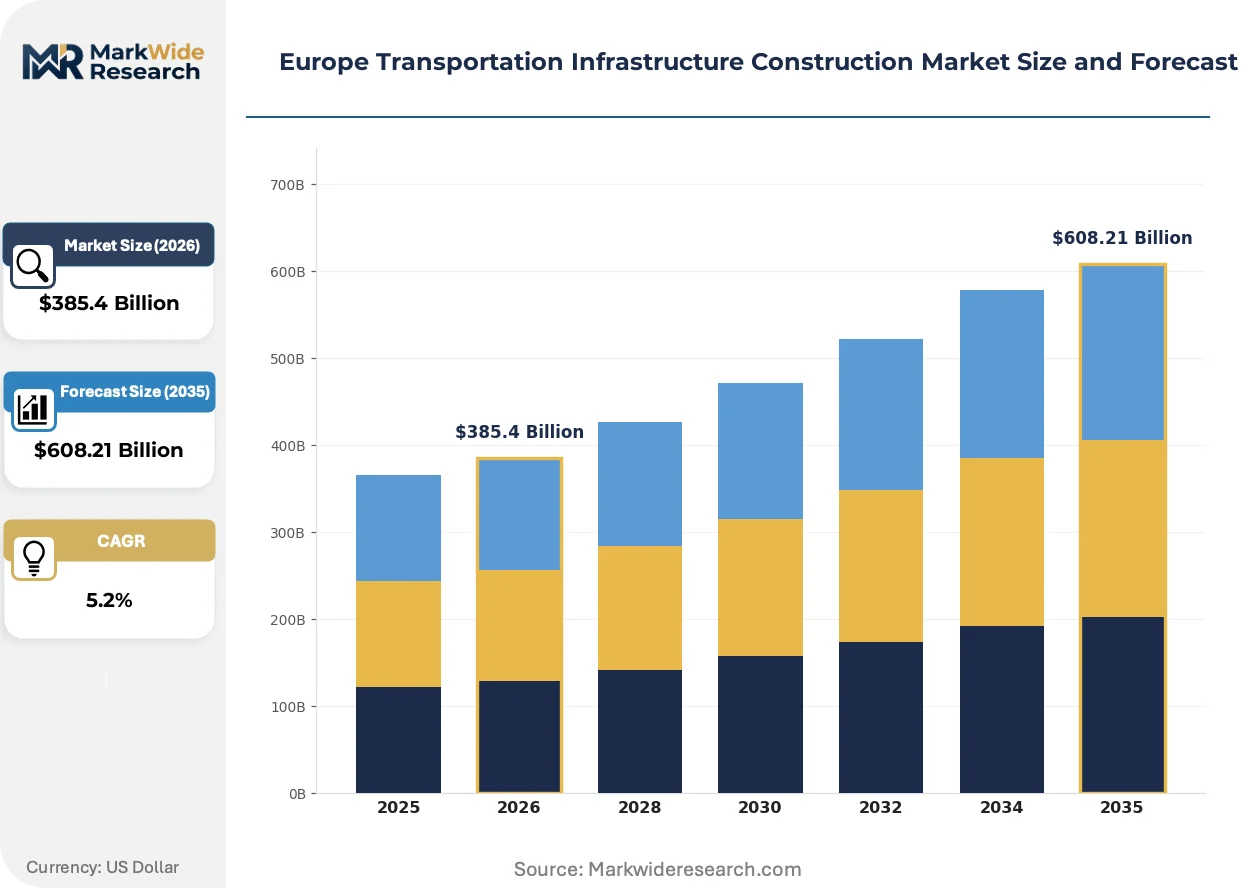
| Market Size in 2026 | $385.4 Billion |
| Market Size in 2035 | $608.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roadways, Bridges, Railways, Airports Material Type: Concrete, Steel, Asphalt, Composites Construction Method: Traditional, Modular, Pre-fabrication, Sustainable End User: Government, Private Sector, Utility Companies, Others |
| Companies Covered | Strabag SE, Ferrovial SA, VINCI SA, Acciona SA, Balfour Beatty plc, ACS Group, Skanska AB, Royal BAM Group nv, Bouygues Construction, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Transportation Infrastructure Construction Market Shifts & Advancements
Electrification requirements are cascading from vehicle fleets through to the infrastructure that carries them, rewiring material specifications and construction methodologies across European transportation networks.
Low-carbon concrete formulations with supplementary cementitious materials are electrifying competitive positioning among material suppliers. French and German rail authorities now specify geopolymer and calcined clay blends for tunnel linings and station platforms. This substitution is compressing traditional Portland cement demand in publicly funded segments where carbon budgets harden fastest.
The EU AI Act's risk-classification framework for critical infrastructure is reshaping contractor qualification criteria. Predictive maintenance algorithms and automated safety systems now face conformity assessment requirements before deployment on rail and airport projects. Scandinavian transport authorities are piloting certified digital twin platforms to satisfy these pre-market validation obligations.
Design-build-finance-operate contracts are displacing traditional lump-sum construction awards in Spanish and Italian toll road renewals. Private capital providers now demand operational cost certainty across thirty-year concession windows, forcing contractors to absorb lifecycle risk. This compression of risk allocation is most visible in Mediterranean member states where public balance sheet constraints limit availability-payment structures.
Europe Transportation Infrastructure Construction Market Segmentation
Transportation infrastructure construction segments diverge sharply in capital intensity, regulatory exposure, and contractor capability requirements. Understanding these fault lines clarifies where EU Green Deal procurement rules redirect contract flows and which material and method combinations capture public funding priority.
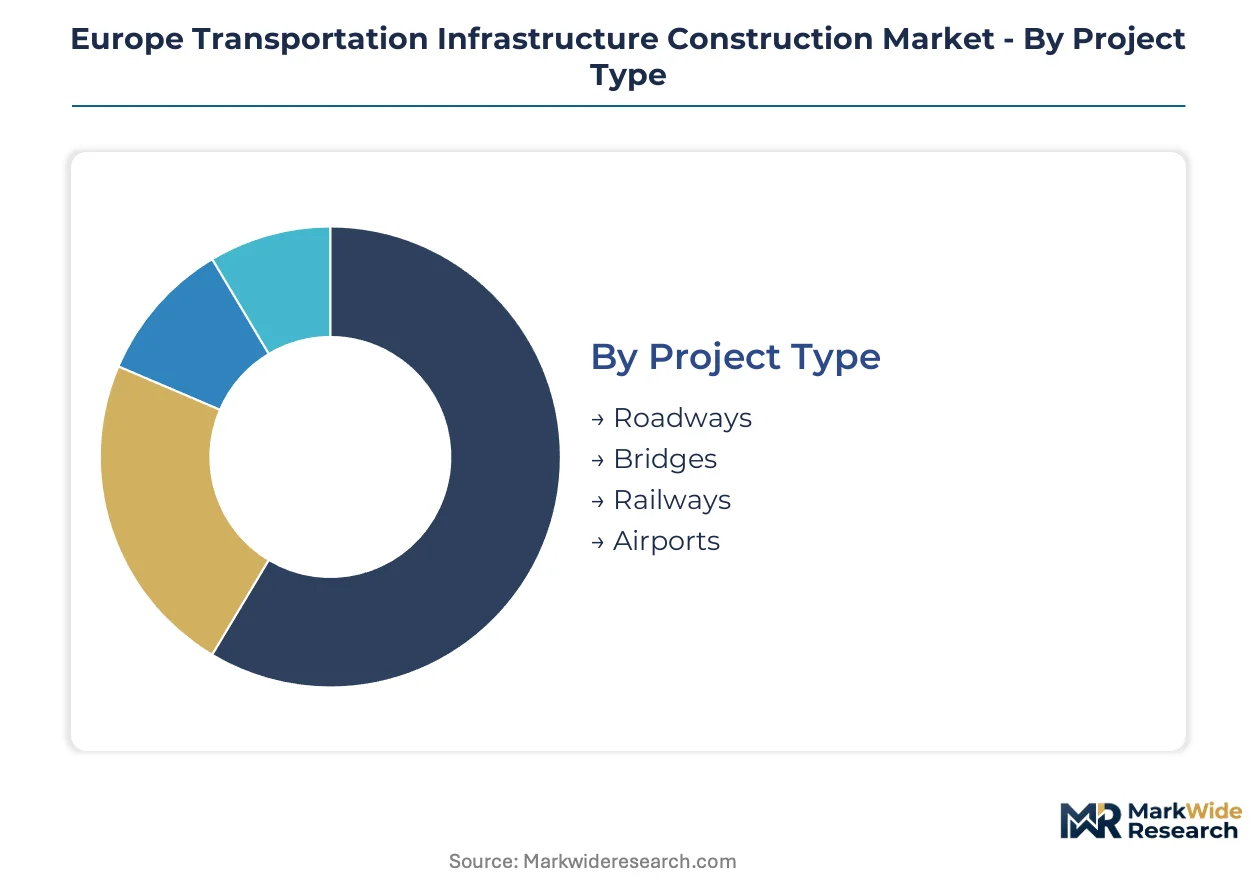
Project Type:
Supply concentration in Alpine tunneling and French high-speed rail engineering creates bidding bottlenecks for complex segments while commoditized road maintenance contracts fragment across regional players.
- Roadways:Asphalt and concrete pavement construction dominates public procurement volume across member states. Poland and Romania absorb EU cohesion funds for last-mile motorway connections where design-build-operate concessions remain underpenetrated.
- Bridges:Long-span steel and composite structures require tensile capacity exceeding fifty kilonewtons per square meter. France, Germany, and Spain concentrate renewal programs as carbon budgets harden fastest in these jurisdictions.
- Railways:Urban rail modernization accelerates tunnel and bridge renewal to accommodate electrified rolling stock. Electrification requirements cascade from vehicle fleets through to infrastructure specifications.
- Airports:Stringent safety certification and specialized MEP integration command the highest margin pools. F-Gas Regulation retrofit mandates for HVAC and fire suppression systems create captive demand for certified contractors.
Today's leader: Roadways. Tomorrow's challenger: Airports.
Material Type:
Cost tier stratification separates premium low-carbon formulations from commodity Portland cement, with carbon cost pass-throughs under EU ETS compressing margins on fixed-price public contracts.
- Concrete:Formulations with supplementary cementitious materials now constitute the dominant material type by volume. French and German rail authorities specify geopolymer and calcined clay blends for tunnel linings and station platforms.
- Steel:Competes in long-span bridge applications where tensile strength requirements exceed concrete capacity. Energy-intensive production faces carbon cost pass-throughs under EU ETS phase-out mechanisms.
- Asphalt:Petroleum-derived binder content exposes pricing to energy market volatility. Warm-mix formulations reduce production temperatures and align with municipal carbon reduction targets.
- Composites:Fiber-reinforced polymers gain traction in corrosion-resistant bridge decks and railway platforms. Extended durability offsets higher upfront material costs in lifecycle procurement frameworks.
Portland cement retains volume dominance. Low-carbon alternatives gain share fastest where national carbon budgets harden procurement specifications.
Construction Method:
Application maturity separates legacy techniques from emerging factory-controlled processes, with weather-related delay reduction driving adoption in Alpine and Nordic geographies.
- Traditional:Cast-in-place concrete and on-site steel assembly remain standard for small-scale maintenance and emergency repair contracts. Labor intensity and weather exposure constrain scheduling certainty.
- Modular:Factory-controlled concrete curing and steel assembly compress on-site construction windows. Scandinavian transport authorities pilot certified platforms to satisfy EU AI Act pre-market validation obligations.
- Pre-fabrication:Off-site component manufacturing reduces waste and quality variance. Design-build-finance-operate contracts in Spanish and Italian toll road renewals absorb lifecycle risk through integrated delivery.
- Sustainable:Low-carbon concrete and circular material sourcing represent the fastest-expanding segment. National transpositions of EU Green Deal obligations now mandate embodied carbon disclosure for publicly funded projects.
Traditional methods retain maintenance contract dominance. Sustainable construction climbs fastest as procurement rules harden.
End User:
Customer type determines contract structure, with government procurement mandating carbon disclosure while private concessions absorb long-term operational risk.
- Government:National and municipal authorities allocate the majority of public capital to roadways and railways. CSRD disclosure alignment forces embodied carbon tracking across tier-two material suppliers.
- Private Sector:Toll road and airport concessions demand operational cost certainty across thirty-year windows. Mediterranean member states limit availability-payment structures due to public balance sheet constraints.
- Utility Companies:Rail electrification and grid connection infrastructure require specialized contractor certification. Predictive maintenance contracting converges with BIM-enabled project delivery.
- Others:Industrial logistics parks and port authorities drive specialized heavy-haul pavement specifications. Geotechnical labor scarcity concentrates bidding power among Alpine-region specialists.
Public procurement anchors contract volume. Private concession models reshape risk allocation fastest in Southern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized tunneling engineers and geotechnical specialists concentrate in Alpine corridors, creating bidding bottlenecks for complex underground segments across the continent.
Germany
Urban rail modernization accelerates tunnel and bridge renewal to accommodate electrified rolling stock. The EU Green Deal's carbon budgeting mandates force embodied carbon disclosure across federally funded projects. Munich and Stuttgart anchor high-speed rail engineering clusters where design-build-operate concessions absorb thirty-year operational risk.
France
Bridge and tunnel renewal programs concentrate public investment as national carbon budgets harden procurement specifications. The CSRD disclosure alignment forces embodied carbon tracking across tier-two material suppliers. Paris and Lyon dominate high-speed rail concessions through long-term operational partnerships with integrated asset managers.
Spain
Toll road renewals reshape competitive positioning as private capital providers demand cost certainty across extended concession windows. Mediterranean member states limit availability-payment structures due to public balance sheet constraints. Madrid and Barcelona anchor design-build-finance-operate contract clusters where contractors absorb lifecycle risk.
Poland
EU cohesion funds finance last-mile motorway connections where design-build-operate concessions remain underpenetrated by integrated asset managers. National transpositions of EU Green Deal obligations mandate low-carbon concrete for publicly funded road projects. Warsaw and Kraków concentrate asphalt and concrete pavement construction capacity.
Switzerland
Alpine tunneling expertise dominates complex geotechnical segments as factory-controlled concrete curing compresses on-site construction windows. The EU AI Act's risk-classification framework reshapes contractor qualification criteria for predictive maintenance algorithms. Zurich and Geneva anchor modular pre-fabrication pilots certified for digital twin platform deployment.
Europe Transportation Infrastructure Construction Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where scale-driven concessionaires absorb long-term operational risk. The vendor base fragments between regional maintenance specialists and integrated multinational asset managers. Three archetypes dominate: Alpine tunneling specialists, Mediterranean concession operators, and Nordic modular fabricators. M&A activity concentrates bidding power while strategic partnerships unlock EU cohesion fund access in Eastern European corridors.
Among Austria-based tunneling specialists, Strabag SE exemplifies the geotechnical engineering archetype with concentrated Alpine expertise. French concessionaires VINCI SA and Bouygues Construction occupy positions within the integrated asset-management tier, anchoring long-term operational partnerships across high-speed rail and airport segments. Spanish operator Ferrovial SA represents the Mediterranean toll road renewal model, sitting within the design-build-finance-operate contract structure displacing traditional lump-sum awards.
| Leading Market Players |
|---|
| Strabag SE |
| Ferrovial SA |
| VINCI SA |
| Acciona SA |
| Balfour Beatty plc |
| ACS Group |
| Skanska AB |
| Royal BAM Group nv |
| Bouygues Construction |
| Others |
Supply & Pricing Matrix
Federally funded procurement programs in France, Germany, and Spain anchor demand concentration for transportation infrastructure construction, locking in project-based contract pricing with lifecycle cost certainty requirements. Public sector buyers dominate volume allocation, compressing margin pools for fixed-price awards while elevating premium capture for concessionaires absorbing long-term operational risk.
Pricing Analysis
Bundled design-build-operate concessions separate from unbundled maintenance contracts across European procurement frameworks. Three-tier pricing structure across premium sustainable builds, standard engineered solutions, and commodity maintenance tiers reflects carbon certification levels and asset lifespan guarantees. Pricing pressure stems from EU ETS carbon cost pass-throughs on energy-intensive clinker production, squeezing margins on fixed-price public awards. Municipal authorities exhibit highest price sensitivity on routine road maintenance, while airport concessions demonstrate lowest sensitivity due to stringent safety certification requirements.
Supply Chain Analysis
Reverse-logistics flows for demolished concrete and steel bridge components are gaining structural importance as circular material sourcing mandates harden under EU Green Deal procurement rules. Supply concentrates in Germany, France, and Poland for cementitious materials, with Austria and Switzerland anchoring specialized tunneling equipment and geotechnical engineering capacity. Raw material dependencies center on Portland cement clinker, structural steel feedstock, and petroleum-derived asphalt binders. Single-source vulnerability in Alpine-region tunneling engineering creates bidding bottlenecks for complex underground segments. Distribution runs through national procurement frameworks with EU cohesion fund co-financing in Eastern European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon budgeting mandates compound demand for low-carbon construction methods, transforming contractor qualification criteria and procurement award structures across member states.
For Market Incumbents: Deepen captive supply of supplementary cementitious materials to defend margin position against EU ETS phase-out cost compression. Acquire specialized tunneling engineering capabilities in Alpine regions to eliminate bidding bottlenecks for complex underground segments. Lock in long-term operational partnerships with French and German rail authorities before CSRD disclosure alignment forces supply chain reconfiguration. For New Entrants and Emerging Players: Digital twin platform deployment offers the lowest-friction entry vector for predictive maintenance contracting convergence with BIM-enabled project delivery. Target Polish and Romanian highway corridors where EU cohesion funds finance last-mile motorway connections and integrated asset managers remain underpenetrated. Pursue F-Gas Regulation retrofit certification to capture captive airport HVAC and fire suppression upgrade demand. For Investors and Strategic Acquirers: Integrated concessionaires with design-build-finance-operate capabilities are the most active acquirer in this space, consolidating bidding power across Mediterranean toll road renewals. Five-to-ten year viability hinges on embodied carbon tracking system investments ahead of national procurement rule transpositions. Monitor EU AI Act pre-market validation obligations for predictive maintenance algorithms as the inflection indicator for digital twin platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Supplementary Cementitious Materials | Captures margin from EU ETS carbon cost pass-throughs on clinker production. |
| Digital Twin Platform Certification | Satisfies EU AI Act pre-market validation for predictive maintenance algorithms. |
| EU Cohesion Fund Partnership Structuring | Unlocks last-mile motorway financing in Polish and Romanian corridors. |
| Alpine Tunneling Capability Acquisition | Eliminates geotechnical labor scarcity bottlenecks for complex underground segments. |
| F-Gas Regulation Retrofit Licensing | Creates captive demand from airport HVAC and fire suppression upgrade mandates. |
Research Methodology
Direct dialogue with EPC contract directors, public procurement officers at French and German transport authorities, tunneling engineering specialists in Alpine regions, and sustainability compliance leads at major material suppliers grounded qualitative findings. Secondary validation drew from EU Tenders Electronic Daily procurement databases, Eurostat construction output statistics, ECHA REACH substance registration filings, and national carbon budget transposition documents. Bottom-up project pipeline analysis triangulated against top-down member state infrastructure investment forecasts.
Market size and growth trajectories across the analysis window reflect segmented modeling by project type, material formulation, construction method, and end-user procurement structure. The analytical framework incorporated EU Green Deal implementation timelines, CSRD disclosure phase-in schedules, and EU AI Act risk classification pathways as regulatory scenario inputs. CAGRs derived from historical construction output correlations with public capital allocation patterns and electrification-driven asset renewal cycles.
Regulatory delay, carbon price volatility, and geotechnical labor supply constraints are the dominant revision risks for forecast trajectories. Forecasts reflect documented assumptions on national transposition timing and cohesion fund disbursement rates. Practitioners should monitor EU AI Act implementing acts and ETS allowance auction prices for early signals of contract award velocity shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Global Rail Infrastructure Market