
 Marine Engine Cooling Systems Market | 2026-2036
Marine Engine Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Engine Cooling Systems Market Outlook
Project finance tied to vessel leasing arrangements is narrowing the competitive field to suppliers with balance-sheet capacity for long-dated contracts. Wärtsilä leverages its integrated power plant approach to bundle cooling systems with engine packages. Alfa Laval anchors its position through backward integration into heat exchanger plate manufacturing, controlling critical component supply.
Marine engine cooling systems manage thermal loads from propulsion and auxiliary engines using seawater, freshwater, or hybrid circuits with specified metallurgy for corrosion resistance; their primary purpose is maintaining optimal cylinder temperatures to prevent thermal fatigue and comply with exhaust emission limits. Heat exchangers dominate product-level margins due to material intensity and replacement frequency. Indirect cooling technology leads newbuild specifications as shipyards seek separation between corrosive seawater and engine jackets.
The International Maritime Organization, EPA, and EU MRV framework collectively tighten thermal efficiency and emission thresholds that dictate cooling system capacity requirements. Classification societies including DNV and Lloyd's Register enforce material and performance standards that filter market access. Stakeholders must monitor how ammonia and methanol fuel transitions alter heat rejection profiles and retrofit compatibility.
Market Dynamics
Naval fleet modernization across NATO members and the International Maritime Organization's tightened NOx and SOx emission rules are compressing procurement cycles for advanced heat rejection equipment, forcing shipyards to specify higher-capacity cooling architectures earlier in vessel design.
Growth Catalysts
- IMO emission mandates:Tightened NOx and SOx thresholds under MARPOL Annex VI compel shipyards to install larger heat exchangers and upgraded seawater circuits to manage elevated thermal loads from exhaust after-treatment systems.
- LNG carrier newbuilds:South Korea's Ulsan-Jeolla shipbuilding cluster is generating concentrated demand for customized cooling packages as orders for membrane-type LNG carriers require specialized low-temperature heat management.
- Hybrid propulsion architectures:Dual-fuel engine installations combining diesel and gas modes are multiplying cooling circuit complexity, expanding specification scope for integrated freshwater-seawater systems.
Market Restraints
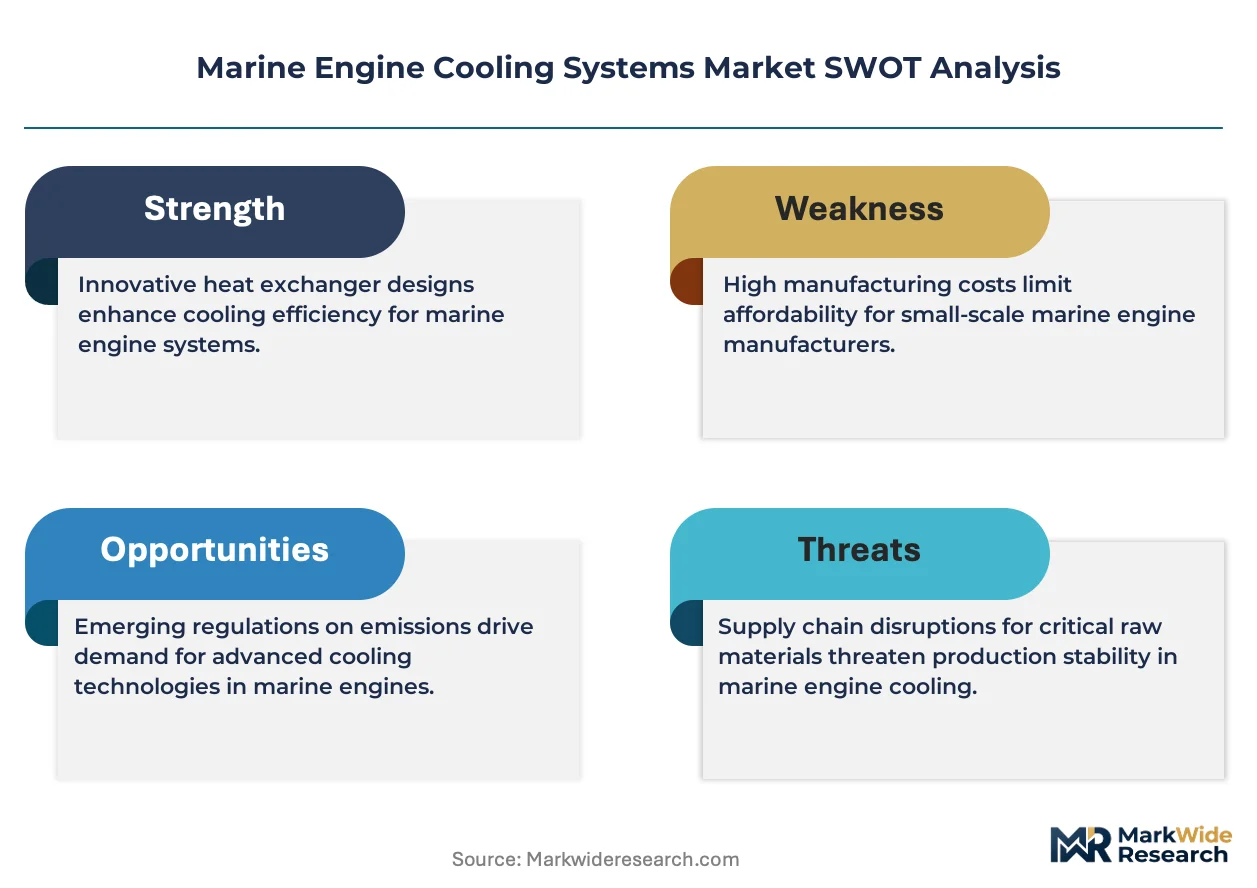
- Copper-nickel alloy volatility:Heat exchanger plate manufacturing depends on copper-nickel pricing, with alloy cost swings compressing margins for component suppliers unable to pass through material adjustments.
- Foundry concentration in East Asia:Casting capacity for corrosion-resistant pump housings and valve bodies concentrates in Chinese and South Korean facilities, creating geographic supply vulnerability for European system integrators.
- Seawater corrosion limitations:Direct cooling configurations face accelerated tube fouling and galvanic degradation in high-salinity operating environments, restricting deployment in certain trade routes.
Strategic Opportunities
- Methanol fuel transition:Ammonia and methanol combustion profiles generate altered heat rejection signatures, creating retrofit demand for cooling capacity upgrades as vessel operators trial alternative fuels.
- EU Green Deal vessel financing:The European Investment Bank's sustainable shipping facility offers preferential terms for ships meeting elevated efficiency benchmarks, incentivizing specification of advanced heat recovery cooling systems.
- Digital twin integration:Convergence of computational fluid dynamics with IoT sensor networks enables predictive maintenance contracts for heat exchanger cleaning cycles, opening recurring revenue streams.
Industry Challenges
- Naval architect specialization gap:System integration engineers capable of optimizing cooling loop topology for variable-speed electric propulsion remain scarce, extending project timelines.
- Classification society certification lag:Lloyd's Register and DNV rule updates for ammonia-fuelled vessels trail fuel technology availability, freezing specification finalization for early-adopter shipowners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Engine Cooling Systems Market |
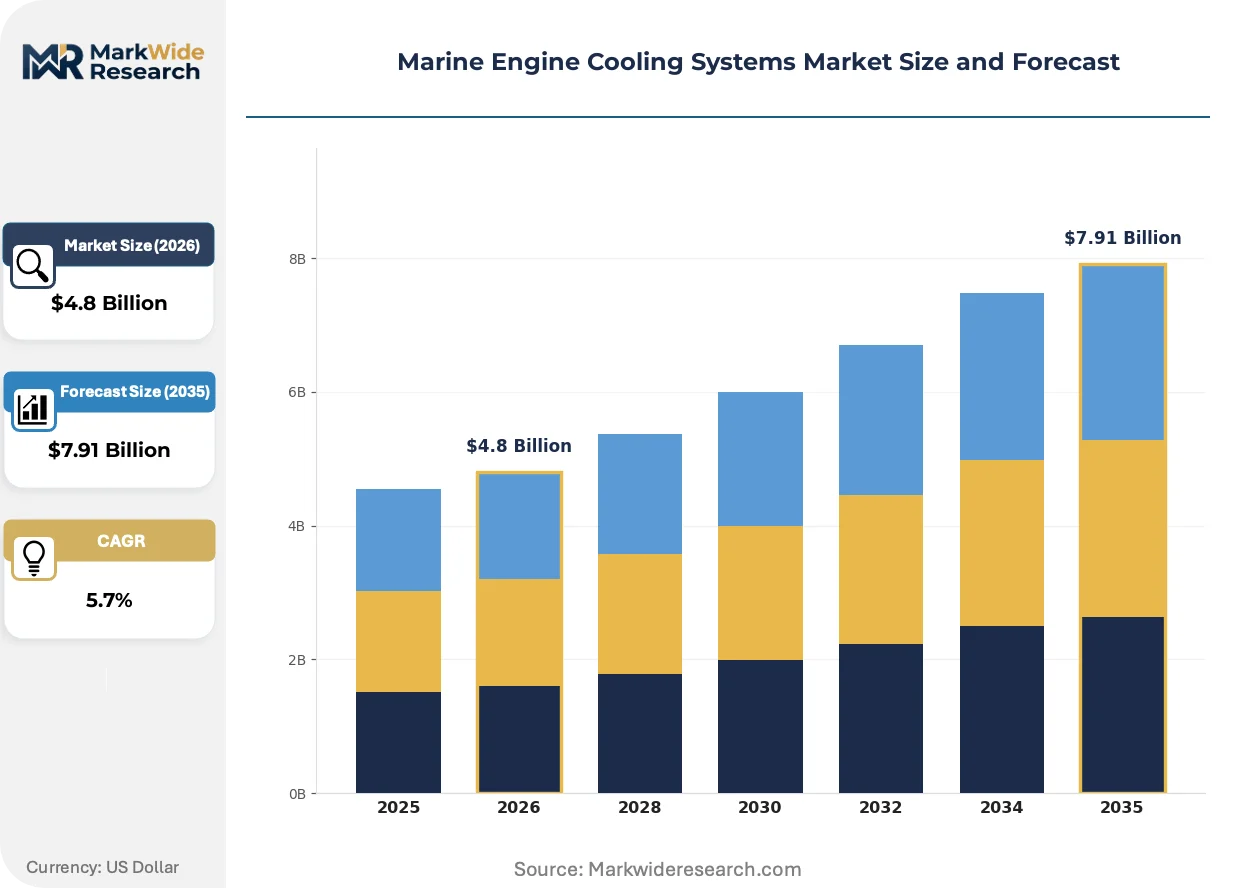
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Water Cooling, Fresh Water Cooling, Heat Exchangers, Oil Coolers Application: Commercial Vessels, Recreational Boats, Fishing Boats, Cargo Ships Technology: Direct Cooling, Indirect Cooling, Thermoelectric, Liquid Cooling End User: Shipbuilders, Vessel Operators, Maintenance Providers, Navy |
| Companies Covered | Alfa Laval, Wärtsilä, MAN Energy Solutions, Volvo Penta, Caterpillar, Scania, Yanmar, EJ Bowman, CP Performance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Engine Cooling Systems Market Strategic Shifts
Cooling system architectures are fragmenting across fuel-type specializations as shipyards confront divergent thermal profiles from methanol, ammonia, and battery-electric propulsion alternatives.
Indirect freshwater cooling circuits are hybridizing with selective catalytic reduction thermal management modules. Container vessel operators in the Asia-Europe trade lane are specifying these integrated packages to separate corrosive seawater from engine jackets while meeting IMO Tier III NOx limits. The technology is compressing demand for standalone auxiliary coolers as shipyards consolidate thermal infrastructure into unified skid-mounted units.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in secondary cooling loops for offshore support vessels. Shipowners operating in North Sea waters are retrofitting CO2-based refrigeration systems to maintain platform supply vessel certifications. Heat pump manufacturers serving this segment are accelerating R&D for transcritical CO2 heat exchangers rated for marine vibration standards.
Shipyard procurement departments are unbundling cooling system specification from engine OEM packages. Independent heat exchanger specialists are winning direct contracts with Korean and Japanese builders seeking component-level cost transparency. This pattern is most visible in Ulsan and Nagasaki, where classification society type-approval databases enable buyers to compare plate heat exchanger performance curves without engine supplier intermediation.
Marine Engine Cooling Systems Market Segmentation
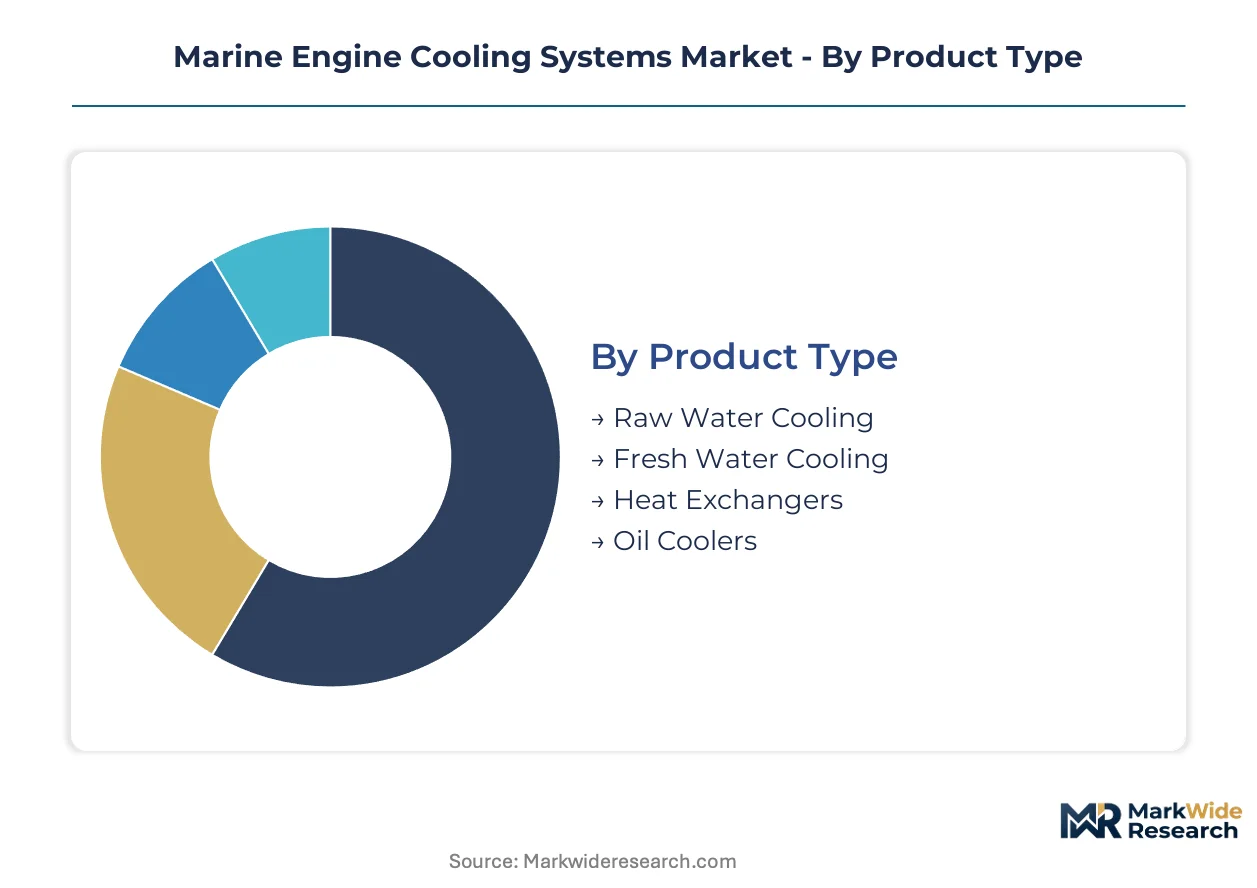
Marine engine cooling systems fragment across incompatible thermal architectures, each segment carrying distinct replacement cycles and specification authority. Shipyards and vessel operators prioritize different performance attributes, creating tiered procurement patterns that reshape supplier positioning.
Product Type:
Replacement velocity varies dramatically across product categories, with consumable components cycling faster than capital-intensive infrastructure.
- Heat Exchangers:Plate-and-frame configurations fabricated from copper-nickel alloys dominate maintenance spend due to seawater corrosion exposure. Korean shipyards in the Ulsan-Jeolla cluster specify oversized units to accommodate IMO Tier III exhaust after-treatment thermal loads.
- Fresh Water Cooling:Closed-loop circuits with deionized water and glycol mixtures protect engine jackets from galvanic degradation. Container vessel operators on Asia-Europe routes favor these systems for their separation of corrosive seawater from precision-machined components.
- Raw Water Cooling:Direct seawater circuits serve auxiliary machinery in coastal fishing fleets where capital constraints limit system complexity.
- Oil Coolers:Shell-and-tube designs manage lubricant viscosity for medium-speed diesel installations.
Heat exchangers anchor the volume base while fresh water cooling gains share at the steepest rate.
Application:
Commercial intensity and regulatory exposure create four distinct customer profiles with divergent technical requirements.
- Cargo Ships:Bulk carriers and tankers demand redundant cooling capacity for continuous operations across tropical and polar routes. South Korean builders specify integrated thermal management skids combining engine jacket cooling with SCR temperature control.
- Commercial Vessels:Ferries and offshore supply vessels face EU F-Gas Regulation mandates for refrigerant phase-down, accelerating CO2-based secondary cooling retrofits in North Sea operations.
- Fishing Boats:Smaller displacement vessels in Southeast Asian fleets prioritize direct cooling simplicity over corrosion resistance.
- Recreational Boats:Yacht builders in Italy and the Netherlands specify compact freshwater heat exchangers for aesthetic engine bay packaging.
Cargo ships generate the highest absolute demand while commercial vessels drive specification complexity fastest.
Technology:
Capital deployment and operating philosophy split the market between legacy direct systems and precision indirect architectures.
- Indirect Cooling:Dual-circuit designs with titanium or cupronickel heat exchangers separate engine jackets from seawater. Japanese shipyards in Nagasaki specify these for LNG carriers requiring precise temperature control for membrane cargo containment systems.
- Direct Cooling:Raw seawater flows through engine blocks in cost-constrained applications, accepting accelerated maintenance intervals in high-salinity environments.
- Liquid Cooling:Battery-electric and hybrid propulsion systems deploy dielectric fluids for thermal management of power electronics.
- Thermoelectric:Solid-state cooling remains experimental for marine applications, limited by efficiency constraints at vessel-scale thermal loads.
Indirect cooling commands specification preference for newbuilds while liquid cooling expands most quickly from electrification mandates.
End User:
Purchasing authority and technical capability determine whether systems are specified at build or retrofitted during service life.
- Shipbuilders:Korean and Japanese yards hold primary specification authority for newbuild cooling architectures, bundling or unbundling from engine OEM packages based on procurement transparency objectives.
- Vessel Operators:Container lines and tanker owners increasingly intervene in cooling system selection to secure fuel efficiency guarantees and residual value protection.
- Maintenance Providers:Independent service contractors dominate heat exchanger plate replacement and cleaning cycles, particularly in Singapore and Rotterdam hub ports.
- Navy:NATO fleet modernization programs specify militarized cooling packages with shock resistance and redundancy requirements distinct from commercial standards.
Shipbuilders retain specification control for new construction while vessel operators gain influence fastest through performance contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in marine cooling equipment trace vessel construction flows. South Korea and China dominate newbuild output, while Germany and Japan supply precision heat exchange components. Norway and Singapore anchor aftermarket service hubs for retrofit installations.
South Korea
Ulsan-Jeolla shipbuilding cluster generates concentrated demand for membrane-type LNG carrier cooling packages. The Ministry of Trade, Industry and Energy subsidizes green ship technology development under the K-Shipbuilding Super Gap initiative. Hyundai Heavy Industries and Samsung Heavy Industries specify oversized heat exchangers for IMO Tier III compliance in vessels bound for European charterers.
China
State-owned shipyards in Shanghai and Dalian expand output of bulk carriers requiring redundant cooling capacity for tropical route operations. The Ministry of Ecology and Environment enforces domestic emission control area rules paralleling IMO Annex VI standards. Jiangsu province foundries supply corrosion-resistant pump castings to European system integrators facing supply bottlenecks.
Germany
Engine OEMs in Augsburg and Hamburg bundle cooling architectures with medium-speed diesel packages for container vessel operators. The Federal Maritime and Hydrographic Agency implements EU MRV monitoring requirements for vessels calling German ports. Bavaria-based component fabricators specialize in titanium plate heat exchangers for chemical tanker applications.
Japan
Nagasaki shipyards specify indirect freshwater cooling for LNG carriers requiring precise temperature control of cargo containment systems. METI coordinates ammonia fuel transition roadmaps affecting heat rejection specifications for next-generation vessels. Kobe and Osaka house engineering consultancies optimizing cooling loop topology for dual-fuel engine installations.
Norway
Offshore vessel operators in Bergen and Stavanger retrofit CO2-based secondary cooling systems to comply with EU F-Gas Regulation phase-down mandates. The Norwegian Maritime Authority enforces strict ballast water and emission standards for North Sea operations. Trondheim research institutes collaborate with shipowners on digital twin integration for predictive heat exchanger maintenance.
Marine Engine Cooling Systems Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower but defensible positions. The vendor base stratifies across three tiers: diversified power plant OEMs bundling cooling with engine packages, dedicated thermal management houses controlling heat exchanger plate supply, and regional fabricators serving aftermarket replacement cycles. Consolidation pressure concentrates among mid-scale European specialists lacking backward integration into metallurgy. Dominant competitive moves include captive supply of copper-nickel alloy plates and strategic unbundling of cooling specifications from engine OEM procurement.
Among Nordic-integrated power plant suppliers, Wärtsilä exemplifies the platform bundling archetype through its combined engine-cooling offerings. Alfa Laval anchors the component specialist tier with upstream control over heat exchanger plate manufacturing. MAN Energy Solutions occupies a hybrid position spanning both system integration and precision component fabrication. These three entities represent contrasting strategic postures toward specification authority in shipyard procurement.
| Leading Market Players |
|---|
| Alfa Laval |
| Wärtsilä |
| MAN Energy Solutions |
| Volvo Penta |
| Caterpillar |
| Scania |
| Yanmar |
| EJ Bowman |
| CP Performance |
| Others |
Value Chain & Pricing Dynamics
Copper-nickel alloy foundries in Jiangsu province and South Korea's Gyeongsang region concentrate upstream metallurgy supply, anchoring margin pools in heat exchanger plate fabrication where backward integration creates pricing power for component specialists.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium titanium-plate configurations, standard cupronickel assemblies, and economy-grade aluminum alternatives. Price differentiation hinges on IMO Tier III certification tier and volume scale in long-dated shipyard contracts. Cost compression in economy tiers is intensifying as Chinese foundries expand casting capacity. Container vessel operators demonstrate lowest price sensitivity due to fuel efficiency guarantee requirements, while coastal fishing fleet buyers maximize procurement leverage through spot replacement cycles.
Supply Chain Analysis
Contract manufacturing for corrosion-resistant pump housings and valve assemblies concentrates in Chinese facilities around Shanghai and Dalian, plus South Korean foundries serving the Ulsan-Jeolla cluster. Raw material dependencies center on copper-nickel alloy feedstock, titanium billet, and specialized gasket polymers. Single-source vulnerability runs through Jiangsu province casting capacity for European system integrators. Distribution runs through shipyard procurement departments unbundling specifications from engine OEM packages, with direct component contracts accelerating in Korean and Japanese builder relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine engine cooling systems constitute a defensive-moat market where regulatory entrenchment through IMO Tier III certification and classification society type-approval creates substantial switching costs for vessel operators.
For Market Incumbents: Entrench position through captive supply of copper-nickel alloy plates and in-house production of titanium heat exchanger configurations to offset margin pressure from Chinese foundry expansion. Deepen certification investment with Lloyd's Register and DNV for ammonia-fuelled vessel architectures before rule finalization freezes competitor access. Prioritize digital twin integration capabilities to secure recurring predictive maintenance revenue streams.
For New Entrants and Emerging Players: Establish a beachhead in CO2-based secondary cooling retrofits for North Sea offshore vessels facing EU F-Gas Regulation phase-down mandates. Target battery-electric and hybrid propulsion liquid cooling segments where electrification mandates expand specification scope beyond incumbent engine-cooling bundling. Pursue direct contracting relationships with Korean and Japanese shipyards seeking component-level procurement transparency.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale European thermal management specialists lacking backward integration into metallurgy. Long-term viability favors targets with IMO Tier III certification entrenchment and established type-approval databases enabling buyer comparison without engine supplier intermediation. Monitor ammonia fuel transition roadmaps from METI and Lloyd's Register rule updates as inflection signals for retrofit cooling capacity demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Metallurgy | Captive copper-nickel plate supply insulates margin from commodity volatility for Korean shipyard contracts. |
| IMO Tier III Certification Investment | Classification society type-approval creates regulatory moat against unbundled component competitors. |
| Digital Twin Platform Development | Predictive maintenance contracts with Singapore and Rotterdam hub operators secure recurring revenue. |
| Ammonia Fuel Cooling Architecture R&D | Early heat rejection specification for METI roadmaps positions for Lloyd's Register rule finalization. |
| Direct Shipyard Contracting Expansion | Bypassing engine OEM intermediation captures specification authority in Ulsan and Nagasaki procurement. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with shipyard procurement directors, marine engineering consultants, classification society surveyors, and heat exchanger maintenance contractors in Singapore and Rotterdam; and secondary validation through Lloyd's Register type-approval databases, IMO MARPOL Annex VI submissions, customs trade records for copper-nickel alloy imports, and SEC filings from diversified power plant OEMs. Bottom-up vessel newbuild projections and top-down fleet modernization budget analysis were triangulated against manufacturer shipment disclosures.
Forecast inputs incorporated propulsion technology transition curves, regulatory enforcement timelines across EU MRV and IMO Annex VI frameworks, and shipyard capacity utilization in South Korea and China. Segmentation modeling spanned product architecture, vessel application class, cooling technology type, and end-user purchasing authority. CAGRs were derived from installed base replacement cycles and newbuild specification trends across the projection horizon. Ammonia and methanol fuel combustion heat rejection profiles were stress-tested as scenario inputs.
Stress conditions across copper-nickel alloy pricing bands, IMO enforcement stringency variations, and shipyard capacity allocation shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding classification society rule finalization schedules and alternative fuel trial adoption curves. Quarterly review of METI ammonia roadmap milestones and Lloyd's Register certification update releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Big Data Market
Marine
Marine Fuel Injector Market
Marine
Europe ROV Market
Marine
Marine Chronometers Market
Marine
Singapore Container Transshipment Market
Marine
Autonomous Ships Market
Marine
Marine Propeller Market
Marine
Boat Trolling Motor Market
Marine
LNG Bunkering Vessel Market
Marine
Integrated Bridge System for Ships Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Pneumatic Marine Fender Market
Marine
Buoys and Beacon Market
Marine
Marine Elevators Market
Marine
India Boat Davits Market
Marine
Marine Shaft Power Meter Market