
 Marine Dynamic Positioning System Market | 2026-2036
Marine Dynamic Positioning System Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Dynamic Positioning System Market Foresight
Lease-to-own and power-by-the-hour arrangements is narrowing the competitive field to capital-rich system integrators and their financing partners. Kongsberg Gruppen leverages its integrated sensor-to-thruster architecture across Arctic offshore fleets. Wärtsilä Corporation anchors its position through captive manufacturing of high-thrust azimuth units. ABB competes on electrical system density for electric-hybrid vessel architectures.
A marine dynamic positioning system uses computer-controlled thrusters to maintain a vessel's position and heading without anchors, typically achieving position-keeping accuracy within one to three meters depending on equipment class and sea state. The system integrates GPS, inertial measurement units, and acoustic position references to calculate force commands distributed across bow and stern thrusters. Control systems and thrusters capture the dominant share of component value, with thruster manufacturing requiring specialized foundry capacity that limits supplier entry. Offshore vessels constitute the largest end-user category, though research vessels represent the fastest-growing segment driven by deep-ocean mapping programs. Active technology leads installations while hybrid configurations gain share in vessels with variable power demand profiles.
The International Maritime Organization's DP equipment class standards shape system redundancy requirements, while classification societies including DNV and Lloyd's Register enforce station-keeping capability benchmarks for commercial certification. The US Coast Guard and EU's MRV framework impose operational documentation that affects system data-logging specifications. Stakeholders must weigh technology refresh cycles against regulatory compliance timelines as next-generation connectivity standards alter position-reference architectures.
Market Dynamics
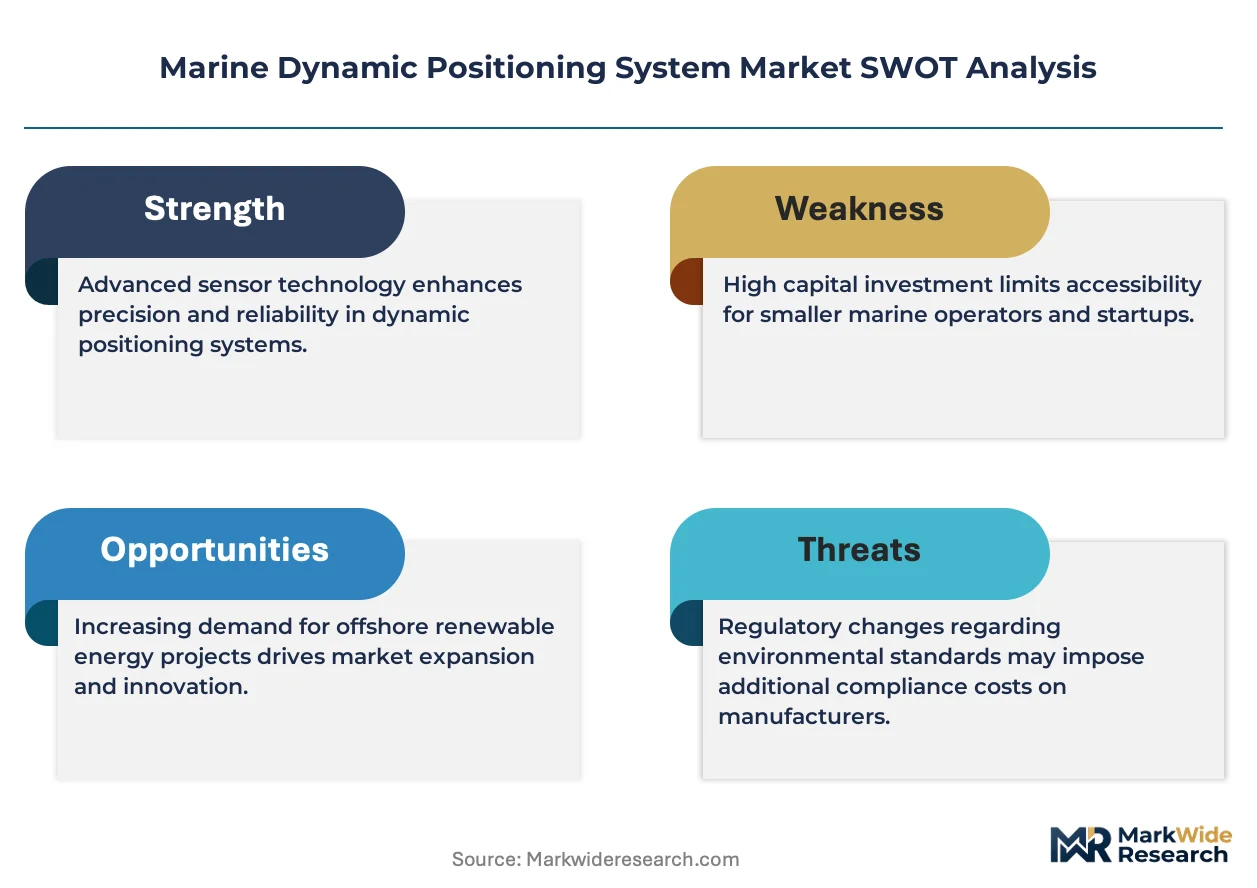
Lease-to-own financing structures are compressing capital barriers for offshore drilling contractors while concentrating vendor relationships around capital-rich system integrators with captive manufacturing capabilities.
Growth Catalysts
- IMO DP Equipment Standards:Updated classification requirements for redundant station-keeping capabilities are mandating system upgrades across existing offshore fleets. Vessel operators face certification deadlines that accelerate replacement cycles.
- Subsea Construction Density:Norway's North Sea cluster sustains concentrated demand for precision position-keeping during pipeline laying and platform installation. Arctic offshore development expands addressable vessel hours.
- Acoustic Position Reference Integration:Hybrid sensor architectures combining GPS with inertial measurement units are extending operational weather windows. Deepwater drilling contractors capture productivity gains from reduced downtime.
Market Restraints
- Specialized Foundry Bottlenecks:High-thrust azimuth thruster manufacturing requires scarce casting capacity concentrated among European and East Asian suppliers. Lead times for critical propulsion components extend procurement cycles.
- Classification Society Friction:DNV and Lloyd's Register enforce divergent interpretation of station-keeping benchmarks across flag states. Vessel owners face redundant certification costs for international operations.
- Electrification Skill Scarcity:Electric-hybrid vessel architectures demand power electronics expertise that outpaces marine engineering training pipelines. System integrators compete for limited commissioning talent.
Strategic Opportunities
- Research Vessel Expansion:Deep-ocean mapping programs in the Pacific and Atlantic basins are generating demand for Class 3 DP systems with sub-meter accuracy. Academic and governmental research fleets represent underpenetrated volume.
- Power-by-the-Hour Penetration:Operational expenditure models are displacing capital purchase structures among mid-tier offshore service operators. Financing partnerships unlock fleet modernization for credit-constrained buyers.
- Arctic Route Development:Northern Sea Route ice-class vessel requirements are creating specifications for ice-strengthened thruster configurations. Russian and Norwegian operators pioneer cold-climate DP reliability standards.
Industry Challenges
- Control System Integration Complexity:Legacy vessel automation architectures require costly retrofit engineering to accommodate modern distributed processing nodes. Shipyards face margin compression from unplanned software interface work.
- Thruster Commissioning Bottlenecks:Sea trial validation for redundant propulsion configurations demands extended vessel downtime. Offshore contractors absorb revenue loss during extended acceptance testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Dynamic Positioning System Market |
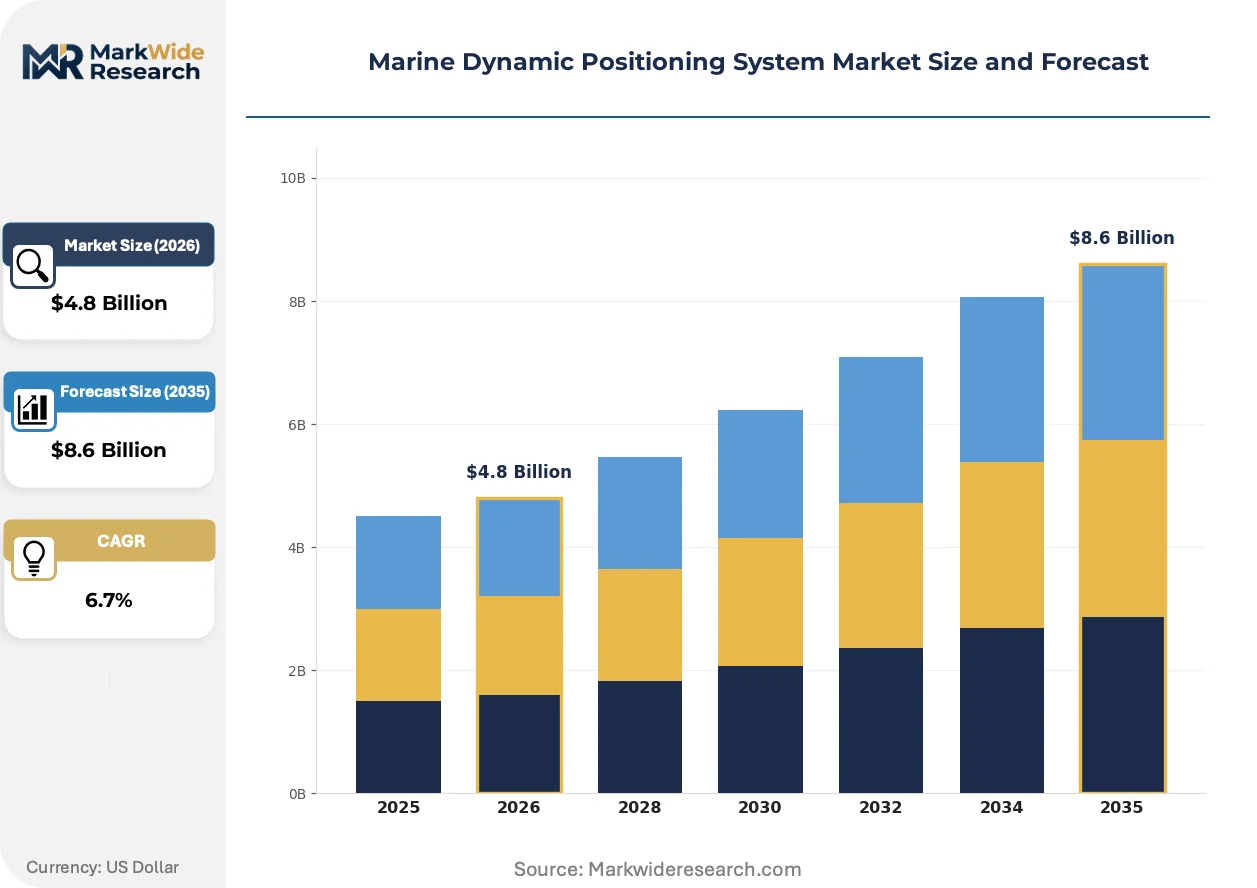
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active, Hybrid, Satellite, Inertial End User: Offshore Vessels, Research Vessels, Cargo Ships, Support Vessels Application: Drilling Operations, Offshore Construction, Surveying, Salvage Operations Component: Control Systems, Position Reference Systems, Sensors, Thrusters |
| Companies Covered | ABB, Kongsberg Gruppen, Wärtsilä Corporation, GE Vernova, L3Harris Technologies, Rolls-Royce, Volvo Penta, Marine Technologies, Navis Engineering Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Dynamic Positioning System Market Shifts & Advancements
Control architectures and position-reference technologies are converging around distributed computing and multi-sensor fusion, compressing system response latency while expanding operational envelopes.
Artificial intelligence-based thrust allocation algorithms are migrating from centralized programmable logic controllers to edge-computing nodes at individual thruster units. Offshore drilling contractors pilot these architectures in North Sea operations where rapid environmental load changes stress conventional control loops. Distributed processing is compressing system latency and enabling predictive thruster maintenance.
The EU's Maritime Safety Package and associated MRV framework are mandating enhanced operational data logging for DP-equipped vessels above specified tonnage thresholds. Classification societies enforce harmonized electronic record-keeping that shapes control system software specifications. European-flagged offshore fleets are responding with integrated vessel management systems that unify DP logging with emissions monitoring.
Charterers are unbundling DP system maintenance from lump-sum vessel hire agreements, creating standalone service contracts with original equipment manufacturers. Offshore drilling contractors in the North Sea and Gulf of Mexico lead this transition, seeking predictable opex structures and guaranteed availability. Equipment vendors capture recurring revenue streams while absorbing operational risk through uptime guarantees.
Marine Dynamic Positioning System Market Segmentation
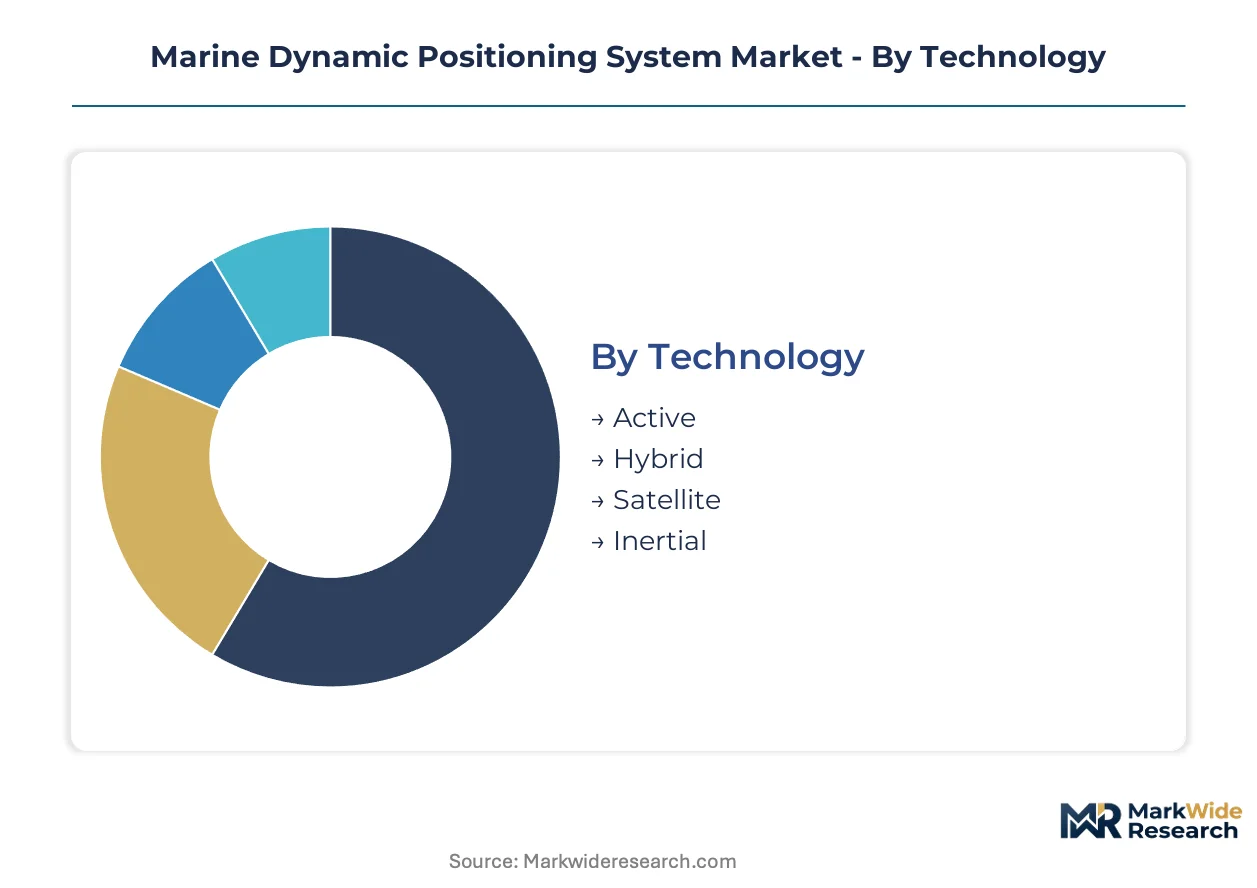
Segmentation in marine dynamic positioning systems reveals how vessel operators balance capital intensity against operational requirements. Technology choices determine redundancy levels, while end-user categories expose divergent accuracy demands and certification burdens across maritime sectors.
Technology:
Cost tier stratification separates proven architectures from emerging hybrid configurations that command premium positioning.
- Active:Continuous thruster modulation maintains station-keeping through real-time force distribution across all available propulsion units. Offshore drilling contractors in Norway's North Sea cluster specify Class 2 and Class 3 active systems for subsea construction where single-point failure risks cascade into platform damage.
- Hybrid:Blended power architectures switch between diesel-mechanical and electric drive modes based on load profiles, reducing fuel consumption during transit versus station-keeping. Arctic offshore fleets operating extended ice-free seasons are rotating toward hybrid installations to manage variable power demand without redundant generator capacity.
- Satellite:GPS-differential corrections provide primary position reference for vessels operating beyond acoustic range.
- Inertial:Motion-sensing gyroscopes and accelerometers bridge reference gaps during GPS signal interruption.
Active systems hold installed capacity. Hybrid configurations are rotating up the share rankings.
End User:
Application maturity varies sharply between established offshore energy infrastructure and emerging deep-ocean research programs.
- Offshore Vessels:Platform supply vessels, anchor-handling tugs, and construction barges constitute the revenue core with established replacement cycles tied to IMO equipment class mandates. Gulf of Mexico and North Sea operators face compressed upgrade timelines as classification societies enforce redundant station-keeping benchmarks.
- Research Vessels:Academic and governmental fleets conducting deep-ocean mapping require Class 3 systems with sub-meter accuracy for seabed instrumentation placement. Pacific basin programs in the United States and Japan are expanding addressable hours for high-precision surveying.
- Cargo Ships:Container and bulk carriers adopt simplified DP for harbor maneuvering and restricted waterway transit.
- Support Vessels:Standby rescue and offshore accommodation ships maintain station-keeping for personnel transfer operations.
Offshore Vessels dominate current installations. Research Vessels are climbing the fastest as governmental oceanographic budgets expand.
Application:
Operational risk profiles dictate redundancy requirements, with drilling and construction commanding the highest equipment class certifications.
- Drilling Operations:Dynamic positioning maintains floating production units and drillships over subsea wells without anchor spread, achieving position-keeping within three meters in moderate sea states. Deepwater contractors in Brazil and West Africa specify redundant thruster configurations where disconnect capability prevents blowout escalation.
- Offshore Construction:Pipeline laying and platform installation demand sustained precision during welding and module mating operations. Norwegian contractors pioneered the acoustic position reference integration now standard for North Sea subsea infrastructure.
- Surveying:Hydrographic and geophysical mapping requires stable sensor platforms for multibeam sonar and sub-bottom profiler deployment.
- Salvage Operations:Wreck recovery and emergency response vessels deploy portable DP systems for rapid mobilization to incident sites.
Drilling Operations anchor equipment value. Offshore Construction is rotating up the share rankings.
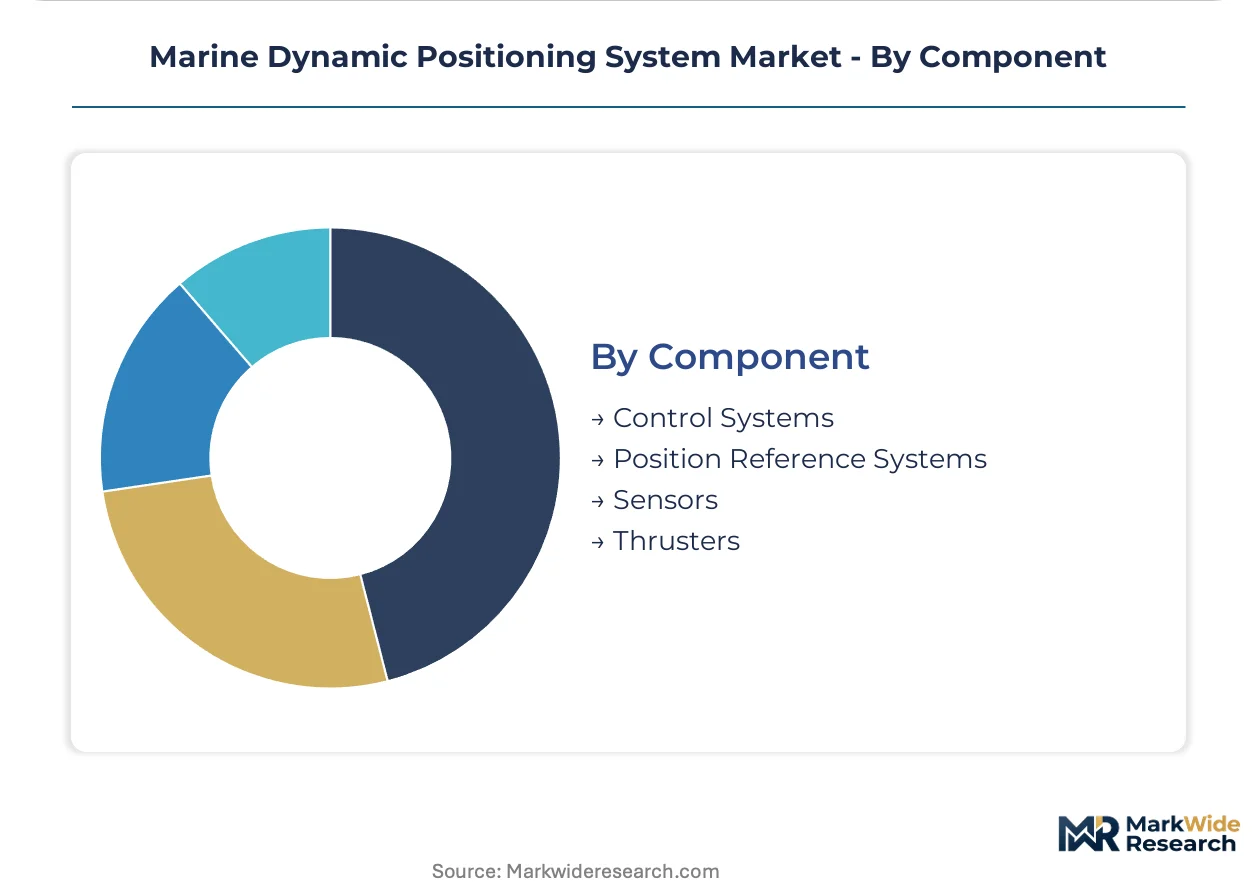
Component:
Supply concentration shapes procurement economics, with thruster manufacturing bottlenecked by specialized foundry capacity.
- Thrusters:High-thrust azimuth and tunnel units convert electrical or hydraulic power into vectored thrust for six-degree-of-freedom control. European and East Asian foundries constrain output for ducted propeller castings, extending lead times for offshore newbuild programs.
- Control Systems:Distributed processing architectures allocate thrust commands across redundant computing nodes with failover logic. Electric-hybrid vessel programs are driving demand for integrated power management software that unifies propulsion with hotel load scheduling.
- Position Reference Systems:GPS, inertial measurement units, and acoustic transponders triangulate vessel position against seabed beacons or satellite constellations.
- Sensors:Wind, current, and motion sensors feed environmental load data into predictive control algorithms.
Thrusters capture the dominant value share. Control Systems are rotating up the share rankings as software-defined architectures displace legacy programmable logic controllers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's offshore tax incentives and Brazil's local content mandates are accelerating DP system procurement cycles. National regulators in key maritime economies are tightening equipment certification timelines. Subsea construction clusters in the North Sea and Campos Basin concentrate vessel demand.
Norway
Arctic offshore development and subsea infrastructure replacement sustain dense DP vessel utilization. The Norwegian Maritime Authority enforces IMO DP equipment class standards through mandatory periodic surveys. Stavanger and Bergen anchor the North Sea cluster where drilling contractors specify redundant thruster configurations.
Brazil
Deepwater pre-salt field development drives demand for Class 3 systems on floating production units. Petrobras local content requirements mandate domestic integration partnerships for foreign system vendors. The Campos Basin and Santos Basin concentrate drillship and FPSO construction at Rio de Janeiro shipyards.
United States
Gulf of Mexico decommissioning activity and wind farm installation expand addressable vessel hours. The US Coast Guard enforces DP operational documentation requirements under 46 CFR Subchapter I. Houston anchors the supply chain for offshore service vessel operators seeking power-by-the-hour arrangements.
China
State-backed offshore wind construction and deepwater drilling programs expand DP-equipped fleet capacity. China Classification Society implements harmonized DP equipment standards aligned with IMO guidelines. Shanghai and Dalian shipyards integrate domestic control system architectures into newbuild offshore vessels.
United Kingdom
North Sea asset life extension and offshore wind interconnection projects sustain precision positioning demand. The Maritime and Coastguard Agency enforces station-keeping capability benchmarks for UK-flagged offshore fleets. Aberdeen maintains engineering density for DP system commissioning and maintenance services.
Marine Dynamic Positioning System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across financing, manufacturing, and integration layers. The market concentrates around capital-rich system integrators with captive thruster production and distributed processing expertise. Three archetypes dominate: integrated sensor-to-thruster architects, electrical system density specialists, and hybrid power management developers. Competitive moves center on lease-to-own financing partnerships and Arctic-class thruster certification programs.
Among Nordic integrated system architects, Kongsberg Gruppen and Wärtsilä Corporation exemplify the capital-intensive archetype combining proprietary thruster manufacturing with control software development. ABB represents the electrical density specialist position, occupying a role centered on power electronics integration for electric-hybrid vessel architectures. These three anchors sit within a vendor base where financing partnerships and captive foundry capacity determine competitive access.
| Leading Market Players |
|---|
| ABB |
| Kongsberg Gruppen |
| Wärtsilä Corporation |
| GE Vernova |
| L3Harris Technologies |
| Rolls-Royce |
| Volvo Penta |
| Marine Technologies |
| Navis Engineering Oy |
| Others |
Supply & Pricing Matrix
Single-source dependency on Norwegian and Finnish foundry capacity for high-thrust azimuth thruster castings determines both pricing tier spreads and supply chain shape, compressing margins for mid-tier integrators while concentrating premium pricing power among captive manufacturers.
Pricing Analysis
Certification level creates the primary spread between Class 3 redundant configurations and simplified Class 1 architectures. Three-tier pricing structure across premium, standard, and economy levels reflects IMO equipment class mandates, with offshore drilling contractors absorbing premium tiers for station-keeping reliability. Cost compression in economy-tier control systems is intensifying because software-defined architectures displace legacy programmable logic controllers. Research vessel operators demonstrate highest price sensitivity due to governmental budget constraints, while Arctic offshore fleets show lowest sensitivity given ice-class specification requirements.
Supply Chain Analysis
Export-control restrictions on acoustic position reference transponder technology limit flows between European suppliers and certain flagged fleets. Manufacturing gravity centers on Norway, Finland, and Japan for specialized ducted propeller castings. The supply chain draws from rare earth magnet suppliers for permanent-magnet thruster motors and precision gyroscope manufacturers for inertial measurement units. Single-source vulnerability concentrates in European foundries with extended lead times for critical propulsion components. Distribution runs through system integrators with captive manufacturing and direct shipyard contracting for newbuild programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore drilling contractor capital expenditure cycles frame this market as a cyclical recovery, with lease-to-own financing structures accelerating fleet modernization timelines.
For Market Incumbents: Entrench position through captive foundry capacity expansion in Norway and Finland while deepening software integration expertise for electric-hybrid architectures. Threat from emerging Chinese control system vendors demands accelerated certification investment with DNV and Lloyd's Register. Backward integration into position reference sensor manufacturing secures supply continuity. For New Entrants and Emerging Players: Research vessel fleets in the Pacific basin represent the most penetrable entry point given underdeveloped service infrastructure and governmental procurement transparency. Power-by-the-hour financing partnerships with credit-constrained mid-tier offshore service operators unlock fleet modernization without capital purchase barriers. Commissioning and maintenance service contracts offer recurring revenue entry with lower capital intensity than hardware manufacturing. For Investors and Strategic Acquirers: Control system software specialists with electric-hybrid vessel management capabilities present the highest-value acquisition profile given electrification skill scarcity. Long-term viability hinges on regulatory compliance timing as IMO equipment class standards reshape replacement cycles. Watch for Petrobras local content mandate enforcement as inflection indicator for Brazilian market access.| Strategic Initiative | Industry Significance |
|---|---|
| Arctic-Class Thruster Certification | Ice-strengthened configurations capture Northern Sea Route vessel specifications ahead of regulatory finalization. |
| Power-by-the-Hour Financing Partnership | Operational expenditure models unlock fleet modernization for credit-constrained offshore service operators. |
| Acoustic Position Reference Integration | Hybrid sensor architectures extend operational weather windows for deepwater drilling contractors. |
| Distributed Processing Control Migration | Edge-computing nodes at thruster units compress system latency for rapid environmental load response. |
| Integrated Vessel Management System Development | Unified DP logging with EU MRV emissions monitoring satisfies Maritime Safety Package mandates. |
Research Methodology
The analysis maps active, hybrid, satellite, and inertial technology segments, each validated through offshore vessel operators, drilling contractor fleet managers, shipyard procurement directors, and classification society surveyors. Primary interviews with system integrators, thruster manufacturers, and control software developers combine with secondary validation from IMO circulars, DNV equipment class guidelines, Lloyd's Register rules, and customs trade data for specialized marine propulsion components. Bottom-up vessel fleet analysis and top-down maritime construction expenditure triangulation anchor volume estimates.
Assumptions held fixed include IMO DP equipment class enforcement timelines and current Arctic offshore development permitting frameworks, while oil price volatility and offshore wind installation rates were varied across scenarios. Segmentation dimensions modeled span technology type, end-user category, application risk profile, and component value chain position. CAGRs derive from vessel replacement cycle analysis against regulatory compliance deadlines. Forecast inputs incorporate subsea construction activity density in named basins and research vessel governmental budget appropriations.
Macroeconomic conditions sit as an overlay; deviation in offshore drilling day rates or marine construction contract awards would shift the trajectory. Forecasts reflect documented assumptions regarding classification society harmonization progress and foundry capacity expansion timelines. Material shifts in IMO equipment class standard implementation schedules or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Fin Stabilizer Market
Marine
Hydrofoil Market
Marine
Marine Engine Cooling Systems Market
Marine
Hybrid Fishing Boats Market
Marine
Marine Beacon Market
Marine
Marine and Marine Management Software Market
Marine
Hydrogen Ships Market
Marine
Dynamic Positioning System Market
Marine
Europe Recreational Boating Market
Marine
Europe Marine Communication Systems Market
Marine
Sliding Fender Market
Marine
Marine Glass Market
Marine
Unmanned Marine Vehicles Market
Marine
Asia-Pacific Electric Boat Market
Marine
Trim Tabs Market
Marine
Freighter Conversions Market