
 Marine Spreader Lights Market | 2026-2036
Marine Spreader Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Spreader Lights Market Analysis
A capital-intensity divergence between integrated manufacturers and assembly-only suppliers is reorganizing competitive tiers in marine lighting. Hella Marine leverages in-house semiconductor sourcing to sustain margin control across European yacht OEM channels. Lumitec LLC anchors its position through Florida-based production that dominates North American recreational boat retrofits. Aqualuma LED Lighting competes via specialized thermal management engineering for high-lumen marine environments.
Marine spreader lights are high-output deck-mounted luminaires engineered to deliver wide-angle illumination across vessel work areas, typically rated for saltwater corrosion resistance through anodized aluminum housings and sealed optical assemblies to IP67 standards or higher. Their primary function centers on crew safety and nighttime operational visibility for vessels ranging from private cruisers to commercial fishing trawlers. LED product type commands the dominant revenue share due to superior energy density and thermal efficiency versus legacy halogen alternatives, while surface mount installation type captures the fastest growth trajectory as boatbuilders prioritize streamlined deck aesthetics. DC power source configurations retain the largest installed base across existing vessel fleets, though solar-integrated spreads are gaining traction in charter yacht segments where auxiliary power independence carries operational value.
IMO SOLAS conventions, USCG navigation light regulations, and ABYC electrical standards collectively shape product certification requirements and market access barriers for marine spreader light suppliers. Compliance with these frameworks demands rigorous photometric testing and material traceability that elevates R&D budgets for new market entrants. Stakeholders must monitor evolving EPA vessel discharge guidelines and emerging state-level blue-light emission restrictions that could redirect product development priorities toward spectrally tunable marine fixtures.
Market Dynamics
IMO-mandated energy efficiency standards for vessel lighting are compressing product replacement cycles and forcing manufacturers to reengineer thermal management systems for LED-based marine spreader lights.
Growth Catalysts
- IMO SOLAS Convention Updates:Revised safety equipment mandates across international shipping lanes are accelerating retrofit demand for certified LED deck illumination on commercial vessels.
- Recreational Boat Electrification:Coastal Mediterranean marinas from Spain to Greece are prioritizing low-draw lighting systems to support battery-dependent auxiliary power architectures.
- ABYC Electrical Standards:Stricter marine electrical compliance in North American boatbuilding is disqualifying legacy halogen fixtures from new vessel certifications.
Market Restraints
- Semiconductor Supply Concentration:LED driver IC sourcing remains concentrated among East Asian foundries, exposing marine lighting OEMs to extended lead time volatility.
- Aluminum Price Volatility:Anodized aluminum housing costs fluctuate with LME pricing, compressing margin predictability for mid-tier fixture assemblers.
- IP67 Sealing Complexity:Achieving reliable saltwater ingress protection demands specialized gasket materials and assembly protocols that elevate unit production costs.
Strategic Opportunities
- Solar-Integrated Charter Yachts:Auxiliary power-independent lighting architectures are gaining operational value in Caribbean and Southeast Asian charter fleets seeking reduced generator runtime.
- Blue-Light Emission Restrictions:Emerging state-level spectral regulations in coastal US jurisdictions are creating first-mover advantage for tunable-CCT marine fixture developers.
- Surface Mount Aesthetic Prioritization:Premium yacht builders in Italy and the Netherlands are specifying flush-deck luminaire profiles that eliminate traditional bracket hardware.
Industry Challenges
- Photometric Testing Bottlenecks:Third-party certification laboratories face capacity constraints for IP67-rated marine lighting validation, extending product launch timelines.
- Thermal Engineering Talent Scarcity:Specialized expertise in high-lumen LED junction temperature management remains concentrated among a limited pool of marine-specific optical engineers.
- Legacy DC System Integration:Retrofitting LED spreaders onto existing 12V and 24V vessel electrical architectures requires custom driver compatibility solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Spreader Lights Market |
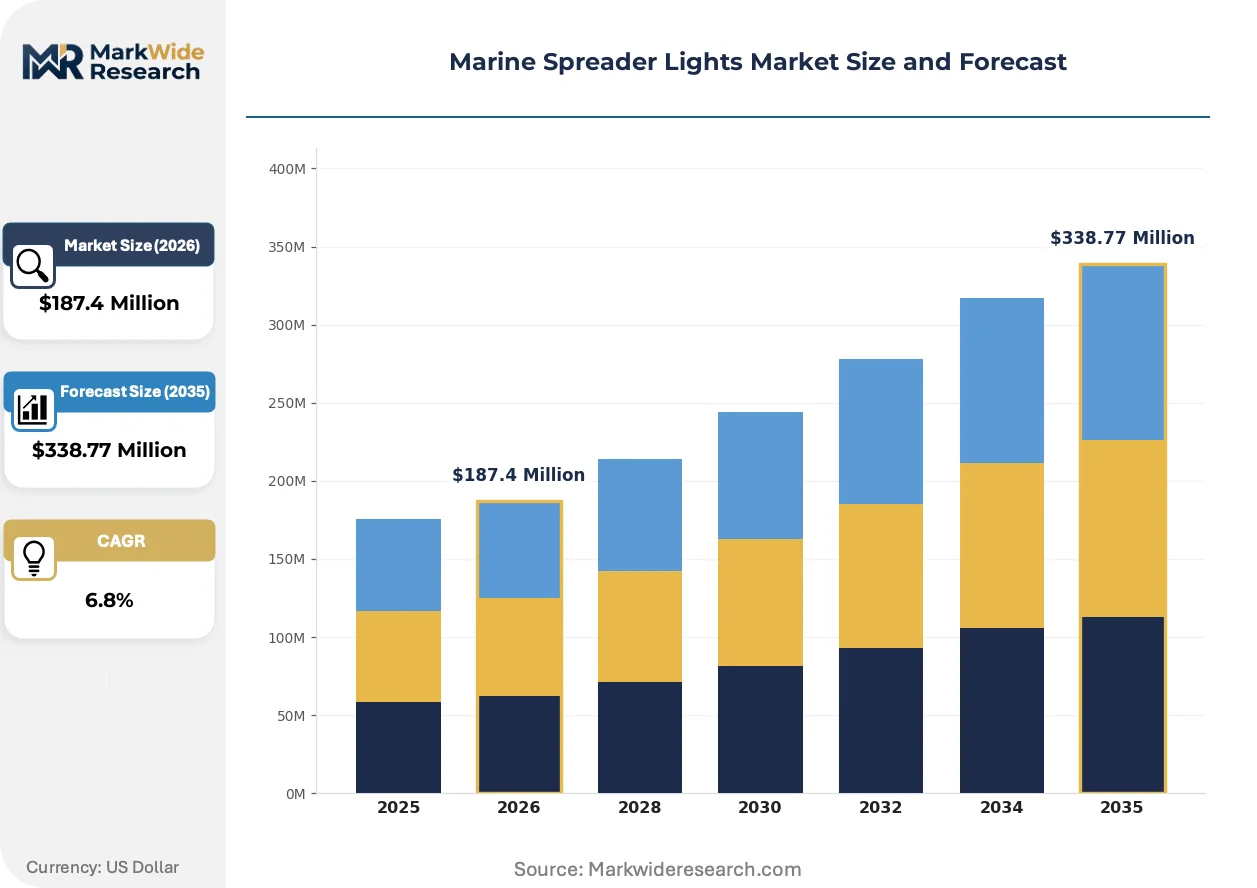
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Fluorescent Installation Type: Surface Mount, Flush Mount, Portable, Fixed Application: Recreational Boats, Commercial Vessels, Fishing Boats, Yachts Power Source: AC, DC, Solar, Battery |
| Companies Covered | Lumitec LLC, Hella Marine, Perko Inc., Aqualuma LED Lighting, OceanLED Marine Ltd., Lumishore, TACO Marine, Rigid Industries, Shadow-Caster Marine LEDs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Spreader Lights Market Emerging Trajectories
Marine spreader light development is converging on three vectors: optical package density, regulatory-driven spectral control, and procurement model restructuring toward direct OEM specification.
Chip-on-board LED technology is miniaturizing emitter arrays while maintaining lumen output targets previously requiring larger multi-die configurations. Superyacht builders in Germany and Finland are specifying these compact optical engines for hidden-deck installations where fixture visibility compromises aesthetic continuity. The form factor compression is miniaturizing housing dimensions and enabling integration into previously inaccessible mounting locations.
EPA vessel discharge guidelines are tightening scrutiny on coating and material composition in marine lighting fixtures. Manufacturers serving US-flagged commercial fleets must now document heavy metal content and anti-fouling treatment absence across supply chains. This regulatory layer most affects surface-mount product lines destined for Great Lakes fishing trawlers and Gulf Coast shrimping operations.
Boatbuilder procurement departments are consolidating vendor panels and demanding extended warranty terms backed by captive spare parts inventory. Direct specification relationships are displacing traditional marine distributor intermediaries for projects above fifty-unit annual volumes. This channel compression is most visible in Florida and Pacific Northwest recreational boat manufacturing clusters.
Marine Spreader Lights Market Segmentation
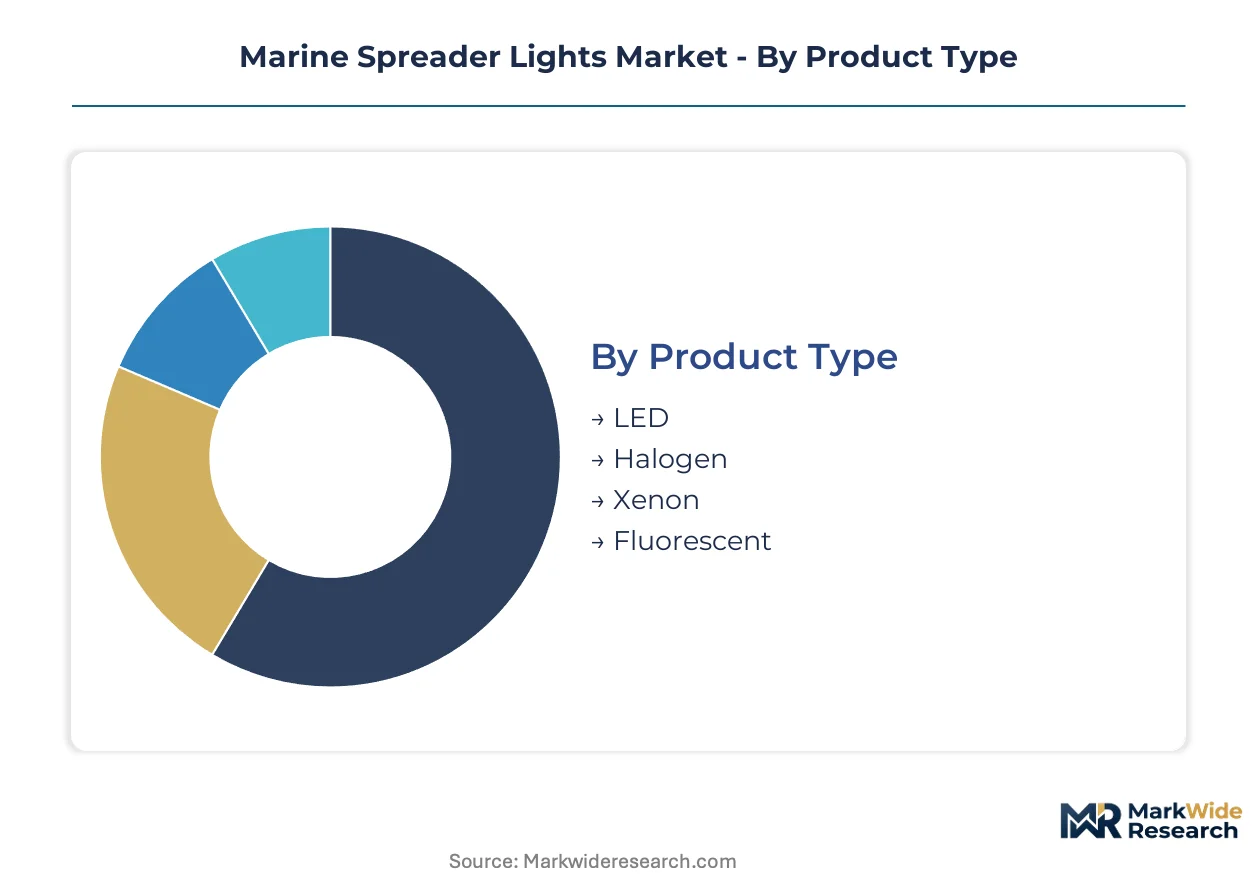
Marine spreader light segmentation reveals how regulatory pressure and vessel electrification reshape procurement priorities across distinct technical specifications. Understanding these category boundaries exposes where legacy technologies face displacement and where emerging configurations capture specification momentum.
Product Type:
Halogen fixtures face the most acute substitution threat as IMO energy mandates and ABYC electrical standards disqualify high-draw incumbents from new certifications.
- LED:Solid-state emitters deliver superior lumens-per-watt efficiency and thermal management through chip-on-board packaging. Demand concentrates in Mediterranean yacht retrofits from Spain to Greece where marina electrical infrastructure constraints favor low-draw systems.
- Halogen:Tungsten-filament technology retains installed-base presence on legacy commercial fishing trawlers with 12V DC architectures. Replacement cycles compress as USCG inspection protocols increasingly flag energy non-compliance.
- Xenon:High-intensity discharge lamps serve specialized searchlight applications requiring extreme throw distances.
- Fluorescent:Linear tube configurations persist in budget-conscious commercial vessel refits where initial cost dominates lifecycle calculations.
LED anchors the volume base while surface mount configurations gain share at the steepest rate.
Installation Type:
Premium Italian and Dutch yacht builders are driving specification shifts toward aesthetic-minimalist mounting approaches that eliminate visible hardware.
- Surface Mount:Bracket-attached fixtures dominate recreational boat retrofits across Florida and Pacific Northwest manufacturing clusters. ABYC electrical compliance requirements favor standardized mounting patterns that reduce installer certification burden.
- Flush Mount:Recessed deck integration satisfies superyacht aesthetic specifications from German and Finnish builders. Hidden-deck installations demand compact optical engines and specialized thermal dissipation pathways.
- Portable:Magnetic or clamp-based temporary lighting serves charter fleet flexibility requirements in Caribbean operations.
- Fixed:Permanent hardwired installations retain preference on commercial fishing vessels where vibration resistance exceeds repositioning value.
Surface mount retains the largest installed base while flush mount climbs the fastest among new-build specifications.
Application:
Commercial vessel segments impose the most stringent certification burdens, creating tiered market access where recreational applications tolerate broader supplier participation.
- Recreational Boats:Private cruiser and day-boat segments prioritize cost-optimized LED retrofits with plug-compatible driver electronics. Florida-based production clusters supply North American demand through streamlined distributor channels.
- Commercial Vessels:Cargo and passenger ships require SOLAS-certified fixtures with documented photometric testing and material traceability. IMO convention updates accelerate replacement demand across international shipping lanes.
- Fishing Boats:Trawler and longline operations in Gulf Coast and Great Lakes regions face EPA vessel discharge scrutiny on coating composition.
- Yachts:Superyacht specifications above fifty-meter LOA demand captive spare parts inventory and extended warranty terms backed by direct OEM relationships.
Recreational boats generate the highest unit volumes while yachts expand most quickly in absolute value terms.
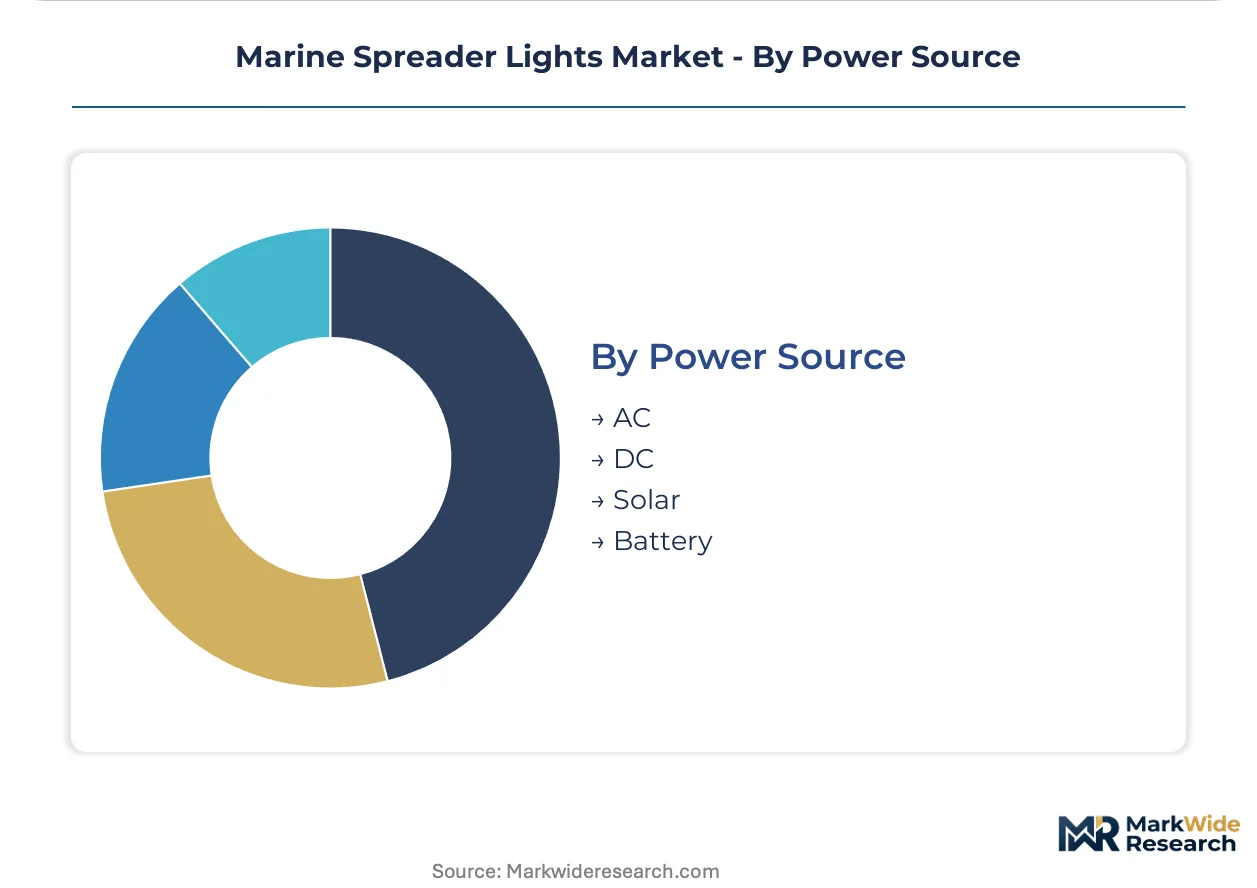
Power Source:
DC configurations face architectural pressure as auxiliary power independence becomes operational priority for charter operators seeking reduced generator runtime.
- DC:12V and 24V systems retain dominant installed base across existing vessel fleets. Retrofit LED compatibility demands custom driver solutions for legacy electrical architectures.
- Solar:Photovoltaic-integrated spreads gain traction in Southeast Asian and Caribbean charter fleets where auxiliary power independence carries operational value.
- AC:Shore-power-dependent configurations serve marina-tethered vessels with consistent grid access.
- Battery:Lithium-ion integrated luminaires address emergency lighting requirements on vessels with hybrid propulsion systems.
DC retains volume leadership while solar-integrated architectures show the steepest expansion trajectory among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in marine lighting components favor established manufacturing clusters with captive semiconductor access, while retrofit demand concentrates in coastal jurisdictions with aging vessel fleets and stringent energy regulations.
United States
Florida-based production clusters dominate North American recreational boat retrofits, with Tampa and Fort Lauderdale serving as distribution hubs for LED spreader systems. USCG navigation light regulations and ABYC electrical standards compress replacement cycles for legacy halogen fixtures. Gulf Coast shrimping operations and Great Lakes fishing trawlers face EPA vessel discharge scrutiny on coating composition, redirecting procurement toward certified suppliers.
Germany
Superyacht builders in Hamburg and Bremen specify flush-deck luminaire profiles that eliminate visible bracket hardware, driving demand for compact optical engines. CE marking requirements and EU RoHS compliance elevate material traceability burdens for fixture assemblers. Bavaria-based marine electronics integrators are consolidating vendor panels and demanding extended warranty terms backed by captive spare parts inventory.
China
LED driver IC sourcing concentrates in East Asian foundries, exposing marine lighting OEMs to extended lead time volatility for semiconductor components. GB standards and MIIT regulations shape domestic certification requirements for vessels operating under Chinese flag. Yangtze River Delta manufacturing clusters supply cost-optimized fixture housings to Southeast Asian charter fleet operators seeking auxiliary power-independent lighting architectures.
Italy
Premium yacht builders in Viareggio and La Spezia prioritize aesthetic-minimalist mounting approaches that demand specialized thermal dissipation pathways for hidden-deck installations. EU Green Deal implementation tightens scrutiny on aluminum sourcing and anodizing processes. Adriatic and Ligurian marinas are retrofitting shore-power infrastructure to support battery-dependent auxiliary power architectures for low-draw lighting systems.
Australia
Queensland and Western Australia fishing fleets require IP67-rated fixtures with documented photometric testing for commercial certification under Australian Maritime Safety Authority protocols. Solar-integrated spreads gain traction in charter operations across the Whitsundays and Great Barrier Reef where reduced generator runtime carries operational value. Sydney and Melbourne marine distributors are consolidating procurement toward direct OEM specification relationships for projects above fifty-unit annual volumes.
Marine Spreader Lights Market Vendor Landscape
Concentration sits with integrated manufacturers possessing in-house semiconductor sourcing capabilities and regional production footprints that control margin exposure across volatile raw material cycles. The vendor base separates into three strategic archetypes: vertically integrated optical engine producers, assembly-focused fixture specialists, and marine distributor intermediaries facing channel compression. Dominant competitive moves include backward integration into LED driver IC procurement and geographic expansion through captive production facilities in coastal manufacturing clusters.
Among North American specialists, Lumitec LLC anchors the recreational retrofit segment through Florida-based production. Hella Marine exemplifies the integrated archetype with European yacht OEM channel control. Aqualuma LED Lighting occupies a position within the thermal engineering specialist tier. These three represent distinct competitive positioning vectors: regional manufacturing scale, upstream component control, and application-specific engineering depth.
| Leading Market Players |
|---|
| Lumitec LLC |
| Hella Marine |
| Perko Inc. |
| Aqualuma LED Lighting |
| OceanLED Marine Ltd. |
| Lumishore |
| TACO Marine |
| Rigid Industries |
| Shadow-Caster Marine LEDs |
| Others |
Supply Flow & Price Mechanics
IMO SOLAS photometric certification requirements gate both supplier qualification and price differentiation simultaneously, compressing margin structures for uncertified assemblers while enabling premium capture by validated OEMs. The interplay between compliance burden and material traceability elevates R&D amortization into fixture pricing, with certified suppliers commanding configured-to-order premiums over standard catalog offerings.
Pricing Analysis
Configured-to-order pricing for SOLAS-certified fixtures commands a substantial premium over standard recreational-grade catalog offerings. Price differentiation rests on certification tier and thermal engineering sophistication, with IMO-validated products separating from ABYC-compliant tiers and uncertified economy alternatives. Pricing pressure stems from aluminum LME volatility compressing housing margins for mid-tier assemblers. Charter fleet operators exhibit the highest price sensitivity due to volume procurement cycles, while superyacht builders prioritize performance over unit cost.
Supply Chain Analysis
China and Taiwan anchor LED driver IC fabrication and chip-on-board packaging for marine optical engines. The supply chain draws from East Asian semiconductor foundries, Yangtze River Delta aluminum extrusion facilities, and German gasket material specialists. Single-source vulnerability concentrates in high-lumen LED junction temperature management components. Distribution runs through marine distributor intermediaries for sub-fifty-unit volumes, with direct OEM specification displacing traditional channels above that threshold.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine spreader lights represent a service-attach opportunity where extended warranty and captive spare parts inventory expand faster than hardware revenue as boatbuilders consolidate vendor panels.
For Market Incumbents: Consolidate position through backward integration into LED driver IC procurement and captive thermal engineering talent pools. Hella Marine's European yacht OEM channel control demonstrates how upstream component command defends margin against East Asian price competition. Capacity addition in Florida production clusters captures North American recreational retrofit demand. For New Entrants and Emerging Players: Aftermarket retrofit technical support gaps where incumbents under-serve legacy DC system integration create white-space entry points. Target Gulf Coast and Great Lakes fishing trawlers facing EPA vessel discharge scrutiny with certified coating documentation services. Penetrate through marine electrical installer certification programs that reduce distributor dependence. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed assembly-focused fixture specialists lacking semiconductor sourcing depth. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Acquisition targets should demonstrate IMO SOLAS laboratory relationships and photometric testing capacity. The signal to watch is state-level blue-light emission restriction adoption accelerating tunable-CCT fixture specification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Driver IC Procurement | Hella Marine's captive semiconductor sourcing sustains margin control across European yacht OEM channels. |
| Florida Production Cluster Expansion | Lumitec LLC's regional manufacturing footprint dominates North American recreational boat retrofit demand. |
| Thermal Engineering Specialist Acquisition | Aqualuma LED Lighting's high-lumen junction temperature expertise addresses superyacht hidden-deck installation requirements. |
| Direct OEM Specification Relationship Development | Boatbuilder procurement consolidation above fifty-unit volumes displaces traditional marine distributor intermediaries. |
| Solar-Integrated Product Line Launch | Caribbean and Southeast Asian charter fleet demand for auxiliary power-independent lighting architectures accelerates specification. |
Methodological Framework
Operator-level perspectives from marine electrical installers, yacht procurement officers, commercial vessel safety managers, and LED component sourcing directors anchored the qualitative base. Primary interview insights combined with secondary validation from USCG navigation light regulations, ABYC electrical standards documentation, IMO SOLAS convention updates, and customs trade data for marine lighting components. Bottom-up fixture shipment analysis and top-down vessel fleet penetration estimates provided triangulation across the analysis window.
Sensitivity analysis examined aluminum price volatility scenarios and semiconductor lead time disruption impacts across the projection horizon. Segmentation dimensions modeled include product type, installation configuration, application category, power source architecture, and regional regulatory cluster. CAGRs derived from vessel fleet growth projections, retrofit replacement cycle compression, and energy efficiency mandate adoption curves. Photometric testing laboratory capacity constraints and thermal engineering talent scarcity served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in IMO SOLAS conventions, USCG navigation light regulations, and ABYC electrical standards; material policy shifts would require re-modeling. Specific risks include EPA vessel discharge guideline expansion, state-level blue-light emission restriction proliferation, and East Asian semiconductor export control escalation. Recalibration cycles align with material shifts in vessel electrification adoption and marina infrastructure investment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Big Data Market
Marine
Sea Scooter Market
Marine
Marine Fuel Injector Market
Marine
Marine Auxiliary Engine Market
Marine
Global Foldable Inflatable Boats Market
Marine
Steel Ship Plate Market
Marine
Trim Tabs Market
Marine
Marine Fin Stabilizer Market
Marine
Boat Trolling Motor Market
Marine
Marine Salvage Services Market
Marine
Marine Beacon Market
Marine
North America Naval Vessels Market
Marine
Ballast Water Management Market
Marine
Marine Stabilizers Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Fender Systems Market