
 Sailboat Propellers Market | 2026-2036
Sailboat Propellers Market Size, Share, and Industry Trends Forecast 2026-2036
Sailboat Propellers Market Analysis
Capability gaps in in-house casting and CNC finishing is unwinding competitive parity among marine drivetrain specialists. Volvo Penta leverages its Scandinavian foundry network to control bronze alloy formulations for folding propeller lines. Mercury Marine anchors its position through vertical integration into stainless steel forging operations in Wisconsin. Brunswick Corporation competes via brand architecture that channels sailboat owners through multiple retail tiers.
A sailboat propeller is a hydrodynamic device with typically two to five blades, manufactured from bronze alloys, stainless steel, or fiber-reinforced composites, that converts engine torque into thrust through controlled rotational motion in water. Its primary commercial purpose is to optimize vessel propulsion efficiency across varying points of sail while minimizing drag when engines idle. Stainless steel propellers command premium positioning in the Type dimension due to durability demands from bluewater cruising segments. Folding configurations capture the fastest growth trajectory as racing rules and marina fees reward reduced underwater appendage drag. Bronze retains volume leadership in the Material category through proven galvanic compatibility with traditional shaft assemblies.
ISO 484/2 governs propeller geometry tolerances while ABYC standards address shaft alignment and vibration thresholds for inboard installations in US waters. The EU Recreational Craft Directive mandates exhaust emission thresholds that indirectly constrain propeller matching to compliant auxiliary engines. Stakeholders must monitor evolving efficiency regulations from the International Maritime Organization as they cascade into auxiliary propulsion requirements for larger sailing yachts.
Market Dynamics
ISO 484/2 tolerance tightening is forcing foundries to retool dimensional measurement protocols, while Mediterranean racing fleets demand folding propellers that slash drag penalties. This dual pressure compresses margins for casting specialists lacking CNC finishing capability.
Growth Catalysts
- EU Recreational Craft Directive:Emission thresholds for auxiliary engines are tightening propeller-engine matching requirements across French and Italian charter fleets.
- Fiber-reinforced composites:Advanced polymer formulations are displacing traditional alloys in high-performance racing applications where weight reduction governs handicap ratings.
- Marina fee structures:Annual berthing costs tied to underwater appendage drag are accelerating folding propeller retrofit cycles in competitive sailing hubs.
Market Restraints
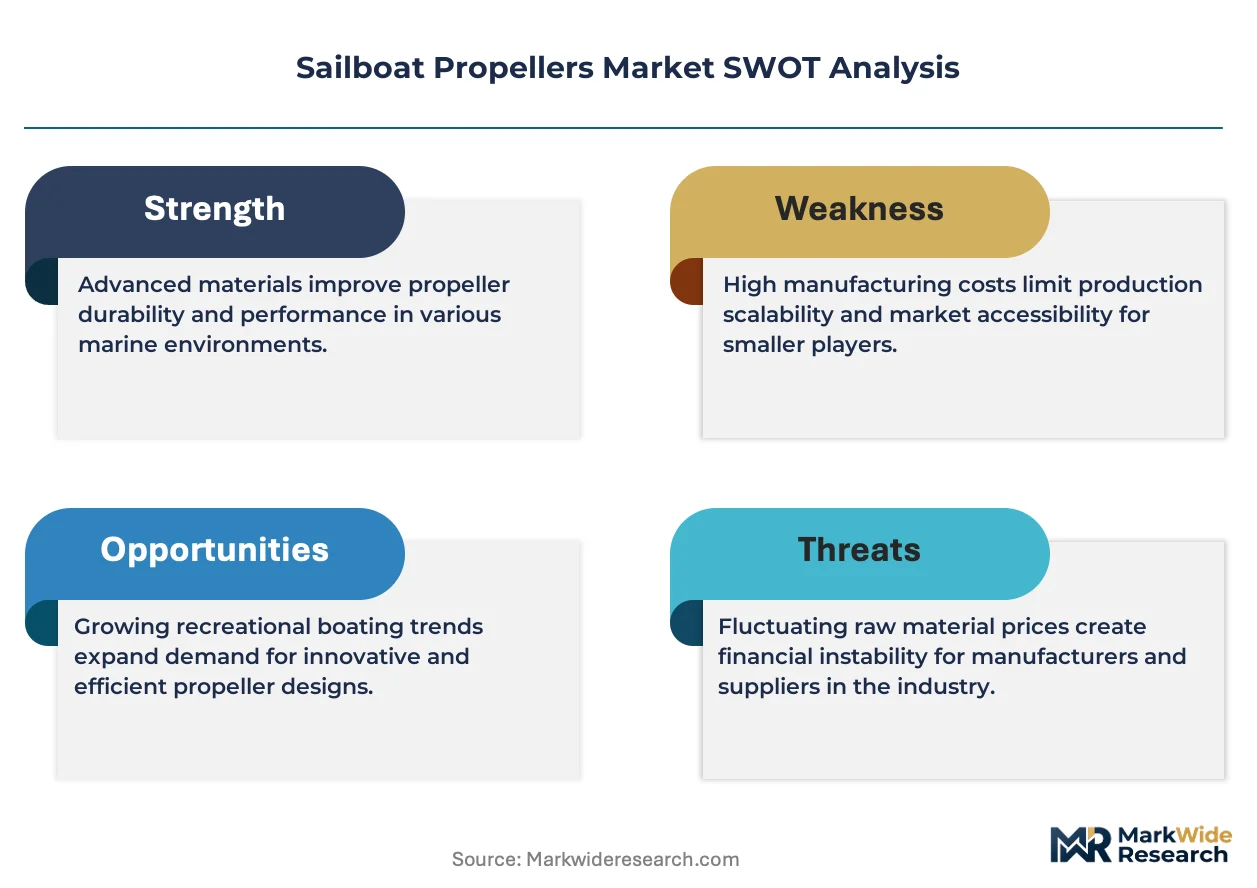
- Bronze alloy volatility:Copper and tin price swings from Chilean and Indonesian concentrate markets destabilize raw material procurement for traditional foundries.
- Scandinavian supply concentration:Premium stainless steel forging capacity clusters in Nordic mill networks, creating single-source vulnerability for bluewater cruising segments.
- Galvanic incompatibility:Composite shaft systems from carbon fiber manufacturers create electrolysis risks that limit bronze propeller pairings in modern drivetrain retrofits.
Strategic Opportunities
- Croatian charter expansion:Adriatic marina infrastructure investment is creating demand for standardized folding propeller fleets serving bareboat tourism.
- ISO 484/2 certification services:Third-party metrology laboratories can capture value from small foundries lacking in-house coordinate measurement machines.
- Digital twin integration:Computational fluid dynamics software paired with additive manufacturing is enabling custom blade geometry for superyacht auxiliary systems.
Industry Challenges
- Five-axis CNC programming:Complex blade surface machining requires specialized CAM expertise that marine foundries struggle to recruit from aerospace talent pools.
- ABYC vibration certification:Extended test cycles for inboard shaft alignment compliance delay product launches for US-market propeller lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sailboat Propellers Market |
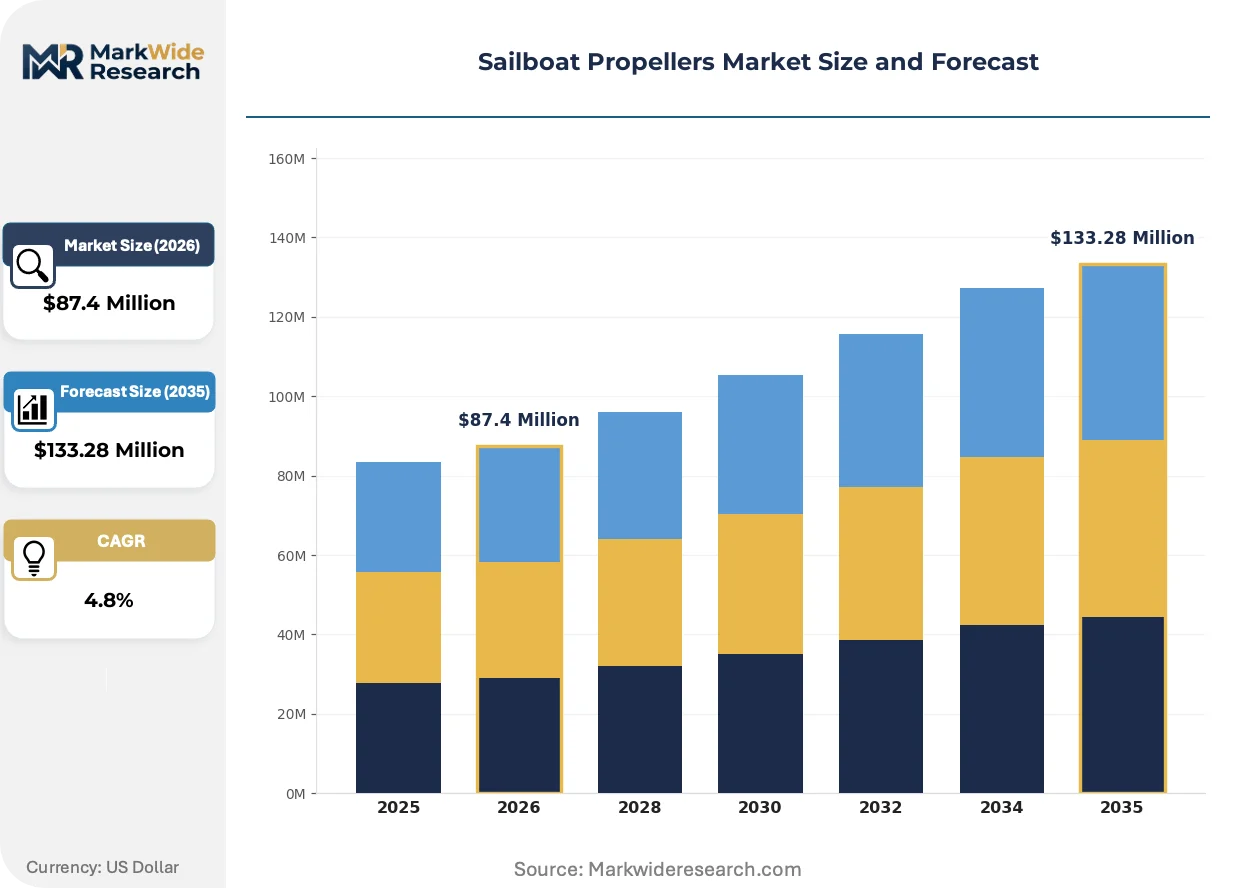
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $133.28 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Stainless Steel, Composite, Bronze Type: Fixed, Folding, Feathering, Variable Pitch Size: Small, Medium, Large, Extra Large Installation: Through-Hull, Outboard, Inboard, Shaft Drive |
| Companies Covered | Volvo Penta, Yamaha Motor, Mercury Marine, Wärtsilä Corporation, MAN Energy Solutions, Rolls-Royce Holdings, Brunswick Corporation, Caterpillar Inc., Hyundai Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sailboat Propellers Market Emerging Trajectories
Propulsion efficiency optimization is fragmenting along material and configuration axes. Racing rulebooks and environmental compliance are jointly rewiring procurement priorities across Mediterranean and Adriatic sailing corridors.
Additive manufacturing of nickel-aluminum-bronze propellers is decomposing traditional sand-casting batch economics. Superyacht refit yards in Palma and Antibes are adopting topology-optimized designs that reduce cavitation erosion. This technology is decomposing the minimum order quantities that historically protected mid-volume foundries from custom competition.
REACH substance restrictions on heavy metals in marine coatings are redirecting surface treatment investments toward plasma electrolytic oxidation. German propeller specialists must reformulate traditional chromium plating workflows. The racing segment faces compressed compliance timelines as EU harbor authorities begin appendage inspections for coating toxicity.
Charter fleet procurement is consolidating through Mediterranean marina management companies that specify standardized folding propeller configurations across multi-vessel contracts. Greek island operators now mandate uniform underwater profiles to simplify maintenance logistics. This pattern is most visible in Cyclades and Ionian charter hubs where fleet turnover exceeds private ownership cycles.
Sailboat Propellers Market Segmentation
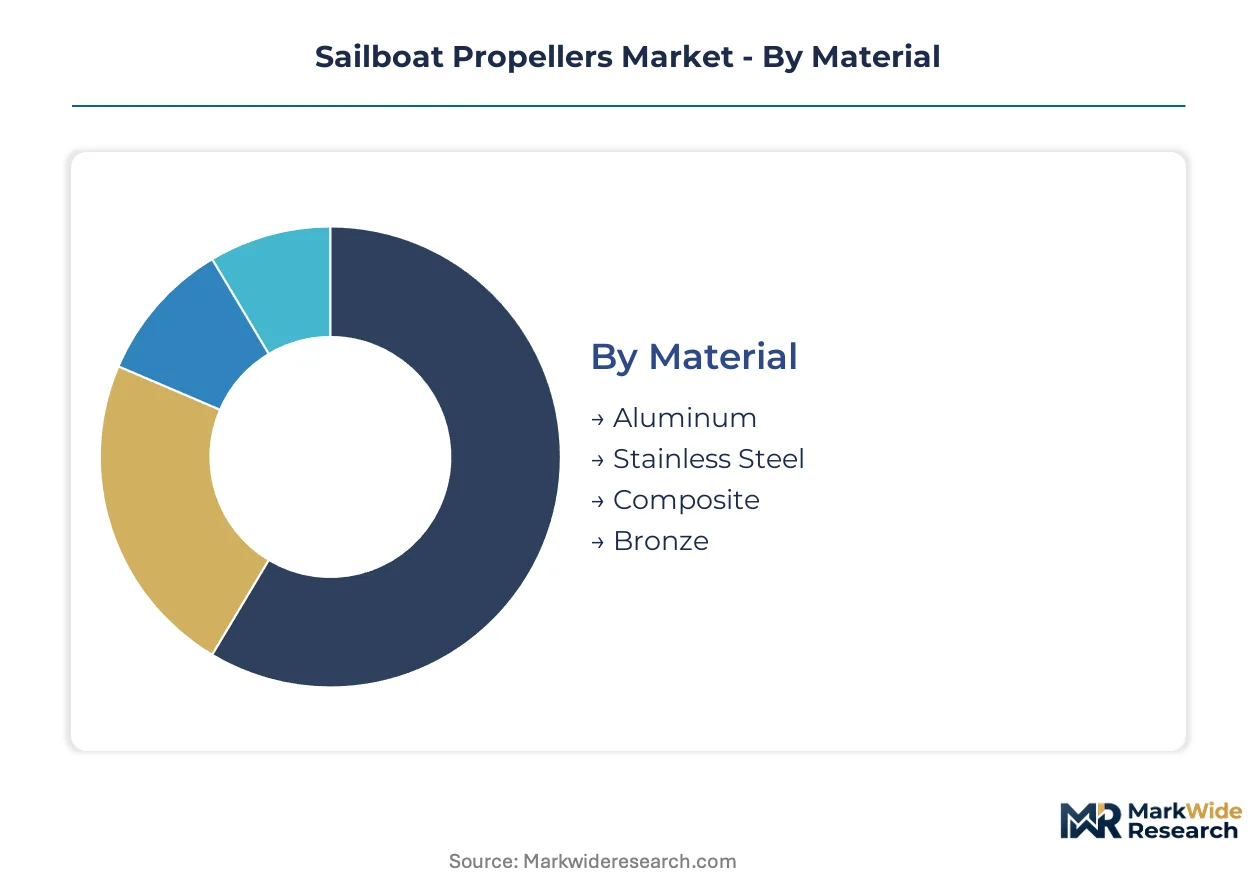
Propeller procurement decisions in sailing fleets fragment sharply across hull configuration, auxiliary engine matching, and underwater appendage drag requirements. Segmentation clarity exposes where composite materials displace traditional alloys and where folding mechanisms command retrofit premiums.
Material:
Composite formulations exert the strongest substitution pressure on legacy bronze foundries as weight-critical racing fleets rewrite procurement specifications.
- Bronze:Nickel-aluminum-bronze alloys dominate traditional shaft assemblies through proven galvanic compatibility with stainless steel hardware. Mediterranean charter operators in French and Italian ports specify bronze for maintenance simplicity across mixed-metal drivetrains.
- Stainless Steel:Martensitic and duplex grades anchor bluewater cruising segments where cavitation erosion resistance governs propeller longevity. Scandinavian mill networks supply forging stock to Palma and Antibes refit yards serving circumnavigation fleets.
- Composite:Carbon-fiber-reinforced polymers reduce rotating mass for handicap-optimized racing yachts.
- Aluminum:Cast alloys serve cost-sensitive coastal day-sailors with limited auxiliary engine hours.
Bronze anchors the volume base while composite gains share at the steepest rate.
Type:
Cost tier stratification separates premium folding mechanisms from commodity fixed-blade installations across bareboat charter and private ownership segments.
- Folding:Twin-blade and three-blade designs pivot to reduce underwater drag when engines idle. Adriatic marina fee structures tied to appendage cross-section accelerate retrofit demand from Croatian charter fleets.
- Fixed:Solid castings with fixed pitch angles dominate entry-level production sailboats. Greek Cyclades operators specify fixed configurations for maintenance simplicity across high-turnover bareboat fleets.
- Feathering:Self-pitching blades optimize thrust across motoring speed ranges for long-distance cruisers.
- Variable Pitch:Hydraulically actuated systems serve superyacht auxiliary installations requiring precise thrust modulation.
Fixed configurations retain the broadest installed base while folding mechanisms climb the fastest among new installations.
Size:
Application scale drives dimensional requirements from auxiliary outboards on trailer-sailers to primary propulsion on motorsailers exceeding displacement thresholds.
- Medium:Diameters between 12 and 18 inches match auxiliary engines on production cruising sailboats from 30 to 45 feet. French Riviera charter fleets standardize medium folding propellers across Beneteau and Jeanneau bareboat inventories.
- Large:18- to 24-inch diameters serve bluewater cruisers and light commercial sailing vessels. Italian Adriatic operators specify large bronze fixed propellers for heavy-displacement motorsailers in Ionian charter service.
- Small:Compact diameters suit trailerable day-sailors with minimal auxiliary requirements.
- Extra Large:Custom diameters address superyacht auxiliary systems and specialized racing maxi yachts.
Medium sizes concentrate production volume while large configurations expand most quickly with bluewater cruising fleet growth.
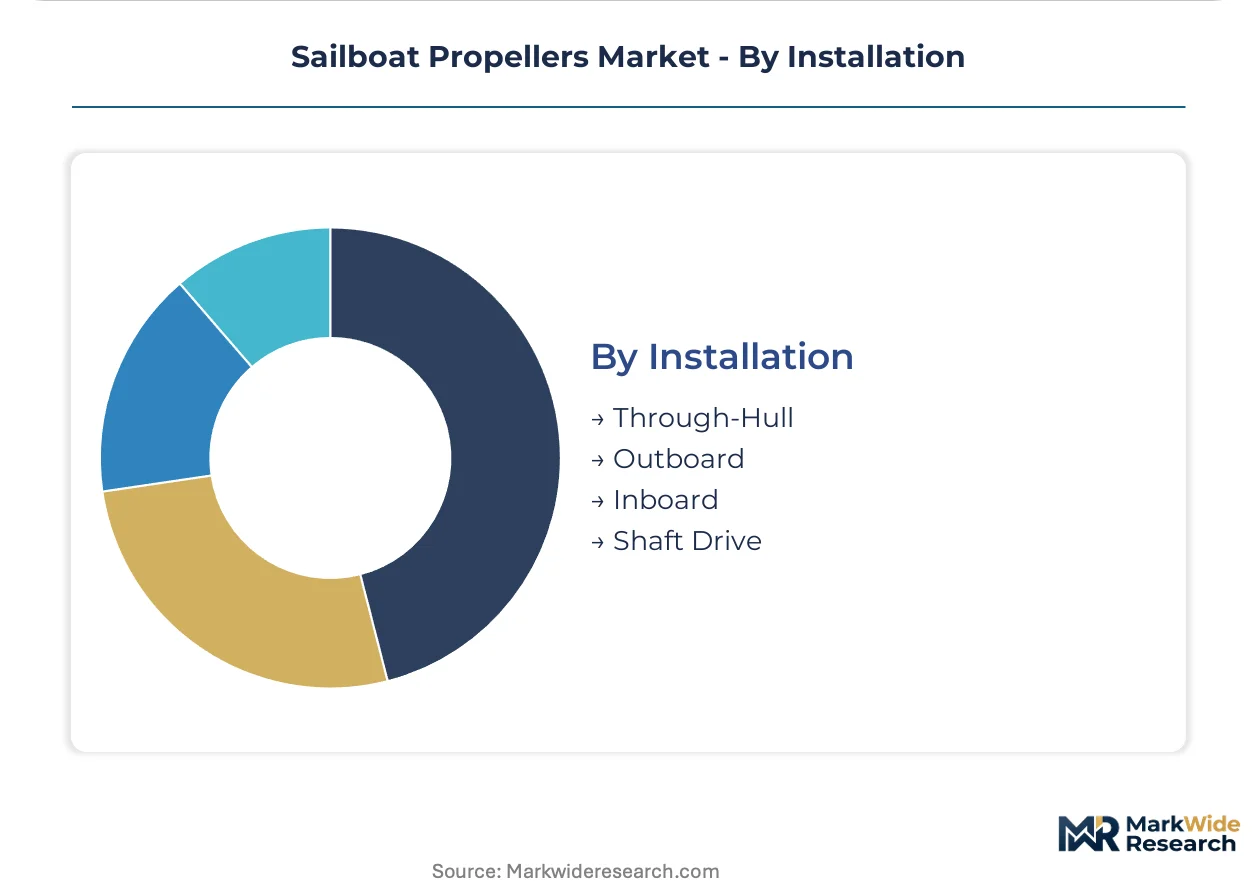
Installation:
Supply concentration in shaft drive manufacturing creates margin pressure for through-hull and outboard specialists lacking in-house drivetrain integration.
- Shaft Drive:Conventional inboard installations with bronze or stainless shafts dominate production sailboat architecture. Wisconsin forging operations and Scandinavian foundries supply integrated propeller-shaft packages to US and European boatbuilders.
- Inboard:Saildrive leg configurations from Volvo Penta and Yanmar require proprietary propeller mounting interfaces. Mediterranean service networks stock folding propeller inventories matched to specific saildrive geometries.
- Through-Hull:Pod-mounted electric drives on emerging electric auxiliary systems demand specialized propeller clearances.
- Outboard:Clamp-on auxiliary engines on smaller cruising sailboats use standardized small-diameter propellers.
Shaft drive retains the deepest installed base while inboard saildrive configurations gain traction fastest among new European production builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across sailing corridors. Adriatic charter operators in Croatia prioritize standardized folding configurations to minimize fleet maintenance costs, while bluewater circumnavigators in French and Italian ports absorb premium stainless steel pricing for durability.
France
Mediterranean charter demand from Marseille to Nice drives folding propeller retrofit cycles among bareboat fleets. The EU Recreational Craft Directive enforces auxiliary engine emission thresholds that tighten propeller-engine matching specifications. Antibes and Cannes refit yards concentrate superyacht auxiliary system installations requiring custom geometry.
Italy
Ionian and Adriatic charter hubs specify large bronze fixed propellers for heavy-displacement motorsailers. REACH substance restrictions on heavy metals in marine coatings redirect surface treatment investments toward plasma electrolytic oxidation. Genoa and La Spezia foundries supply nickel-aluminum-bronze castings to mixed-metal drivetrain assemblers.
Croatia
Adriatic marina infrastructure investment creates standardized folding propeller demand for bareboat tourism expansion. National harbor authorities align with EU harbor inspection protocols for underwater appendage coating toxicity. Split and Dubrovnik charter operators mandate uniform underwater profiles across multi-vessel maintenance contracts.
United States
Bluewater cruising segments from Florida to the Pacific Northwest absorb premium stainless steel pricing for cavitation erosion resistance. ABYC standards govern shaft alignment and vibration thresholds for inboard installations. Wisconsin forging operations supply martensitic and duplex grade stock to circumnavigation fleet service networks.
Sweden
Scandinavian mill networks concentrate premium stainless steel forging capacity serving bluewater segments. ISO 484/2 tolerance tightening forces foundry retooling of dimensional measurement protocols. Gothenburg and Stockholm marine drivetrain specialists leverage captive foundry networks to control bronze alloy formulations.
Sailboat Propellers Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the sailboat propellers market. Scandinavian and German specialists anchor premium tiers through metallurgical control and CNC finishing capability, while Asian fabricators compete on volume production of standardized castings. The competitive terrain separates into three archetypes: vertically integrated marine drivetrain specialists, component-focused foundries, and diversified industrial conglomerates with marine divisions. Dominant competitive moves include backward integration into captive alloy supply and geographic expansion through Mediterranean service network acquisitions.
Among diversified industrial conglomerates, Wärtsilä Corporation and MAN Energy Solutions occupy positions spanning auxiliary propulsion systems for larger sailing yachts. Volvo Penta anchors the vertically integrated specialist tier through Scandinavian foundry network control. Brunswick Corporation exemplifies brand architecture strategies that channel sailboat owners through multiple retail tiers without direct manufacturing exposure.
| Leading Market Players |
|---|
| Volvo Penta |
| Yamaha Motor |
| Mercury Marine |
| Wärtsilä Corporation |
| MAN Energy Solutions |
| Rolls-Royce Holdings |
| Brunswick Corporation |
| Caterpillar Inc. |
| Hyundai Heavy Industries |
| Others |
Supply Flow & Price Mechanics
Scandinavian stainless steel forging capacity operates at tight utilization rates, concentrating metallurgical control among Nordic mill networks and establishing price floors that propagate through bluewater cruising supply chains. This scale concentration compresses margin flexibility for mid-volume foundries lacking captive alloy supply or in-house CNC finishing capability.
Pricing Analysis
After-sales service revenue from propeller refurbishment and blade reconditioning drives lifetime value capture for marine drivetrain specialists. Three-tier pricing structure across premium, standard, and economy levels segments the market: ISO 484/2-certified custom geometries command top positioning, Mediterranean charter fleet contracts anchor mid-tier volume, and standardized castings serve cost-sensitive coastal operators. Pricing pressure stems from composite material substitution in racing segments eroding traditional bronze premiums. Charter fleet procurement managers exhibit highest price sensitivity through multi-vessel tender processes, while circumnavigation owners absorb stainless steel premiums for cavitation durability.
Supply Chain Analysis
Sweden and Finland anchor premium stainless steel forging capacity for bluewater propulsion systems, while Italy and Germany concentrate nickel-aluminum-bronze foundry operations serving Mediterranean mixed-metal drivetrains. Raw material procurement draws from Chilean copper concentrate, Indonesian tin, and Nordic chromium-molybdenum alloys. Single-source vulnerability concentrates in Scandinavian mill networks supplying martensitic grades. Distribution runs through refit yards in Palma, Antibes, and Gothenburg, with charter fleet procurement consolidating through marina management companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Propeller aftermarket services expand faster than hardware sales as folding mechanism maintenance and ISO 484/2 recertification cycles generate recurring revenue. This service-attach opportunity restructures competitive economics toward installed-base capture.
For Market Incumbents: Consolidate Mediterranean service network coverage through targeted acquisitions of Croatian and Greek refit operations. Secure captive supply of nickel-aluminum-bronze alloys through backward integration into Scandinavian foundry partnerships. Composite shaft system proliferation threatens traditional bronze pairings; counter through certification investment in galvanic-isolation interfaces for modern drivetrain retrofits. For New Entrants and Emerging Players: Lead with digital twin-enabled custom geometry services for superyacht auxiliary systems, exploiting topology-optimized additive manufacturing white space. Croatian charter expansion offers the most penetrable geography, with Adriatic marina infrastructure investment creating standardized fleet demand. Target ISO 484/2 third-party metrology certification services for small foundries lacking coordinate measurement capability. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated marine drivetrain specialists with captive foundry networks and established Mediterranean service footprints. Long-term viability favors acquisition targets controlling both alloy formulation intellectual property and CNC finishing capability. Watch composite propeller adoption rates in handicap-optimized racing fleets as inflection indicator for traditional foundry displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Acquisition | Backward integration into Scandinavian bronze alloy supply secures margin control against copper price volatility. |
| ISO 484/2 Certification Investment | Third-party metrology capability captures value from small foundries lacking dimensional measurement infrastructure. |
| Composite Propeller Development | Carbon-fiber-reinforced polymer formulations address weight-critical racing fleet procurement specifications. |
| Mediterranean Service Network Expansion | Adriatic and Ionian charter hub coverage locks in standardized fleet maintenance contracts. |
| Digital Twin Integration | Computational fluid dynamics software paired with additive manufacturing enables custom superyacht auxiliary geometries. |
Methodological Framework
Operator-level perspectives from marine drivetrain engineering directors, refit yard procurement managers, charter fleet operations heads, and foundry technical directors anchored the qualitative base. Primary interview insights combined with secondary validation from EU Recreational Craft Directive filings, ISO 484/2 certification registries, Scandinavian mill network capacity disclosures, and Mediterranean marina infrastructure investment records. Bottom-up vessel fleet analysis and top-down marine equipment trade data triangulated market sizing.
Sensitivity analysis tested forecast robustness across composite substitution scenarios, copper price volatility bands, and charter fleet growth assumptions. Segmentation modeling spanned material grade, propeller configuration type, vessel size tier, and installation architecture across the projection horizon. CAGRs derived from regression analysis against auxiliary engine installation rates and racing fleet retrofit cycles. Forecast inputs incorporated REACH substance restriction compliance timelines and Adriatic marina fee structure evolution.
Forecasts assume regulatory continuity in EU Recreational Craft Directive emission thresholds and ISO 484/2 tolerance standards; material policy shifts would require re-modeling. Specific risks include accelerated composite material adoption in racing segments, Scandinavian mill network supply disruption, and galvanic incompatibility constraints from carbon fiber shaft proliferation. Recalibration cycles align with material shifts in charter fleet procurement consolidation patterns and additive manufacturing cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Exhaust Systems Market
Marine
Integrated Bridge System for Ships Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Salvage Services Market
Marine
Military Marine Engine Market
Marine
Electric Outboard Engines Market
Marine
Azimuth Thrusters Market
Marine
Boat Hook Market
Marine
Passenger Vessel Propeller Market
Marine
Autonomous Ships Market
Marine
US Fish Finders Market
Marine
GCC ROV Market
Marine
Marine Bearings Market
Marine
Yacht Shell Doors Market
Marine
Ship/Boat Keel Market
Marine
Sea Scooter Market