
 Marine LED Lights Market | 2026-2036
Marine LED Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Marine LED Lights Market Analytics
Modular fixture bundling with integrated control systems is hardening as the dominant procurement pattern for commercial fleets. Lumitec leverages its Florida manufacturing base to sustain rapid-turn custom configurations for sportfishing vessels. Hella anchors European OEM supply through dedicated marine divisions in Germany and Denmark. OceanLED competes on underwater luminaire specialization, dominating superyacht aesthetic lighting specifications in Mediterranean refit yards.
Marine LED lights are solid-state electroluminescent fixtures engineered with sealed IP67-plus housings, corrosion-resistant aluminum or polymer substrates, and color temperatures ranging from warm white to RGB spectrum control, designed to withstand salt spray, vibration, and voltage fluctuation aboard seagoing vessels. The primary purpose is to replace legacy incandescent and halogen marine lighting with energy-efficient, long-lifespan illumination for navigation safety, deck operations, and vessel aesthetics. Underwater product types command premium positioning due to pressure-rated sealing complexity and superyacht demand for hull-mounted aesthetic arrays. Navigation applications remain structurally mature with stable replacement cycles tied to regulatory compliance intervals. Hardwired installations occupy the dominant share in commercial operator fleets where permanent integration with vessel electrical systems reduces failure points.
The International Maritime Organization (IMO) COLREGs and US Coast Guard navigation light standards shape product certification requirements, while EU REACH and RoHS directives restrict hazardous substances in fixture substrates and electronics. The US FDA maintains indirect relevance through marine aquaculture lighting applications requiring biose-safe material contact ratings. Stakeholders must monitor phosphor substrate supply concentration and evolving IMO efficiency mandates to calibrate R&D allocation and regional certification sequencing.
Market Dynamics
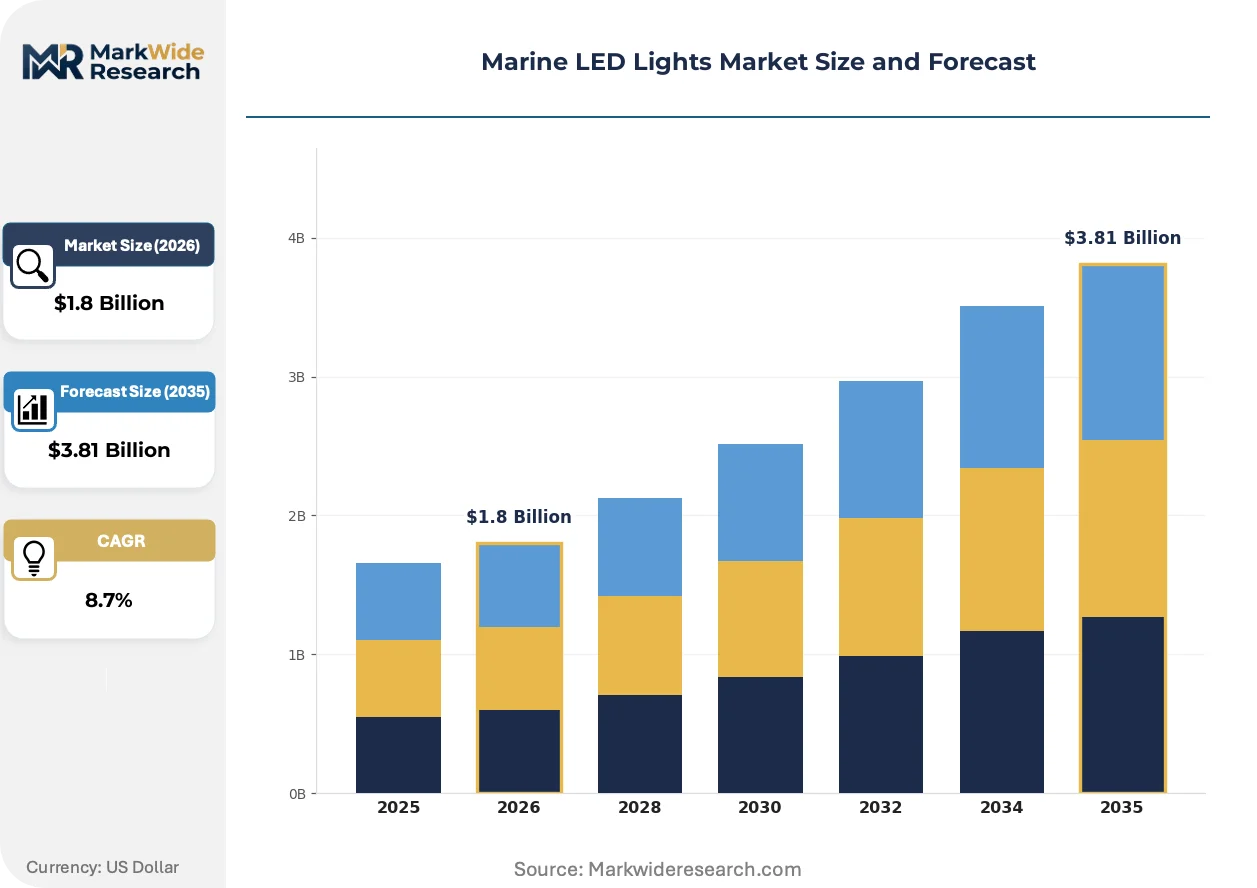
Commercial fleet retrofit cycles and superyacht aesthetic specifications are tightening procurement requirements around modular fixture-control bundling, compressing supplier margins while elevating certification barriers for smaller manufacturers.
Growth Catalysts
- IMO COLREGs compliance intervals:Mandatory navigation light replacement cycles generate predictable demand from commercial operators seeking certified LED retrofits.
- Italian superyacht build centers:Hull-mounted underwater aesthetic arrays command premium positioning as owners specify RGB spectrum control for Mediterranean charter visibility.
- Solid-state phosphor advances:Improved lumen maintenance and thermal management extend fixture lifespan in salt-spray environments, reducing total cost of ownership for offshore vessel operators.
Market Restraints
- Phosphor substrate supply concentration:Rare-earth phosphor processing capacity clusters in limited geographies, exposing fixture manufacturers to input volatility.
- EU REACH substance restrictions:Hazardous material limits in aluminum substrates and electronics complicate supply chain qualification for European OEM contracts.
- Incumbent halogen infrastructure:Legacy socket standards and crew familiarity slow replacement velocity in cost-sensitive commercial fishing fleets.
Strategic Opportunities
- Norwegian offshore vessel yards:North Sea oil services demand for explosion-rated LED fixtures exceeds qualified supplier capacity.
- Aquaculture lighting biosecurity ratings:US FDA marine aquaculture contact-safe material specifications open specialized product lines for fish farm operators.
- Integrated control system convergence:Fixture manufacturers bundling DMX-protocol lighting with vessel automation systems capture higher contract values.
Industry Challenges
- IP67-plus sealing certification timelines:Pressure-rated underwater luminaire validation extends product development cycles beyond commercial fleet bidding windows.
- Electrical systems integration complexity:Hardwired marine installations require specialized marine electrician labor pools concentrated in Mediterranean and North Sea port cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine LED Lights Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Underwater, Deck Lights, Navigation, Interior Lighting Application: Boating, Fishing, Aquatic Shows, Recreational Installation: Hardwired, Plug-and-Play, Surface Mounted, Portable End User: Boat Owners, Commercial Operators, Event Planners, Aquarists |
| Companies Covered | Lumitec, Hella, OceanLED, Lumishore, OSRAM Licht AG, Signify, KOITO MANUFACTURING CO., LTD., Aqualuma LED Lighting, Aqua Signal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine LED Lights Market Evolving Landscape
Product development trajectories center on thermal management advances, regulatory efficiency mandates, and procurement model consolidation across commercial operator fleets.
Chip-on-board LED arrays with ceramic substrates are absorbing thermal loads previously requiring active cooling, enabling slimmer fixture profiles. Superyacht builders in Italian and Dutch yards specify these packages for concealed cove lighting. The technology is absorbing market share from discrete LED modules in premium navigation and aesthetic applications.
EU RoHS hazardous substance directives are tightening allowable thresholds in fixture housings and driver electronics. Manufacturers serving European OEM supply chains must reformulate aluminum alloys and conformal coatings. Underwater luminaire suppliers face the steepest compliance costs given sealing compound material restrictions.
Fleet operators now bundle fixture procurement with integrated control system contracts, displacing standalone lighting purchases. Large Mediterranean yacht management companies and Norwegian offshore contractors consolidate supplier relationships through multi-vessel framework agreements. This concentration is most visible in refit yards where single-source accountability reduces project coordination overhead.
Marine LED Lights Market Segmentation
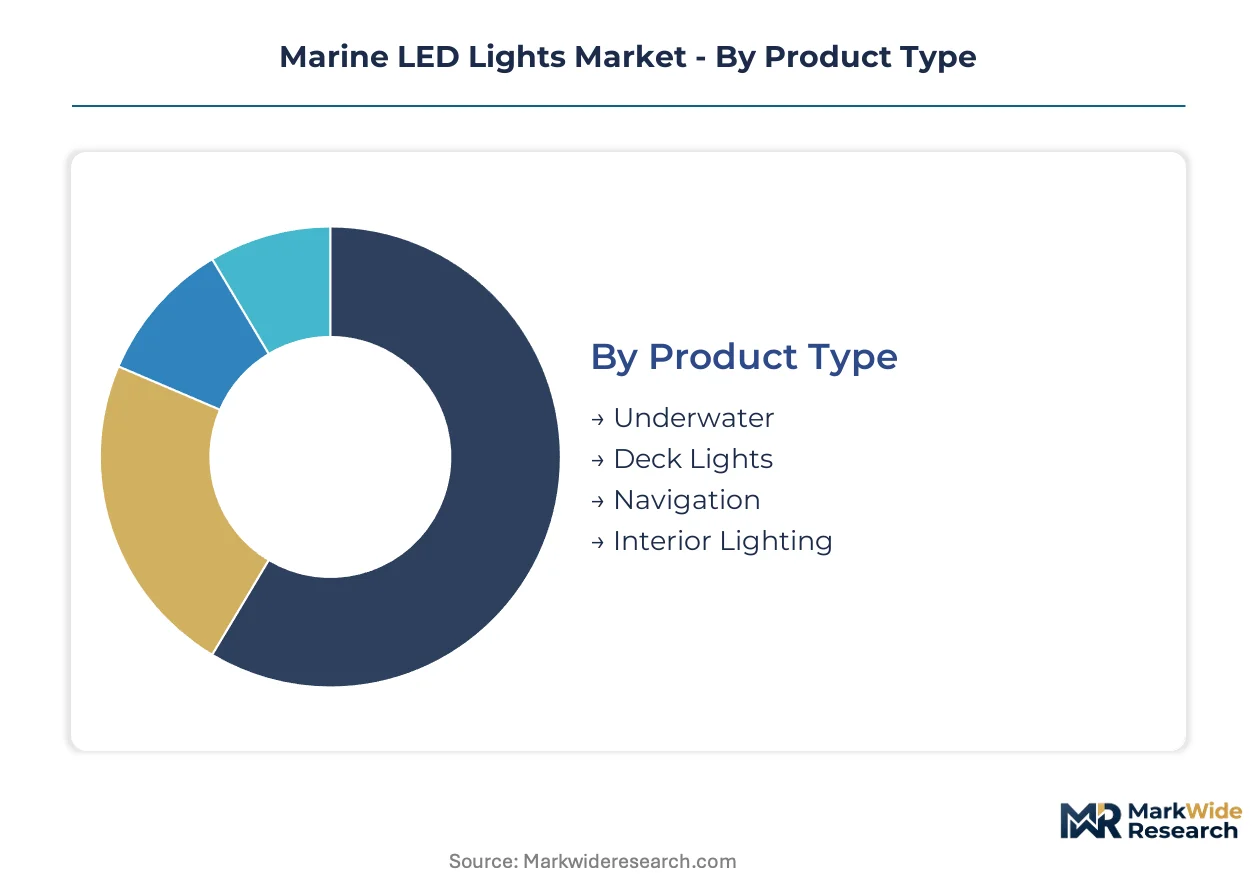
Segmentation in marine LED lighting exposes how technical specifications, installation constraints, and end-use economics create divergent procurement patterns across vessel types. Suppliers must align product architectures with distinct certification burdens and replacement cycles.
Product Type:
Technical specifications around sealing ratings, pressure tolerance, and thermal management define competitive positioning across fixture categories.
- Underwater:Pressure-rated IP68-plus housings with marine-grade aluminum or polymer substrates withstand hydrostatic loads at depth. Italian superyacht builders in Viareggio and Dutch yards in Amsterdam specify RGB spectrum arrays for hull-mounted aesthetic visibility in Mediterranean charter markets.
- Navigation:IMO COLREGs-certified fixtures with precise horizontal and vertical sector angles ensure collision avoidance compliance. Commercial fleets operating under US Coast Guard and EU harbor regulations replace these on mandatory intervals, generating stable aftermarket demand from container shipping operators.
- Deck Lights:Vibration-resistant enclosures with wide-angle optics illuminate working surfaces on offshore supply vessels. Norwegian North Sea operators prioritize explosion-rated variants for oil platform servicing.
- Interior Lighting:Low-profile chip-on-board arrays with ceramic substrates reduce thermal footprint in cabin retrofits. Warm white to tunable color temperature options dominate refit specifications for Mediterranean yacht management companies.
Navigation fixtures lead on scale through regulatory replacement cycles; underwater arrays lead on momentum through superyacht aesthetic specification.
Application:
End-use economics range from regulatory compliance mandates to discretionary aesthetic spending, reshaping supplier margin structures.
- Boating:Private vessel owners balance upfront fixture costs against fuel savings from reduced electrical load. Sportfishing operators in Florida and charter fleets in the Greek Islands drive demand for modular control-integrated systems.
- Fishing:Commercial fleets prioritize durability and crew safety over efficiency metrics. Icelandic and Alaskan longline operators resist LED retrofits due to legacy halogen infrastructure and harsh-environment reliability concerns.
- Aquatic Shows:Synchronized RGB fixtures with DMX protocol compatibility enable programmable underwater displays. Fixed installations in Las Vegas and Dubai fountain attractions require specialized biose-safe material ratings.
- Recreational:Marina-based leisure craft owners seek plug-and-play aesthetic upgrades. Mediterranean seasonal demand concentrates in Italian and Croatian coastal regions.
Boating applications anchor volume through fleet scale; aquatic shows command premium pricing through technical complexity.
Installation:
Integration depth with vessel electrical systems determines labor qualification requirements and failure-mode risk profiles.
- Hardwired:Permanent connection to DC distribution panels eliminates connector corrosion points. Commercial operators in Norwegian offshore yards mandate this architecture for explosion-rated zone compliance.
- Plug-and-Play:Standardized marine connectors enable owner-installed retrofit without electrician certification. Caribbean charter fleets favor these for seasonal equipment rotation.
- Surface Mounted:Low-profile brackets secure fixtures without through-hull penetration. Dutch superyacht builders specify these for interior cove lighting where concealed wiring paths are pre-engineered.
- Portable:Battery-powered or clamp-mounted units serve temporary deck operations. Alaskan crab fishing crews deploy these for emergency illumination when permanent systems fail.
Hardwired installations dominate commercial fleet procurement; plug-and-play configurations gain share fastest in recreational retrofit channels.
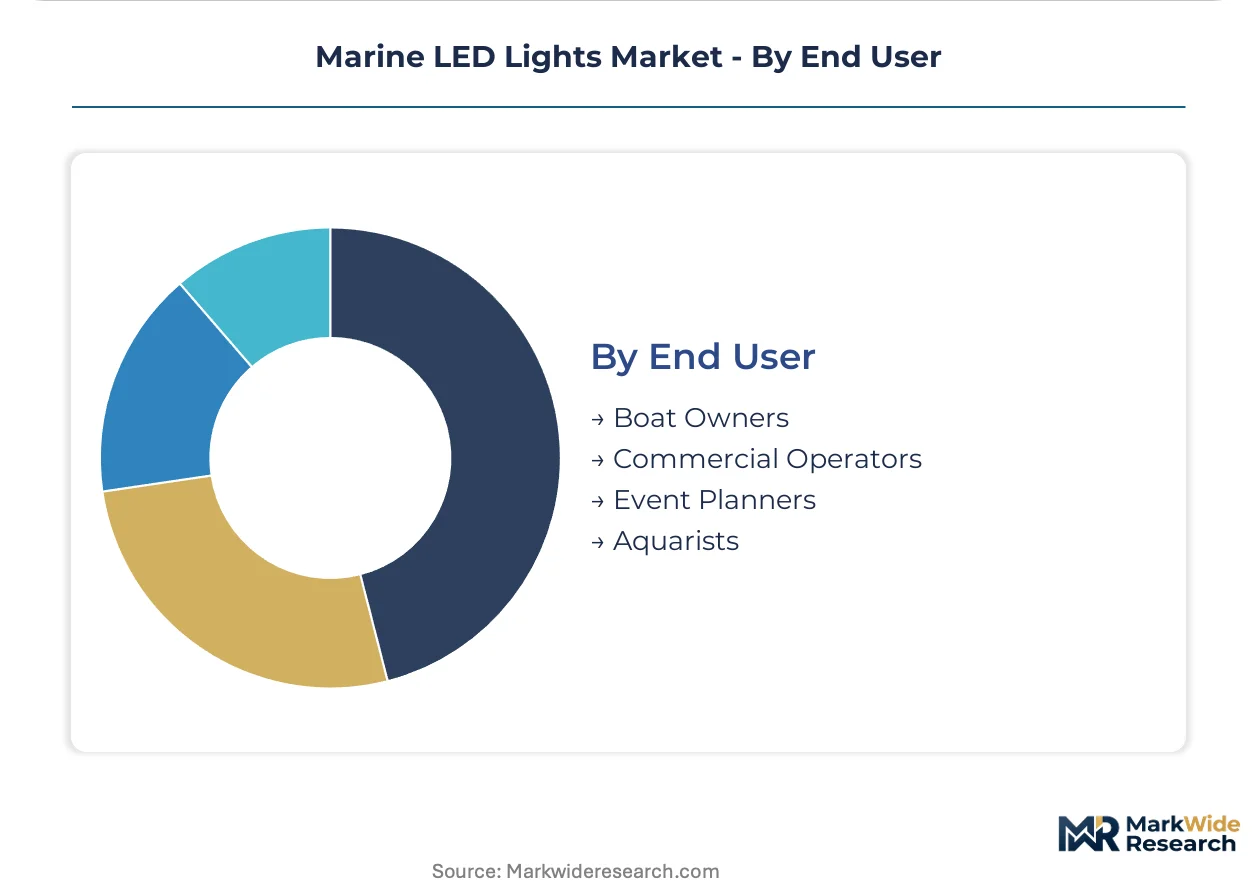
End User:
Procurement sophistication varies from individual purchase decisions to framework agreements consolidating multi-vessel specifications.
- Boat Owners:Individual purchasers prioritize aesthetic customization and installation simplicity. Mediterranean marina retailers stock RGB underwater arrays for weekend cruiser upgrades.
- Commercial Operators:Fleet managers negotiate multi-year supply contracts with certified maintenance provisions. Norwegian oil services contractors consolidate LED procurement through single-source framework agreements.
- Event Planners:Temporary installation specialists require rapid-deployment fixtures with synchronized control protocols. Dubai fountain show contractors source through specialized theatrical lighting distributors.
- Aquarists:Public aquarium and marine research facilities demand biose-safe material contact ratings. US FDA compliance distinguishes suppliers serving Monterey Bay and Georgia Aquarium installations.
Commercial operators concentrate procurement volume through fleet scale; aquarists represent the steepest expansion trajectory as public aquarium construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine LED lighting manufacturing originated in German and Danish industrial zones serving North Sea commercial fleets, then expanded through Italian superyacht craftsmanship and Florida sportfishing specialization. The current geographic footprint reflects this tripartite heritage.
United States
Florida's sportfishing vessel builders and Pacific Northwest commercial fishing fleets drive retrofit demand for corrosion-resistant fixtures. US Coast Guard navigation light standards mandate COLREGs-compliant certification for all commercial operators. Lumitec's Stuart, Florida manufacturing base supplies rapid-turn custom configurations to Caribbean charter fleets and Gulf Coast shrimp operators.
Germany
Hella's Lippstadt headquarters anchors European OEM supply through dedicated marine divisions serving commercial shipping lines. EU REACH substance restrictions and RoHS hazardous material limits tighten allowable thresholds in aluminum substrates and driver electronics. Hamburg and Bremerhaven port clusters concentrate refit yard activity for container shipping operators replacing navigation fixtures on mandatory compliance intervals.
Italy
Viareggio and La Spezia superyacht builders specify RGB spectrum underwater arrays for Mediterranean charter visibility. IMO maritime safety codes shape fixture certification requirements for vessels operating EU harbor regulations. Dutch yards in Amsterdam and Italian facilities compete on hull-mounted aesthetic lighting specifications, with OceanLED dominating Mediterranean refit contracts.
Norway
North Sea oil services demand for explosion-rated LED fixtures exceeds qualified supplier capacity across offshore supply vessel operators. The country's national maritime regulator enforces strict electrical safety standards for platform servicing fleets. Bergen and Stavanger yards consolidate procurement through multi-year framework agreements with certified maintenance provisions.
China
Coastal manufacturing zones produce discrete LED modules and phosphor substrates for fixture assembly serving Asian commercial fishing fleets. GB standards and MIIT industrial policy guide domestic certification requirements. Zhoushan and Qingdao port clusters concentrate vessel construction activity where cost-sensitive operators resist premium fixture retrofits despite fuel efficiency gains.
Marine LED Lights Market Competitive Landscape
The competitive structure tilts toward specialized marine divisions of diversified lighting conglomerates rather than pure-play specialists. Three tiers have crystallized: European OEM-anchored suppliers with dedicated marine divisions, underwater luminaire specialists commanding superyacht aesthetic specifications, and regional rapid-turn fabricators serving sportfishing and charter fleets. Consolidation pressure intensifies as fleet operators bundle fixture procurement with integrated control systems, favoring suppliers with vessel automation integration capabilities. Geographic expansion through Mediterranean and Southeast Asian distribution partnerships represents the dominant competitive move alongside backward integration into phosphor substrate supply.
Among European-anchored diversified lighting groups, Hella and OSRAM Licht AG occupy positions exemplifying the OEM-supply archetype with dedicated marine divisions in Germany and Denmark. OceanLED sits within the specialization tier, its name signaling underwater luminaire focus that dominates Mediterranean superyacht refit specifications. Lumitec represents the regional rapid-turn model, its Florida base enabling custom configuration velocity for sportfishing vessel operators. Signify and KOITO MANUFACTURING CO., LTD. demonstrate the conglomerate marine division pattern, with the latter's corporate suffix indicating Japanese corporate structure. Aqua Signal and Aqualuma LED Lighting exemplify naming conventions that signal marine-specific positioning, while Lumishore's compound construction suggests integrated shoreline-marine capability.
| Leading Market Players |
|---|
| Lumitec |
| Hella |
| OceanLED |
| Lumishore |
| OSRAM Licht AG |
| Signify |
| KOITO MANUFACTURING CO., LTD. |
| Aqualuma LED Lighting |
| Aqua Signal |
| Others |
Value Network & Pricing Analysis
Rare-earth phosphor substrate costs cascade through fixture manufacturing tiers, with supply concentration in limited geographies amplifying input volatility for premium underwater luminaire producers serving Mediterranean superyacht yards.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IMO-certified navigation fixtures with COLREGs validation from commercial-grade deck lighting and unbranded recreational retrofit units. Price differentiation hinges on IP68 sealing certification grade and volume scale in fleet framework agreements. Cost compression in standard-tier fixtures is intensifying because commercial operators consolidate procurement through multi-vessel contracts. Charter fleet managers exhibit highest price sensitivity; Italian superyacht builders show lowest sensitivity when specifying RGB hull-mounted arrays.
Supply Chain Analysis
Regional distribution centers in Hamburg, Miami, and Singapore anchor hub-and-spoke patterns serving Mediterranean refit yards, Caribbean charter bases, and Southeast Asian commercial fishing fleets. Manufacturing concentrates in Germany, Denmark, and coastal China zones. Fixture assembly draws from rare-earth phosphor substrates, marine-grade aluminum extrusions, and ceramic COB substrates. Single-source vulnerability in phosphor processing exposes producers to supply disruption. Distribution runs through specialized marine electrical distributors and OEM direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where superyacht aesthetic specifications and offshore explosion-rated demands shift procurement toward premium-certified fixtures with integrated control bundling.
For Market Incumbents: Anchor defensive positioning through backward integration into phosphor substrate supply and dedicated marine division capacity expansion in Norwegian offshore yards. Certification investment in IMO efficiency mandates and EU REACH compliance creates barriers against emerging Asian producers. Channel control through framework agreements with Mediterranean yacht management companies protects margin structure. For New Entrants and Emerging Players: Specialized theatrical lighting distributors offer partnership pathways into aquatic show installations and public aquarium biosecurity-rated specifications. Norwegian offshore vessel yards present the most penetrable geography given qualified supplier scarcity for explosion-rated LED fixtures. DMX-protocol integration capabilities enable differentiation against legacy fixture-only suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where fleet operators demand single-source accountability for fixture-control system bundles. Long-term viability favors suppliers with vessel automation integration capabilities and captive phosphor substrate access. Acquisition targets include underwater luminaire specialists with Mediterranean superyyard relationships and ceramic COB thermal management IP. The signal to watch is framework agreement renewal rates among Norwegian oil services contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphor Substrates | Captive rare-earth processing reduces input volatility for premium fixture manufacturers. |
| IMO Efficiency Certification Investment | COLREGs compliance validation opens commercial fleet replacement cycles. |
| DMX Protocol Control System Bundling | Integrated lighting-automation contracts capture higher values from yacht management companies. |
| Explosion-Rated Fixture Development | North Sea oil platform servicing demand exceeds qualified supplier capacity. |
| Mediterranean Distribution Partnership | Viareggio and La Spezia yard access secures superyacht aesthetic specification channels. |
Research Methodology
Multiple input streams — primary interviews with marine electrical distributors, superyacht build yard procurement directors, and offshore vessel fleet managers; secondary validation through IMO regulatory filings, US Coast Guard certification databases, and EU REACH substance restriction updates; plus customs trade data on marine fixture imports — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include fixture type, installation architecture, vessel class, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating fleet retrofit cycle timing, superyacht order book visibility, and phosphor substrate supply elasticity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IMO mandate acceleration, rare-earth export restriction policies, and offshore oil services capital allocation shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Filter Market
Marine
Integrated Bridge System for Ships Market
Marine
Marine Glass Market
Marine
Boat Steering Systems Market
Marine
Marine VFD Market
Marine
Ballast Water Management Market
Marine
Europe ROV Market
Marine
Sailboat Propellers Market
Marine
Asia-Pacific Offshore Support Vessels Market
Marine
Marine Elevators Market
Marine
Boat Trolling Motor Market
Marine
Electric Outboard Engines Market
Marine
Sea Skimmer Market
Marine
Marine Diesel Engine Market
Marine
Marine Trenchers Market
Marine
Marine Shackle Market