
 Global Submarine Market | 2026-2036
Global Submarine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Submarine Market Outlook
Defense procurement channels across NATO and Indo-Pacific allied nations are reshaping contract allocation and technology-sharing frameworks. Naval Group leverages its Barracuda-class program to sustain French nuclear submarine exports into the Australian and Indian markets. General Dynamics Electric Boat anchors US Navy supply through Columbia-class construction at its Groton and Quonset facilities. BAE Systems competes for Royal Navy Dreadnought program work while navigating AUKUS technology integration demands.
A submarine is a self-propelled underwater vessel engineered to operate below the surface for extended durations, typically constructed from high-tensile steel or titanium alloy hulls rated to depths exceeding 300 meters, with pressure hull diameters ranging from 8 to 13 meters depending on mission class. Its primary purpose spans strategic nuclear deterrence, intelligence collection, anti-submarine warfare, and seabed infrastructure protection. Nuclear submarines command the largest value share given their reactor plant complexity and decades-long service life, while autonomous submarines represent the fastest-expanding segment as navies deploy extra-large uncrewed underwater vehicles for mine countermeasures and persistent surveillance. Diesel-electric variants retain strong demand among coastal defense navies in the Indo-Pacific where shallow-water operations predominate.
The US Navy's Naval Sea Systems Command enforces reactor safety standards that constrain foreign supplier participation in nuclear submarine programs, while the EU Green Deal's defense industrial emissions framework pressures European yards to decarbonize construction processes. Australia's Defence Export Controls under the AUKUS treaty create new compliance layers for technology transfer. Stakeholders must monitor how reactor fuel enrichment restrictions and sovereign shipyard capacity constraints interact to determine which nations can sustain indigenous submarine production versus import-dependent fleet renewal.
Market Dynamics
Nuclear propulsion technology transfer agreements are restructuring fleet procurement patterns, with AUKUS treaty obligations forcing allied navies to rebuild sovereign shipyard capacity and reactor fuel supply chains from first principles.
Growth Catalysts
- Strategic Deterrence Modernization:NATO members and Indo-Pacific allies are accelerating fleet replacement cycles. The US Navy's Columbia-class program and Australia's AUKUS submarine commitment demonstrate how extended-range nuclear patrol requirements redirect procurement toward Pacific basin basing infrastructure.
- Seabed Infrastructure Protection:Critical undersea cable networks and energy pipelines require persistent submerged surveillance. Diesel-electric variants optimized for shallow-water loitering attract coastal defense budgets across Southeast Asian and Nordic markets.
- EU Green Deal Defense Industrial Emissions Framework:European yards face mandatory decarbonization of steel cutting, welding, and hull assembly processes. This regulatory pressure stimulates investment in electric arc furnace feedstock and closed-loop manufacturing systems.
Market Restraints
- Reactor Fuel Enrichment Restrictions:Weapons-grade uranium supply concentrates in a handful of sovereign enrichment facilities. Non-nuclear weapon states face treaty-limited access to high-assay low-enriched uranium, constraining indigenous nuclear submarine programs.
- Pressure Hull Steel Supply Concentration:HY-80 and HY-100 high-tensile steel production for deep-rated hulls depends on specialized US and Japanese mill capacity. Alternative suppliers require years of metallurgical qualification.
- Extended Construction Timelines:Nuclear submarine build cycles stretch across seven to ten years. Capital lockup and workforce retention across this duration deter new market entrants and strain government budget continuity.
Strategic Opportunities
- Extra-Large Uncrewed Underwater Vehicles:Autonomous submarine segments for mine countermeasures and persistent surveillance represent underpenetrated procurement categories. Navies in Norway, Singapore, and South Korea are issuing development contracts for extra-large UUV prototypes.
- AUKUS Technology Integration Demands:Australia's Defence Export Controls create new compliance service layers. Specialist engineering consultancies can capture value advising on reactor safety documentation and controlled technology handling protocols.
- Modular Diesel-Electric Propulsion:Air-independent propulsion systems using fuel cells or closed-cycle diesel are converging with lithium-ion battery banks. This technology pairing enables submerged endurance previously requiring nuclear plants at a fraction of capital cost.
Industry Challenges
- Nuclear Reactor Operator Certification:Naval Sea Systems Command enforces reactor safety standards that constrain foreign supplier participation. Qualified welders, reactor technicians, and nuclear engineers require security clearance and specialized training pipelines that take decades to establish.
- Legacy Platform Integration Complexity:New sonar, combat management, and communications systems must interface with hull architectures designed thirty years prior. Software-defined upgrades face physical space, power, and cooling constraints in existing fleet vessels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Submarine Market |
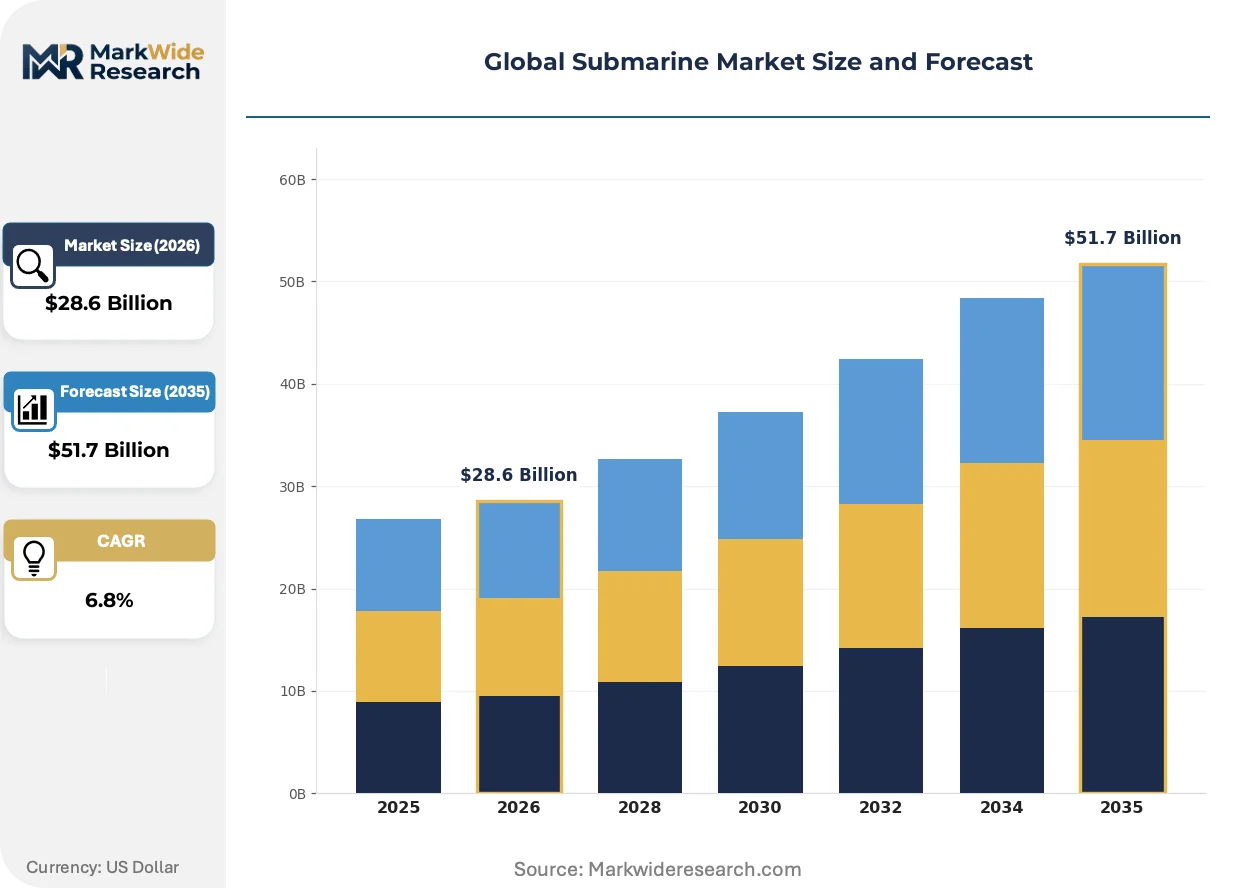
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nuclear Submarines, Diesel-Electric Submarines, Air-Independent Propulsion, Autonomous Submarines End User: Military, Research Institutions, Commercial Operators, Defense Contractors Deployment Mode: Onshore, Offshore, Coastal, Open Ocean Size: Small, Medium, Large, Extra Large |
| Companies Covered | Naval Group, General Dynamics Electric Boat, BAE Systems, ThyssenKrupp Marine Systems, Huntington Ingalls Industries, HD Hyundai Heavy Industries, Fincantieri, Mitsubishi Heavy Industries, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Submarine Market Strategic Shifts
Submarine design and construction practices are undergoing fundamental revision as digital hull modeling, additive manufacturing, and uncrewed system integration compress development cycles and expand operational envelopes.
Air-independent propulsion is collapsing the endurance gap between diesel-electric and nuclear submarines for missions under thirty days. South Korean and German shipyards are integrating fuel cell stacks with advanced battery management systems for export customers in Southeast Asia and the Middle East. This propulsion architecture is collapsing the traditional premium commanded by nuclear plants for medium-range patrol requirements.
The EU Green Deal's defense industrial emissions framework is mandating carbon accounting across steel procurement, welding energy consumption, and surface treatment chemical flows. French and Spanish yards are piloting hydrogen-powered gantry cranes and electric induction heating for hull section assembly. Nuclear submarine programs face particular scrutiny given uranium fuel cycle emissions, forcing contractors to document Scope 3 supply chain impacts.
Naval procurement offices are consolidating maintenance and modernization contracts under single-source availability agreements. The Royal Navy's Dreadnought program and US Navy's Columbia-class both embed fifteen-to-twenty-year through-life support into initial construction awards. British and American shipyards are responding by building captive overhaul capacity and predictive analytics capabilities to capture long-term revenue streams.
Global Submarine Market Segmentation
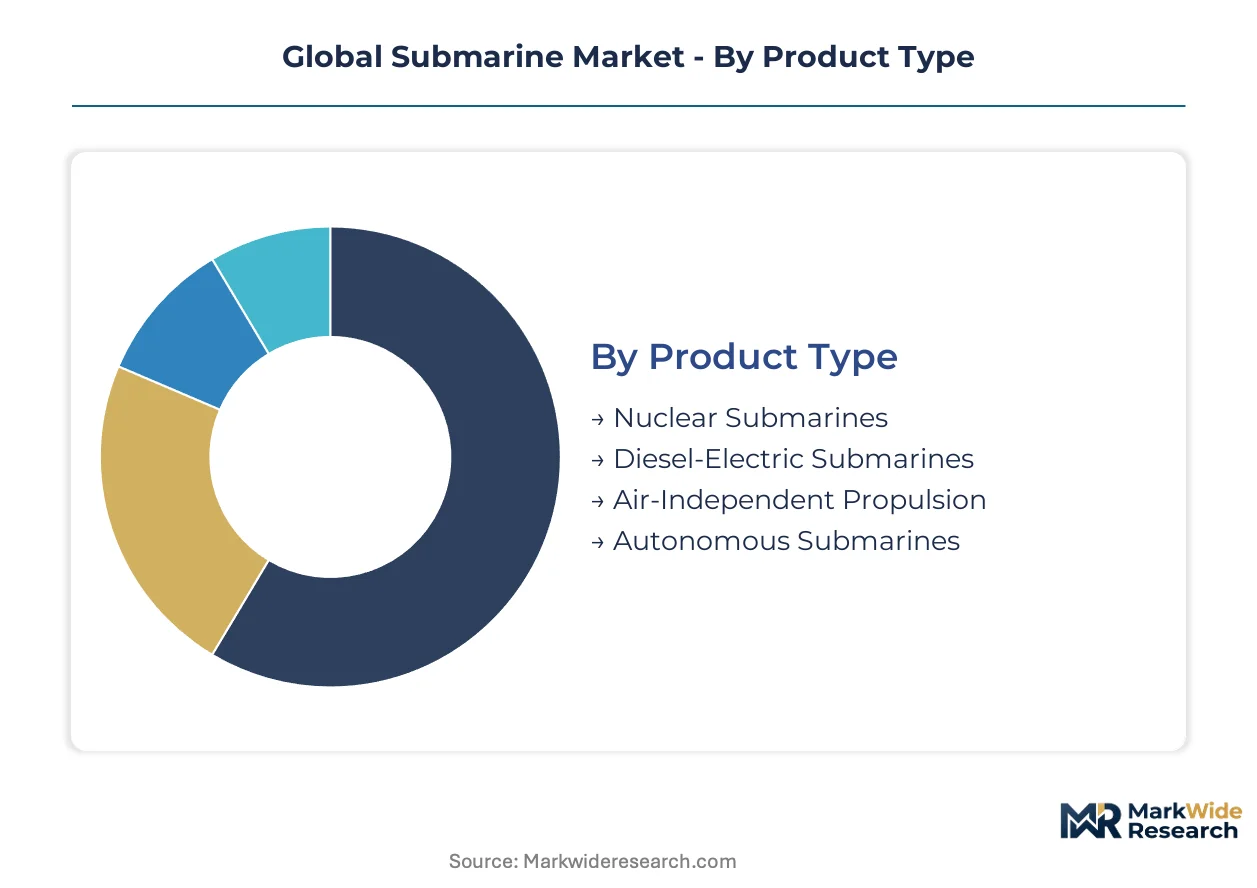
Segmentation in submarine procurement reveals divergent capital cycles and operational requirements. Nuclear programs demand decade-long construction timelines and sovereign infrastructure, while autonomous platforms compress development cycles and lower entry barriers for new suppliers.
Product Type:
Nuclear submarines stretch across seven-to-ten-year build cycles with reactor fuel qualification adding years to commissioning, while autonomous variants iterate in two-to-three-year development sprints driven by commercial robotics supply chains.
- Nuclear Submarines:Steel-hulled vessels with pressurized water reactor plants rated for 25-year fuel cycles without refueling. US Navy Columbia-class and Royal Navy Dreadnought programs concentrate demand in the Atlantic basin, constrained by weapons-grade uranium access treaties and specialized hull steel mill capacity.
- Autonomous Submarines:Extra-large uncrewed underwater vehicles deploying lithium-ion battery stacks and modular sensor payloads. Norwegian and Singaporean navies issue prototype contracts for mine countermeasures and seabed cable surveillance, exploiting commercial autonomy software from robotics clusters.
- Diesel-Electric Submarines:Conventional lead-acid or lithium-ion battery propulsion for coastal defense patrols. Southeast Asian navies favor these for shallow-water endurance at acquisition costs below nuclear alternatives.
- Air-Independent Propulsion:Fuel cell or closed-cycle diesel systems eliminating snorkel exposure. German and South Korean shipyards integrate these with advanced battery management for export customers requiring submerged endurance without reactor infrastructure.
Nuclear submarines anchor the volume base while autonomous submarines gain share at the steepest rate.
End User:
Defense contractors capture the highest contract values through multi-decade platform sustainment, while research institutions drive fastest technology refresh through iterative prototype procurement.
- Military:National navies operating strategic deterrent patrols, anti-submarine warfare, and intelligence collection. NATO and Indo-Pacific allied fleet modernization programs redirect procurement toward Pacific basin basing infrastructure under AUKUS treaty obligations.
- Defense Contractors:Prime shipbuilders and subsystem integrators holding construction and through-life support contracts. General Dynamics Electric Boat and BAE Systems embed fifteen-to-twenty-year availability agreements capturing long-term revenue streams.
- Research Institutions:National oceanographic laboratories and naval research centers commissioning experimental hull forms and sensor suites. These users tolerate higher technical risk for access to cutting-edge autonomy and propulsion architectures.
- Commercial Operators:Oil and gas majors and seabed mining ventures deploying crewed and uncrewed assets for pipeline inspection and resource survey. Regulatory frameworks for commercial nuclear propulsion remain undeveloped, limiting this segment to conventional or battery-electric systems.
Military end users dominate absolute contract value while research institutions expand most quickly as testbed demand accelerates.
Deployment Mode:
Coastal deployments favor smaller diesel-electric hulls with air-independent propulsion, while open ocean requirements drive nuclear plant selection for endurance and transit speed.
- Coastal:Shallow-water operations demanding high maneuverability and minimal draft. Baltic and South China Sea littoral states prioritize diesel-electric variants with AIP for mine laying and seabed infrastructure protection.
- Open Ocean:Deep-water patrols requiring 90-day submerged endurance and high-speed transit capability. Nuclear propulsion concentrates here due to reactor plant power density and elimination of battery recharge cycles.
- Onshore:Training, maintenance, and construction phases in sovereign shipyard facilities. Australia's Osborne Naval Shipyard and US Navy's Groton facility represent capital-intensive infrastructure anchoring regional supply chains.
- Offshore:Forward-deployed operations from allied bases or submarine tenders. AUKUS treaty provisions require new infrastructure investment in HMAS Stirling and prospective Australian east coast facilities.
Open ocean deployment commands the largest platform sizes while coastal applications show the steepest expansion trajectory for mid-size diesel-electric hulls.
Size:
Large hulls concentrate reactor plant volume and strategic weapon payload capacity, while extra-large autonomous platforms displace crewed alternatives in surveillance missions.
- Large:Nuclear ballistic missile submarines and guided missile variants exceeding 150 meters length. These hulls accommodate reactor compartments, vertical launch systems, and crew habitability for extended patrols.
- Extra Large:Uncrewed underwater vehicles exceeding 50 tons displacement with modular payload bays. Norwegian defense research establishment and US Navy's Orca program prototype these for persistent seabed warfare.
- Medium:Attack submarines and diesel-electric patrol boats between 70 and 100 meters. Coastal defense navies in the Indo-Pacific favor this size for operational flexibility and port access limitations.
- Small:Midget submarines and swimmer delivery vehicles for special operations. Limited procurement volumes concentrate in specialist naval units with discrete mission profiles.
Large hulls anchor the capital investment base while extra-large uncrewed platforms climb the fastest as autonomy matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific basin nations command pricing premiums for nuclear propulsion technology transfer, while Atlantic shipyards absorb cost penalties from EU Green Deal decarbonization mandates. Sovereign enrichment capacity and hull steel mill proximity determine which nations sustain indigenous production versus import-dependent fleet renewal.
United States
Columbia-class ballistic missile submarine construction drives demand for HY-100 hull steel and reactor plant components. Naval Sea Systems Command enforces reactor safety standards that constrain foreign supplier participation in nuclear programs. Groton and Quonset Point facilities anchor Atlantic submarine production, with Electric Boat capturing through-life support contracts spanning fifteen-to-twenty years.
United Kingdom
Royal Navy Dreadnought program renewal concentrates investment in Barrow-in-Furness shipyard capacity expansion. AUKUS treaty obligations force simultaneous reactor technology integration and sovereign workforce pipeline rebuilding. BAE Systems embeds long-term availability agreements to capture maintenance revenue across platform service life.
Australia
AUKUS submarine commitment requires rebuilding sovereign shipyard capacity at Osborne Naval Shipyard from first principles. Defence Export Controls create compliance layers for controlled nuclear technology handling. HMAS Stirling and prospective east coast facilities demand new basing infrastructure investment for nuclear patrol operations.
France
Naval Group leverages Barracuda-class program experience to sustain nuclear submarine export competitiveness. EU Green Deal defense industrial emissions framework pressures decarbonization of steel cutting and welding processes. Cherbourg and Toulon facilities pilot hydrogen-powered gantry cranes and electric induction heating for hull assembly.
South Korea
DSME and HD Hyundai Heavy Industries integrate fuel cell air-independent propulsion with lithium-ion battery management for Southeast Asian export customers. Shallow-water diesel-electric variants attract coastal defense budgets across Indonesian and Vietnamese markets. Geoje shipyard specializes in modular construction compressing build cycles for mid-size patrol hulls.
Global Submarine Market Competitive Environment
Sovereign shipyard operators and defense prime contractors split the market between nuclear strategic programs and conventional export variants. Construction timelines stretching seven-to-ten years for nuclear hulls create capital barriers that sustain incumbent positions. Two archetypes dominate: state-owned naval constructors with captive domestic demand, and private defense primes embedding through-life support into initial awards. Competitive moves concentrate on reactor technology licensing partnerships and modular construction capacity expansion.
Among state-backed naval constructors, Naval Group and BAE Systems exemplify the sovereign-integrated archetype, anchoring European nuclear submarine production through captive domestic orders and selective export positioning. General Dynamics Electric Boat occupies the premium-tier position in North American strategic programs, representing the private prime model with embedded multi-decade sustainment revenue. These three entities collectively demonstrate how reactor plant complexity and security-cleared workforce pipelines sustain concentrated supply structures against new market entry.
| Leading Market Players |
|---|
| Naval Group |
| General Dynamics Electric Boat |
| BAE Systems |
| ThyssenKrupp Marine Systems |
| Huntington Ingalls Industries |
| HD Hyundai Heavy Industries |
| Fincantieri |
| Mitsubishi Heavy Industries |
| Lockheed Martin |
| Others |
Value Chain & Pricing Dynamics
Pacific Rim freight corridors linking Japanese HY-100 steel mills to Australian and US West Coast shipyards impose cost premiums that cascade through nuclear submarine procurement, concentrating pricing power among hull steel suppliers while forcing buyers into decade-long contract structures that lock in escalation clauses.
Pricing Analysis
Configured-to-order pricing for nuclear submarines commands substantial premiums over standard diesel-electric variants, with customization depth around reactor plant specifications and combat system integration driving spreads. Price differentiation rests on weapons-grade uranium access tiers and sovereign construction yard availability, with NATO members facing softer pricing pressure than non-treaty navies constrained by enrichment restrictions. Coastal defense fleets in Southeast Asia exhibit highest price sensitivity, prioritizing air-independent propulsion variants that trade endurance for capital efficiency.
Supply Chain Analysis
Export-control regimes under AUKUS treaty provisions and US International Traffic in Arms Regulations constrain reactor technology flows to allied nations exclusively. Geographic supply concentrates in the United States, France, and the United Kingdom for pressurized water reactor plants, while Japan and South Korea dominate high-tensile hull steel production. Raw material dependencies span weapons-grade uranium, HY-80/HY-100 steel plate, and specialized welding consumables. Single-source vulnerability around enriched fuel supply chains represents the dominant structural risk. Distribution runs through sovereign naval shipyards with captive maintenance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by deferred NATO fleet modernization programs now accelerating under extended-range Pacific patrol requirements.
For Market Incumbents: Insulate reactor plant intellectual property through workforce pipeline investments at sovereign enrichment facilities, countering emerging entrant threats from South Korean shipyards developing fuel cell air-independent propulsion. Prioritize backward integration into HY-100 steel supply through long-term offtake agreements with Japanese mills, securing hull material priority allocation against competing naval programs.
For New Entrants and Emerging Players: Southeast Asian coastal defense procurement represents underpenetrated demand for mid-size diesel-electric hulls with modular air-independent propulsion. Target Indonesian and Vietnamese navies with technology transfer partnerships that circumvent direct reactor plant competition. Pursue joint development contracts for extra-large uncrewed underwater vehicles, exploiting commercial autonomy software stacks to compress development cycles versus crewed alternatives.
For Investors and Strategic Acquirers: Specialist engineering consultancies with nuclear safety certification credentials and AUKUS compliance expertise offer compelling acquisition profiles for portfolio exposure to technology transfer service layers. Long-term viability hinges on sustained Pacific basin defense procurement and sovereign shipyard capacity constraints limiting new construction competition. Monitor Australian Osborne Naval Shipyard workforce development milestones as inflection indicator for regional supply chain maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Technology Licensing Partnership | Naval Group and BAE Systems leverage French-British collaboration to sustain European nuclear submarine competitiveness against US primes. |
| Modular Construction Capacity Expansion | HD Hyundai Heavy Industries compresses diesel-electric build cycles through Geoje shipyard section prefabrication for Southeast Asian export contracts. |
| Air-Independent Propulsion Integration | DSME converges fuel cell stacks with lithium-ion battery management to collapse endurance gaps versus nuclear plants for medium-range patrol requirements. |
| Through-Life Support Contract Embedding | General Dynamics Electric Boat captures fifteen-to-twenty-year availability agreements within Columbia-class initial construction awards. |
| Extra-Large UUV Prototype Development | Norwegian defense research establishment issues development contracts for autonomous mine countermeasures exploiting commercial robotics supply chains. |
Study Parameters
A spread of perspectives from submarine program managers at national navies, reactor plant engineers at sovereign shipyards, procurement officers at defense ministries, and regulatory affairs specialists at naval classification societies converged on the working assumptions underlying this analysis. Primary interview intelligence combined with secondary validation from naval construction databases, AUKUS treaty documentation, EU Green Deal defense industrial emissions filings, and customs records tracking HY-100 steel trade flows. Bottom-up platform unit economics and top-down defense budget appropriation analysis were triangulated to anchor volume and value estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning propulsion architecture, hull size class, deployment mode, and end-user category. CAGRs were derived from fitted trend analysis against historical procurement cycles and disclosed program timelines. Industry-specific forecast inputs incorporated reactor fuel enrichment capacity constraints and sovereign shipyard workforce pipeline development rates.
Practitioners should monitor AUKUS treaty implementation milestones, EU Green Deal defense industrial emissions enforcement actions, and weapons-grade uranium supply chain disruptions for early signals warranting forecast reassessment. Material shifts in Pacific basin basing infrastructure investment commitments or reactor technology transfer agreement scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Electric Outboard Engines Market
Marine
Yacht Painting and Maintenance Market
Marine
Electric Ship Market
Marine
Marine Fender Market
Marine
GCC ROV Market
Marine
Sea Scooter Market
Marine
Singapore Container Transshipment Market
Marine
Deep-V Boat Market
Marine
Marine Shaft Power Meter Market
Marine
Steel Ship Plate Market
Marine
Integrated Bridge System for Ships Market
Marine
Europe ROV Market
Marine
Marine Airbags Market
Marine
Marine Base Steering Gear Market
Marine
Asia-Pacific Offshore Support Vessels Market
Marine
Flap Rudder Market