
 Boat Cleat Market | 2026-2036
Boat Cleat Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Cleat Market Analytics
The capital-intensity divergence between die-cast aluminum specialists and precision-machined stainless steel producers is redrawing supplier tiers in the boat cleat landscape. Attwood leverages its vertically integrated zinc-alloy foundry network to dominate OEM supply contracts for mid-size recreational vessels. Schaefer Marine anchors its position through captive 316-grade stainless forging capacity serving premium sailing and megayacht segments.
A boat cleat is a deck-mounted hardware fitting with horn-shaped arms, typically cast or forged from marine-grade alloys, designed to secure mooring lines through friction-based line handling with rated working loads from 500 to 50,000 pounds. Fixed cleats sustain the largest volume share due to their structural simplicity and universal compatibility with dock infrastructure across commercial and recreational fleets. Folding cleats are gaining structural importance in flush-deck yacht designs where snag-free surfaces reduce tripping hazards and improve aesthetic integration. Stainless steel commands the dominant material position by value, though aluminum competes aggressively on weight-sensitive performance sailing craft where every kilogram above the waterline degrades handling characteristics.
ISO 15085 welding standards and ABYC H-40 load-testing protocols shape product certification requirements for cleats installed on vessels over 20 meters, effectively filtering out uncertified Asian suppliers from premium distribution channels. The US Coast Guard's recreational craft safety inspections and the EU's Recreational Craft Directive collectively enforce minimum breaking-strength thresholds that elevate engineering documentation burdens for market entry. Stakeholders must monitor evolving megayacht build rates in Northern Europe and the regulatory harmonization pressure between ABYC and ISO testing methodologies as the decisive variables shaping competitive positioning.
Market Dynamics
Marina redevelopment cycles in Florida, Italy, and Australia are compressing replacement timelines for mooring hardware while ISO 15085 welding standards filter uncertified suppliers from premium channels. This dual pressure on demand acceleration and compliance elevation is restructuring competitive tiers across material grades and fabrication methods.
Growth Catalysts
- Recreational Yachting Fleet Expansion:Mooring hardware replacement demand concentrates in Mediterranean and Australian coastal corridors where berth construction outpaces historical maintenance schedules.
- ISO 15085 Certification Mandates:Welding protocol enforcement for vessels exceeding 20 meters elevates engineering documentation burdens that favor established European and North American fabricators.
- Flush-Deck Yacht Architecture:Snag-free surface requirements from performance sailing craft and megayacht designers accelerate folding cleat specification rates in premium build segments.
Market Restraints
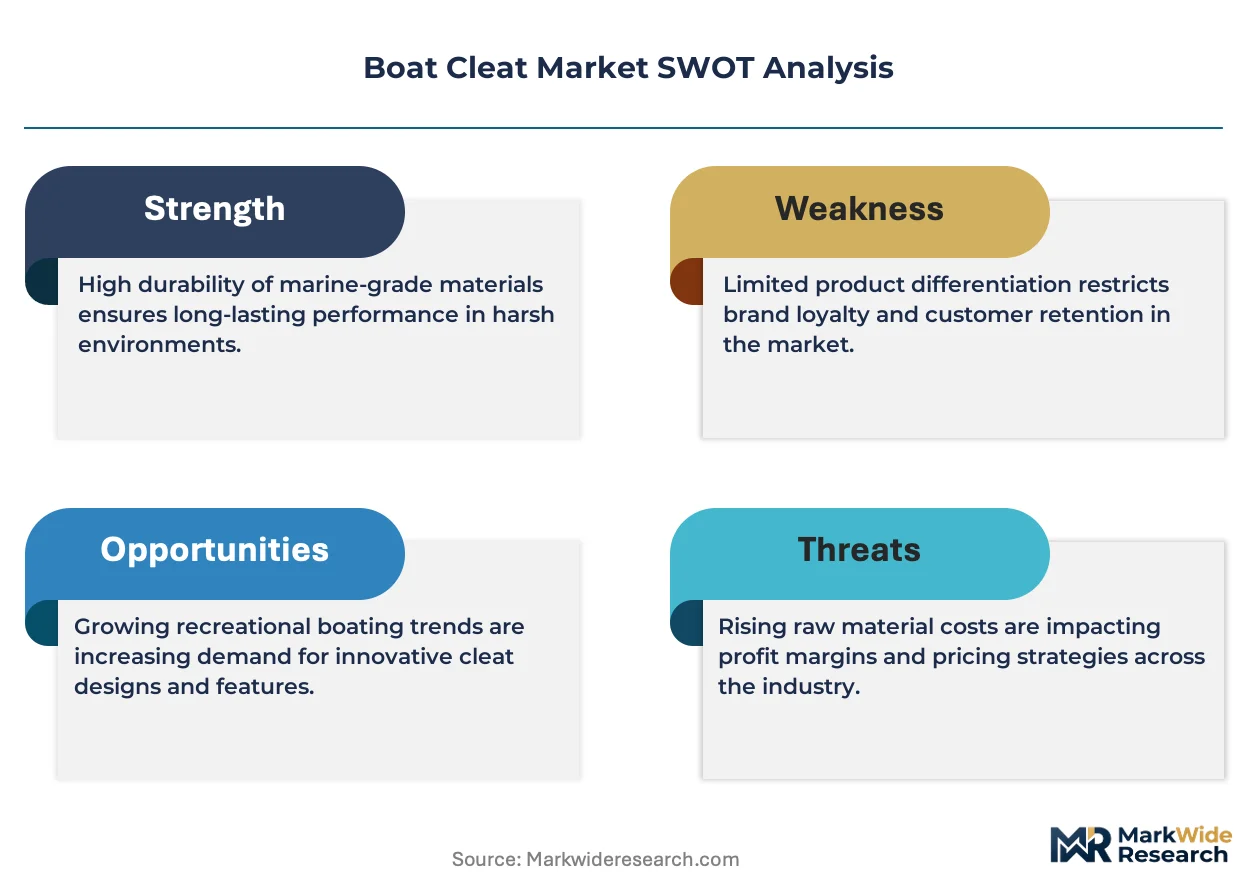
- 316-Grade Stainless Input Volatility:Nickel and molybdenum price swings in commodity markets compress margin predictability for precision-forged cleat specialists dependent on marine-grade alloys.
- Asian Supplier Exclusion:ABYC H-40 load-testing documentation requirements block uncertified foundries from premium distribution channels in US and EU recreational craft markets.
- Weight-Performance Substitution:Carbon fiber and titanium mooring hardware alternatives threaten aluminum cleat positions in ultra-light racing yacht segments where deck mass directly degrades handling metrics.
Strategic Opportunities
- Nordic Megayacht Build Corridors:Northern European superyacht construction clusters present uncaptured demand for 50,000-pound rated cleat systems with integrated load monitoring.
- EU Recreational Craft Directive Harmonization:Convergence of breaking-strength thresholds across member states reduces certification duplication costs for multi-market suppliers.
- Additive Manufacturing Convergence:Topology-optimized aluminum cleat geometries from powder-bed fusion processes enable weight reduction without sacrificing ISO-rated load capacity in performance sailing applications.
Industry Challenges
- Marine Metallurgy Talent Scarcity:Qualified welding inspectors certified to ISO 15085 standards remain concentrated in legacy shipbuilding regions, constraining production scaling for emerging foundries.
- ABYC-ISO Testing Divergence:Misaligned load-testing methodologies between US and European protocols force dual certification investments that extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Cleat Market |
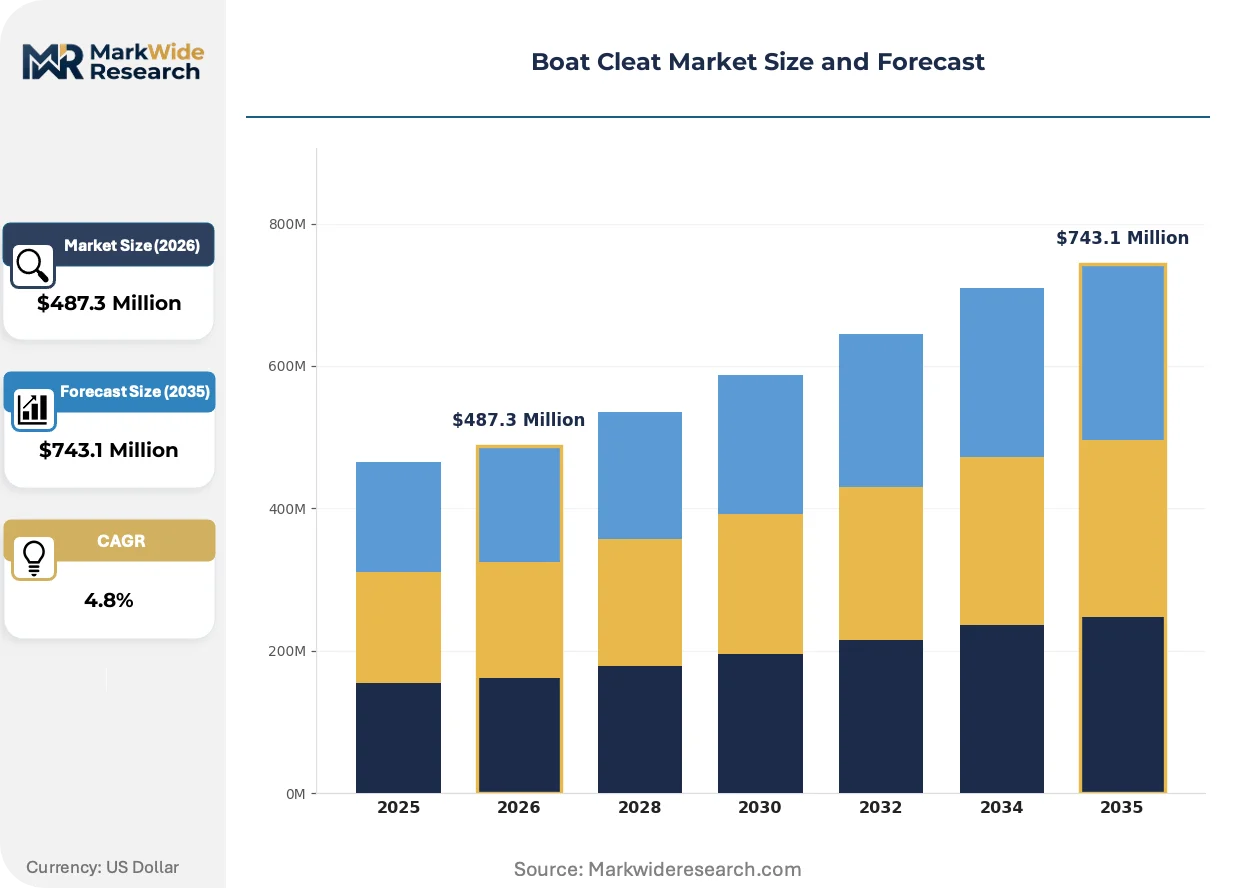
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cleats, Folding Cleats, Cam Cleats, Tapered Cleats Material: Stainless Steel, Aluminum, Plastic, Bronze Size: Small, Medium, Large, Extra Large Application: Sailing, Fishing, Yachting, Mooring |
| Companies Covered | Attwood, Perko, Schaefer Marine, West Marine, Suncor, Isure Marine, Ubi Maior, CANDOCK, Eval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Cleat Market Evolving Landscape
Material science advances and regulatory harmonization pressures are compressing traditional cleat design cycles while opening fabrication pathways previously excluded from marine hardware. Three distinct vectors currently reshape competitive positioning.
Topology-optimized aluminum alloys produced through hybrid casting-machining workflows are fragmenting the traditional stainless-aluminum performance hierarchy in mid-size recreational vessels. Performance sailing craft builders under 15 meters now specify these geometries for weight-critical deck layouts. The structural consequence is compressing premium pricing power for conventional 316-grade forged cleats in segments previously dominated by stainless specialists.
REACH substance restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent passivation and PVD coating alternatives across EU-distributed cleat portfolios. Marine hardware distributors serving Mediterranean and Baltic marinas now demand full material disclosure documentation upstream. Nordic foundries with captive electroplating capacity capture margin expansion as compliance costs exclude smaller Asian competitors from these channels.
Specifying engineers at major yacht builders now unbundle cleat procurement from integrated deck hardware packages, driving direct-to-yard contracting that disintermediates traditional chandlery distribution. Flush-deck yacht specialists in Italy and Florida lead this pattern, issuing performance-based specifications rather than brand-designated purchase orders. The shift compresses aftermarket parts revenue for legacy suppliers while elevating technical sales engineering requirements at the fabrication tier.
Boat Cleat Market Segmentation
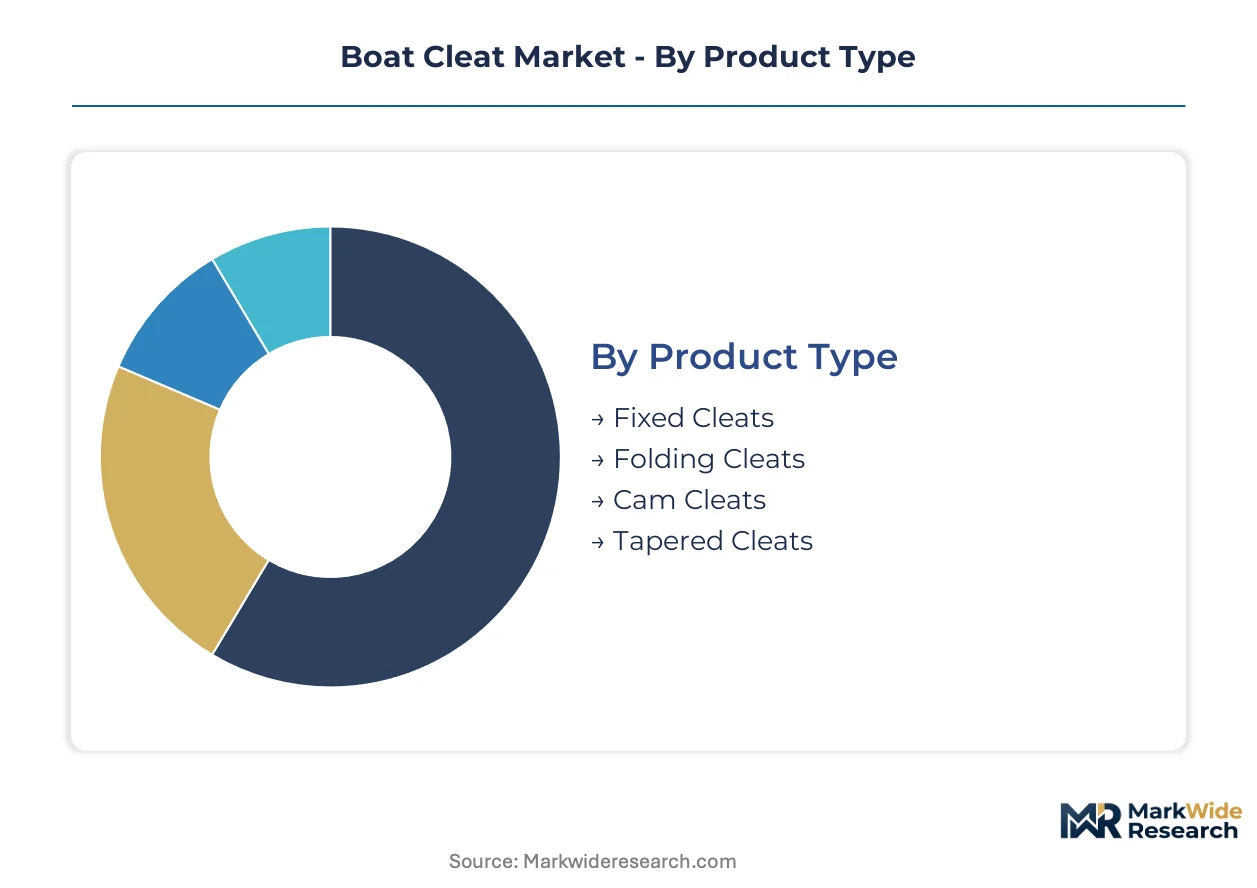
Boat cleat segmentation reveals divergent supply chain configurations across product architectures and material grades. Each dimension carries distinct geographic demand signatures, certification burdens, and margin structures that reshape supplier positioning.
Product Type:
Domestic production dominates fixed cleat supply chains in North America and Europe, while folding and cam cleat categories rely heavily on export-oriented fabrication clusters in Asia-Pacific.
- Fixed Cleats:Structural simplicity and universal dock compatibility sustain volume leadership across commercial fishing fleets and recreational marinas. Demand concentrates in Florida and Mediterranean coastal corridors where berth infrastructure standardization favors permanent-mount hardware.
- Folding Cleats:Flush-deck yacht architects in Italy and Florida specify these for snag-free surfaces that reduce tripping hazards. Performance sailing craft under 15 meters drive specification acceleration as deck mass sensitivity tightens.
- Cam Cleats:Quick-release line handling systems serve racing yacht segments where rapid sail adjustment dominates operational priorities.
- Tapered Cleats:Specialized geometries for high-load mooring applications in megayacht and commercial towing configurations.
Fixed cleats hold the largest share; momentum sits with folding cleats.
Material:
Cost tier stratification separates precision-forged stainless specialists from die-cast aluminum volume producers, with plastic and bronze occupying niche application bands.
- Stainless Steel:316-grade marine alloys command premium positioning through corrosion resistance and ISO 15085 weld certification compliance. Nordic foundries with captive forging capacity anchor supply for megayacht builders in Northern Europe.
- Aluminum:Marine-grade alloys from powder-bed fusion and hybrid casting-machining workflows fragment traditional performance hierarchies. Weight-critical racing yachts specify these for every-kilogram-counts deck layouts.
- Plastic:Glass-reinforced polymer cleats serve small-craft freshwater applications where salt corrosion is absent.
- Bronze:Traditional marine metallurgy persists in heritage vessel restoration and certain commercial fishing fleet specifications.
Stainless steel dominates value capture; aluminum climbs the fastest on weight-performance substitution.
Size:
Application scale determines procurement channel fragmentation, with small and medium cleats flowing through chandlery distribution while large and extra-large units deploy direct-to-yard contracting.
- Small:Dinghy and tender specifications under 500-pound working loads.
- Medium:Coastal recreational vessels from 20 to 40 feet dominate volume throughput.
- Large:Commercial fishing and mid-size yacht applications from 40 to 80 feet.
- Extra Large:Megayacht and commercial towing configurations exceeding 50,000-pound rated loads.
Medium sizes anchor volume; extra-large commands the steepest expansion trajectory on superyacht build rates.
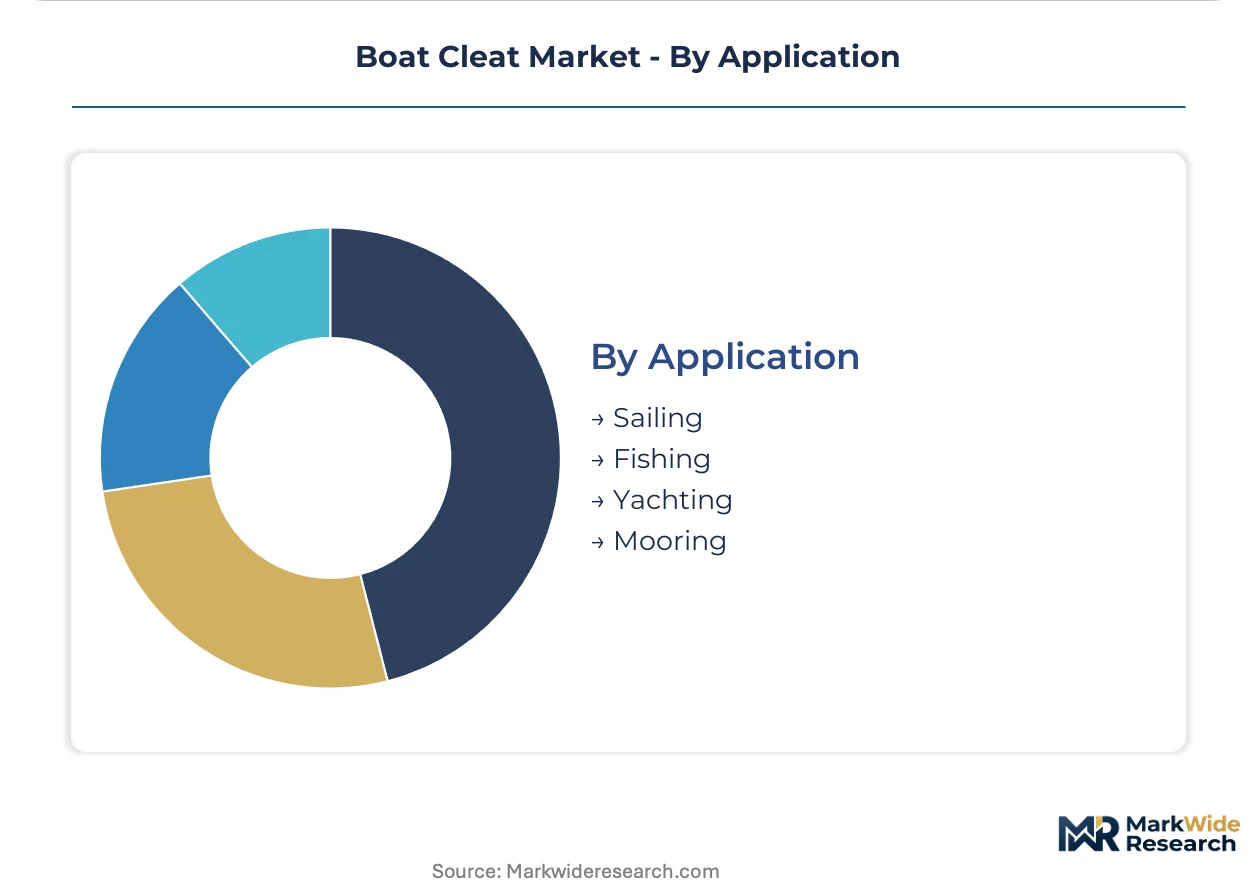
Application:
Customer type divergence splits specification authority between owner-operators in fishing and sailing versus naval architects in yachting and mooring infrastructure.
- Sailing:Performance craft builders prioritize weight reduction and flush-deck integration.
- Fishing:Commercial fleet operators emphasize durability and corrosion resistance in high-salinity operational environments.
- Yachting:Megayacht construction clusters in Northern Europe and Florida drive integrated load monitoring and aesthetic specification.
- Mooring:Marina redevelopment in Australia, Italy, and Florida compresses hardware replacement cycles for fixed infrastructure.
Mooring applications hold the largest share; yachting gains share fastest on build rate concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Italian and Northern European fabrication corridors where ISO 15085 certification scarcity limits supply expansion. Cost-competitive production clusters in Asia-Pacific face persistent exclusion from megayacht and high-performance sailing specifications due to documentation gaps.
United States
Florida's marina redevelopment wave and recreational fleet expansion drive replacement demand for fixed and folding cleat systems. The US Coast Guard enforces recreational craft safety inspections that elevate breaking-strength documentation requirements. Miami and Fort Lauderdale anchor megayacht service corridors where direct-to-yard procurement displaces traditional chandlery channels.
Italy
Flush-deck yacht architects in Viareggia and La Spezia accelerate folding cleat specifications for performance sailing craft under 15 meters. The EU's Recreational Craft Directive harmonizes breaking-strength thresholds across member states, reducing certification duplication for Italian fabricators. Lombardy and Tuscany host precision-machining clusters serving Mediterranean superyacht build programs.
Germany
Nordic megayacht construction corridors generate uncaptured demand for 50,000-pound rated cleat systems with integrated load monitoring. REACH substance restrictions on hexavalent chromium surface treatments force conversion to trivalent passivation alternatives. Hamburg and Bremen harbor regions concentrate captive electroplating capacity that captures margin expansion from compliance-driven supplier exclusion.
Australia
Coastal marina redevelopment in Queensland and New South Wales compresses hardware replacement cycles beyond historical maintenance schedules. The country's national maritime safety regulator enforces load-testing documentation that filters uncertified import suppliers. Sydney and Gold Coast clusters drive specification authority toward direct fabricator relationships.
France
Mediterranean berth construction outpaces maintenance schedules in Côte d'Azur and Brittany coastal corridors. ANSM and CNIL oversight extends to material disclosure documentation for marine hardware distribution. La Rochelle and Saint-Malo fabrication centers serve heritage vessel restoration and commercial fishing fleet specifications.
Boat Cleat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the boat cleat landscape. The market structure fragments across three functional tiers: vertically integrated foundries with captive forging capacity, precision-machining specialists serving premium segments, and die-cast volume producers for mid-size recreational vessels. Strategic archetypes include stainless steel corrosion specialists, aluminum weight-performance innovators, and hybrid casting-machining workflow adopters. Dominant competitive moves center on backward integration into marine-grade alloy supply and geographic expansion into Northern European megayacht build corridors.
Among North American fabricators, Attwood and Perko exemplify contrasting archetypes within the recreational vessel supply chain. Schaefer Marine occupies a position on the premium-tier vector serving sailing and megayacht segments. These three companies represent the structural divergence between die-cast aluminum volume production and precision-forged stainless specialization that defines competitive positioning across material grades and fabrication methods.
| Leading Market Players |
|---|
| Attwood |
| Perko |
| Schaefer Marine |
| West Marine |
| Suncor |
| Isure Marine |
| Ubi Maior |
| CANDOCK |
| Eval |
| Others |
Value Network & Pricing Analysis
Captive 316-grade stainless forging capacity in Nordic foundries and Italian precision-machining clusters anchors price floors across premium cleat tiers, while die-cast aluminum volume producers in Asia-Pacific compete on scale economies for mid-size recreational specifications. This dual-structure pricing dynamic concentrates margin capture among ISO 15085-certified fabricators serving megayacht and performance sailing segments.
Pricing Analysis
Configured-to-order pricing for 50,000-pound rated cleat systems with integrated load monitoring commands substantial premiums over standard fixed-cleat catalogs. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15085-certified European fabricators from ABYC H-40 documented North American suppliers and uncertified Asian volume producers. Cost compression in die-cast aluminum tiers is intensifying because Nordic foundries with captive electroplating capacity capture REACH compliance margins that exclude smaller competitors. Commercial fishing fleet operators in Australia and Florida exhibit highest price sensitivity, while megayacht naval architects in Northern Europe prioritize certification documentation over unit cost.
Supply Chain Analysis
Strait of Malacca transit for nickel and molybdenum concentrates exposes 316-grade stainless specialists to commodity price volatility that propagates through marine-grade alloy input costs. Supply concentration rests on Italy, Germany, and Australia for precision-forged premium cleats, while China, Vietnam, and Taiwan anchor die-cast aluminum volume production. Raw material dependencies draw from nickel-molybdenum alloy feedstock, marine-grade aluminum billet, and trivalent chromium passivation chemistry. Single-source vulnerability concentrates in ISO 15085-certified welding inspector pools concentrated in legacy shipbuilding regions. Distribution runs through direct-to-yard contracting for megayacht specifications and chandlery networks for recreational fleet replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boat cleat market fragmentation creates opportunity niches as flush-deck yacht architects unbundle cleat procurement from integrated deck hardware packages, disintermediating traditional distribution channels and elevating technical sales engineering requirements at the fabrication tier.
For Market Incumbents: Shield premium positioning by deepening backward integration into marine-grade alloy supply and securing captive ISO 15085 welding inspector capacity before talent scarcity constrains production scaling. Carbon fiber and titanium mooring hardware alternatives threaten aluminum cleat positions in ultra-light racing segments, making certification investment the critical defensive lever against substitution. For New Entrants and Emerging Players: ABYC H-40 load-testing documentation fast-tracks market entry into Florida and Mediterranean marina redevelopment corridors where berth construction compresses hardware replacement timelines. Target Australian coastal infrastructure specifications where national maritime safety regulator enforcement filters uncertified import suppliers. Lead with topology-optimized aluminum geometries from powder-bed fusion processes to penetrate weight-critical performance sailing craft under 15 meters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated foundries with captive forging capacity serving OEM supply contracts for mid-size recreational vessels. Long-term viability over the projection horizon favors precision-machining specialists with established European megayacht build corridor relationships. Monitor Nordic superyacht construction cluster activity as the decisive inflection indicator for 50,000-pound rated cleat system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15085 Certification Investment | Welding protocol compliance opens premium distribution channels in EU and US megayacht segments. |
| Backward Integration into Marine Alloy Supply | Captive nickel-molybdenum sourcing buffers margin volatility from commodity price swings. |
| Direct-to-Yard Contracting Expansion | Technical sales engineering relationships displace traditional chandlery intermediaries in Florida and Italy. |
| Additive Manufacturing Adoption | Powder-bed fusion topology optimization enables weight reduction without sacrificing ISO-rated load capacity. |
| REACH Compliance Electroplating Capacity | Trivalent passivation conversion captures margin expansion as hexavalent chromium restrictions exclude competitors. |
Research Methodology
Initial hypotheses were tested against primary input from yacht naval architects, marina infrastructure procurement managers, marine hardware distributors, and ISO 15085 welding inspectors and refined through secondary validation against customs trade data, ABYC technical standards documentation, EU Recreational Craft Directive filings, and SEC 10-K disclosures from listed marine equipment suppliers. Bottom-up vessel fleet analysis and top-down mooring hardware spend estimates were triangulated to anchor volume projections.
Variance decomposition across product type, material grade, size tier, application segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro fleet expansion assumptions. Forecast inputs incorporated megayacht build rate tracking in Northern Europe, marina redevelopment pipeline monitoring in Florida and Australia, and REACH substance restriction implementation timelines affecting surface treatment chemistry.
Decision-makers should treat outputs as directional under base assumptions of sustained recreational yachting fleet expansion and regulatory harmonization pressure between ABYC and ISO testing methodologies; material deviation in superyacht construction activity or certification enforcement intensity would warrant model refresh. Practitioners should keep alternative scenarios live as nickel-molybdenum commodity price volatility and additive manufacturing cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Flap Rudder Market
Marine
Recreational Vessel Battery Market
Marine
Marine and Marine Management Software Market
Marine
Shipbuilding Market
Marine
Tele-Operated Marine Drone Market
Marine
Marine Lighting Market
Marine
Marine Shaft Power Meter Market
Marine
Electric Ship Market
Marine
Singapore Container Transshipment Market
Marine
Marine Asset Integrity Services Market
Marine
Fishing Vessel Market
Marine
Buoys and Beacon Market
Marine
Swamp Boat Market
Marine
Marine VFD Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
US Fish Finders Market