
 Hypopituitarism Diagnostics Market | 2026-2036
Hypopituitarism Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Hypopituitarism Diagnostics Market Foresight
North American laboratory capacity is reconfiguring around automated endocrine testing workflows. Roche Diagnostics leverages its cobas platform dominance to sustain high-throughput immunoassay throughput in hospital core labs. Thermo Fisher Scientific anchors its position through specialized reagent supply chains for pituitary hormone panels. Abbott Laboratories differentiates via point-of-care connectivity that feeds directly into electronic health record systems.
Hypopituitarism diagnostics encompasses biochemical assays, imaging modalities, and genetic analyses that quantify anterior and posterior pituitary hormone deficiencies, typically measuring cortisol, thyroid-stimulating hormone, growth hormone, and sex steroids against dynamic stimulation protocols. The primary purpose is to localize lesion etiology—whether hypothalamic, pituitary, or peripheral—and guide hormone replacement therapy dosing. Immunoassays occupy the largest revenue pool due to recurring test frequency, while genetic testing captures the fastest expansion as next-generation sequencing panels identify congenital causes previously classified as idiopathic. Molecular diagnostics platforms command premium positioning where mass spectrometry methods challenge conventional immunoassay specificity for low-abundance analytes like free testosterone and insulin-like growth factor-1.
FDA premarket notification pathways and EMA in vitro diagnostic regulation govern assay analytical validity claims, while CLIA laboratory certification in the United States shapes where complex dynamic testing may be performed. WHO prequalification standards influence procurement in lower-resource settings where pituitary disorder prevalence remains undercounted. Stakeholders must monitor evolving reimbursement thresholds for combined pituitary function testing versus sequential single-hormone approaches.
Market Dynamics
Automated immunoassay platforms are compressing turnaround times for dynamic stimulation testing while tightening analytical validity requirements from FDA and EMA reshape competitive positioning for assay manufacturers.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Stricter analytical validity claims for companion diagnostics are forcing platform upgrades that expand addressable test menus in European hospital laboratories.
- Next-Generation Sequencing Panels:Molecular diagnostics platforms are capturing congenital hypopituitarism cases previously classified as idiopathic, opening new revenue streams in genetic testing laboratories.
- Hospital Core Lab Consolidation:High-throughput automation in United States academic medical centers is standardizing pituitary function testing workflows and reducing per-test operational costs.
Market Restraints
- Reagent Supply Concentration:Specialized antibody and calibrator production clusters in Germany and Switzerland create vulnerability to single-source dependencies for high-specificity hormone assays.
- CLIA Complexity Barriers:United States laboratory certification requirements restrict complex dynamic testing to reference laboratories, limiting point-of-care expansion for stimulation protocols.
- Mass Spectrometry Substitution:LC-MS/MS methods for low-abundance analytes like free testosterone are challenging immunoassay dominance in tertiary care settings with existing capital equipment.
Strategic Opportunities
- Underpenetrated Latin America:WHO prequalification pathways for hormonal assays remain underutilized in Brazil and Mexico where pituitary disorder prevalence is systematically undercounted.
- Integrated EHR Connectivity:Direct data feed protocols from diagnostic platforms to electronic health record systems are creating differentiation leverage in United States integrated delivery networks.
- AI-Assisted Image Interpretation:Machine learning algorithms applied to pituitary MRI are converging with biochemical panels to localize lesion etiology faster than sequential specialist review.
Industry Challenges
- Specialized Endocrinology Workforce Scarcity:Interpretation of dynamic stimulation test results requires fellowship-trained specialists, creating bottlenecks in community hospital settings without academic affiliations.
- Multi-Platform Integration Complexity:Harmonization of immunoassay results across Roche, Abbott, and Siemens platforms demands ongoing proficiency testing investments that strain mid-volume laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypopituitarism Diagnostics Market |
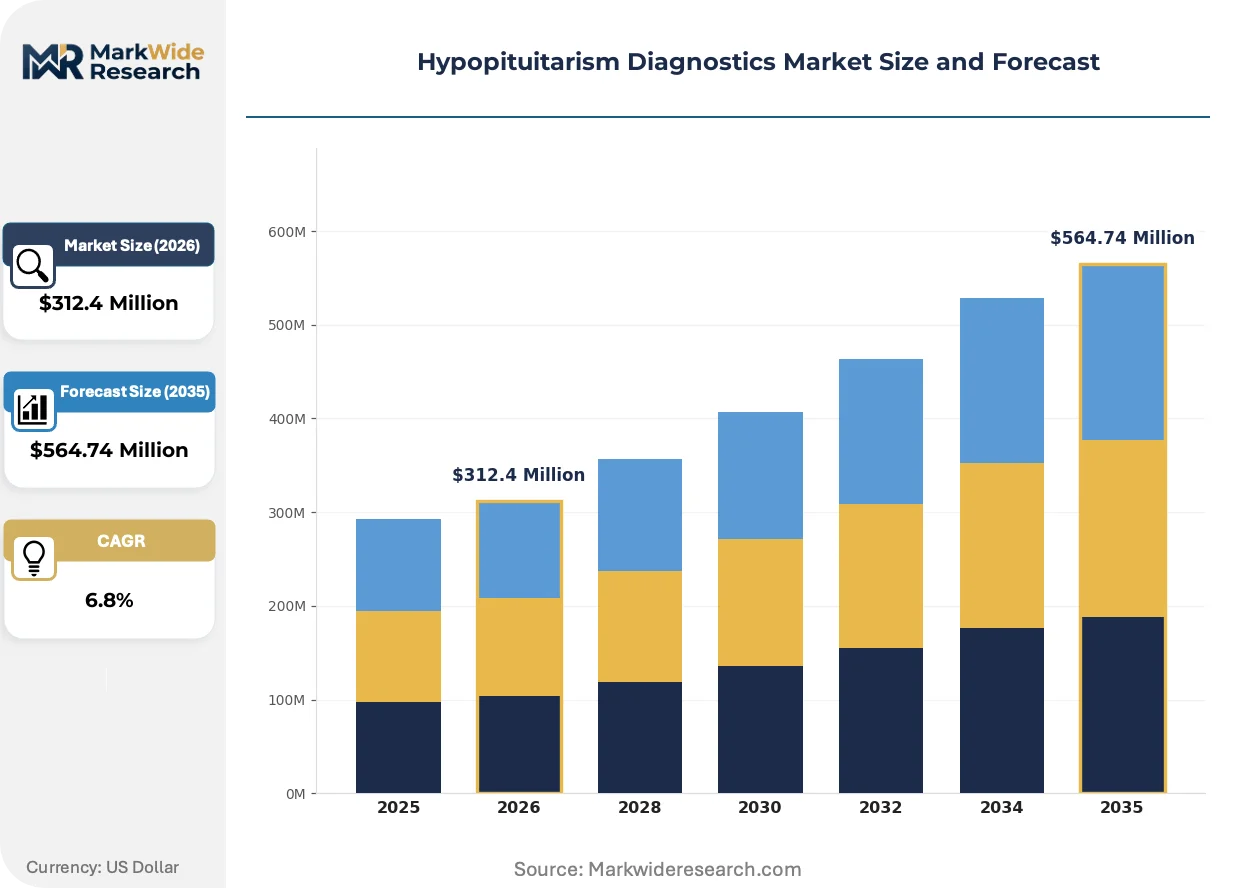
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, CT Scans, MRI, Genetic Testing End User: Hospitals, Diagnostic Labs, Research Institutes, Home Care Technology: Enzyme-Linked Immunosorbent Assay (ELISA), Radioimmunoassay, Molecular Diagnostics, Mass Spectrometry Application: Hormonal Imbalance, Tumor Detection, Genetic Disorders, Disease Monitoring |
| Companies Covered | Roche Diagnostics, Thermo Fisher Scientific Inc., Beckman Coulter, Abbott Laboratories, Bio-Rad Laboratories, Inc., bioMérieux SA, Danaher Corporation, QIAGEN N.V., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypopituitarism Diagnostics Market Shifts & Advancements
Digital pathology and remote consultation platforms are redrawing where complex pituitary case interpretation occurs, while regulatory pressure on analytical specificity accelerates platform replacement cycles.
Mass spectrometry-based steroid profiling is virtualizing the reference standard for low-abundance hormone quantification. Tertiary care endocrinology departments in the United States and Germany are adopting LC-MS/MS for free testosterone and insulin-like growth factor-1 validation. This technology is virtualizing the competitive boundary between core laboratory immunoassays and specialized reference testing.
EMA Medical Device Regulation implementation timelines are compressing CE mark renewal cycles for existing hormonal assay platforms. Manufacturers must resubmit clinical performance data under stricter post-market surveillance requirements. In vitro diagnostic companies with European revenue concentration are accelerating quality management system investments to maintain market access.
Hospital procurement committees are unbundling after-sales service contracts from instrument lease agreements, forcing diagnostic platform vendors to compete on standalone maintenance pricing. This pattern is most visible in German university hospital consortia where centralized purchasing pools extract service cost transparency. Reagent rental models are displacing capital purchase structures in mid-tier United States health systems seeking to reduce balance sheet exposure.
Hypopituitarism Diagnostics Market Segmentation
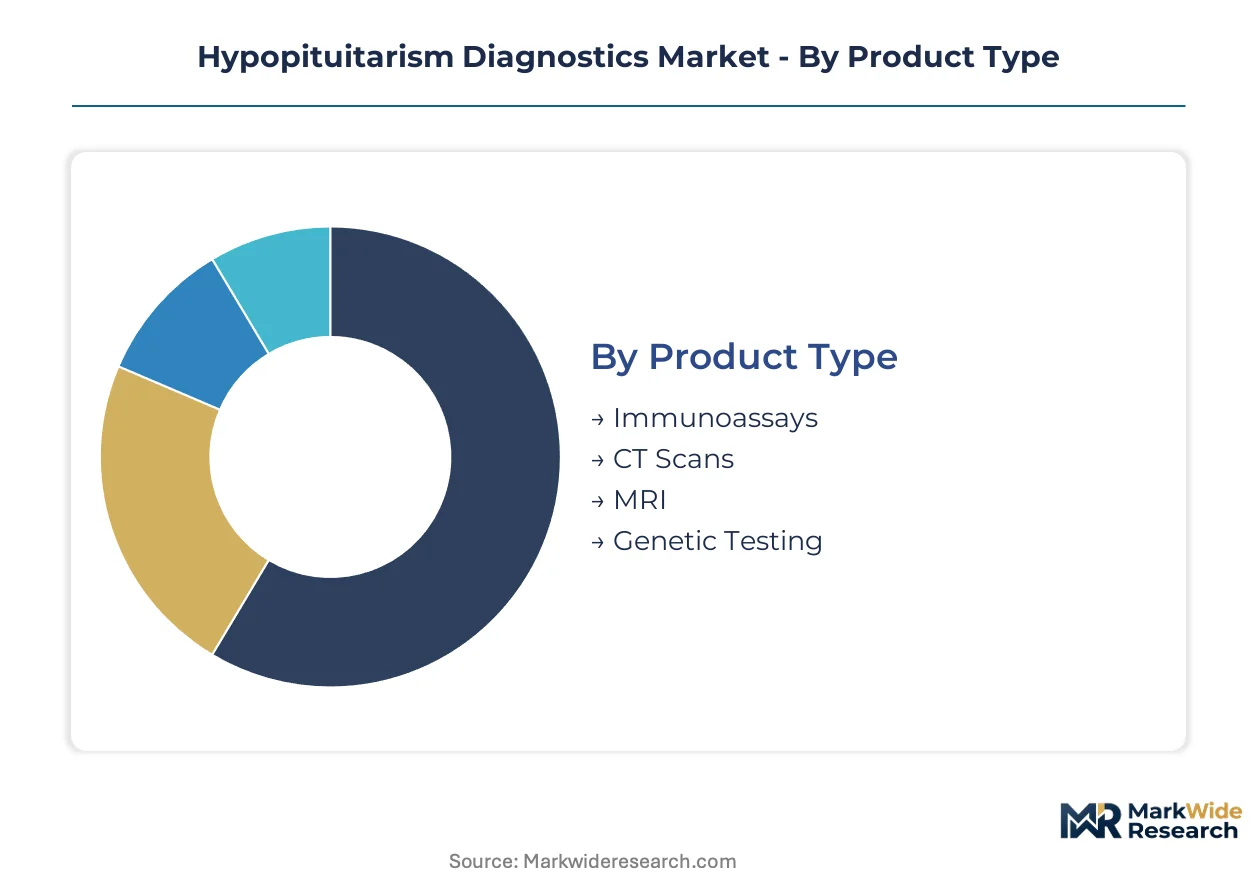
Hypopituitarism diagnostics operates across four intersecting dimensions that determine reimbursement pathways, capital deployment, and regulatory scrutiny. Product type governs margin structure, while end-user concentration shapes geographic demand patterns. Technology selection drives platform consolidation, and application focus determines clinical workflow integration.
Product Type:
Cost tier stratification across biochemical, imaging, and molecular modalities determines capital intensity and recurring revenue profiles for manufacturers.
- Immunoassays:Automated chemiluminescent and electrochemiluminescent platforms quantify cortisol, thyroid-stimulating hormone, and growth hormone through high-throughput workflows. Hospital core laboratories in the United States and Germany concentrate procurement around integrated systems that compress turnaround times for dynamic stimulation protocols.
- MRI:Pituitary-dedicated sequences with gadolinium contrast localize sellar and suprasellar lesions with millimetric resolution. Tertiary academic medical centers anchor demand as fellowship-trained neuroradiologists interpret complex cases requiring differentiation of microadenomas from Rathke cleft cysts.
- CT Scans:High-resolution bone algorithm imaging detects calcifications and bony erosions in congenital or invasive pituitary pathology. Emergency departments deploy CT for acute presentations where MRI contraindications exist.
- Genetic Testing:Next-generation sequencing panels identify PROP1, POU1F1, and HESX1 mutations in congenital hypopituitarism. Reference laboratories in Japan and Switzerland are expanding test menus as idiopathic cases undergo reclassification.
Immunoassays hold installed capacity across hospital networks. Genetic testing is rotating up the share rankings as reclassification of congenital cases accelerates.
End User:
Customer type concentration determines service intensity, regulatory compliance burden, and connectivity requirements for diagnostic platforms.
- Hospitals:Academic medical centers and community hospital systems perform complex dynamic stimulation testing under CLIA high-complexity certification. United States integrated delivery networks are standardizing pituitary function panels across multi-site laboratory networks to reduce operational variability.
- Diagnostic Labs:Independent reference laboratories in Germany and Japan specialize in low-volume, high-specificity hormone assays requiring mass spectrometry confirmation. These facilities capture overflow from hospital core labs lacking LC-MS/MS capacity.
- Research Institutes:Translational endocrinology centers investigate novel biomarkers for subclinical hypopituitarism. NIH-funded consortia in Bethesda and university-affiliated institutes in Heidelberg drive protocol development for next-generation pituitary function assessment.
- Home Care:Salivary cortisol collection kits and dried blood spot cards enable remote sampling for pediatric and rural populations. Reimbursement limitations in the United States constrain expansion beyond wellness-oriented direct-to-consumer channels.
Hospitals dominate absolute test volume. Diagnostic labs are climbing the fastest as outsourcing of specialized assays accelerates.
Technology:
Maturity gradients across established immunoassay platforms and emerging molecular methods create divergent investment horizons for laboratory capital planning.
- Enzyme-Linked Immunosorbent Assay (ELISA):Microplate-based colorimetric detection remains prevalent in resource-limited settings and research applications. WHO prequalification pathways are expanding access in Brazil and Mexico where laboratory infrastructure supports manual workflows.
- Radioimmunoassay:Iodine-125 labeled tracers provide reference-standard sensitivity for low-abundance analytes like ACTH. Specialized reference laboratories in Switzerland maintain capacity for discrepancy resolution between automated immunoassay platforms.
- Molecular Diagnostics:Real-time PCR and next-generation sequencing platforms detect congenital hypopituitarism gene panels. PMDA regulatory pathways in Japan are streamlining approval for companion diagnostic claims linking genetic results to hormone replacement protocols.
- Mass Spectrometry:LC-MS/MS methods for free testosterone and insulin-like growth factor-1 are displacing immunoassay dominance in tertiary settings. German university hospital consortia are consolidating steroid profiling services to capture economies of scale.
ELISA maintains broad installed base. Mass spectrometry is gaining share fastest as analytical specificity requirements tighten under EMA post-market surveillance.
Application:
Clinical utility focus determines test panel composition, specialist referral patterns, and longitudinal monitoring frequency.
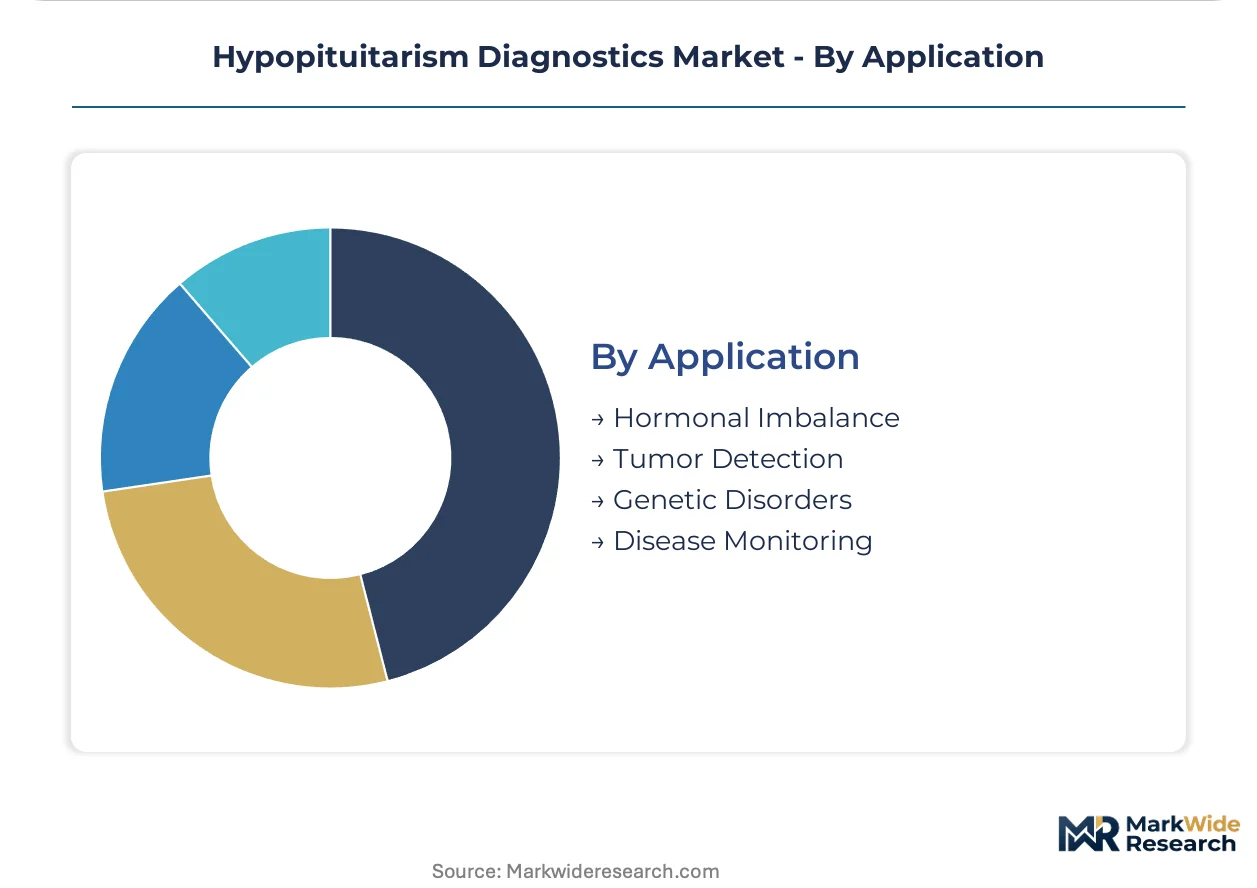
- Hormonal Imbalance:Dynamic stimulation protocols—insulin tolerance, glucagon, and arginine-GHRH testing—quantify anterior pituitary reserve. United States endocrinology practices concentrate this testing in fellowship-trained centers due to CLIA complexity requirements.
- Tumor Detection:MRI with dedicated pituitary protocols and visual field assessment localizes space-occupying lesions. Neurosurgical referral networks in Japan and Germany coordinate preoperative biochemical staging with transsphenoidal surgical planning.
- Genetic Disorders:Neonatal screening expansions and familial cascade testing identify congenital hypopituitarism before clinical manifestation. Swiss reference laboratories are developing targeted panels for PROP1-related combined pituitary hormone deficiency.
- Disease Monitoring:Post-treatment surveillance for pituitary adenoma recurrence combines biochemical remission criteria with serial imaging. Longitudinal test frequency creates recurring revenue streams for immunoassay manufacturers.
Hormonal imbalance assessment commands the largest test volume base. Genetic disorder applications are expanding most quickly as newborn screening panels broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic consumption patterns diverge sharply by geography: the United States prioritizes high-throughput automation in consolidated hospital networks, while Japan and Germany emphasize specialized reference laboratory precision for complex hormonal assays.
United States
Academic medical centers in Boston and Bethesda drive dynamic stimulation test volumes under CLIA high-complexity certification requirements. FDA premarket notification pathways govern assay analytical validity claims for new immunoassay platforms. The Mayo Clinic and NIH-funded consortia anchor specialized endocrinology interpretation capacity that community hospitals increasingly outsource to.
Germany
University hospital consortia in Heidelberg and Munich standardize pituitary function testing workflows through centralized purchasing pools. EMA In Vitro Diagnostic Regulation implementation compresses CE mark renewal cycles for hormonal assay platforms. The Baden-Württemberg and Bavaria clusters concentrate mass spectrometry capacity for free testosterone and IGF-1 validation services.
Japan
PMDA regulatory pathways streamline approval for companion diagnostics linking genetic results to hormone replacement protocols in Tokyo and Osaka metropolitan laboratories. Translational research institutes in Kobe and Tsukuba develop novel biomarkers for subclinical hypopituitarism identification. The Kanto region anchors specialized neuroradiology interpretation for pituitary MRI with dedicated sellar protocols.
Switzerland
Reference laboratories in Basel and Zurich maintain radioimmunoassay capacity for discrepancy resolution between automated immunoassay platforms. Swissmedic post-market surveillance requirements enforce stringent quality management systems for hormone assay reagent production. The Basel biotech cluster supports specialized antibody and calibrator manufacturing for high-specificity pituitary hormone panels.
Brazil
WHO prequalification pathways for hormonal assays remain underutilized despite systematic undercounting of pituitary disorder prevalence in São Paulo and Rio de Janeiro metropolitan regions. The national pharmaceutical regulator governs import licensing for diagnostic reagents. Southeast Brazil concentrates the limited endocrinology specialist workforce available for dynamic test interpretation outside academic centers.
Hypopituitarism Diagnostics Market Competitive Landscape
Capability concentration sits with specialized reference laboratories and precision diagnostics developers; scale advantage sits with consolidated hospital core lab automation providers. The market structures around three tiers: multinational platform manufacturers with installed base dominance, mid-sized reagent specialists with disease-specific assay portfolios, and regional service laboratories with interpretation expertise. Strategic moves center on reagent rental model expansion and quality management system investments to maintain EMA market access.
Among platform-scale manufacturers, Roche Diagnostics and Abbott Laboratories exemplify the automation-centric archetype with cobas and Alinity system footprints across United States and European hospital networks. Thermo Fisher Scientific occupies a position within the reagent-specialist tier, anchoring supply chains for pituitary hormone panel components. Siemens Healthineers and Danaher Corporation sit within the diversified health technology conglomerate structure, representing portfolio breadth strategies that span imaging, diagnostics, and life sciences instrumentation. These named entities illustrate competitive positioning patterns rather than definitive market share claims.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Thermo Fisher Scientific Inc. |
| Beckman Coulter |
| Abbott Laboratories |
| Bio-Rad Laboratories, Inc. |
| bioMérieux SA |
| Danaher Corporation |
| QIAGEN N.V. |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Single-source antibody and calibrator production clusters in Germany and Switzerland determine both three-tier pricing structure across premium, standard, and economy levels and supply chain vulnerability to disruption. Reagent rental models are displacing capital purchase structures as mid-tier health systems seek balance sheet protection, while procurement committees unbundle after-sales contracts to extract service cost transparency.
Pricing Analysis
Geographic price spreads between United States academic medical centers and German university hospital consortia reflect certification-grade differentiation and after-sales bundling configurations. Pricing stratifies across premium, standard, and economy tiers based on analytical specificity claims and EMA post-market surveillance compliance status. Cost compression in standard-tier immunoassay reagents is intensifying because hospital procurement committees centralize purchasing pools. Community hospital laboratories without CLIA high-complexity certification exhibit highest price sensitivity; tertiary academic centers with dedicated endocrinology infrastructure demonstrate lowest.
Supply Chain Analysis
Upstream feedstock for high-specificity hormone assays draws from monoclonal antibody production facilities concentrated in Switzerland, Germany, and the United States. Specialized calibrator matrices and isotope-labeled tracers rest on precision chemical synthesis capabilities anchored in Basel and Zurich clusters. Single-source vulnerability permeates the reagent supply tier where Swissmedic-enforced quality management systems create regulatory chokepoints for market entry. Distribution runs through regional reference laboratory networks that consolidate overflow testing from hospital core labs lacking LC-MS/MS capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
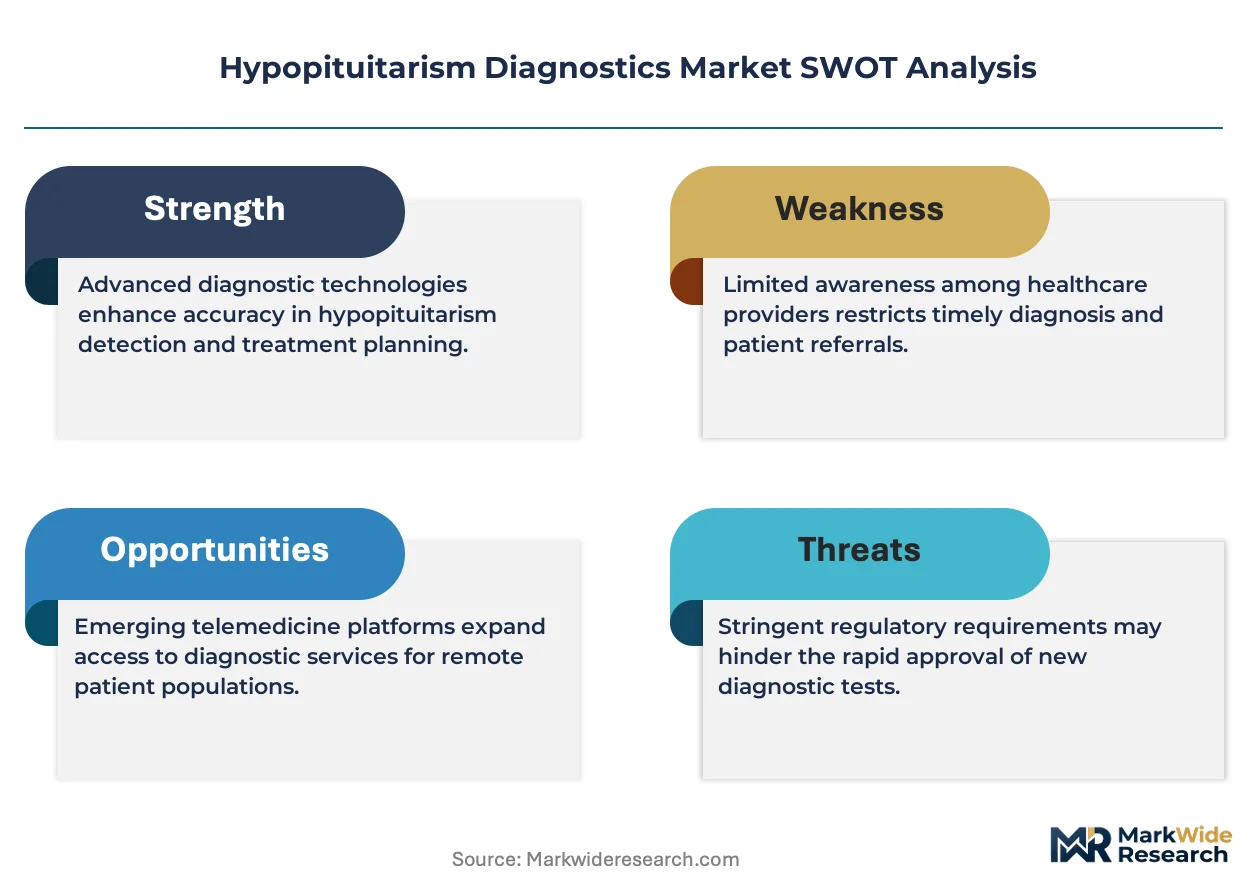
This market functions as a defensive-moat story where regulatory entrenchment around FDA premarket notification and EMA In Vitro Diagnostic Regulation creates durable switching costs for validated assay platforms.
For Market Incumbents: Build switching-cost moats through integrated EHR connectivity protocols that embed diagnostic platforms into hospital information system architecture. Consolidate position by acquiring specialized mass spectrometry service laboratories in Germany to capture reference-standard validation workflows. Mass spectrometry substitution threatens immunoassay dominance in tertiary settings; vertical integration into steroid profiling services defends margin position. For New Entrants and Emerging Players: Establish a beachhead in Latin American reference laboratory markets where WHO prequalification pathways remain underutilized despite systematic undercounting of pituitary disorder prevalence. Target Brazilian metropolitan regions with salivary cortisol collection kits and dried blood spot cards for pediatric populations underserved by fellowship-trained endocrinologists. Partner with regional distributors holding import licensing for diagnostic reagents to navigate national pharmaceutical regulator requirements. For Investors and Strategic Acquirers: EMA Medical Device Regulation implementation reshapes the acquisition landscape by compressing CE mark renewal cycles and accelerating quality management system investment requirements. Long-term viability centers on molecular diagnostics platforms capturing congenital hypopituitarism cases previously classified as idiopathic. Acquisition target archetype: mid-sized reagent specialists with PROP1 and HESX1 gene panel capabilities. Signal to watch: PMDA regulatory pathway streamlining for companion diagnostic claims linking genetic results to hormone replacement protocols.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Quality Management System Investment | CE mark renewal under stricter post-market surveillance requirements preserves European hospital laboratory access. |
| Integrated EHR Connectivity Development | Direct data feed protocols from cobas and Alinity platforms embed automation vendors into United States integrated delivery networks. |
| Mass Spectrometry Service Consolidation | LC-MS/MS capacity capture in German university hospital consortia secures reference-standard validation for free testosterone and IGF-1. |
| Next-Generation Sequencing Panel Expansion | PROP1, POU1F1, and HESX1 mutation detection opens revenue streams in genetic testing laboratories reclassifying idiopathic cases. |
| WHO Prequalification Pathway Utilization | Hormonal assay access expansion in Brazil and Mexico addresses systematically undercounted pituitary disorder prevalence. |
Research Methodology
Initial hypotheses were tested against primary input from endocrinology laboratory directors, hospital procurement committee members, diagnostic platform engineers, and regulatory affairs specialists at in vitro diagnostic manufacturers and refined through secondary validation. FDA 510(k) premarket notifications, EMA In Vitro Diagnostic Regulation guidance documents, CLIA laboratory certification databases, and hospital GPO contract repositories anchored quantitative sizing. Bottom-up test volume modeling across United States, German, and Japanese hospital networks triangulated against top-down immunoassay platform installed base estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, end-user concentration, technology maturity, and application focus. CAGRs were derived from test volume growth trajectories and reagent rental model penetration curves. Industry-specific forecast inputs incorporated EMA Medical Device Regulation implementation timelines and PMDA companion diagnostic pathway streamlining.
Stress conditions across regulatory approval delays, reagent supply disruptions, and mass spectrometry substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospital core lab consolidation velocity and genetic testing reimbursement expansion. Cross-checking against hospital capital expenditure disclosures and reference laboratory service line growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Glucose Biosensors Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Vision Screeners Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Pathogen Detection Market