
 Blood Testing Market | 2026-2036
Blood Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Testing Market Analysis
EU IVDR is hardening the cost-of-entry calculus for blood testing manufacturers seeking CE-marked access to European diagnostic laboratories. Abbott Laboratories leverages its vertically integrated immunoassay manufacturing to sustain compliance economies that smaller rivals cannot match. Siemens Healthineers anchors its competitive position through deep automation expertise in hematology analyzer platforms deployed across German and French hospital networks.
Blood testing encompasses the quantitative and qualitative analysis of blood specimens using instruments, reagents, and consumables to detect cellular components, biochemical markers, coagulation factors, or nucleic acid targets, typically requiring sample volumes between 100 microliters and 10 milliliters depending on assay complexity. Immunoassay platforms currently command the largest product type revenue pool due to recurring reagent consumption tied to chronic disease monitoring, while microfluidics technology represents the fastest-expanding segment as point-of-care devices shrink sample requirements and turnaround times for infectious disease screening in non-hospital settings.
The FDA regulates blood testing devices as Class II or Class III in vitro diagnostics under 21 CFR requirements, while the EU IVDR imposes stricter clinical evidence and post-market surveillance obligations on manufacturers distributing across European diagnostic laboratories. CLIA certification in the United States shapes demand by stratifying test complexity and determining which procedures hospitals, reference labs, or physician offices may perform. Stakeholders must weigh the capital intensity of automated platform upgrades against the regulatory risk of legacy system obsolescence as both jurisdictions tighten analytical performance and traceability standards.
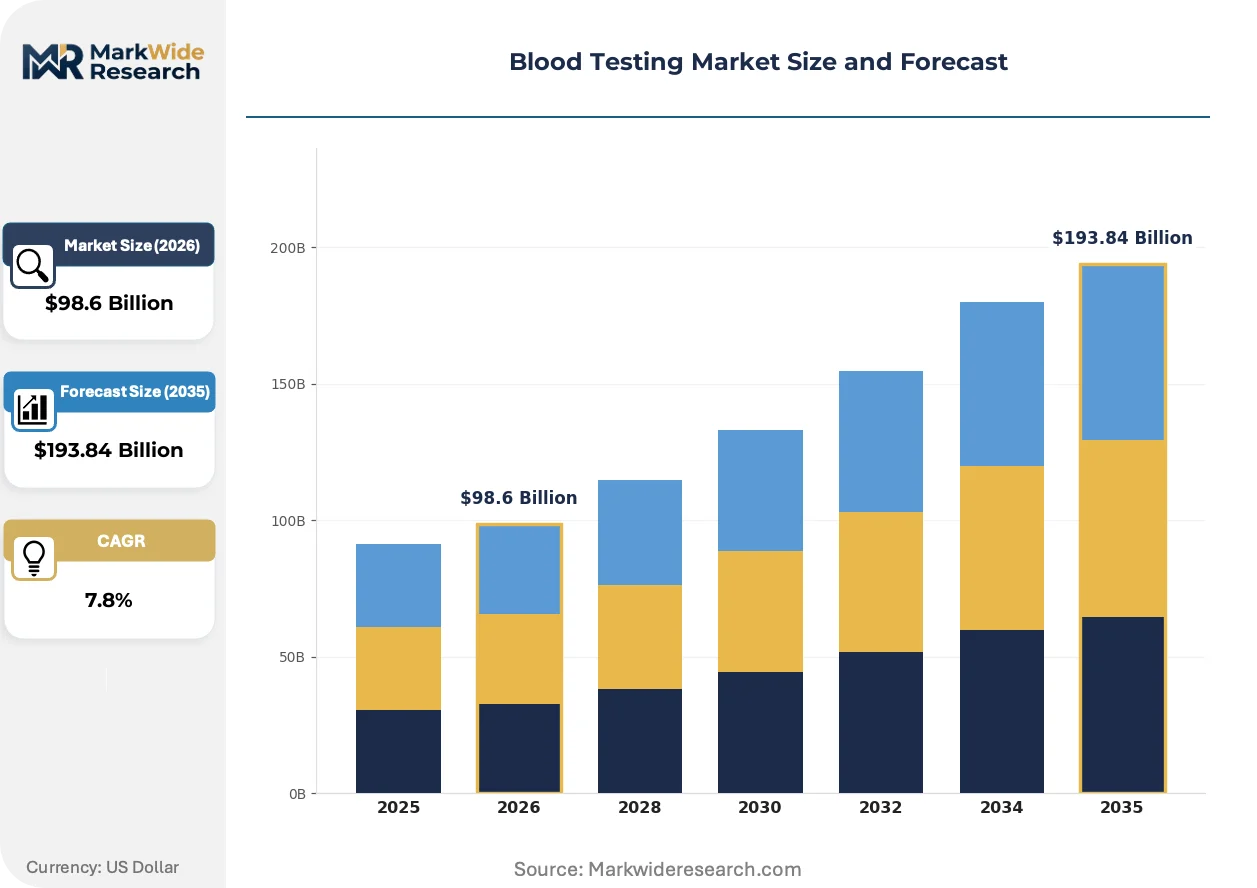
Market Dynamics
EU IVDR compliance deadlines are compressing manufacturer timelines while automated hematology platforms absorb capital budgets across hospital networks, creating a bifurcation between scaled platform operators and reagent-dependent specialists.
Growth Catalysts
- Chronic disease monitoring protocols:Diabetes and cardiovascular management programs in Germany and France require quarterly HbA1c and lipid panel testing, generating recurring reagent consumption.
- FDA quality-system tightening:Enhanced 21 CFR Part 820 enforcement drives hospital laboratories toward integrated analyzer platforms with embedded quality control modules.
- Microfluidics miniaturization:Point-of-care infectious disease screening in physician offices and retail clinics reduces sample volume requirements below 100 microliters.
Market Restraints
- EU IVDR clinical evidence burden:Stricter post-market surveillance obligations extend certification timelines and elevate documentation costs for CE-marked devices.
- Reagent supply concentration:Specialized antibody and enzyme suppliers cluster in Switzerland and southern Germany, creating single-source vulnerability for immunoassay manufacturers.
- Analyzer platform capex intensity:Automated hematology systems require seven-figure capital commitments, freezing out mid-tier hospital laboratories.
Strategic Opportunities
- Home-based coagulation monitoring:INR self-testing for anticoagulation therapy patients bypasses hospital phlebotomy entirely.
- India's CDSCO fast-track pathway:Streamlined approval for Class B and C in vitro diagnostics accelerates market entry for mid-complexity assays.
- Digital pathology convergence:Integration of AI-enabled cell morphology analysis with traditional hematology analyzers creates premium pricing tiers.
Industry Challenges
- IVDR technical documentation backlog:Notified body capacity constraints delay CE certificate renewals for legacy immunoassay products.
- Analyzer-IT integration complexity:Hospital laboratory information systems require custom middleware development for bidirectional data exchange with new platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Testing Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $193.84 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biochemical Assays, Hematology Analyzers, Coagulation Analyzers, Immunoassays Technology: PCR, ELISA, Microfluidics, Mass Spectrometry End User: Hospitals, Diagnostic Laboratories, Home Care Settings, Research Institutions Application: Infectious Diseases, Blood Grouping, Cancer Diagnosis, Metabolic Disorders |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, Bio-Rad Laboratories, Inc., Quest Diagnostics Incorporated, Becton, Dickinson and Company, Thermo Fisher Scientific Inc., bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Testing Market Emerging Trajectories
Digital integration and miniaturization are redefining where blood testing occurs, shifting analytical capacity from centralized laboratories toward distributed diagnostic nodes.
Microfluidics-based point-of-care devices is overtaking conventional benchtop analyzers for infectious disease screening in urgent care settings. Retail clinic chains and emergency departments in the United States deploy cartridge-based systems delivering results within fifteen minutes. This compression of turnaround time is overtaking the historical advantage of hospital central laboratories for routine pathogen detection.
EU IVDR's enhanced clinical evidence requirements force manufacturers to rebuild technical documentation for legacy immunoassay portfolios. The regulation mandates proactive post-market performance follow-up and trend reporting that exceeds predecessor IVDD obligations. German reference laboratories now demand extended stability data and traceability matrices as procurement prerequisites.
Hospital procurement departments unbundle analyzer hardware from reagent supply agreements, reversing decade-long bundled pricing conventions. Independent service organizations now compete for maintenance contracts previously captive to original equipment manufacturers. This disaggregation is most advanced in French and Dutch hospital networks seeking operational flexibility.
Blood Testing Market Segmentation
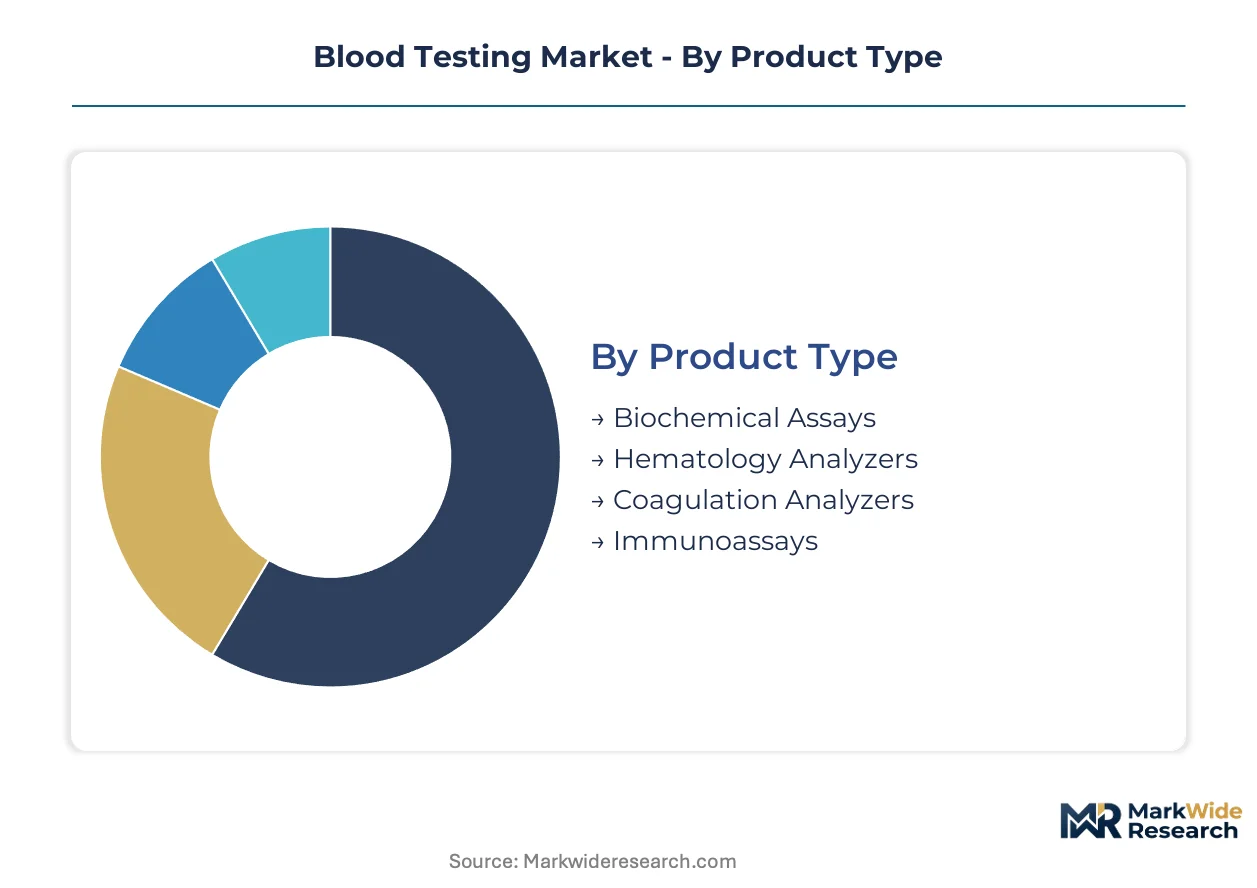
Blood testing segmentation reveals how regulatory complexity and automation intensity fragment procurement patterns across healthcare settings. Each dimension—product, technology, end user, and application—carries distinct compliance burdens and capital requirements that reshape competitive positioning.
Product Type:
Standalone benchtop systems dominate high-throughput hospital laboratories, while cartridge-based formats embed into distributed care networks where space and technical staffing constrain deployment.
- Immunoassays:These platforms detect antibodies, antigens, and hormones through labeled binding reactions, consuming specialized reagents on recurring schedules. Demand concentrates in German and French reference laboratories where EMA-aligned protocols mandate quarterly chronic disease monitoring for diabetes and cardiovascular patients.
- Hematology Analyzers:Automated cell counters classify blood components through flow cytometry and impedance methods. Siemens Healthineers anchors European standardization through platforms deployed across hospital networks in Germany, though seven-figure capital commitments freeze out mid-tier facilities.
- Biochemical Assays:Enzymatic and colorimetric methods quantify electrolytes, enzymes, and metabolites in serum or plasma specimens.
- Coagulation Analyzers:Clot-based and chromogenic tests measure hemostasis parameters for anticoagulation therapy management.
Volume placements concentrate in immunoassays; the faster expansion belongs to hematology analyzers as automation penetrates tier-two hospital networks.
Technology:
Cost stratification separates capital-intensive platforms from disposable-intensive formats, with reimbursement codes favoring centralized laboratory confirmation over point-of-care screening.
- Microfluidics:Miniaturized channels manipulate sub-milliliter samples through laminar flow physics. Urgent care chains and retail clinics in the United States deploy cartridge-based systems delivering infectious disease results within fifteen minutes, bypassing hospital phlebotomy entirely.
- ELISA:Enzyme-linked immunosorbent assays remain the workhorse for batch-processed antibody detection in high-volume reference laboratories.
- PCR:Polymerase chain reaction amplifies nucleic acid targets for pathogen identification and genetic marker detection.
- Mass Spectrometry:High-resolution molecular weight analysis enables metabolite profiling and therapeutic drug monitoring in specialized academic medical centers.
Microfluidics commands premium pricing per test; mass spectrometry maintains the steepest expansion trajectory as metabolomics enters clinical workflows.
End User:
Customer type determines regulatory pathway complexity, with CLIA certification tiers in the United States and IVDR conformity routes in Europe creating divergent go-to-market economics.
- Diagnostic Laboratories:Centralized facilities process thousands of specimens daily through automated workflow integration. German reference laboratories now demand extended stability data and traceability matrices as procurement prerequisites under tightened EU IVDR obligations.
- Hospitals:Acute care settings balance STAT turnaround requirements against economies of scale from high-volume routine testing.
- Home Care Settings:Patient-operated devices for INR monitoring and glucose tracking bypass clinical infrastructure entirely.
- Research Institutions:Academic and pharmaceutical laboratories drive protocol development for novel biomarker validation.
Procurement volumes cluster in diagnostic laboratories; home care settings are gaining share fastest as self-testing protocols expand reimbursement eligibility.
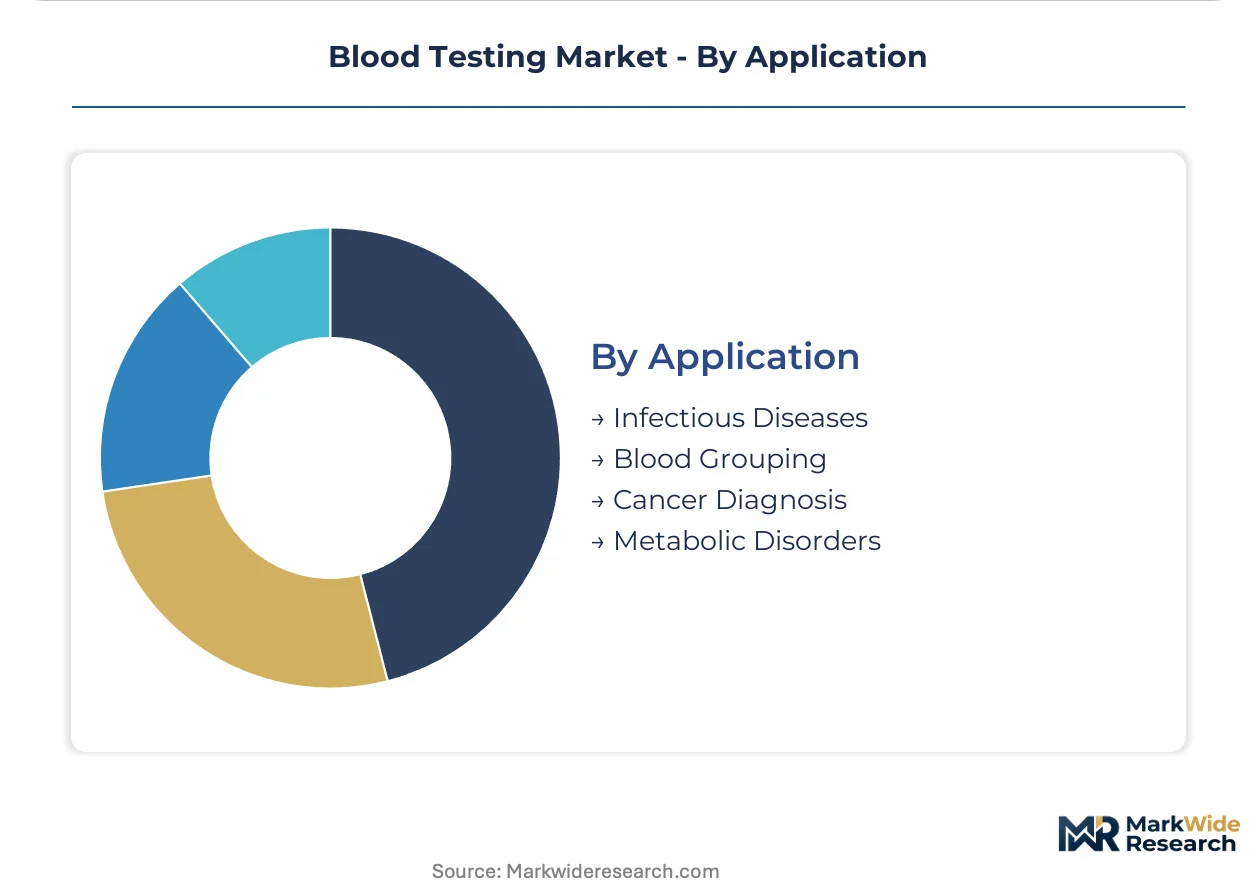
Application:
Disease-specific testing protocols create sticky demand patterns where clinical guidelines institutionalize reorder frequency and panel composition.
- Infectious Diseases:Pathogen detection panels cover bacterial, viral, and parasitic targets through multiplexed nucleic acid and immunoassay methods. Emergency departments in the United States prioritize fifteen-minute turnaround for respiratory and bloodstream infection protocols.
- Metabolic Disorders:Diabetes and lipid management programs require quarterly HbA1c and lipid panel testing, generating recurring reagent consumption in German and French chronic care networks.
- Cancer Diagnosis:Tumor marker quantification supports screening, staging, and therapeutic monitoring across oncology service lines.
- Blood Grouping:Serological and molecular methods determine ABO/Rh type and antibody screen status for transfusion safety.
Test volumes concentrate in infectious diseases; metabolic disorders show the fastest climb as population aging expands chronic disease prevalence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital laboratories in the United States and German reference facilities concentrate the highest analytical throughput volumes, while India's CDSCO pathway and China's NMPA reforms are redrawing manufacturer entry economics across Asia-Pacific.
United States
FDA's tightened 21 CFR Part 820 enforcement drives hospital laboratories toward integrated analyzer platforms with embedded quality control modules. CLIA certification tiers stratify test complexity, determining which procedures hospitals, reference labs, or physician offices may perform. Greater Boston and the Research Triangle anchor automated hematology and immunoassay workflow expansions as health systems absorb seven-figure capital commitments.
Germany
EMA-aligned reference laboratories and Siemens Healthineers' domestic manufacturing base anchor European test standardization under EU IVDR obligations. Stricter post-market surveillance mandates extend certification timelines and elevate documentation costs for CE-marked devices. The Rhine-Ruhr and Munich-Stuttgart corridors concentrate specialized antibody and enzyme suppliers, creating procurement gravity for immunoassay manufacturers.
France
Hospital procurement departments unbundle analyzer hardware from reagent supply agreements, reversing decade-long bundled pricing conventions. ANSM oversight aligns with EMA protocols for in vitro diagnostic quality systems. The Paris-Saclay cluster and Lyon biotech corridor drive demand for extended stability data and traceability matrices as procurement prerequisites.
India
CDSCO's fast-track pathway for Class B and C in vitro diagnostics accelerates market entry for mid-complexity assays. Maharashtra and Karnataka host contract research organizations validating novel biomarker protocols for multinational manufacturers. Mumbai and Bangalore laboratories absorb point-of-care infectious disease screening devices as retail clinic chains expand beyond hospital networks.
China
NMPA's streamlined approval for innovative in vitro diagnostics compresses timelines for domestic manufacturers while elevating evidence requirements for imported devices. Yangtze River Delta and Pearl River Delta production clusters supply microfluidics components and cartridge-based systems. Shanghai and Shenzhen drive miniaturization research as point-of-care devices shrink sample requirements below 100 microliters.
Blood Testing Market Vendor Landscape
United States producers anchor one tier through vertically integrated immunoassay manufacturing and deep automation expertise; German and Swiss specialists hold another through precision hematology platforms and reagent standardization. The structure bifurcates between scaled platform operators absorbing capital budgets and reagent-dependent specialists vulnerable to supply concentration. Three archetypes dominate: integrated diagnostic conglomerates, precision instrument specialists, and reference laboratory consolidators. Competitive moves center on analyzer-IT integration partnerships and disaggregated service contracts that break OEM maintenance captivity.
Within the integrated diagnostic tier, Abbott Laboratories exemplifies vertically stacked immunoassay production sustaining compliance economies that smaller rivals cannot match. Siemens Healthineers AG occupies a position anchored in German automation expertise deployed across hospital networks. Danaher Corporation represents the precision instrument archetype through its life sciences portfolio structure. These three entities sit within distinct competitive vectors—Abbott through reagent recurring revenue, Siemens through platform standardization, Danaher through acquisition-driven portfolio breadth—yet all confront identical IVDR documentation burdens and FDA quality-system tightening.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Quest Diagnostics Incorporated |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific Inc. |
| bioMérieux |
| Others |
Supply Flow & Price Mechanics
Specialized antibody engineering talent clustering in the Basel-Zurich corridor and southern Germany creates labor-cost differentials that widen pricing-tier spreads between premium CE-IVD certified platforms and economy-grade instruments.
Pricing Analysis
Volume placements concentrate in mid-tier standard analyzers while margins pool in premium platforms with embedded quality control modules. Pricing stratifies across premium, standard, and economy tiers based on FDA Class III versus Class II certification levels and after-sales service bundling. Cost compression in economy segments is intensifying because hospital procurement departments now unbundle hardware from reagent agreements. Reference laboratories show least price sensitivity; mid-tier hospitals face greatest budget constraints.
Supply Chain Analysis
EU IVDR local-content requirements for technical documentation and post-market surveillance are reshaping sourcing toward European-based notified body relationships and regional stability testing facilities. Specialized enzymes and monoclonal antibodies draw from Switzerland, Germany, and the United States. Supply chain risk centers on single-source vulnerability for rare earth magnets in hematology analyzer flow cytometry modules. Distribution runs through hospital GPO contracts and reference laboratory direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints for EU IVDR technical documentation reviews prop pricing power for manufacturers with existing CE certificates, creating supply-constrained dynamics that favor incumbents with regulatory backlogs already cleared.
For Market Incumbents: Deepen backward integration into specialized reagent production to offset supply concentration risks in Swiss and German enzyme suppliers. Expand service organization capabilities to capture maintenance contracts disaggregated from OEM agreements, defending against independent service competitors.
For New Entrants and Emerging Players: Begin with India's CDSCO fast-track pathway for Class B and C diagnostics to establish manufacturing scale before tackling FDA or EU IVDR submissions. Target point-of-care infectious disease screening in retail clinic chains as the most penetrable segment, leveraging cartridge-based microfluidics to bypass capital-intensive analyzer competition.
For Investors and Strategic Acquirers: Re-rating potential sits with precision instrument specialists possessing IVDR-ready technical documentation given the certification backlog facing legacy immunoassay portfolios. Long-term viability favors acquisition targets with established hospital system partnerships and embedded software companion development capabilities. Watch for inflection when notified body capacity expansion clears documentation backlogs.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR compliance accelerates market access for manufacturers with notified body relationships in Germany. |
| Hospital System Partnership | Integrated analyzer placements with GPO contracts lock in recurring reagent revenue across US networks. |
| Software Companion Development | AI-enabled cell morphology analysis creates premium pricing tiers for hematology platforms. |
| Backward Integration | In-house antibody production reduces single-source vulnerability from Swiss and German suppliers. |
| Reimbursement Strategy | Home-based coagulation monitoring protocols expand eligibility for patient-operated INR devices. |
Methodological Framework
Multi-period observation of FDA 510(k) submission volumes, EU IVDR certificate issuance rates, and hospital capital expenditure disclosures anchored the trend analysis, supplemented by interviews with regulatory affairs directors, hospital laboratory managers, GPO contract specialists, and biomedical engineers. Secondary validation drew from FDA 510(k) databases, EUDAMED vigilance reports, hospital procurement databases, and CMS Medicare laboratory fee schedule data. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
The input-output matrix framed projections across product type, technology platform, end-user setting, and application area dimensions throughout the forecast period. CAGRs derived from regression analysis against historical placement rates and regulatory timeline compression. Forecast inputs incorporated CLIA certification tier expansions and IVDR notified body capacity constraints.
Underlying measurement precision varies by segment; immunoassay and hematology analyzer volumes carry tighter precision than emerging microfluidics categories. Forecasts reflect documented assumptions about regulatory timeline adherence and reimbursement stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
US Viral Clearance Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Home Menopause Testing Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Addison Disease Testing Market