
 Rickets Market | 2026-2036
Rickets Market Size, Share, and Industry Trends Forecast 2026-2036
Rickets Market Outlook
Aftermarket service revenue from patient monitoring and compliance programs is reshaping how nutritional therapy vendors capture lifetime value. Abbott Laboratories leverages its pediatric nutrition infrastructure to sustain high-touch distribution in emerging markets. Fresenius Kabi anchors hospital channel supply for injectable vitamin D formulations. GlaxoSmithKline competes through broad-spectrum multivitamin portfolios that span prescription and over-the-counter access points.
Rickets denotes a skeletal mineralization disorder arising from vitamin D, calcium, or phosphate deficiency, characterized by defective cartilage calcification at growth plates and progressive bone deformities; laboratory diagnosis thresholds typically require serum 25-hydroxyvitamin D below 20 ng/mL alongside elevated alkaline phosphatase. Vitamin D supplements occupy the dominant product category due to direct etiological targeting and low-cost manufacturing via ergocalciferol and cholecalciferol synthesis. Injectable treatment methods represent the fastest-growing segment as severe deficiency cases in pediatric populations require rapid correction bypassing gastrointestinal absorption limitations.
FDA orphan drug designations and WHO Essential Medicines List inclusion govern product registration pathways and procurement eligibility for severe rickets therapies. EMA pediatric investigation plans mandate age-appropriate formulation development, while national regulators such as India's CDSCO enforce local stability testing for imported vitamin products. Stakeholders must monitor evolving fortification mandates and reimbursement tier shifts that will determine competitive access across public health procurement systems.
Market Dynamics
The WHO vitamin D fortification guidelines are compressing formulation standards across national health systems, forcing suppliers to recalibrate product portfolios for procurement eligibility while pediatric screening expansion in South Asia pulls volume toward preventive supplementation models.
Growth Catalysts
- India's BIS fortification mandates:Compulsory food fortification standards for edible oils and milk are institutionalizing vitamin D distribution channels through public distribution systems.
- Injectable cholecalciferol synthesis:Advances in lipid-based parenteral formulations are enabling rapid correction of severe deficiency in malabsorption cases.
- Pediatric end-user concentration:School-based screening programs in high-burden districts are converting latent deficiency into diagnosed demand.
Market Restraints
- API supply concentration:Bulk vitamin D3 (cholecalciferol) production clusters in Chinese chemical manufacturing zones, creating single-source vulnerability.
- Stability testing requirements:India's CDSCO mandates local accelerated degradation studies for imported formulations, extending registration timelines.
- Oral formulation substitution:Low-cost calcium-vitamin D combinations in retail pharmacy channels compete with standalone therapeutic dosing.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:WHO Essential Medicines List inclusion for severe rickets therapies creates procurement pathway for hospital-grade injectables.
- Point-of-care diagnostics convergence:Lateral flow 25-hydroxyvitamin D assays combined with mobile health platforms enable decentralized screening.
- Europe's CSRD sustainability disclosure:Fortified food manufacturers gain procurement preference in institutional catering contracts.
Industry Challenges
- Pediatric formulation expertise gap:Age-appropriate palatable dosage forms require specialized excipient knowledge scarce in generic API suppliers.
- EMA pediatric investigation timelines:PIP compliance for novel delivery systems extends development cycles before market authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rickets Market |
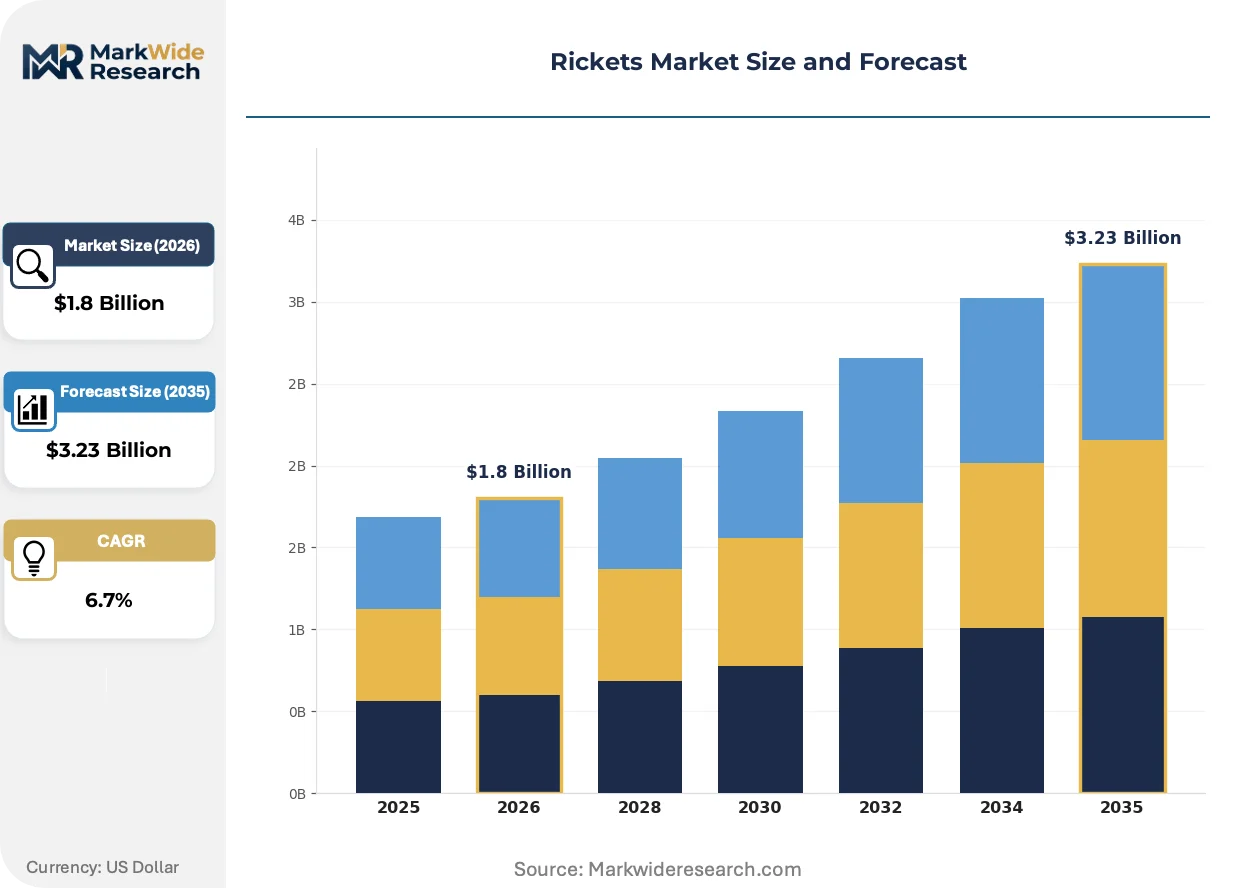
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin D Supplements, Calcium Supplements, Multivitamins, Prescription Medications End User: Pediatric Patients, Adult Patients, Healthcare Providers, Caregivers Diagnosis Type: Blood Tests, X-Rays, Bone Density Scans, Genetic Testing Treatment Method: Oral Treatment, Injectable Treatment, Nutritional Therapy, Surgical Interventions |
| Companies Covered | Abbott Laboratories, Fresenius Kabi, GlaxoSmithKline, Chiesi Farmaceutici, Bayer AG, Pfizer, Merck & Co., Enzymotec, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rickets Market Strategic Shifts
Formulation science and diagnostic integration are converging to shift rickets management from hospital-based correction toward community-level prevention, rewiring how nutritional therapies reach at-risk pediatric populations.
Nanoemulsion-based vitamin D delivery is hybridizing oral bioavailability enhancement with thermostable packaging requirements. Pediatric nutrition manufacturers in tropical climates are adopting lipid-nanoparticle carriers to reduce degradation during ambient-temperature distribution. This convergence is compressing the efficacy gap between pharmaceutical-grade supplements and commodity fortificants.
REACH authorization requirements for novel excipients in parenteral formulations are tightening supply qualification protocols. European manufacturers must submit extended toxicity dossiers for lipid solvents used in injectable vitamin D products. Hospital procurement committees are responding by consolidating supplier lists around pre-qualified formulation houses.
Aftermarket compliance monitoring is displacing transactional supplement sales with subscription-based adherence programs. Pediatric clinics in urban Indian health systems are bundling diagnostic testing with automated refill services. This pattern concentrates lifetime value capture among vendors with integrated patient management infrastructure.
Rickets Market Segmentation
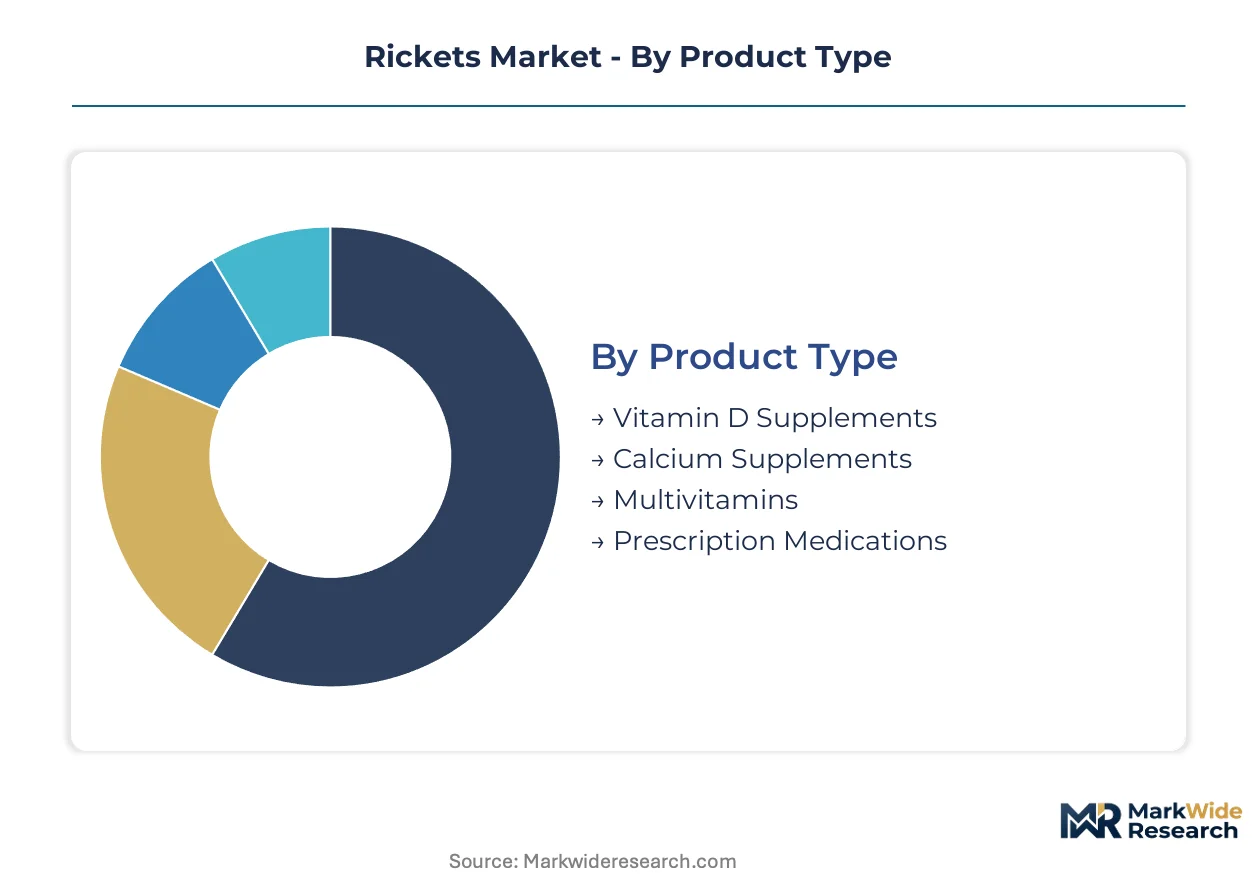
Rickets treatment markets fragment across four distinct category axes, each commanding different service intensity models. Pediatric nutrition programs demand sustained compliance monitoring, while diagnostic pathways require integrated laboratory partnerships.
Product Type:
Aftermarket service intensity varies sharply across product categories, with prescription formulations requiring pharmacovigilance programs that commodity supplements avoid.
- Vitamin D Supplements:Ergocalciferol and cholecalciferol formulations dominate procurement volumes through direct etiological targeting. India's public distribution systems channel these through Anganwadi centers and school health programs, with BIS-mandated fortification standards compressing supplier margins.
- Injectable Treatment:Lipid-based parenteral cholecalciferol enables rapid correction in severe malabsorption cases, particularly among pediatric populations with cystic fibrosis or biliary atresia. Hospital procurement committees in Delhi and Mumbai are consolidating supplier lists around pre-qualified formulation houses capable of cold-chain integrity.
- Calcium Supplements:Carbonate and citrate salts serve as adjunctive therapy, with retail pharmacy substitution eroding therapeutic dosing compliance.
- Multivitamins:Broad-spectrum portfolios span prescription and over-the-counter access points, with GlaxoSmithKline competing through combined vitamin D-calcium positioning.
- Prescription Medications:High-potency D2 and active metabolite formulations require specialized compounding infrastructure concentrated in hospital pharmacy networks.
By volume, Vitamin D Supplements leads. By growth pace, Injectable Treatment is ahead.
End User:
Customer archetypes determine pricing architecture, with institutional procurement favoring annual contracts and retail channels absorbing spot-market volatility.
- Pediatric Patients:School-based screening programs in high-burden districts convert latent deficiency into diagnosed demand. WHO Essential Medicines List inclusion for severe rickets therapies creates procurement pathways for hospital-grade injectables in Sub-Saharan Africa.
- Healthcare Providers:Pediatric clinics in urban Indian health systems bundle diagnostic testing with automated refill services, concentrating lifetime value capture among vendors with integrated infrastructure.
- Adult Patients:Malabsorption syndromes and chronic kidney disease drive maintenance therapy, with nephrology practices in Chennai and Hyderabad anchoring specialty prescribing.
- Caregivers:Home administration of oral supplements depends on palatability engineering and dosing compliance tools, with Abbott Laboratories leveraging pediatric nutrition infrastructure for high-touch distribution.
By patient volume, Pediatric Patients dominates. By service revenue per case, Healthcare Providers extracts premium capture.
Diagnosis Type:
Diagnostic modality selection follows disease severity staging, with point-of-care convergence compressing traditional laboratory referral patterns.
- Blood Tests:Serum 25-hydroxyvitamin D quantification remains the reference standard, with thresholds below 20 ng/mL triggering therapeutic intervention alongside elevated alkaline phosphatase confirmation.
- X-Rays:Radiographic assessment of growth plate deformities serves confirmatory staging in established disease, particularly for wrist and knee epiphyseal evaluation.
- Bone Density Scans:DEXA utilization concentrates in tertiary referral centers assessing fracture risk in adolescent populations with prolonged deficiency.
- Genetic Testing:Hereditary hypophosphatemic rickets subtypes require specialized endocrinology workup, with testing volume constrained to academic medical centers in Bangalore and Pune.
By test frequency, Blood Tests leads. By diagnostic yield per dollar, X-Rays retains cost efficiency.
Treatment Method:
Delivery channel selection reflects absorption physiology and severity stratification, with parenteral routes commanding hospital-based revenue pools.
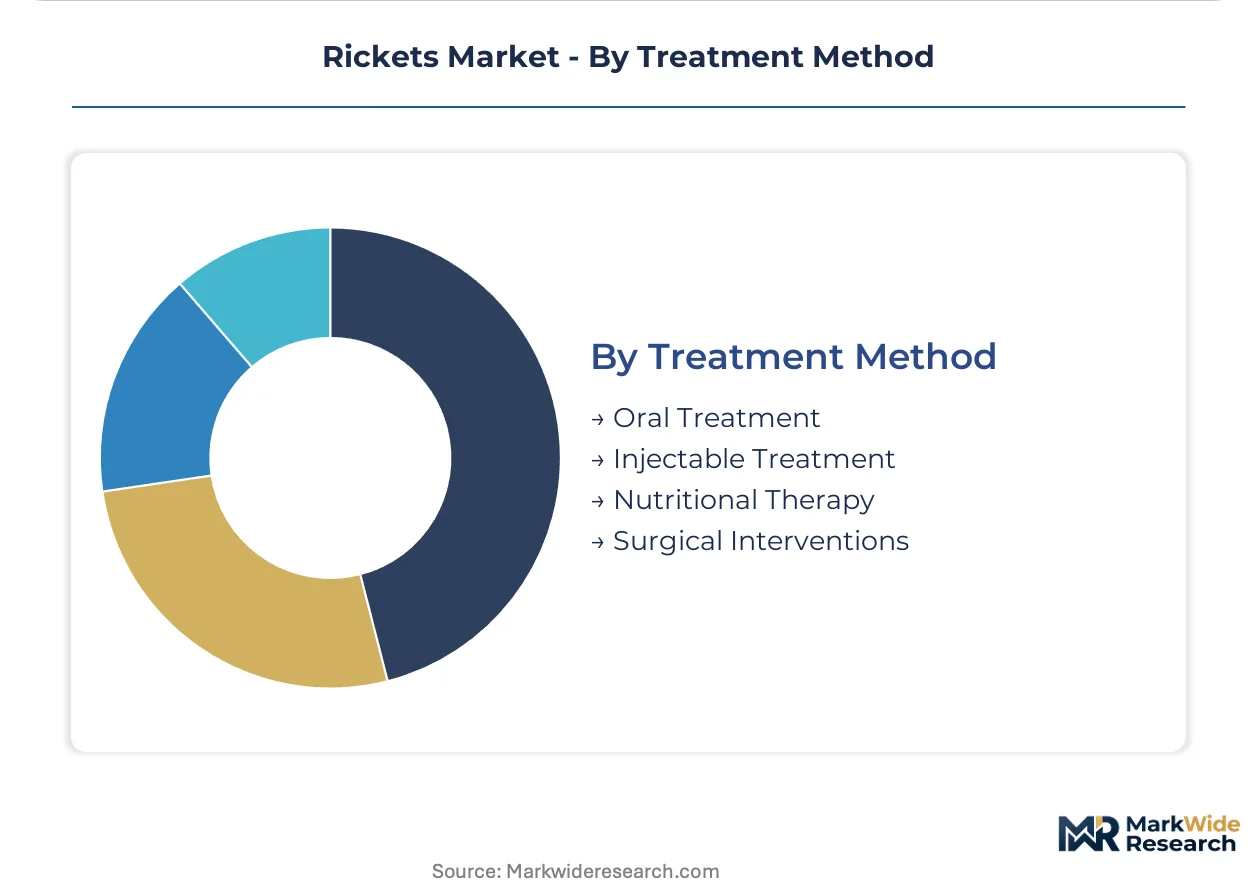
- Injectable Treatment:Rapid correction bypasses gastrointestinal limitations in severe deficiency, with EMA pediatric investigation plans mandating age-appropriate formulation development that extends authorization timelines.
- Nutritional Therapy:Fortified food distribution through India's public distribution systems institutionalizes preventive supplementation, with BIS standards for edible oils and milk creating procurement scale.
- Oral Treatment:First-line maintenance therapy faces retail substitution pressure from low-cost calcium-vitamin D combinations.
- Surgical Interventions:Orthopedic correction of established deformities concentrates in pediatric specialty hospitals, with volume limited to refractory cases.
By procedure count, Oral Treatment leads. By value per episode, Injectable Treatment commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in rickets treatment varies sharply by geography. India's public distribution systems absorb high volumes at compressed margins, while European hospital procurement sustains premium positioning for specialized formulations.
India
School-based screening programs in high-burden districts convert latent deficiency into diagnosed demand. BIS fortification mandates for edible oils and milk institutionalize vitamin D distribution through public channels. Pediatric clinics in Delhi and Mumbai bundle diagnostic testing with automated refill services.
United States
FDA orphan drug designations govern registration pathways for severe rickets therapies targeting pediatric populations. Medicaid reimbursement tiers determine competitive access across state health systems. Hospital procurement committees in Boston and Philadelphia anchor specialty prescribing for high-potency formulations.
Germany
EMA pediatric investigation plans mandate age-appropriate formulation development before market authorization. REACH authorization requirements for novel excipients tighten supply qualification protocols for lipid-based parenteral products. Formulation houses in Baden-Württemberg consolidate around pre-qualified supplier status.
Brazil
ANVISA registration timelines for imported vitamin products extend market entry for foreign manufacturers. Retail pharmacy substitution of low-cost calcium-vitamin D combinations competes with standalone therapeutic dosing. São Paulo-based distributors channel volume through institutional catering contracts.
United Kingdom
NHS procurement frameworks for pediatric nutrition programs concentrate demand among vendors with integrated patient management infrastructure. MHRA stability testing requirements for imported formulations extend registration timelines. London health systems pilot subscription-based adherence programs bundling diagnostics with automated refills.
Rickets Market Competitive Environment
Capability concentration sits with formulation specialists possessing pediatric expertise; scale advantage sits with diversified nutrition and pharmaceutical conglomerates. The market structures around three tiers: global nutrition houses with high-touch distribution infrastructure, hospital-channel suppliers of injectable formulations, and broad-spectrum multivitamin portfolios spanning prescription and over-the-counter access. Dominant competitive moves include backward integration into API supply and geographic expansion through public health procurement systems.
Among diversified pharmaceutical conglomerates, Abbott Laboratories and GlaxoSmithKline exemplify scale-driven positioning. Abbott leverages pediatric nutrition infrastructure for high-touch distribution in emerging markets. GlaxoSmithKline competes through combined vitamin D-calcium portfolio positioning across access points. Fresenius Kabi occupies a distinct tier anchoring hospital-channel supply for parenteral formulations.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Fresenius Kabi |
| GlaxoSmithKline |
| Chiesi Farmaceutici |
| Bayer AG |
| Pfizer |
| Merck & Co. |
| Enzymotec |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Mumbai maritime corridor's freight cost dynamics compress margins for vitamin D API importers while amplifying price differentiation between hospital-grade injectables and commodity oral supplements. Indian public distribution systems absorb volume at standardized tender rates, whereas European hospital procurement sustains premium positioning for lipid-based parenteral formulations through cold-chain integrity requirements.
Pricing Analysis
Aftermarket service revenue from patient compliance programs and automated refill subscriptions drives lifetime value capture for nutritional therapy vendors. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and distribution channel control. Cost compression in the oral supplement segment intensifies as low-cost calcium-vitamin D combinations flood retail pharmacy channels. Pediatric clinics and hospital procurement committees demonstrate the widest price sensitivity gap, with institutional buyers negotiating annual contracts while caregivers absorb spot-market volatility for home-administered therapies.
Supply Chain Analysis
Single-source vulnerability in Chinese chemical manufacturing zones for bulk cholecalciferol API dominates supply chain risk assessments for formulation houses. Active pharmaceutical ingredient production clusters in China, India, and Germany, with lipid-nanoparticle excipient supply anchored in European specialty chemical producers. Parenteral formulation development hinges on REACH-authorized solvent qualification protocols that extend supplier onboarding timelines. Distribution runs through hospital pharmacy networks for injectable products and Anganwadi center channels for fortified food commodities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern driven by WHO fortification guideline adoption waves that institutionalize procurement volume through national health systems.
For Market Incumbents: Insulate market position through backward integration into API supply and captive production of lipid-based excipients to offset Chinese manufacturing concentration risk. Pediatric formulation expertise and pre-qualified supplier status with EMA pediatric investigation plans serve as defensive moats against generic substitution pressure. For New Entrants and Emerging Players: Establish a beachhead in Sub-Saharan Africa hospital-grade injectable procurement pathways created by WHO Essential Medicines List inclusion for severe rickets therapies. Point-of-care diagnostic convergence with mobile health platforms offers the most penetrable go-to-market angle for decentralized screening bundled with supplementation compliance programs. For Investors and Strategic Acquirers: Formulation specialists with EMA pediatric investigation plan completion and tropical-climate stability testing capabilities represent priority acquisition targets. Long-term viability hinges on 5-10 year public health procurement contract visibility rather than retail pharmacy channel dependence. The signal to watch is BIS fortification mandate expansion into additional food categories beyond edible oils and milk.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Completion | Accelerates market authorization timelines for novel lipid-based parenteral formulations targeting malabsorption cases. |
| Backward Integration into API Supply | Reduces single-source vulnerability from Chinese cholecalciferol manufacturing concentration. |
| WHO Essential Medicines List Procurement Pathway | Unlocks hospital-grade injectable demand in underpenetrated Sub-Saharan African markets. |
| Point-of-Care Diagnostic Platform Integration | Enables decentralized screening convergence with automated refill subscription models. |
| REACH Excipient Authorization Investment | Qualifies suppliers for European hospital procurement committee pre-approved vendor lists. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of CDSCO registration filings, BIS fortification standards documentation, and WHO guideline repositories. Pediatric nutrition program directors, hospital pharmacy procurement managers, and regulatory affairs leads at formulation houses provided operational validation. Bottom-up demand modeling from Anganwadi center distribution data triangulates against top-down pharmaceutical procurement spend analysis.
Forecast inputs incorporate patient screening expansion rates, fortification mandate enforcement timelines, and parenteral formulation authorization progressions across the analysis window. Segmentation dimensions span product type, end-user archetype, diagnosis modality, and treatment delivery method. CAGRs derive from volume trajectory analysis anchored in public health procurement contract visibility and pediatric population demographic projections.
Sensitivities concentrate around BIS mandate expansion scope, EMA pediatric investigation plan approval velocity, and Chinese API supply disruption scenarios. Forecasts reflect assumptions about regulatory enforcement consistency and procurement budget continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Bone Spur Market
Orthopedics
US Arthritis Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Costochondritis Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Tendon Repair Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Orthopedics Market