
 Costochondritis Market | 2026-2036
Costochondritis Market Size, Share, and Industry Trends Forecast 2026-2036
Costochondritis Market Intelligence
Biologic delivery platforms is reconfiguring how anti-inflammatory therapies reach costochondrial tissue, enabling targeted drug release with reduced systemic exposure. Pfizer Inc leverages its respiratory and pain portfolio to sustain clinical relevance across outpatient settings. Novartis AG anchors its position through specialized inflammation research programs. AbbVie Inc differentiates via immunology expertise that extends into musculoskeletal pain management.
Costochondritis denotes inflammation of the costochondral junctions connecting ribs to the sternum, typically presenting with reproducible chest wall tenderness and pain exacerbated by movement or palpation. The condition primarily serves to distinguish benign musculoskeletal pain from cardiac etiologies in acute care and primary care settings. Anti-inflammatory medications dominate current treatment flows due to established efficacy profiles and broad prescriber familiarity. Physical therapy represents the fastest-expanding segment as payers favor non-pharmacological interventions amid opioid scrutiny. Imaging tests maintain stable utilization for ruling out pulmonary or cardiac pathologies in atypical presentations.
The FDA shapes pharmaceutical development through bioequivalence requirements for generic NSAID formulations, while the EMA's pharmacovigilance frameworks influence safety labeling across European markets. The WHO's essential medicines list indirectly guides procurement priorities in emerging health systems. Stakeholders must monitor evolving reimbursement criteria for interventional pain procedures versus conservative management protocols.
Market Dynamics
Biologic delivery platforms are reconfiguring how anti-inflammatory therapies reach costochondrial tissue, compressing development timelines for targeted formulations while reducing systemic exposure concerns that have constrained prescriber confidence in conventional NSAID protocols.
Growth Catalysts
- Sports medicine clinic expansion:Athletes seeking non-surgical chest pain management are driving protocol adoption across specialized rehabilitation centers in Germany and the United States.
- FDA bioequivalence pathways:Streamlined approval frameworks for generic topical NSAID formulations are accelerating product pipeline velocity and market entry.
- Multimodal therapy integration:Specialized pain management centers in Germany are consolidating patient flows through combined pharmacological and physical intervention protocols.
Market Restraints
- Opioid substitution scrutiny:Heightened regulatory surveillance of pain medication prescribing patterns creates prescriber hesitation and documentation burden.
- Diagnostic imaging cost structures:Mandatory chest radiography and cardiac workups for atypical presentations inflate episode costs and extend care pathways.
- Physical therapy reimbursement compression:Payer tightening on non-pharmacological intervention codes limits provider margin and session authorization.
Strategic Opportunities
- Transdermal patch innovation:Sustained-release formulations targeting costochondrial tissue penetration offer differentiation from oral NSAID commoditization.
- Telehealth diagnostic protocols:Remote chest wall examination algorithms are expanding access to specialized assessment in underserved rural geographies.
- EMA pharmacovigilance alignment:Early adoption of European safety labeling standards positions products for streamlined cross-border registration.
Industry Challenges
- Palpation skill standardization:Inconsistent physical examination training across primary care networks yields diagnostic delay and inappropriate cardiac referrals.
- Biologic manufacturing scale-up:Tissue-targeted delivery platforms require specialized production infrastructure with limited contract manufacturing availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Costochondritis Market |
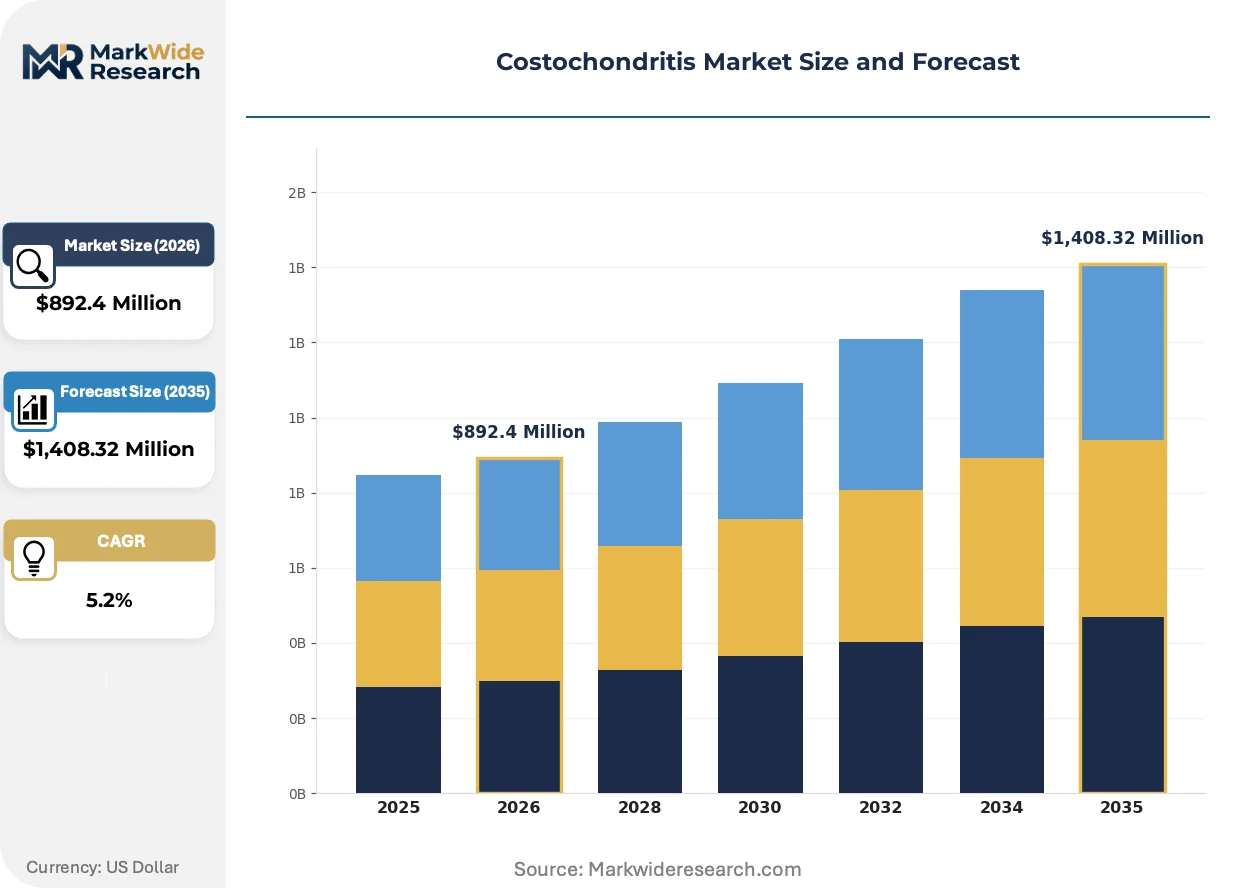
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,408.32 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Physical Therapy, Anti-inflammatory Medications, Steroid Injections, Heat Therapy Diagnosis Method: Physical Examination, Imaging Tests, Blood Tests, Electrocardiogram Severity Level: Mild, Moderate, Severe, Chronic Patient Demographics: Adults, Teenagers, Elderly, Athletes |
| Companies Covered | Novartis AG, AbbVie Inc, Pfizer Inc, Sanofi S.A., Amgen Inc, Johnson & Johnson, Bristol-Myers Squibb Company, AstraZeneca PLC, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Costochondritis Market Strategic Shifts & Innovations
Digital diagnostic tools are compressing the gap between initial presentation and definitive musculoskeletal diagnosis, reducing unnecessary cardiac workups while redirecting patient flows toward appropriate conservative management channels.
Ultrasound-guided injection systems is digitizing precision targeting of costochondral junctions, enabling real-time visualization of inflammatory tissue. Sports medicine specialists and interventional pain clinics are adopting these platforms at accelerating rates. The technology is digitizing procedure standardization while reducing complication rates and repeat intervention frequency.
The FDA's evolving guidance on topical NSAID bioequivalence is forcing reformulation investments across generic portfolios. Manufacturers must demonstrate comparable tissue penetration profiles to reference listed drugs. Dermatology-focused sponsors with existing topical expertise are capturing disproportionate share of abbreviated new drug application approvals.
Patient-initiated diagnostic pathways are displacing traditional primary care gatekeeping for chest wall pain. Direct-to-specialist booking platforms and sports medicine direct access laws are compressing referral cycles. This pattern is most visible in Germany and select United States markets with mature physical therapy autonomy frameworks.
Costochondritis Market Segmentation
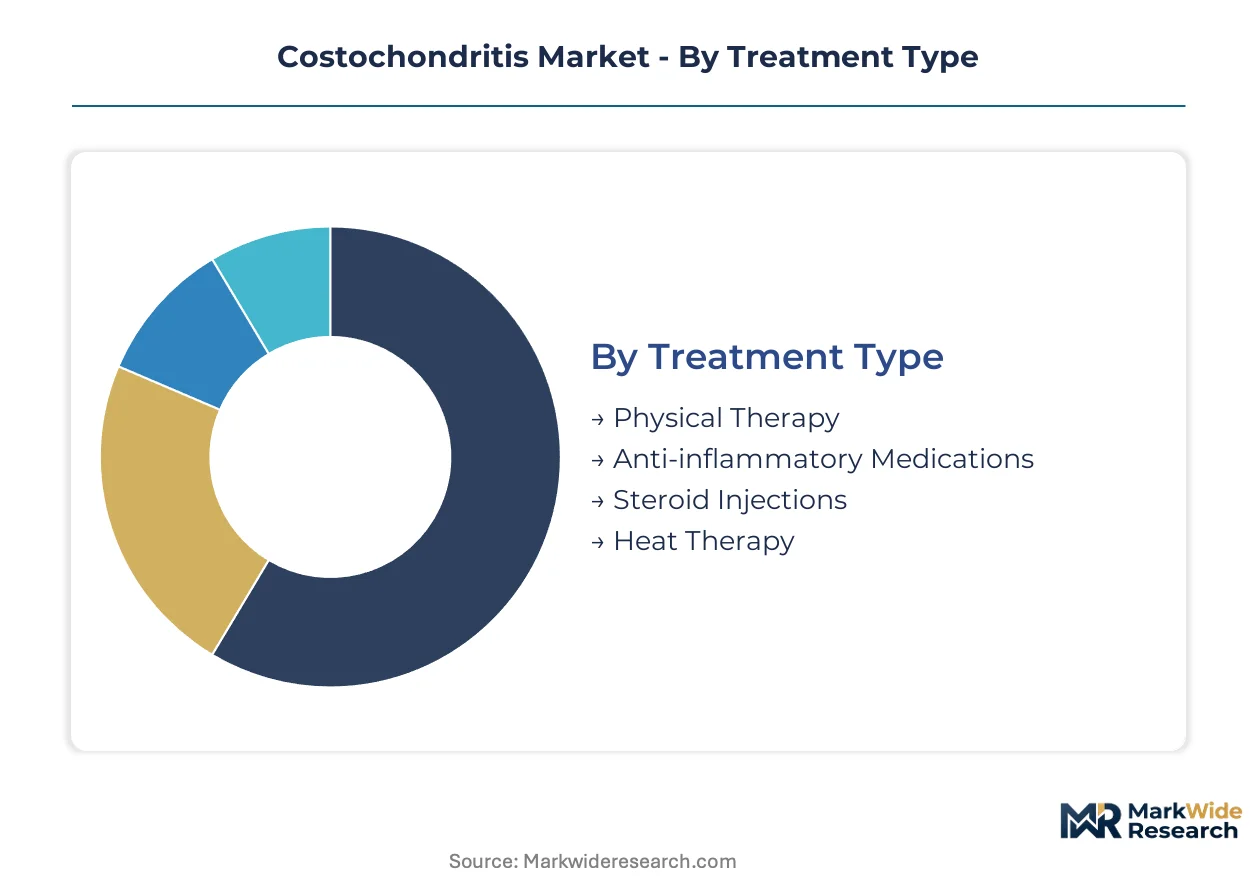
Costochondritis treatment pathways fragment sharply across clinical settings, with prescriber specialty and patient presentation driving divergent product selection. Segmentation clarity enables manufacturers to align formulation development with reimbursement codes and prescriber workflow preferences.
Treatment Type:
Use-case spectrum spans acute symptom suppression through long-term functional restoration, with payer preference shifting toward non-pharmacological protocols.
- Physical Therapy:Manual mobilization protocols and thoracic spine manipulation target mechanical dysfunction at the costochondral junction. Demand concentrates in German sports medicine clinics and United States outpatient rehabilitation centers as insurers expand authorization for conservative management codes.
- Anti-inflammatory Medications:Oral NSAIDs and topical formulations remain the default first-line intervention across primary care networks. Prescribing volume clusters in the United States where FDA bioequivalence pathways for generic topical products accelerate formulary access.
- Steroid Injections:Corticosteroid delivery to costochondral junctions addresses refractory cases unresponsive to conservative measures.
- Heat Therapy:Thermal modalities support home-based symptom management with minimal clinical supervision requirements.
Established volume favors Anti-inflammatory Medications; emerging adoption favors Physical Therapy.
Diagnosis Method:
Cost tier separates rapid clinical assessment from technology-intensive exclusion protocols.
- Physical Examination:Palpation-based diagnosis of reproducible chest wall tenderness remains the clinical standard. Utilization concentrates in German primary care networks where standardized musculoskeletal training reduces unnecessary cardiac referrals.
- Imaging Tests:Chest radiography and CT protocols rule out pulmonary or cardiac pathology in atypical presentations. Demand clusters in United States emergency departments where defensive medicine pressures inflate diagnostic workup intensity.
- Blood Tests:Inflammatory marker panels assist differential diagnosis when systemic conditions are suspected.
- Electrocardiogram:Cardiac exclusion protocols dominate acute chest pain triage pathways regardless of pre-test probability.
Cost efficiency favors Physical Examination; defensive medicine protocols favor Imaging Tests.
Severity Level:
Application intensity escalates from self-managed episodes to interventional pain clinic referrals.
- Mild:Self-limiting presentations resolve with activity modification and over-the-counter analgesia. Volume concentrates in United States retail clinic settings where nurse practitioners manage uncomplicated cases.
- Moderate:Persistent symptoms requiring prescription intervention and structured physical therapy protocols. Adoption clusters in German multimodal pain centers integrating pharmacological and rehabilitative approaches.
- Severe:Functionally limiting pain necessitating specialist referral and possible interventional procedures.
- Chronic:Recalcitrant cases exceeding standard treatment timelines drive pain clinic consultation.
Episode volume favors Mild presentations; margin concentration favors Chronic cases.
Patient Demographics:
Customer type determines channel strategy and messaging emphasis.
- Adults:Working-age presentations linked to occupational ergonomic stress or post-viral inflammation. Demand concentrates in United States employer-sponsored health plans where productivity-focused return-to-work protocols drive physical therapy authorization.
- Athletes:Sports-specific chest wall mechanics create distinct injury patterns requiring specialized rehabilitation. Volume clusters in German sports medicine clinics and United States collegiate athletic programs with embedded physical therapy resources.
- Teenagers:Adolescent presentations often associate with growth-related mechanical stress or postural factors.
- Elderly:Age-related diagnostic complexity requires careful cardiac exclusion before musculoskeletal attribution.
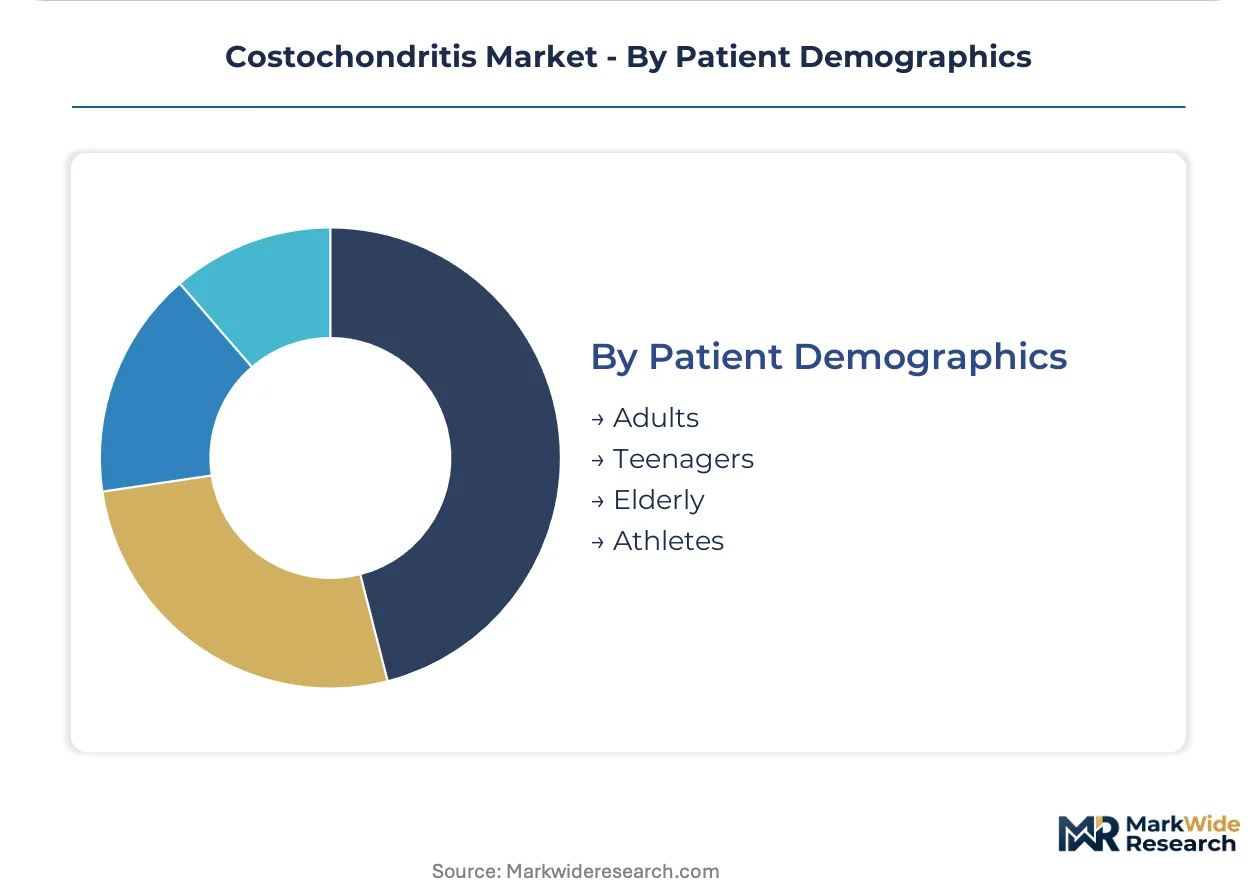
Commercial priority favors Adults; specialized service margin favors Athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for specialized pain management devices runs highest in markets with limited domestic manufacturing infrastructure. Export competitiveness concentrates in jurisdictions with established pharmaceutical formulation capabilities and streamlined regulatory pathways.
United States
FDA bioequivalence pathways for topical NSAID formulations accelerate generic product pipeline velocity. Sports medicine clinic expansion across Texas and Florida drives demand for non-surgical chest pain protocols. The Cleveland Clinic and Mayo Clinic anchor specialized rehabilitation networks integrating multimodal therapy approaches.
Germany
Specialized pain management centers in Bavaria and North Rhine-Westphalia consolidate patient flows through combined pharmacological and physical intervention protocols. EMA pharmacovigilance frameworks influence safety labeling standards adopted by domestic manufacturers. Berlin hosts concentration of musculoskeletal research institutes advancing diagnostic standardization.
United Kingdom
NHS England reimbursement tightening on non-pharmacological intervention codes limits provider margin authorization. MHRA alignment with EMA standards streamlines cross-border product registration for topical formulation sponsors. London and Manchester cluster interventional pain clinics serving refractory costochondritis cases.
Japan
PMDA review timelines for novel transdermal delivery platforms extend development cycles for tissue-targeted formulations. METI industrial policy supports domestic manufacturing of precision injection systems. Osaka and Tokyo metropolitan areas concentrate sports medicine facilities adopting ultrasound-guided intervention technologies.
Australia
TGA approval pathways for biologic delivery platforms require localized clinical evidence generation. Rural telehealth diagnostic protocols expand access to specialized chest wall assessment beyond metropolitan centers. Sydney and Melbourne anchor private pain management networks serving athlete populations.
Costochondritis Market Key Industry Players
On the supply side, the industry is consolidating around pharmaceutical incumbents with established inflammation portfolios and emerging device specialists with targeted delivery expertise. Tiered competitive dynamics separate mass-market oral NSAID manufacturers from premium-positioned topical formulation sponsors. Three archetypes dominate: diversified pharmaceutical conglomerates, dermatology-focused topical specialists, and interventional device innovators. Capacity expansion in transdermal manufacturing and strategic partnerships with sports medicine clinic networks represent the dominant competitive moves reshaping market access.
Within the diversified pharmaceutical tier, Pfizer Inc, Novartis AG, and AbbVie Inc occupy positions anchored by respiratory and pain portfolio breadth, specialized inflammation research programs, and immunology expertise extending into musculoskeletal applications respectively. These incumbents exemplify the scale-driven archetype leveraging existing prescriber relationships and formulary access to sustain clinical relevance across outpatient settings.
| Leading Market Players |
|---|
| Novartis AG |
| AbbVie Inc |
| Pfizer Inc |
| Sanofi S.A. |
| Amgen Inc |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| GlaxoSmithKline plc |
| Others |
Cost & Logistics Intelligence
North Rhine-Westphalia's concentration of specialized pain management device manufacturing compresses margins for downstream distributors while amplifying pricing power for topical formulation sponsors with FDA bioequivalence certifications. Generic oral NSAID commoditization runs deepest in United States retail channels where formulary access battles force cost absorption upstream.
Pricing Analysis
Next-generation biologic delivery platforms command substantial premiums over conventional oral NSAID formulations, while prior-generation topical creams face accelerating price erosion. Three-tier pricing structure across premium targeted-release patches, standard topical gels, and economy oral tablets dominates the landscape. Price differentiation hinges on FDA bioequivalence certification tier and sports medicine clinic endorsement status. Pricing pressure stems from German payer tightening on non-pharmacological intervention codes. Retail pharmacy chains exhibit highest price sensitivity; specialized pain management centers demonstrate lowest.
Supply Chain Analysis
United States export-control scrutiny on precision injection system components constrains flows to German and Japanese device assemblers. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland. Transdermal patch manufacturing draws from specialized polymer substrates, micro-needle arrays, and sustained-release matrices. Single-source vulnerability persists in ultrasound-guided injection system optics. Distribution runs through hospital procurement consortia and sports medicine clinic direct agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA bioequivalence pathway acceleration for topical NSAID formulations constitutes a regulatory inflection compressing development timelines and reshaping competitive entry economics. Biologic delivery platform maturation simultaneously threatens commoditized oral NSAID positions while opening premium pricing tiers.
For Market Incumbents: Entrench formulary access through vertical integration into transdermal manufacturing capacity in Bavaria and North Carolina production clusters. Defend against topical formulation specialists by accelerating FDA abbreviated new drug application filings. Prioritize certification investment in EMA pharmacovigilance alignment to streamline cross-border registration.
For New Entrants and Emerging Players: Pursue telehealth diagnostic protocol partnerships in Australian rural networks and United States collegiate athletic programs. White-space availability concentrates in ultrasound-guided injection system software layers and patient-initiated booking platforms. Go-to-market execution should anchor in sports medicine clinic direct access frameworks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dermatology-focused topical specialists with existing FDA bioequivalence expertise over diversified pharmaceutical conglomerates. Long-term viability hinges on tissue-targeted delivery platform differentiation rather than oral NSAID volume scale. Acquisition target archetype: transdermal manufacturing assets with specialized costochondrial penetration capabilities. Signal to watch: PMDA approval timeline compression for novel Japanese transdermal entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Abbreviated New Drug Application Acceleration | Streamlined bioequivalence pathways compress generic topical NSAID market entry timelines. |
| Transdermal Manufacturing Scale-Up | Specialized patch production capacity in Germany and United States secures supply security. |
| Sports Medicine Clinic Network Partnership | Direct access agreements with Texas and Florida rehabilitation centers bypass primary care gatekeeping. |
| EMA Pharmacovigilance Early Alignment | Proactive European safety labeling adoption enables streamlined cross-border product registration. |
| Ultrasound-Guided Injection Software Development | Real-time costochondral visualization algorithms differentiate interventional pain clinic offerings. |
Research Approach
A standing panel of sports medicine physicians, interventional pain specialists, formulary directors at United States employer-sponsored plans, and German multimodal therapy center administrators provided ongoing calibration throughout the study. Primary interviews with topical formulation R&D heads and transdermal manufacturing plant managers combined with secondary validation against FDA 510(k) filings, EMA centralized procedure documents, ClinicalTrials.gov entries, and German hospital procurement databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored volume estimates.
Scenario-bracketing around FDA bioequivalence pathway velocity, German physical therapy reimbursement stability, and Japanese PMDA review timeline variation framed projection uncertainty. Segmentation dimensions spanned treatment type, diagnosis method, severity level, and patient demographic archetype across the modeling period. CAGRs derived from therapeutic adoption curve analysis and payer authorization trend extrapolation. Forecast inputs incorporated sports medicine clinic expansion rates and telehealth diagnostic protocol penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates or pharmaceutical reimbursement indexing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and prescriber behavior stability. Material shifts in FDA topical NSAID guidance or EMA pharmacovigilance enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Canine Orthopedics Market
Orthopedics
Kyphosis Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Podiatry Services Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Hallux Rigidus Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Septic Arthritis Market
Orthopedics
Bone Spur Market