
 Staphylococcal Infection Treatment Market | 2026-2036
Staphylococcal Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Staphylococcal Infection Treatment Market Analytics
Hospital end-user demand is restructuring as outpatient parenteral antimicrobial therapy programs expand, shifting volume toward home care channels while intensive care units retain high-acuity cases. Pfizer leverages its established hospital formulary relationships to sustain injectable antibiotic access across integrated delivery networks. Basilea Pharmaceutica specializes in beta-lactamase-resistant cephalosporins, occupying a narrow but defensible position against multidrug-resistant strains. Merck & Co. dominates the late-stage pipeline for novel mechanism agents targeting refractory infections.
Staphylococcal infection treatment encompasses pharmaceutical and biologic interventions designed to eliminate or suppress pathogenic Staphylococcus aureus and coagulase-negative species, with formulations typically requiring MIC-guided dosing against methicillin-resistant and vancomycin-intermediate strains to ensure therapeutic efficacy. The primary purpose centers on reducing mortality from invasive bacteremia, endocarditis, and deep-seated soft tissue infections while preventing recurrence in colonized carriers. Antibiotics remain the largest product type segment, though margin pools increasingly concentrate in monoclonal antibodies targeting toxin-mediated pathophysiology. Intravenous delivery mode retains the highest value per patient episode, while oral step-down protocols gain traction in management-stage protocols seeking to reduce catheter-associated complications.
FDA's Qualified Infectious Disease Product program and EMA's PRIME eligibility pathway shape clinical trial investment by granting expedited review and extended market exclusivity for novel anti-staphylococcal agents. BIS pharmacopoeial standards in India and CDSCO manufacturing inspections further constrain which suppliers qualify for institutional procurement tenders across major hospital chains. Stakeholders must monitor resistance surveillance data from the CDC's Emerging Infections Program and WHO's GLASS network to anticipate protocol shifts that reorder product preference hierarchies.
Market Dynamics
Hospital formulary committees are tightening antibiotic stewardship protocols, forcing manufacturers to demonstrate superior resistance profiles against MRSA and VISA strains before securing procurement contracts across integrated delivery networks.
Growth Catalysts
- FDA Qualified Infectious Disease Product designation:Expedited review timelines and extended exclusivity periods incentivize pharmaceutical developers to prioritize novel anti-staphylococcal mechanisms in their clinical pipelines.
- Outpatient parenteral antimicrobial therapy expansion:Home infusion programs are extending treatment episodes beyond hospital walls, creating demand for stable, long-acting injectable formulations with simplified cold-chain requirements.
- Vancomycin-intermediate S. aureus emergence:Clinical microbiology laboratories are escalating surveillance sensitivity, triggering protocol updates that favor next-generation lipoglycopeptides and oxazolidinones.
Market Restraints
- Active pharmaceutical ingredient concentration:Beta-lactam and glycopeptide precursor synthesis clusters in Chinese and Indian manufacturing zones, exposing supply continuity to geopolitical friction and environmental compliance shutdowns.
- Antibiotic development economics:Reimbursement compression and short-course therapy requirements compress revenue per patient episode below thresholds that justify billion-dollar R&D outlays for novel mechanisms.
- Diagnostic stewardship mandates:Narrow-spectrum prescribing protocols from CDC's Core Elements of Hospital Antibiotic Stewardship restrict empirical broad-spectrum deployment, limiting addressable patient populations.
Strategic Opportunities
- Monoclonal antibody toxin neutralization:Anti-alpha-hemolysin and anti-PVL biologics targeting sepsis pathophysiology rather than bacterial clearance are opening parallel therapeutic categories with distinct reimbursement codes.
- Indian institutional procurement expansion:CDSCO manufacturing inspections and BIS pharmacopoeial compliance are unlocking tender access for qualified suppliers across corporate hospital chains in Mumbai, Delhi, and Bangalore.
- Pharmacokinetic-guided dosing software:Integration of Bayesian dosing algorithms with electronic health records enables precision vancomycin and daptomycin administration, differentiating service-attached product offerings.
Industry Challenges
- Clinical microbiology workforce scarcity:Specialized training programs for MIC interpretation and resistance mechanism identification lag hospital expansion rates, delaying appropriate therapy initiation.
- Multisite trial coordination complexity:Recruiting sufficient invasive MRSA cases across geographically dispersed sites strains investigator networks and extends regulatory submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Staphylococcal Infection Treatment Market |
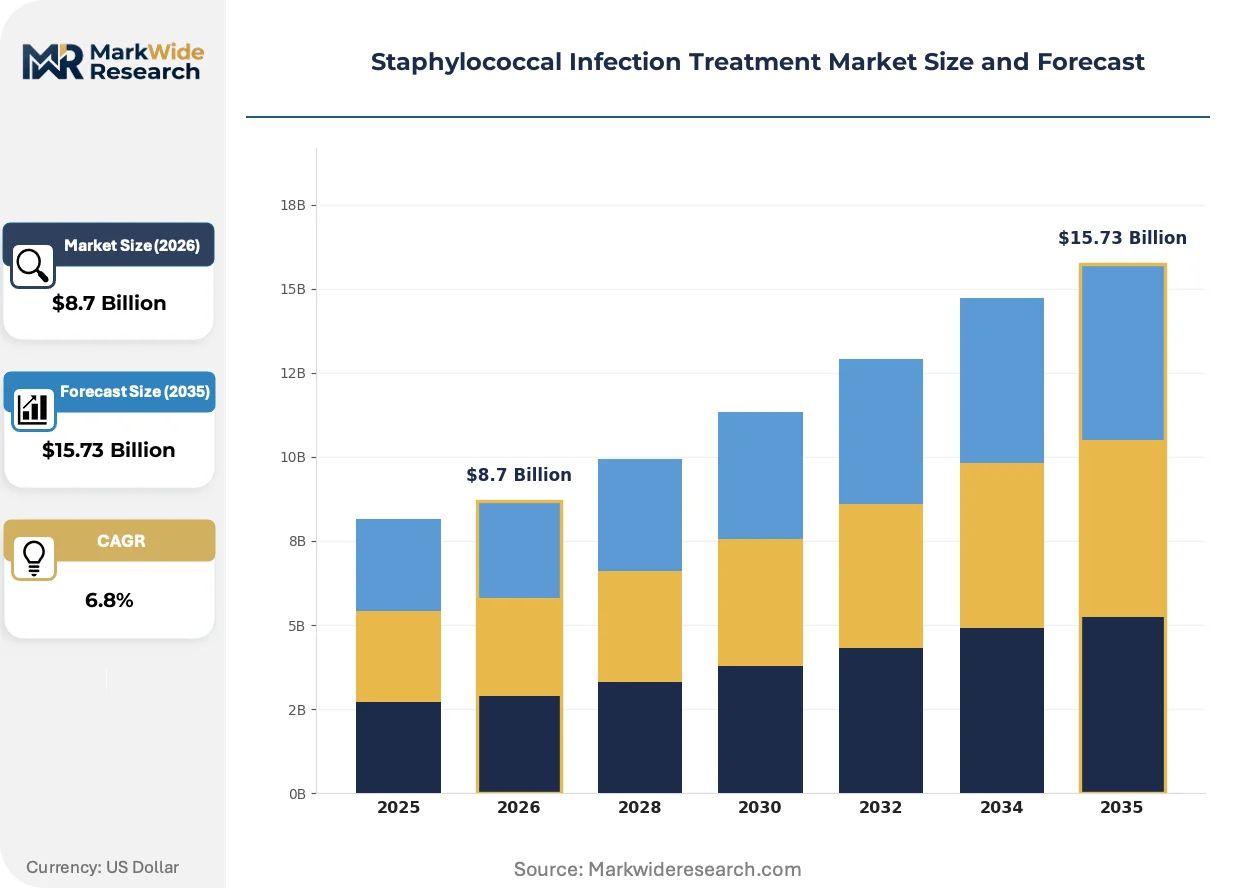
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiseptics, Vaccines, Monoclonal Antibodies Delivery Mode: Oral, Topical, Injectable, Intravenous End User: Hospitals, Clinics, Home Care, Laboratories Treatment Stage: Prevention, Acute Treatment, Management, Refractory Cases |
| Companies Covered | Merck & Co., Pfizer, Allergan, GlaxoSmithKline, Bayer, Basilea Pharmaceutica, Theravance Biopharma, Melinta Therapeutics, Cumberland Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Staphylococcal Infection Treatment Market Evolving Landscape
Novel therapeutic modalities are fragmenting traditional antibiotic-centric treatment paradigms, with biologics and precision diagnostics inserting themselves between empirical prescribing and pathogen-directed therapy.
Next-generation oxazolidinones with enhanced Gram-negative coverage are consolidating hospital formulary positioning against earlier-generation linezolid. Intensive care units in tertiary academic centers are adopting these agents for polymicrobial ventilator-associated pneumonia where MRSA co-pathogenicity is suspected. This consolidation is compressing market access for standalone anti-MRSA agents lacking spectrum extension.
EMA's PRIME eligibility pathway is accelerating conditional marketing authorization timelines for breakthrough anti-staphylococcal therapies targeting refractory bacteremia. European reference pricing systems are responding by establishing distinct reimbursement tiers for agents demonstrating mortality benefit in registrational trials. Critical care specialists in Germany, France, and Italy are revising sepsis bundles to incorporate these prioritized therapies.
Integrated delivery networks are unbundling antimicrobial stewardship from pharmacy benefit management, creating direct contracting relationships with manufacturers for outcomes-guaranteed supply agreements. Hospital systems in Texas, Florida, and California are piloting readmission-risk-adjusted pricing models that tie formulary placement to 30-day infection recurrence rates. This restructuring is displacing traditional group purchasing organization intermediaries in high-acuity antibiotic categories.
Staphylococcal Infection Treatment Market Segmentation
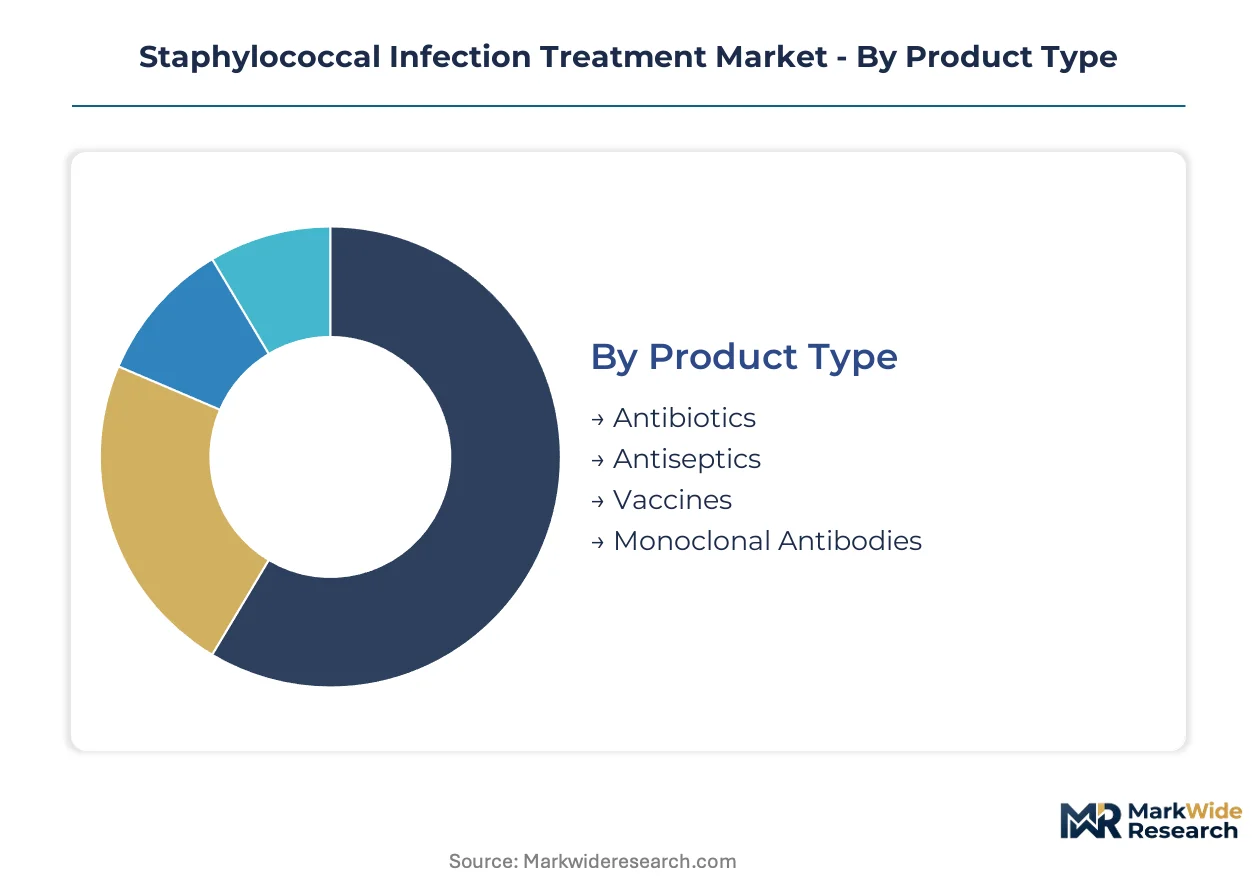
Segmentation in staphylococcal infection treatment reveals divergent margin structures across administration routes and care settings. Product type splits between commodity antibiotics and premium biologics, while delivery mode determines reimbursement tiers and patient episode economics.
Product Type:
Volume concentration sits with established small-molecule antibiotics, while premium capture concentrates in targeted biologics and next-generation modalities.
- Antibiotics:Beta-lactams, glycopeptides, lipoglycopeptides, oxazolidinones, and lipopeptides constitute the therapeutic backbone against MSSA and MRSA. Hospital formularies in the United States prioritize agents with MIC breakpoints below resistant thresholds for bloodstream infection protocols.
- Monoclonal Antibodies:Anti-toxin biologics targeting alpha-hemolysin and PVL-mediated pathophysiology command distinct reimbursement codes outside traditional antimicrobial categories. Academic medical centers in Boston and San Francisco are integrating these into sepsis bundles for toxin-mediated pneumonia.
- Antiseptics:Chlorhexidine and povidone-iodine formulations dominate decolonization protocols for MRSA carriers pre-surgery.
- Vaccines:Investigational S. aureus vaccines remain confined to Phase II trials with no approved prophylactic products currently available.
Mature deployment sits with Antibiotics. Newer deployment is concentrated in Monoclonal Antibodies.
Delivery Mode:
Route of administration determines care setting eligibility, cold-chain requirements, and per-episode reimbursement levels across integrated delivery networks.
- Intravenous:Continuous or intermittent infusion of vancomycin, daptomycin, and ceftaroline retains the highest value per patient episode in intensive care settings. Home infusion programs in Florida and Texas are extending IV therapy beyond hospital walls through outpatient parenteral antimicrobial therapy expansion.
- Injectable:Long-acting lipoglycopeptides with extended half-lives enable simplified dosing schedules for osteomyelitis and endocarditis. These formulations are gaining traction in step-down units seeking to reduce catheter-associated complications.
- Oral:Step-down protocols favor linezolid and tedizolid for stable patients transitioning from inpatient to outpatient management.
- Topical:Mupirocin and retapamulin address localized skin and soft tissue infections with minimal systemic exposure.
Established utilization centers on Intravenous administration. Steepest expansion trajectory is occurring in Injectable formulations for extended outpatient therapy.
End User:
Procurement authority and formulary control vary sharply across institutional, ambulatory, and home-based care environments.
- Hospitals:Tertiary academic centers and community hospitals command the largest procurement volumes through antibiotic stewardship committees. These institutions enforce narrow-spectrum prescribing protocols that reorder product preference hierarchies based on resistance surveillance data.
- Home Care:Infusion therapy providers and skilled nursing facilities are capturing extended treatment episodes as OPAT programs expand. Demand concentrates for stable formulations with simplified storage requirements and reduced nursing supervision needs.
- Clinics:Outpatient wound care and infectious disease practices manage uncomplicated skin and soft tissue infections with oral and topical agents.
- Laboratories:Clinical microbiology services support therapeutic decision-making through MIC testing and resistance mechanism identification.
Primary volume capture remains with Hospitals. Emerging volume redistribution is shifting toward Home Care channels.
Treatment Stage:
Clinical urgency and therapeutic intensity define product selection across the care continuum from prophylaxis through salvage therapy.
- Acute Treatment:Empirical and pathogen-directed therapy for bacteremia, endocarditis, and deep-seated infections requires IV agents with rapid bactericidal activity. FDA's Qualified Infectious Disease Product designation accelerates development timelines for breakthrough therapies in this category.
- Refractory Cases:Vancomycin-intermediate and daptomycin-non-susceptible infections drive demand for novel mechanism agents in salvage settings. These cases concentrate in referral centers with specialized infectious disease consultation services.
- Prevention:Preoperative decolonization and carrier suppression protocols utilize topical antiseptics and intranasal mupirocin.
- Management:Suppressive oral therapy for chronic osteomyelitis and prosthetic joint infections extends treatment duration over months.
Established clinical infrastructure supports Acute Treatment. Novel therapeutic development is concentrating in Refractory Cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical manufacturing zones in Ireland and Puerto Rico concentrate sterile injectable production for anti-MRSA agents, attracting FDA-regulated facilities through tax-advantaged structures. These zones anchor supply security for North American and European hospital networks managing resistant staphylococcal infections.
United States
Hospital-based acute treatment programs in Texas, Florida, and California drive procurement volume for novel anti-MRSA agents through integrated delivery networks. The FDA's Qualified Infectious Disease Product designation accelerates development timelines for breakthrough therapies targeting refractory infections. Boston and San Francisco academic medical centers pilot sepsis bundles incorporating anti-toxin biologics.
Germany
Critical care specialists in German tertiary centers revise sepsis protocols to incorporate EMA PRIME-eligible therapies demonstrating mortality benefit. The country's reference pricing system establishes distinct reimbursement tiers for prioritized anti-staphylococcal agents. Bavaria and North Rhine-Westphalia host specialized infectious disease referral networks managing vancomycin-intermediate cases.
India
Corporate hospital chains in Mumbai, Delhi, and Bangalore expand procurement tenders for qualified suppliers meeting CDSCO manufacturing inspections and BIS pharmacopoeial standards. The country's national pharmaceutical regulator enforces compliance constraints that determine institutional access. Maharashtra and Karnataka concentrate manufacturing capacity for beta-lactam and glycopeptide precursors.
Japan
PMDA accelerated review pathways prioritize novel mechanism agents for daptomycin-non-susceptible infections in aging patient populations. METI industrial policy supports domestic production of critical antibiotic precursors to reduce import dependency. The Kanto region around Tokyo anchors hospital formulary decision-making for premium anti-MRSA therapies.
Switzerland
Swissmedic regulatory frameworks attract specialized developers of beta-lactamase-resistant cephalosporins through streamlined approval procedures for breakthrough therapies. Basel and Zurich host clinical trial coordination networks for multisite invasive MRSA studies. The country's precision medicine infrastructure supports pharmacokinetic-guided dosing software integration.
Staphylococcal Infection Treatment Market Competitive Landscape
Top-tier vendors anchor hospital formulary relationships across integrated delivery networks, while mid-cap specialists occupy narrow resistance-profile niches against multidrug-resistant strains. The competitive structure stratifies across diversified pharmaceutical conglomerates with broad infectious disease portfolios and focused biotechnology developers with single-mechanism depth. Three archetypes dominate: large-cap incumbents leveraging established injectable infrastructure, mid-tier specialists in beta-lactamase-resistant modalities, and late-stage developers advancing novel mechanism agents. Consolidation pressure manifests through strategic partnerships for co-commercialization rights and selective licensing of salvage-therapy candidates.
Within the diversified pharmaceutical tier, Merck & Co. and Pfizer represent scale-driven positions anchored by hospital formulary access and late-stage pipeline depth. Basilea Pharmaceutica occupies a specialist position exemplifying narrow-but-defensible focus against multidrug-resistant strain evolution. These three entities illustrate the competitive spectrum from broad infectious disease platforms to targeted resistance-profile specialization.
| Leading Market Players |
|---|
| Merck & Co. |
| Pfizer |
| Allergan |
| GlaxoSmithKline |
| Bayer |
| Basilea Pharmaceutica |
| Theravance Biopharma |
| Melinta Therapeutics |
| Cumberland Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Product-tier bifurcation between premium novel agents and commodity generics manifests in divergent margin structures and supply chain configurations across the staphylococcal infection treatment landscape. Premium lipoglycopeptides and monoclonal antibodies command hospital formulary placement through FDA Qualified Infectious Disease Product designation, while generic vancomycin and linezolid flow through high-volume, price-sensitive procurement channels tethered to Indian and Chinese API supply.
Pricing Analysis
Lead-time-driven pricing angles dominate hospital procurement, with manufacturers extracting premiums for just-in-time delivery of novel anti-MRSA agents against resistant strain outbreaks. Contract-based long-term offtake agreements anchor pricing for established antibiotics, while spot purchasing for salvage-therapy candidates reflects acute demand surges. Price differentiation rests on FDA breakthrough therapy designation and MIC breakpoint superiority. Cost compression in generic glycopeptides is intensifying because of API oversupply from Indian manufacturing zones. Integrated delivery networks exhibit highest price sensitivity, while specialized infectious disease referral centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Direct-to-hospital channels handle formulary-committed volume, while distributor intermediaries manage spot procurement for smaller community hospitals. Geographic supply concentration centers on India and China for beta-lactam and glycopeptide precursors, with Ireland and Puerto Rico anchoring sterile injectable finishing. Raw material dependencies include fermentation-derived starting materials, specialized chromatography resins, and cold-chain packaging components. Single-source vulnerability in Chinese API manufacturing exposes continuity to environmental compliance shutdowns. Distribution runs through integrated delivery network central warehouses, with home infusion providers capturing outpatient parenteral antimicrobial therapy volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic development economics are forcing consolidation as reimbursement compression and short-course therapy requirements squeeze standalone developers. Scale-driven players with hospital formulary depth and manufacturing integration will capture displaced volume from subscale competitors.
For Market Incumbents: Lock in formulary positioning through outcomes-guaranteed contracting with integrated delivery networks piloting readmission-risk-adjusted pricing models. Deepen backward integration into API supply through strategic partnerships with Indian manufacturers meeting CDSCO inspection standards. Pfizer and Merck & Co. can leverage existing hospital relationships to extend access for novel mechanism agents against daptomycin-non-susceptible infections. For New Entrants and Emerging Players: FDA Qualified Infectious Disease Product designation in the United States opens a window for developers of anti-toxin monoclonal antibodies to secure expedited review and extended exclusivity. Target home care channels in Florida and Texas where outpatient parenteral antimicrobial therapy expansion creates demand for stable, long-acting injectable formulations. A go-to-market angle centered on pharmacokinetic-guided dosing software integration differentiates service-attached product offerings in academic medical centers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing novel mechanism pipelines and EMA PRIME eligibility given European reference pricing system's distinct reimbursement tiers for mortality-benefit therapies. Long-term viability over the next decade favors developers with diversified portfolios spanning antibiotics and biologics rather than single-mechanism bets. The signal to watch is formulary committee adoption of sepsis bundles incorporating anti-alpha-hemolysin biologics as inflection indicator for toxin-neutralization category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Qualified Infectious Disease Product designation accelerates breakthrough therapy timelines for refractory MRSA agents. |
| Manufacturing Scale-Up | CDSCO-compliant facilities in Maharashtra and Karnataka unlock tender access across corporate hospital chains. |
| Hospital System Partnership | Integrated delivery network contracting displaces traditional group purchasing organization intermediaries in high-acuity categories. |
| Pipeline Diversification | Anti-toxin monoclonal antibodies create parallel therapeutic categories with distinct reimbursement codes outside antimicrobial frameworks. |
| Reimbursement Strategy | EMA PRIME eligibility secures conditional marketing authorization and prioritized reference pricing tiers in Germany and France. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis of staphylococcal infection treatment market dynamics. Primary interviews with infectious disease specialists, hospital formulary directors, regulatory affairs leads at pharmaceutical developers, and procurement managers at integrated delivery networks complemented secondary validation. FDA approval databases, EMA submission records, ClinicalTrials.gov protocols, and CDC Emerging Infections Program surveillance data provided quantitative anchors. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation reconciled segment estimates across the analysis window.
Data-stream reconciliation integrated hospital procurement database trends with resistance surveillance patterns from WHO GLASS network and national health authority reports. Segmentation dimensions modeled include product type, delivery mode, end user, and treatment stage, with regional regulatory clusters capturing FDA, EMA, PMDA, and CDSCO framework variations. CAGRs were derived through logarithmic trend fitting against historical volume trajectories and adjusted for protocol shift elasticity. Bayesian dosing algorithm adoption rates and outpatient parenteral antimicrobial therapy expansion curves informed care-setting transition assumptions.
The model assumes a particular technology adoption path for pharmacokinetic-guided dosing software; alternative pathways for monoclonal antibody sepsis bundle integration would alter the outlook for toxin-neutralization category development. Forecasts reflect documented assumptions regarding resistance surveillance sensitivity, formulary committee composition, and reimbursement tier stability. Periodic stress-testing of base assumptions against CDC protocol updates and EMA reference pricing revisions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Sterility Indicators Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Sterilization Equipment and Disinfectant Market
Infection Control
Perianal Infection Treatment Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Antimicrobial Suture Market
Infection Control
Antiseptic Bathing Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
Infection Prevention Market
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
Sterilization Tunnel Market
Infection Control
Clinical Hand Hygiene Products Market
Infection Control
Global Dental Infection Control Products Market