
 USA Artificial Organs and Bionic Implants Market | 2026-2036
USA Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
USA Artificial Organs and Bionic Implants Market Analytics
Silicon carbide is restructuring ceramic-bearing surfaces in total artificial hearts, cutting thrombogenicity and extending device durability beyond prior polymer generations. Medtronic plc leverages its vertically integrated cardiovascular manufacturing footprint to control pump assembly costs. Boston Scientific Corporation anchors its position through deep R&D spending on leadless pacing and neuromodulation platforms. Abiomed Inc. specializes in percutaneous heart pump miniaturization, occupying a narrow but defensible niche in acute mechanical circulatory support.
Artificial organs and bionic implants comprise electromechanical or biological substitutes designed to replace or augment native tissue function, typically incorporating biocompatible alloys, polymers, or living cells with power densities exceeding 15 microwatts per cubic millimeter for neural interfaces and flow rates above 5 liters per minute for cardiac support. Their primary purpose spans life-sustaining organ replacement, sensory restoration, and motor function rehabilitation across acute and chronic care settings. Cochlear implants represent the most mature segment with established reimbursement and predictable replacement cycles, while bionic limbs incorporating myoelectric robotics command premium pricing due to customization complexity. Artificial hearts and retinal implants carry the steepest regulatory burdens but offer the largest unmet need pools, concentrating margin opportunity among manufacturers that navigate FDA premarket approval pathways successfully.
FDA premarket approval and breakthrough device designation govern market access timelines and clinical evidence requirements for implantable devices in the United States, while CMS national coverage determinations directly shape hospital purchasing decisions and patient access. The National Organ Transplant Act and subsequent amendments create statutory frameworks for organ allocation that indirectly expand the addressable population for mechanical alternatives. State-level certificate-of-need regulations in Texas, Florida, and California influence where advanced implant programs concentrate geographically. Stakeholders must monitor evolving FDA guidance on brain-computer interfaces and anticipated CMS technology add-on payment reforms for artificial organs, as these will determine which platform technologies achieve sustainable commercial scale.
Market Dynamics
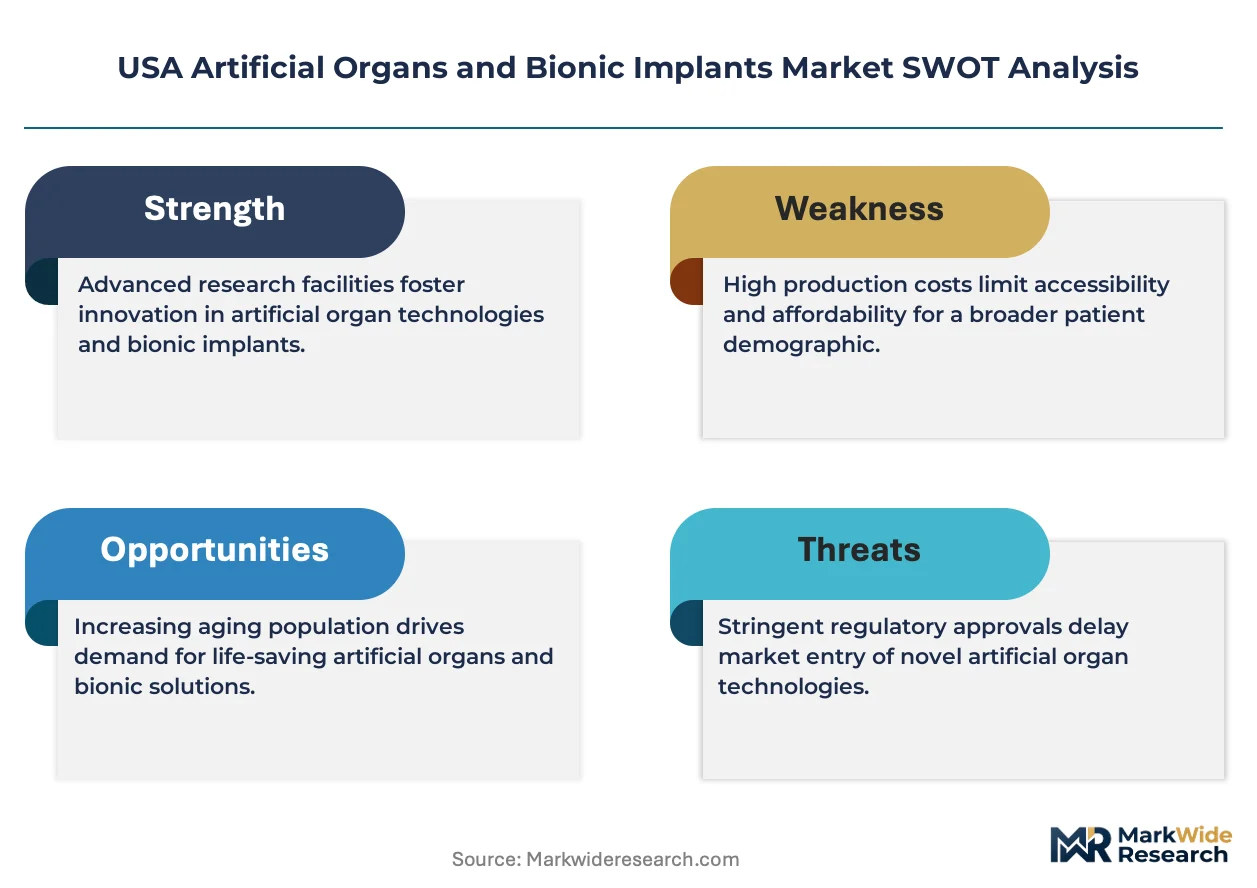
CMS reimbursement pathways for breakthrough devices are compressing hospital adoption timelines, while FDA premarket approval requirements for Class III implants maintain steep clinical evidence barriers that concentrate manufacturing among vertically integrated cardiovascular specialists.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines for ventricular assist devices and transcatheter valves reduce commercialization lag, expanding hospital procedural volumes in acute mechanical circulatory support.
- Silicon Carbide Ceramic Surfaces:This material substitution in total artificial heart bearings cuts thrombogenicity and extends device durability beyond polymer generations, driving replacement demand in cardiac centers.
- Certificate-of-Need Concentration:Texas, Florida, and California regulations cluster advanced implant programs in designated medical centers, creating predictable demand nodes for manufacturers.
Market Restraints
- Premarket Approval Burden:FDA Class III PMA requirements demand multi-year clinical trials and substantial safety databases, freezing out early-stage developers without captive cardiovascular manufacturing infrastructure.
- Biocompatible Alloy Supply Concentration:Titanium and cobalt-chromium feedstock sourcing concentrates among specialty metallurgical suppliers, exposing device makers to input cost volatility and qualification delays.
- Organ Transplant Substitution:The National Organ Transplant Act allocation frameworks and improved immunosuppression protocols extend biological organ viability, capping the addressable pool for mechanical heart alternatives in select patient cohorts.
Strategic Opportunities
- Neuromodulation Platform Expansion:Deep brain stimulation and spinal cord interfaces for movement disorders represent underpenetrated therapeutic areas with established reimbursement infrastructure and aging demographic tailwinds.
- Leadless Pacing Miniaturization:Battery-free and energy-harvesting cardiac rhythm devices eliminate transvenous lead complications, opening procedural expansion into community hospital settings previously excluded by complication risk.
- Technology Add-On Payment Reform:Anticipated CMS adjustments for artificial organs would reduce hospital cost absorption for novel implants, accelerating procurement committee approval cycles for premium-priced bionic platforms.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 18-24 month completion timelines, compressing product development windows and demanding parallel rather than sequential regulatory submissions.
- Neural Interface Talent Scarcity:Electrochemical engineering and microelectromechanical systems design expertise concentrates among a limited pool of academic and industry specialists, inflating compensation costs and extending hiring cycles.
- Legacy Electronic Health Record Integration:Implantable device data streams require proprietary middleware development for Epic and Cerner compatibility, fragmenting remote monitoring deployment across hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Artificial Organs and Bionic Implants Market |
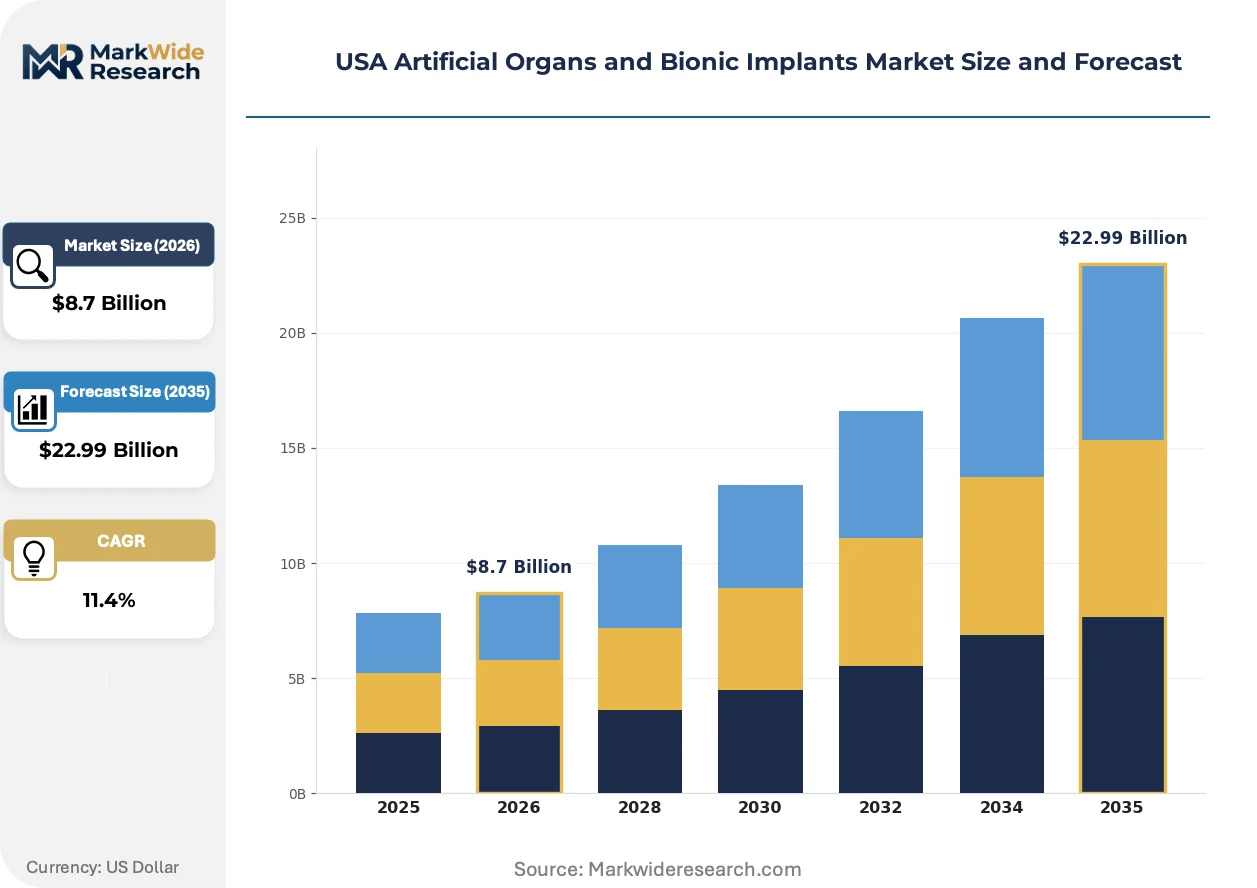
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Heart, Cochlear Implants, Retinal Implants, Bionic Limbs End User: Hospitals, Rehabilitation Centers, Research Institutions, Homecare Settings Technology: Bioengineering, Nanotechnology, Robotics, 3D Printing Application: Cardiovascular, Neurological, Orthopedic, Urological |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abiomed Inc., Zimmer Biomet Holdings Inc., Edwards Lifesciences Corporation, Cochlear Ltd., Ekso Bionics Holdings Inc., Berlin Heart GmbH, Össur, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Artificial Organs and Bionic Implants Market Evolving Landscape
Electrification of biological interfaces is compressing power density thresholds and enabling ambulatory functionality previously confined to acute care settings, while regulatory sandboxes and reimbursement pilots accelerate translation from bench to bedside.
Silicon carbide ceramic bearing technology is electrifying total artificial heart design by enabling rotational speeds above 12,000 RPM without thrombus formation. Major cardiac surgery centers in Cleveland, Houston, and Los Angeles are piloting these devices in bridge-to-transplant protocols. The technology is electrifying competitive positioning by rewarding manufacturers with captive ceramic processing capabilities and punishing polymer-dependent product lines.
FDA guidance on brain-computer interfaces is crystallizing clinical evidence requirements for neural signal acquisition devices, creating a predictable pathway for cortical implant commercialization. The framework mandates long-term biostability data that favors established neuromodulation platforms with decade-long safety databases. Retinal prosthesis developers and motor neuroprosthetic specialists are responding by consolidating preclinical programs and prioritizing chronic implantation studies over acute feasibility demonstrations.
Hospital value analysis committees are consolidating purchasing authority for high-cost implantable devices, displacing individual physician preference as the primary procurement determinant. Cardiovascular service lines now route ventricular assist device and transcatheter valve selections through standardized technology assessment protocols. This concentration is most visible in integrated delivery networks across Pennsylvania, Ohio, and North Carolina, where system-wide contracts compress vendor margins in exchange for volume guarantees.
USA Artificial Organs and Bionic Implants Market Segmentation
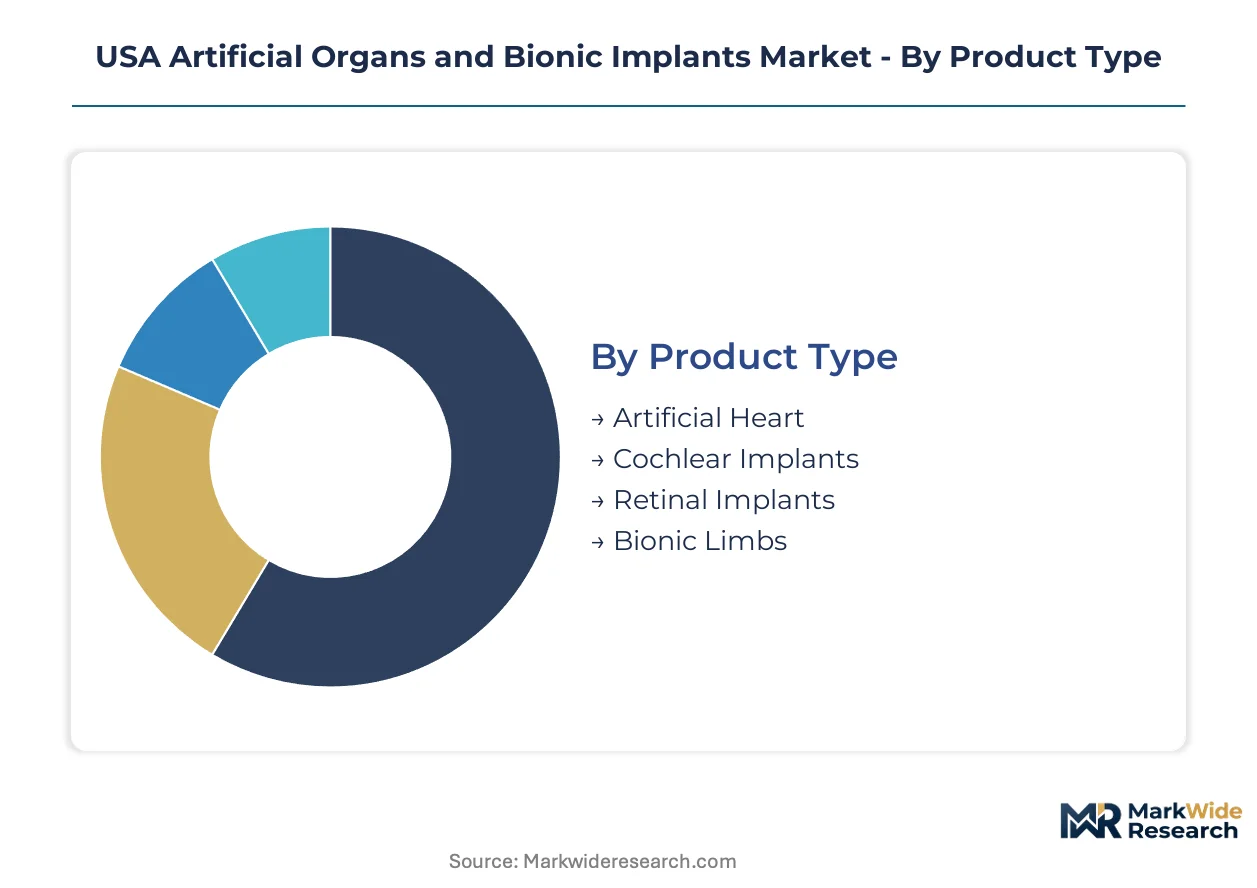
Segmentation in the USA artificial organs and bionic implants market reveals distinct procurement patterns across clinical settings and technology platforms. Hospital value analysis committees route purchasing decisions through different evaluation frameworks depending on product complexity and reimbursement status.
Product Type:
Procurement committees weight replacement cycle predictability and reimbursement certainty when allocating capital budgets across implant categories.
- Artificial Heart:Silicon carbide ceramic bearings enable rotational speeds exceeding 12,000 RPM while suppressing thrombus formation. Demand clusters in Cleveland, Houston, and Los Angeles cardiac centers where bridge-to-transplant protocols dominate patient selection criteria.
- Cochlear Implants:The most mature segment with established CMS reimbursement and predictable replacement cycles every 8-12 years. Volume concentrates in pediatric and aging cohorts across Texas, Florida, and California where certificate-of-need regulations concentrate implant surgery programs.
- Retinal Implants:FDA Class III PMA requirements demand multi-year biostability databases, limiting commercialization to developers with captive manufacturing infrastructure.
- Bionic Limbs:Myoelectric robotics command premium pricing due to customization complexity and prosthetist labor intensity.
Volume sits with Cochlear Implants; growth tilts toward Artificial Heart.
End User:
Site-of-care economics and complication risk profiles determine where each technology achieves sustainable procedural volume.
- Hospitals:Dominant channel for ventricular assist devices and transcatheter valves where 24-hour perfusionist coverage and cardiothoracic surgery backup are mandatory. Integrated delivery networks in Pennsylvania, Ohio, and North Carolina route high-cost implant decisions through standardized technology assessment protocols.
- Rehabilitation Centers:Primary site for bionic limb fitting and myoelectric training protocols. Demand concentrates in states with dense veteran populations and workers compensation frameworks.
- Research Institutions:Bridge-to-clinical trials for brain-computer interfaces and retinal prostheses requiring long-term biostability data collection.
- Homecare Settings:Emerging channel for leadless pacing and remote monitoring platforms as battery-free energy harvesting eliminates transvenous lead complications.
Procurement authority concentrates in Hospitals; expansion is climbing the fastest in Homecare Settings.
Technology:
Manufacturing process maturity and regulatory qualification timelines separate scalable platforms from niche applications.
- Bioengineering:Living cell incorporation and biocompatible scaffold development for organoid applications. FDA breakthrough device designation accelerates review timelines for tissue-engineered vascular grafts.
- Nanotechnology:Surface modification and drug-eluting coatings for thrombogenicity reduction in cardiovascular implants.
- Robotics:Myoelectric control systems and sensory feedback loops for upper-limb prostheses.
- 3D Printing:Patient-specific anatomical modeling and surgical planning tools; expanding into titanium and cobalt-chromium implant fabrication with ISO 10993 biocompatibility certification.
Commercial scale favors Bioengineering; steepest expansion trajectory belongs to 3D Printing.
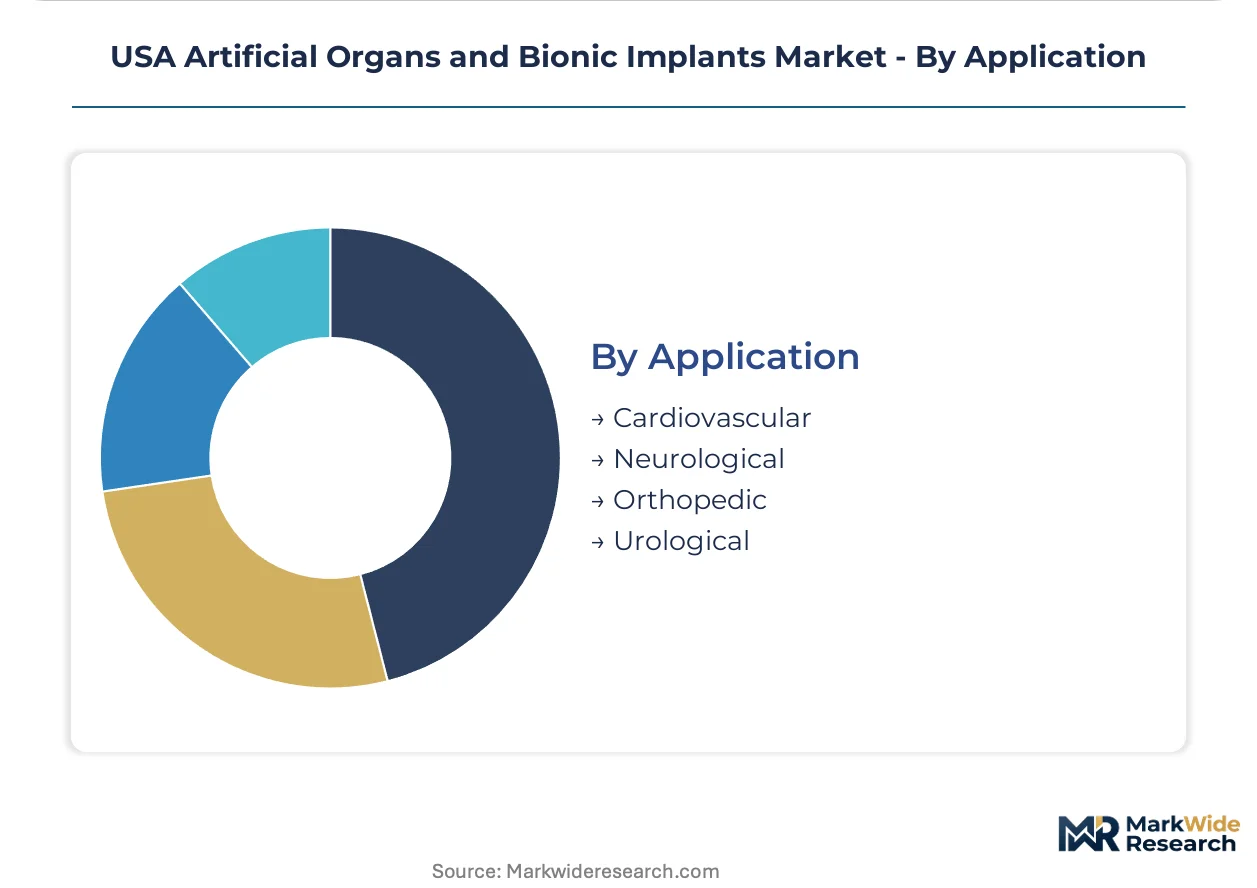
Application:
Therapeutic area unmet need and reimbursement infrastructure maturity create divergent margin profiles across clinical domains.
- Cardiovascular:Ventricular assist devices and transcatheter heart valves where CMS national coverage determinations directly shape hospital purchasing. Silicon carbide bearings and miniaturized percutaneous pumps define current technology investment.
- Neurological:Deep brain stimulation and spinal cord interfaces for movement disorders. Aging demographics and established reimbursement codes drive volume in Parkinson's and essential tremor indications.
- Orthopedic:Bionic limbs and osseointegrated prosthetic anchors with myoelectric control systems.
- Urological:Artificial urinary sphincters and neuromodulation devices for bladder dysfunction with narrower addressable populations.
Revenue concentration rests in Cardiovascular; margin expansion is gaining share fastest in Neurological.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certificate-of-need regulations and transplant center density are concentrating advanced implant programs in designated medical zones across the United States, creating predictable demand nodes for manufacturers.
Texas
The Texas Medical Center in Houston anchors one of the nation's highest volumes of ventricular assist device implantations, driven by bridge-to-transplant protocols and established cardiothoracic surgery infrastructure. FDA breakthrough device designations for novel cardiac support technologies accelerate hospital adoption timelines in this cluster. Dallas-Fort Worth and San Antonio secondary markets expand procedural access for bionic limb fittings through veteran-focused rehabilitation networks.
California
Silicon Valley's neural interface startup ecosystem feeds into Stanford and UCSF clinical trial pipelines for brain-computer interfaces and retinal prostheses. The state's certificate-of-need framework concentrates artificial heart programs at Cedars-Sinai, UCLA, and Stanford Medical Center. Los Angeles and San Diego cardiac centers drive demand for silicon carbide bearing technology in total artificial heart applications.
Ohio
Cleveland Clinic's dominance in cardiovascular innovation creates a captive market for next-generation ventricular assist devices and transcatheter valve platforms. Ohio's integrated delivery networks route high-cost implant decisions through standardized technology assessment protocols that compress vendor margins. Cincinnati and Columbus secondary markets expand cochlear implant volumes through pediatric and aging demographic concentration.
Florida
Retirement migration patterns concentrate aging cohorts requiring cochlear implants and cardiac rhythm management devices across Tampa, Orlando, and Miami metro areas. The state's certificate-of-need regulations cluster advanced implant surgery programs at Mayo Clinic Jacksonville and University of Miami Health System. Veteran populations in Pensacola and Jacksonville drive bionic limb demand through workers compensation and VA procurement channels.
Pennsylvania
Philadelphia and Pittsburgh academic medical centers anchor NIH-funded research pipelines for bioengineered vascular grafts and tissue-engineered organoids. University of Pennsylvania and Carnegie Mellon electrochemical engineering programs supply neural interface talent to regional device manufacturers. Integrated delivery networks across the Commonwealth consolidate ventricular assist device purchasing authority through system-wide technology contracts.
USA Artificial Organs and Bionic Implants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated cardiovascular conglomerates controlling pump assembly costs while niche percutaneous specialists defend premium positioning in acute mechanical circulatory support. The market structure concentrates manufacturing among FDA premarket approval veterans with captive metallurgical processing capabilities, freezing out early-stage developers without multi-year safety databases. Three archetypes dominate: diversified cardiovascular conglomerates with in-house ceramic processing, focused acute-support specialists, and orthopedics-led bionics platforms. Competitive moves center on silicon carbide bearing technology licensing and neuromodulation platform expansion through strategic R&D partnerships.
Among diversified cardiovascular manufacturers, Medtronic plc and Boston Scientific Corporation exemplify the conglomerate archetype with vertically integrated manufacturing footprints spanning pump assembly and leadless pacing platforms. Abiomed Inc. occupies a narrow but defensible position in percutaneous heart pump miniaturization, representing the focused acute-support specialist model. These three anchors demonstrate how FDA breakthrough device designation experience and CMS reimbursement pathway navigation separate scalable competitors from development-stage aspirants.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abiomed Inc. |
| Zimmer Biomet Holdings Inc. |
| Edwards Lifesciences Corporation |
| Cochlear Ltd. |
| Ekso Bionics Holdings Inc. |
| Berlin Heart GmbH |
| Össur |
| Others |
Value Network & Pricing Analysis
Cobalt-chromium alloy spot indices on the London Metal Exchange cascade through three pricing tiers for cardiovascular implant manufacturers, with premium grades commanding markups for FDA-qualified lots while standard feedstock serves contract-manufactured components.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to silicon carbide ceramic bearing orders below standard batch minimums, while spot inventory liquidations in titanium bar stock attract discount-seeking orthopedic contract manufacturers. A three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated device platforms from PMA-track generics and unapproved investigational units. Pricing pressure stems from hospital value analysis committee consolidation in integrated delivery networks, compressing vendor margins in exchange for multi-year volume commitments. Community hospital procurement managers exhibit the highest price sensitivity, while quaternary cardiac centers prioritize device reliability metrics over unit cost.
Supply Chain Analysis
Domestic-content mandates in the Buy American Act and subsequent executive orders on critical medical supplies are reshaping sourcing patterns for titanium and cobalt-chromium feedstock, pressuring manufacturers to qualify US-based metallurgical suppliers against established German and Japanese alternatives. Raw material dependencies center on specialty alloy ingots from Germany, precision ceramic powders from Japan, and biocompatible polymer resins from the United States. Single-source vulnerability concentrates in silicon carbide ceramic processing, where two German suppliers control qualification-grade output for total artificial heart bearings. Distribution runs through GPO-negotiated contracts to hospital systems, with direct-to-manufacturer relationships reserved for research institution and VA procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The USA artificial organs and bionic implants market sits in a technology-transition phase as silicon carbide ceramic bearings displace polymer generations in total artificial heart platforms, rewriting durability benchmarks and procurement criteria simultaneously.
For Market Incumbents: Deploy ceramic processing capacity additions in Ohio and Texas to capture bridge-to-transplant protocol demand before polymer-dependent competitors requalify supply chains. Fortify FDA breakthrough device designation pipelines against emerging neuromodulation specialists with deeper brain-computer interface patent portfolios. Lock in multi-year GPO contracts with integrated delivery networks in Pennsylvania and North Carolina to preempt procurement committee consolidation. For New Entrants and Emerging Players: Launch via homecare channel partnerships for leadless pacing and energy-harvesting cardiac rhythm devices, bypassing hospital value analysis committee gatekeeping that favors incumbent relationships. Target rehabilitation center networks in Florida and California for myoelectric bionic limb fittings, where veteran procurement channels and workers compensation frameworks reduce pricing sensitivity. Pursue FDA breakthrough device designation for acute mechanical circulatory support miniaturization to compress commercialization timelines against PMA-track competitors. For Investors and Strategic Acquirers: The window for entry favors neuromodulation platform specialists with chronic implantation safety databases exceeding five years, as FDA guidance on brain-computer interfaces crystallizes evidence requirements that freeze out preclinical-stage aspirants. Monitor CMS technology add-on payment reform announcements as the inflection signal for artificial organ procurement acceleration in hospital settings.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Bearing Qualification | FDA breakthrough designation for ceramic total artificial hearts rewards captive processing capabilities at Cleveland Clinic anchor sites. |
| Neuromodulation Platform Expansion | Deep brain stimulation volume in Parkinson's indications leverages established CMS reimbursement codes and aging demographic concentration. |
| Leadless Pacing Miniaturization | Battery-free energy harvesting eliminates transvenous lead complications, opening community hospital penetration previously blocked by complication risk. |
| GPO Contract Consolidation | System-wide technology assessment protocols in Pennsylvania and Ohio integrated delivery networks compress vendor margins for volume guarantees. |
| Homecare Channel Development | Remote monitoring platform deployment bypasses Epic and Cerner middleware fragmentation through proprietary data stream integration. |
Research Methodology
Multi-period observation of FDA premarket approval timelines, CMS national coverage determination issuance patterns, and hospital procedural volume reports anchored the trend analysis, supplemented by interviews with biomedical engineers, cardiothoracic surgeons, hospital purchasing committee chairs, GPO contracts managers, and neural interface electrochemical specialists. Secondary validation drew from FDA 510(k) and PMA databases, CMS Medicare claims data, hospital procurement records, and certificate-of-need regulatory filings across Texas, Florida, California, Ohio, and Pennsylvania. Bottom-up triangulation across implant shipment data and top-down reconciliation against CMS expenditure reports ensured cross-verification.
Input-output matrices modeled demand drivers across product type, end-user site-of-care, underlying technology platform, and therapeutic application segmentation dimensions throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to historical adoption rates for comparable implantable device categories, with adjustment factors for FDA breakthrough designation acceleration effects and CMS reimbursement pathway timing. Industry-specific forecast inputs incorporated silicon carbide bearing durability test results and neural interface biostability study completion timelines.
Regulatory guidance revision, CMS technology add-on payment reform delays, and biocompatible alloy supply disruptions are the dominant revision risks that could compress or extend commercialization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tissue Expanders Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Medical Device Trays Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Plethysmograph Market
Medical Devices
Global Ventilators Market