
 Postpartum Hemorrhage (PPH) Devices Market | 2026-2036
Postpartum Hemorrhage (PPH) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Postpartum Hemorrhage (PPH) Devices Market Analytics
India is tilting toward domestic manufacturing of balloon tamponade devices as import substitution policies gain traction. Cook Medical leverages extensive obstetric product portfolios to sustain presence across tertiary hospital networks. Becton Dickinson anchors North American supply chains through established gynecological surgery divisions. Teleflex Incorporated competes on catheter-based platform expertise that extends into uterine compression applications.
Postpartum Hemorrhage Devices comprise mechanical, thermal, pharmacological, and monitoring instruments designed to arrest excessive bleeding following delivery, with uterine balloon tamponade systems typically constructed from silicone or latex and rated for intrauterine pressures of 180-220 mmHg to achieve hemostasis through direct compression of placental bed vasculature. These devices serve the critical clinical purpose of preventing hypovolemic shock and coagulopathy when pharmacological uterotonics fail. Uterine balloon systems dominate procedure volumes due to their non-surgical deployment and reversibility, while hemostatic devices command premium positioning in emergency care settings where surgical backup remains unavailable. Monitoring systems represent the fastest-expanding technology segment as obstetric practices integrate hemodynamic tracking into standardized PPH response protocols.
FDA 510(k) clearance pathways govern balloon tamponade commercialization in the United States, while the EU Medical Device Regulation mandates clinical evidence thresholds that manufacturers must satisfy for CE marking access across European member states. WHO prequalification programs shape procurement eligibility for low-resource settings, directly determining which devices enter national essential equipment lists. Stakeholders must monitor evolving harmonization between FDA breakthrough device designations and WHO prequalification timelines to optimize dual-market registration strategies.
Market Dynamics
The WHO prequalification program for uterine balloon tamponade devices is compressing registration timelines and forcing manufacturers to redesign clinical evidence packages for dual-market access. This regulatory harmonization pressure is redrawing competitive boundaries between established suppliers and emerging domestic producers in high-volume procurement markets.
Growth Catalysts
- India's PLI scheme for medical devices:Production-linked incentives now cover balloon tamponade manufacturing, attracting component suppliers to establish silicone catheter production near Mumbai and Chennai industrial corridors.
- WHO Essential Medicines List inclusion:The 2019 addition of uterine balloon tamponade to the EML is mandating procurement across 46 low-resource countries through national maternal health programs.
- Sub-Saharan Africa clinic expansion:PEPFAR and Global Fund financing is equipping district maternity units with PPH response kits containing mechanical hemostasis devices.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply clusters in Northeast China and Bavaria, exposing manufacturers to logistics disruptions and input cost volatility.
- EU MDR clinical evidence thresholds:The 2021 Medical Device Regulation requires prospective uterine safety data that balloon tamponade manufacturers lack from legacy product histories.
- Pharmacological uterotonic substitution:Injectable tranexamic acid and carbetocin remain first-line PPH protocols in many tertiary hospitals, limiting mechanical device penetration.
Strategic Opportunities
- Ethiopia's national PPH kit program:The Ministry of Health's decentralized procurement model creates direct-to-distributor channels bypassing traditional hospital tender processes.
- Telemedicine-integrated monitoring:Hemodynamic tracking systems that transmit balloon pressure and blood loss data to referral hospitals are enabling rural clinic deployment.
- Domestic manufacturing in Indonesia:The national health sovereignty initiative offers tax holidays for catheter assembly operations serving ASEAN procurement networks.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 14-18 months at accredited laboratories, delaying product iterations.
- Legacy training infrastructure:Simulation-based competency programs for balloon tamponade insertion remain underdeveloped in regions where skilled birth attendant density is lowest.
Report Scope
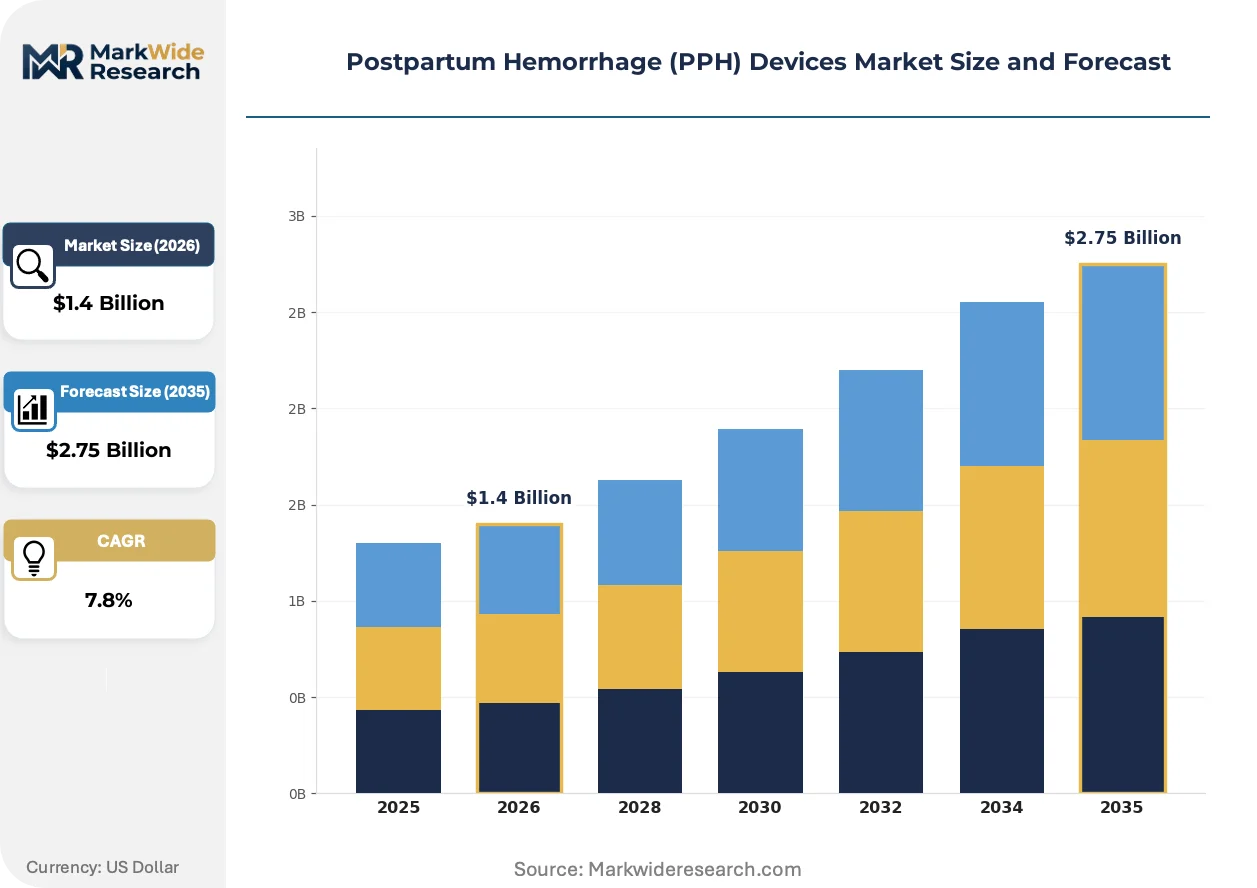
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postpartum Hemorrhage (PPH) Devices Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Uterine Balloon, Hemostatic Device, Suture Kit, Blood Volume Monitor Application: Emergency Care, Surgical Intervention, Obstetric Practices, Postoperative Monitoring End User: Hospitals, Maternity Clinics, Home Healthcare, Research Institutions Technology: Mechanical Compression, Thermal Coagulation, Pharmacological Agents, Monitoring Systems |
| Companies Covered | Cook Medical, Teleflex Incorporated, Becton Dickinson, Utah Medical Products, Organon, Bactiguard AB, Clinical Innovations, 3rd Stone Design, PATH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postpartum Hemorrhage (PPH) Devices Market Evolving Landscape
Digital integration is penetrating obstetric emergency response workflows, compressing the gap between hemorrhage detection and mechanical intervention deployment. This convergence of monitoring hardware and clinical decision support is redefining device value propositions beyond standalone mechanical function.
Condensed silicone-latex hybrid balloon catheters with integrated pressure sensors are virtualizing the traditional two-step process of device insertion and separate hemodynamic monitoring. Tertiary hospital networks in Turkey and South Korea are piloting these systems for high-risk delivery units. The technology is virtualizing capital allocation patterns by collapsing monitoring and intervention spend into single-procedure reimbursement bundles.
The FDA's 2023 updated guidance on obstetric device breakthrough designation pathways is accelerating parallel review processes for balloon tamponade innovations with pediatric extension claims. Manufacturers now structure pre-submission meetings to align 510(k) clearance evidence with WHO prequalification requirements. Emergency care settings in the United States are responding by expanding balloon tamponade stocking beyond traditional labor and delivery suites into emergency department trauma bays.
Centralized national tendering for PPH device kits is displacing hospital-level purchasing autonomy in high-volume markets. India's Government e-Marketplace platform now aggregates district hospital demand into single-source contracts with price discovery mechanisms. This pattern is most visible in Uttar Pradesh and Bihar, where state health missions have consolidated 847 facility procurements into unified balloon tamponade supply agreements.
Postpartum Hemorrhage (PPH) Devices Market Segmentation
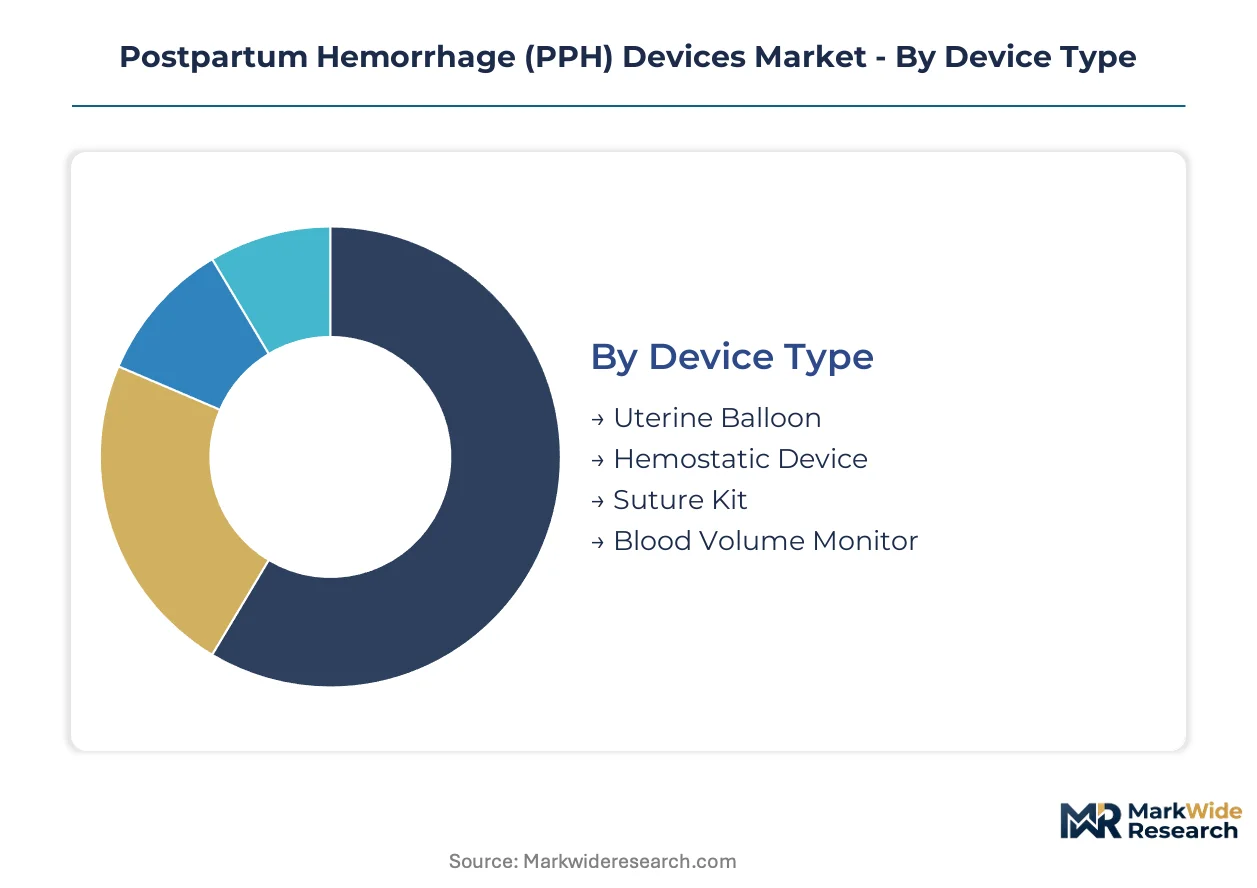
Segmentation in the PPH devices market reveals distinct procurement patterns across clinical settings, with balloon tamponade systems commanding premium service contracts while monitoring technologies drive recurring revenue streams. Understanding these divides exposes where manufacturers must build technical support infrastructure versus where standardized distribution suffices.
Device Type:
After-sales intensity varies sharply across device categories, with balloon systems requiring field training programs and hemostatic devices demanding cold-chain logistics rather than clinical support.
- Uterine Balloon:Silicone or latex catheters rated for 180-220 mmHg intrauterine pressure achieve hemostasis through direct placental bed compression. District hospitals in Uttar Pradesh and Bihar now stock these as first-line mechanical interventions under India's consolidated state health mission contracts.
- Hemostatic Device:Absorbable sponges and flowable hemostats target coagulopathic bleeding when balloon tamponade proves insufficient. PEPFAR-financed maternity units across Ethiopia's regional health bureaus prioritize these for emergency surgical backup where operating theater access remains limited.
- Suture Kit:Uterine compression sutures including B-Lynch and Hayman techniques require skilled surgical deployment with absorbable or non-absorbable materials.
- Blood Volume Monitor:Non-invasive hemoglobin spectrophotometry and arterial waveform analysis devices track hypovolemia progression.
Uterine Balloon holds the largest share; momentum sits with Blood Volume Monitor.
Application:
Cost tier stratification separates emergency settings requiring immediate mechanical intervention from postoperative monitoring where bundled reimbursement applies.
- Emergency Care:Labor ward crash carts and emergency department trauma bays stock balloon tamponade for pharmacological failure scenarios. US hospital networks are expanding device placement beyond traditional obstetric suites following FDA guidance updates on breakthrough designation pathways.
- Surgical Intervention:Peripartum hysterectomy and uterine artery ligation require specialized compression and coagulation adjuncts. Tertiary referral hospitals in Turkey and South Korea pilot integrated pressure-sensing balloon systems for high-risk delivery units.
- Obstetric Practices:Routine antenatal screening identifies hemorrhage risk factors guiding prophylactic device positioning.
- Postoperative Monitoring:Continuous hemodynamic surveillance detects delayed PPH in recovery settings.
Emergency Care dominates procedure volumes; Postoperative Monitoring is climbing the fastest as digital integration compresses detection-to-intervention timelines.
End User:
Customer type determines procurement channel structure, with centralized government tenders displacing hospital-level purchasing autonomy in high-volume markets.
- Hospitals:Tertiary academic medical centers and district general hospitals balance capital equipment budgets against consumable replenishment cycles. India's Government e-Marketplace platform now aggregates 847 facility procurements into unified supply agreements across Uttar Pradesh and Bihar state health missions.
- Maternity Clinics:Standalone birth centers and primary care maternity units prioritize non-surgical device portfolios. Sub-Saharan Africa's clinic expansion programs under Global Fund financing equip district units with standardized PPH response kits.
- Home Healthcare:Postpartum hemorrhage risk stratification and remote monitoring for high-risk home births.
- Research Institutions:Clinical trial infrastructure and device validation studies for regulatory prequalification.
Hospitals command the largest procurement volumes; Maternity Clinics show steepest expansion trajectory as maternal mortality reduction programs intensify facility equipping.
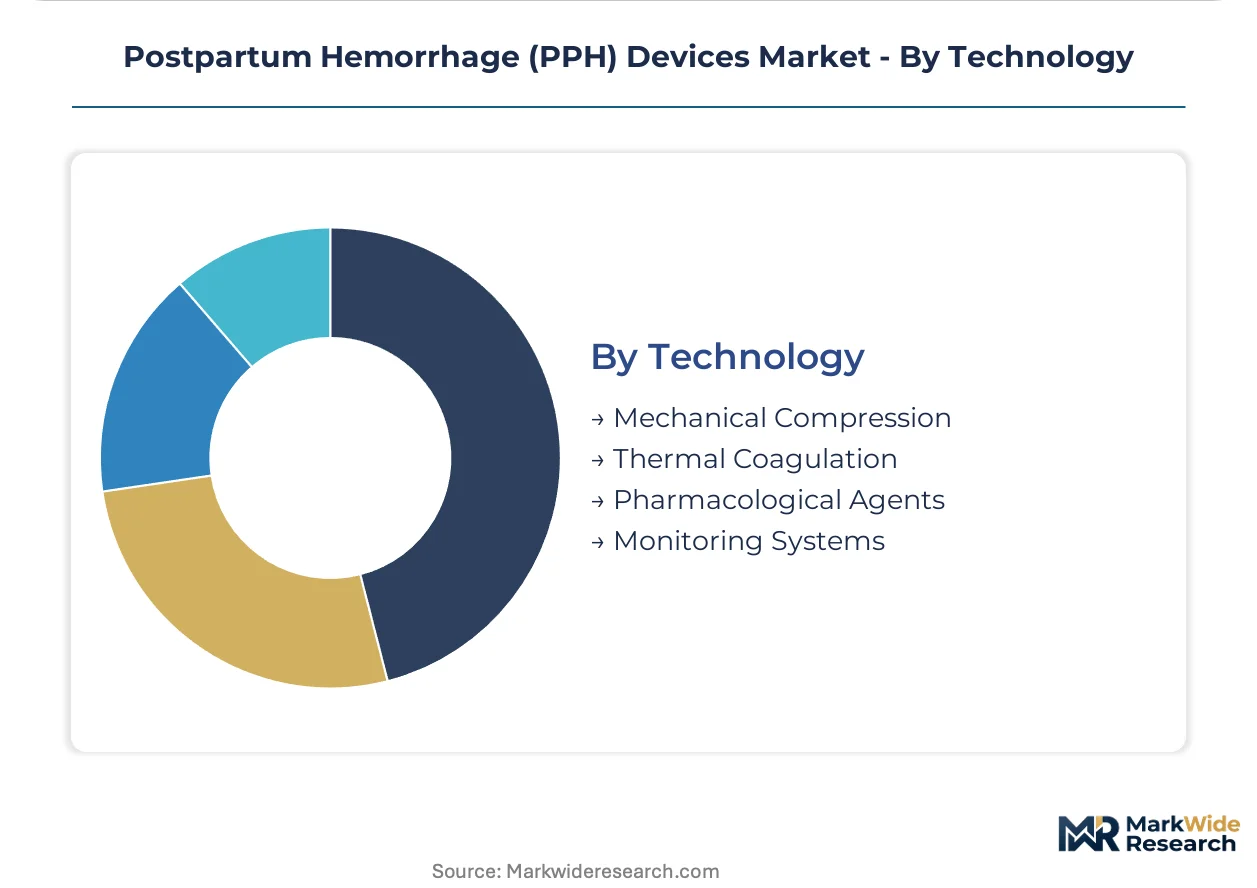
Technology:
Supply concentration clusters around mechanical compression platforms while regulatory harmonization pressures reshape competitive boundaries for integrated monitoring systems.
- Mechanical Compression:Balloon tamponade and uterine compression sutures deliver immediate physical hemostasis without pharmaceutical dependency. WHO prequalification programs for these devices compress registration timelines and force manufacturers to redesign clinical evidence packages for dual-market FDA and WHO access.
- Monitoring Systems:Hemodynamic tracking with telemedicine integration enables rural clinic deployment through real-time data transmission to referral hospitals. Condensed silicone-latex hybrid catheters with integrated pressure sensors are virtualizing capital allocation by collapsing monitoring and intervention spend into single-procedure reimbursement bundles.
- Thermal Coagulation:Bipolar vessel sealing and argon beam coagulation for surgical hemorrhage control.
- Pharmacological Agents:Uterotonic infusion pumps and tranexamic acid delivery systems adjunctive to mechanical intervention.
Mechanical Compression retains dominant share; Monitoring Systems gain share fastest as obstetric practices integrate hemodynamic tracking into standardized response protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor North American market access, while WHO prequalification programs reshape procurement eligibility across low-resource settings. National maternal health programs in India and sub-Saharan Africa are consolidating device demand through centralized tender mechanisms.
United States
Emergency departments are expanding balloon tamponade stocking beyond labor suites following updated FDA guidance on breakthrough device designations. The FDA's 2023 pathway acceleration enables parallel review processes for innovations with pediatric extension claims. Boston-area hospital networks pilot integrated pressure-sensing systems for high-risk delivery units.
India
State health missions in Uttar Pradesh and Bihar consolidated 847 facility procurements into unified supply agreements through the Government e-Marketplace platform. CDSCO regulatory harmonization with WHO prequalification timelines is compressing registration for domestic manufacturers. Production-linked incentives now attract silicone catheter suppliers to industrial corridors near Mumbai and Chennai.
Germany
The EU Medical Device Regulation mandates prospective uterine safety data that legacy balloon tamponade manufacturers must generate for CE marking renewal. Bavaria's medical-grade silicone supply clusters expose device makers to input cost volatility from concentrated raw material sourcing. Frankfurt-area distributors serve as procurement gateways for Eastern European hospital networks.
Ethiopia
The Ministry of Health's decentralized PPH kit program creates direct-to-distributor channels bypassing traditional hospital tender processes. PEPFAR and Global Fund financing equip district maternity units with standardized mechanical hemostasis devices. Addis Ababa's regional health bureaus coordinate procurement for peripheral clinics in maternal mortality reduction zones.
Brazil
ANVISA regulatory alignment with WHO prequalification standards is streamlining market entry for prequalified balloon tamponade devices. São Paulo state's unified purchasing system aggregates demand from public maternity hospitals across the Southeast region. Domestic assembly operations are emerging to serve Mercosur procurement networks with reduced import dependency.
Postpartum Hemorrhage (PPH) Devices Market Competitive Landscape
Capability concentration sits with established obstetric device specialists; scale advantage sits with diversified medical technology conglomerates. The market structures around three tiers: legacy manufacturers with deep gynecological surgery portfolios, catheter-platform specialists extending into uterine applications, and emerging domestic producers capturing government tender volumes. Strategic moves center on regulatory harmonization investments and production-linked incentive alignment in high-volume procurement markets.
Within the diversified medical technology tier, Cook Medical and Becton Dickinson exemplify scale-driven positioning through extensive obstetric product portfolios and established North American supply chain infrastructure. Teleflex Incorporated occupies a distinct position as a catheter-platform specialist whose vascular access expertise extends into compression-based uterine interventions. Utah Medical Products represents the focused-device archetype with concentrated perinatal monitoring capabilities.
| Leading Market Players |
|---|
| Cook Medical |
| Teleflex Incorporated |
| Becton Dickinson |
| Utah Medical Products |
| Organon |
| Bactiguard AB |
| Clinical Innovations |
| 3rd Stone Design |
| PATH |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone supply concentration in Northeast China and Bavaria exposes manufacturers to logistics disruptions that compress pricing spreads between premium and economy tiers while forcing dual-sourcing investments into supply chain architecture. This raw material chokepoint simultaneously elevates balloon tamponade production costs and constrains procurement flexibility for district hospitals across high-volume markets.
Pricing Analysis
Price spreads between the United States and sub-Saharan Africa exceed 300% for identical balloon tamponade devices, with three-tier pricing structure across premium, standard, and economy levels driven by WHO prequalification status and cold-chain logistics requirements. Premium tiers command certification-grade positioning for FDA-cleared and CE-marked devices, while economy tiers serve government tender markets with stripped-down packaging. Cost compression in the standard tier intensifies as Indian domestic manufacturers exploit PLI scheme subsidies to undercut import pricing. Maternity clinics in Ethiopia and Nigeria exhibit highest price sensitivity, whereas tertiary hospital networks in Turkey and South Korea absorb premium positioning for integrated pressure-sensing systems.
Supply Chain Analysis
Extended payment terms from 60 to 120 days dominate procurement contracts for Ethiopian Ministry of Health PPH kit programs, straining working capital for catheter assembly operations. Medical-grade silicone draws from Northeast China and Bavaria, while latex processing clusters in Malaysia and Thailand. Balloon catheter manufacturing feeds from precision molding equipment anchored in Germany and Japan. Single-source vulnerability pervades silicone feedstock supply, with 70% of medical-grade production concentrated in three provinces. Distribution runs through regional health bureau consolidation in India and direct-to-distributor channels in sub-Saharan Africa, bypassing traditional hospital procurement hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ISO 13485-certified manufacturing capacity with simultaneous WHO prequalification and FDA 510(k) clearance constrains competitive entry and rewards early-mover investments in dual-market regulatory infrastructure. This capability gap favors incumbents with legacy clinical evidence packages while raising barriers for emerging domestic producers.
For Market Incumbents: Entrench market position through backward integration into medical-grade silicone compounding in Bavaria or Northeast China to secure input cost stability against commodity volatility. Prioritize CE marking renewal investments under EU MDR prospective safety data requirements to defend European market access against emerging competitors lacking legacy clinical histories. Channel control through exclusive distributor agreements with India's Government e-Marketplace platform operators protects consolidated state tender participation. For New Entrants and Emerging Players: Establish a beachhead in Ethiopia's decentralized PPH kit program, where direct-to-distributor channels bypass entrenched hospital procurement relationships and price-sensitive government demand favors cost-optimized device configurations. Indonesia's national health sovereignty initiative offers tax-advantaged catheter assembly operations serving ASEAN procurement networks with reduced import dependency. Go-to-market execution should anchor on telemedicine-integrated monitoring partnerships with regional health bureaus seeking rural clinic deployment solutions. For Investors and Strategic Acquirers: The market sits at a regulatory harmonization phase that favors dual-qualified manufacturers with compressed registration timelines across FDA and WHO pathways. Long-term viability hinges on 5-10 year positioning for centralized national tender consolidation in India and sub-Saharan Africa. Acquisition targets should display catheter-platform manufacturing expertise with extensible pressure-sensor integration capabilities. The signal to watch is CDSCO regulatory alignment velocity with WHO prequalification timelines, indicating which domestic producers can capture import substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks procurement eligibility across 46 low-resource countries through national maternal health programs. |
| Domestic Manufacturing Scale-Up | PLI scheme alignment in India attracts silicone catheter suppliers to Mumbai and Chennai industrial corridors. |
| Telemedicine Integration Partnership | Enables rural clinic deployment through real-time hemodynamic data transmission to referral hospitals. |
| EU MDR Clinical Evidence Investment | Secures CE marking renewal for legacy balloon tamponade devices under prospective uterine safety mandates. |
| Centralized Tender Channel Control | Consolidates 847 facility procurements through India's Government e-Marketplace platform aggregation. |
Research Methodology
Desk research of FDA 510(k) filings, WHO prequalification databases, and Indian Government e-Marketplace tender records preceded structured interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and maternal health program procurement officers. Secondary validation drew from CDSCO registration data, EU MDR technical documentation, and PEPFAR equipment disbursement records. Bottom-up demand modeling across device categories triangulated against top-down market sizing from centralized tender aggregation.
Assumptions held regulatory harmonization timelines and raw material supply concentration fixed across the projection horizon, while varying government procurement budget trajectories and domestic manufacturing incentive intensity. Segmentation dimensions modeled include device type, application setting, end-user category, and technology platform. CAGRs derived from procedure volume elasticity to maternal mortality reduction program expansion and price trajectory analysis for tiered procurement segments. Forecast inputs incorporated skilled birth attendant density projections and telemedicine infrastructure deployment schedules.
Stress conditions across silicone supply disruption severity, EU MDR enforcement rigor, and Indian PLI scheme continuation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Oxygen Therapy Devices Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Thrombectomy System Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Minimally Invasive Deformity Correction System Market