
 Organic Polymer Electronics Market | 2026-2036
Organic Polymer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Polymer Electronics Market Outlook
Small-molecule phosphorescent emitters is hardening as the dominant emissive material in premium organic light-emitting diode stacks, displacing earlier fluorescent systems across smartphone and television panels. Samsung Display Co. Ltd leverages vertical integration across substrate supply and encapsulation to sustain cost leadership in foldable panel production. LG Display Co. Ltd anchors its position through differentiated white-OLED architectures for large-format displays. Universal Display Corporation specializes in phosphorescent emitter and host intellectual property, competing through royalty-bearing technology licensing to panel manufacturers worldwide.
Organic polymer electronics encompasses devices fabricated from carbon-based conjugated polymers and small molecules that conduct charge, emit light, or harvest energy through thin-film deposition at temperatures below 150 degrees Celsius, enabling fabrication on flexible plastic or metal foil substrates incompatible with conventional silicon processing. The primary commercial purpose centers on large-area, mechanically compliant electronics for displays, photovoltaics, and sensing surfaces where silicon brittleness and processing costs prove prohibitive. Organic LEDs within the product-type dimension command the dominant revenue share due to mature mass-production infrastructure serving smartphone and television brands, while organic photovoltaics represents the fastest-expanding category as building-integrated and indoor energy-harvesting applications scale. Flexible electronics technology leads the technology dimension in investment intensity, with organic thin-film transistors forming the backplane layer that enables conformable display and sensor formats.
REACH in Europe and the EU Green Deal constrain halogenated solvent use and mandate recyclability planning for electronics containing organic semiconductors, directly elevating compliance costs for material suppliers and panel fabricators exporting into the European Union. The EPA in the United States enforces TSCA reporting for novel polymer introductions, shaping the pace at which new emissive materials enter commercial qualification cycles. Korea's Ministry of Trade, Industry and Energy administers national display-industry support frameworks that influence capacity allocation decisions by domestic panel makers. Stakeholders must monitor divergence between Korean industrial policy, European chemical regulation, and emerging U.S. semiconductor-packaging standards to anticipate which substrate-size and material-format combinations will capture the next wave of manufacturing investment.
Market Dynamics
Solution-processed organic semiconductors are compressing thermal budgets and enabling roll-to-roll fabrication on polyethylene naphthalate substrates, fundamentally restructuring capital deployment patterns across display backplane manufacturing.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on halogenated solvents are accelerating water-based ink formulations for organic thin-film transistor deposition, forcing material suppliers to reformulate emitter host systems.
- Flexible display penetration:Smartphone manufacturers in South Korea are specifying bend-radius requirements below 3mm for foldable panels, pulling phosphorescent emitter volumes through qualified supply chains.
- Building-integrated photovoltaics:Semi-transparent organic solar cell installations on glass facades in Germany are creating demand pull for large-area module formats incompatible with silicon wafer dimensions.
Market Restraints
- Indium tin oxide dependency:Transparent electrode supply concentrates among Chinese smelters, exposing panel fabricators to price volatility and export license uncertainty.
- Encapsulation yield limits:Multilayer barrier films against oxygen and moisture ingress require atomic layer deposition sequences that throttle throughput in high-volume OLED manufacturing.
- Thermal stability ceiling:Glass transition temperatures below 120 degrees Celsius in most conjugated polymers constrain operating environments and limit automotive interior applications.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for display module assembly are attracting emitter material qualification programs from panel makers seeking tariff-advantaged export platforms.
- Wearable health patches:Conformable organic electrochemical transistor arrays for continuous glucose monitoring represent unpenetrated volume potential outside traditional display applications.
- EU Green Deal circularity:Mandated recyclability roadmaps for electronics are creating first-mover advantage for material suppliers with verified depolymerization pathways and solvent recovery systems.
Industry Challenges
- Cleanroom technician scarcity:Thin-film deposition expertise for organic semiconductor handling resides in a limited pool concentrated around Seoul and Gumi, constraining capacity expansion timelines.
- Cross-licensing complexity:Phosphorescent emitter IP thickets involving host-dopant combinations require multi-party negotiations that delay commercialization of next-generation blue emitters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Polymer Electronics Market |
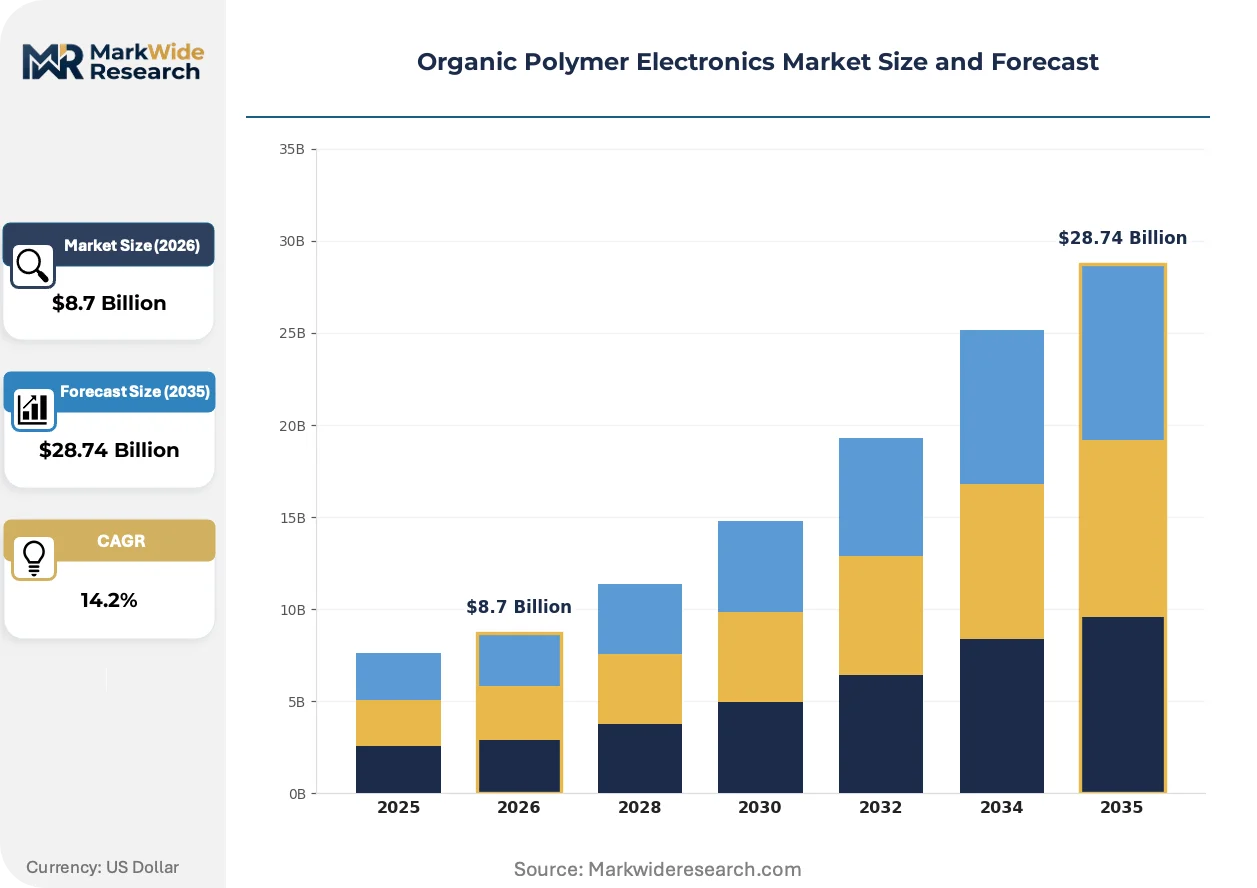
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Polymers, Organic Photovoltaics, Organic LEDs, Organic Sensors Technology: Organic Thin-Film Transistors, Organic Solar Cells, Organic Light Emitting Diodes, Flexible Electronics End User: Consumer Electronics, Automotive Applications, Healthcare Devices, Industrial Automation Application: Display Technology, Energy Harvesting, Wearable Devices, Smart Packaging |
| Companies Covered | Novaled GmbH, FlexEnable Ltd, Sony Corporation, Samsung Display Co. Ltd, LG Display Co. Ltd, AU Optronics Corp, Universal Display Corporation, BOE Technology Group Co. Ltd, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Polymer Electronics Market Strategic Shifts
Thermal evaporation equipment for small-molecule deposition is absorbing substantial capital allocation as manufacturers retool for phosphorescent emitter architectures that demand sub-nanometer thickness control across Gen 8.5 substrate sizes.
Tandem OLED stacks incorporating multiple emission layers are absorbing efficiency gains from charge-balancing architectures, with television panel specifications now requiring peak luminance above 2000 nits that single-unit cells cannot sustain. Automotive display integrators in Germany are qualifying these structures for dashboard applications where sunlight readability is mandatory. The technology is absorbing premium positioning in product portfolios as manufacturers seek differentiation through power consumption reduction rather than panel thickness alone.
ECHA's expanding SVHC candidate list for persistent organic pollutants is absorbing compliance resources across material supply chains, with fluorinated encapsulation precursors now facing substitution deadlines that compress qualification windows for alternative barrier chemistries. Korean panel exporters are pre-emptively reformulating adhesive layers to maintain EU market access ahead of 2027 restriction enactment. The regulation is absorbing disproportionate attention from legal teams relative to technical development budgets.
Direct procurement of emitter materials by brand owners rather than through panel maker intermediation is absorbing relationship restructuring across the value chain, with smartphone OEMs in South Korea establishing dedicated organic semiconductor sourcing desks that bypass traditional display supply hierarchies. This pattern is absorbing margin compression for merchant material suppliers while rewarding captive chemistry operations with volume guarantees. The shift is absorbing most visibly in flexible OLED programs where emitter performance directly determines end-product differentiation.
Organic Polymer Electronics Market Segmentation
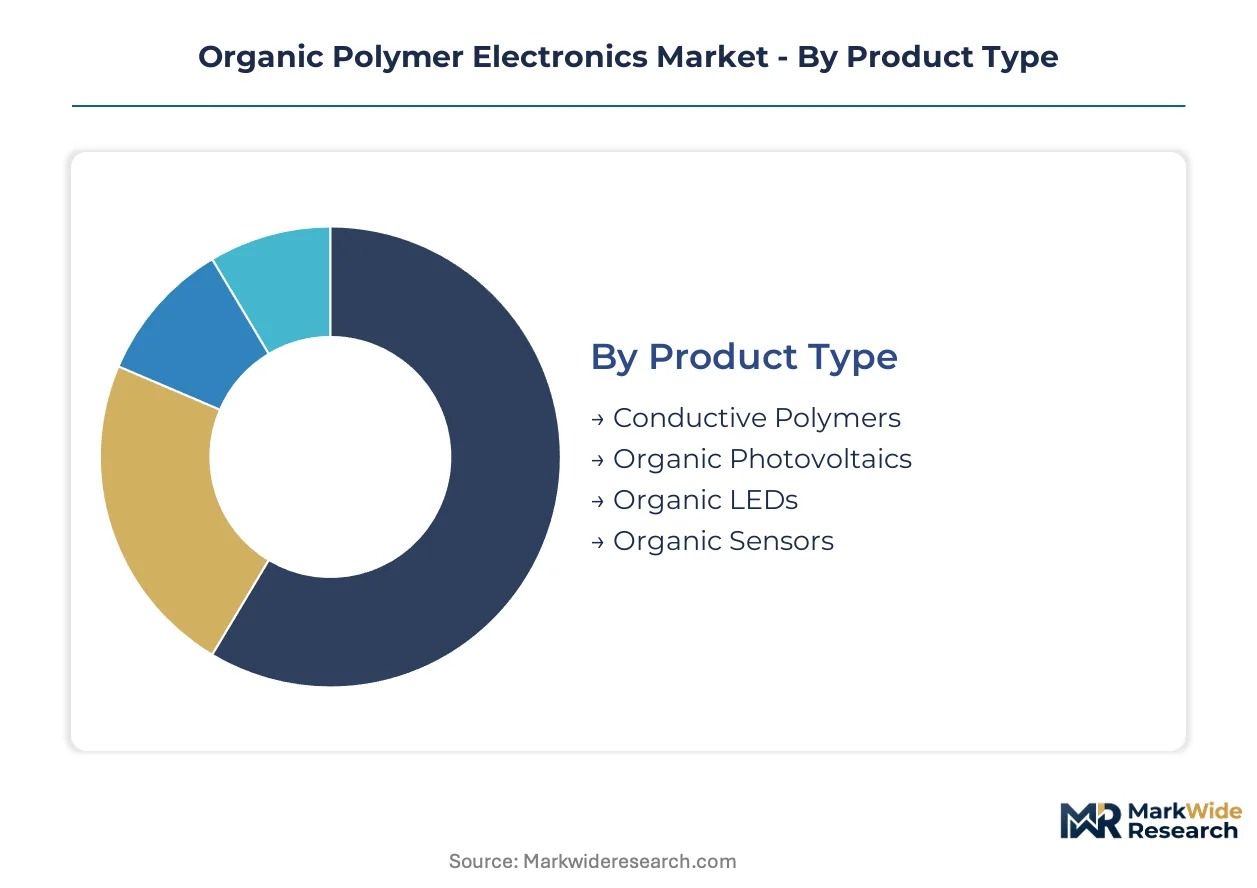
Segmentation in organic polymer electronics reveals how material properties and fabrication constraints dictate addressable markets. Each dimension carries distinct certification burdens and supply chain configurations that determine commercial viability.
Product Type:
REACH compliance in Europe and Korea's national display-industry frameworks impose divergent material qualification timelines across these segments.
- Organic LEDs:Phosphorescent emitter stacks with sub-nanometer thickness control dominate premium smartphone and television panels. Samsung Display and LG Display anchor demand concentration in Seoul and Gumi, pulling emitter volumes through qualified supply chains as foldable specifications tighten bend-radius requirements below 3mm.
- Organic Photovoltaics:Semi-transparent organic solar cells fabricated on glass or flexible substrates harvest indoor and building-integrated energy. Installations on German commercial facades are creating demand pull for large-area module formats incompatible with silicon wafer dimensions, representing the steepest expansion trajectory within this category.
- Conductive Polymers:Solution-processed formulations enable transparent electrodes and interconnect layers.
- Organic Sensors:Conformable electrochemical transistor arrays target continuous physiological monitoring applications.
Organic LEDs sit at the top of the volume ranking, with organic photovoltaics climbing the fastest.
Technology:
Capital deployment patterns diverge sharply between vacuum thermal evaporation and roll-to-roll solution processing.
- Flexible Electronics:Polyethylene naphthalate and metal foil substrates enable conformable displays and sensor formats through low-temperature fabrication below 150 degrees Celsius. Korean panel makers concentrate investment here to sustain cost leadership in foldable production.
- Organic Light Emitting Diodes:Tandem stacks incorporating multiple emission layers now achieve peak luminance above 2000 nits for television and automotive dashboard applications where sunlight readability is mandatory.
- Organic Thin-Film Transistors:Solution-processed semiconductor inks form backplane layers driving pixel switching in flexible displays.
- Organic Solar Cells:Bulk heterojunction architectures optimize donor-acceptor phase separation for power conversion efficiency.
Flexible electronics commands the largest installed equipment base, while organic solar cells are gaining share fastest in non-display applications.
End User:
Automotive qualification cycles and medical device FDA pathways create the longest commercialization timelines.
- Consumer Electronics:Smartphone and wearable brands specify emitter performance directly, bypassing traditional display supply hierarchies through dedicated organic semiconductor sourcing desks. South Korean OEMs drive volume concentration.
- Automotive Applications:Glass transition temperature ceilings below 120 degrees Celsius in most conjugated polymers currently constrain dashboard and interior lighting adoption, with German integrators qualifying tandem OLED structures for sunlight-readable displays.
- Healthcare Devices:Conformable patches for continuous glucose monitoring represent unpenetrated volume potential outside traditional display applications.
- Industrial Automation:Large-area sensor surfaces for process monitoring leverage mechanical compliance unavailable in silicon.
Consumer electronics maintains the dominant revenue position, with healthcare devices expanding most quickly as regulatory pathways mature.
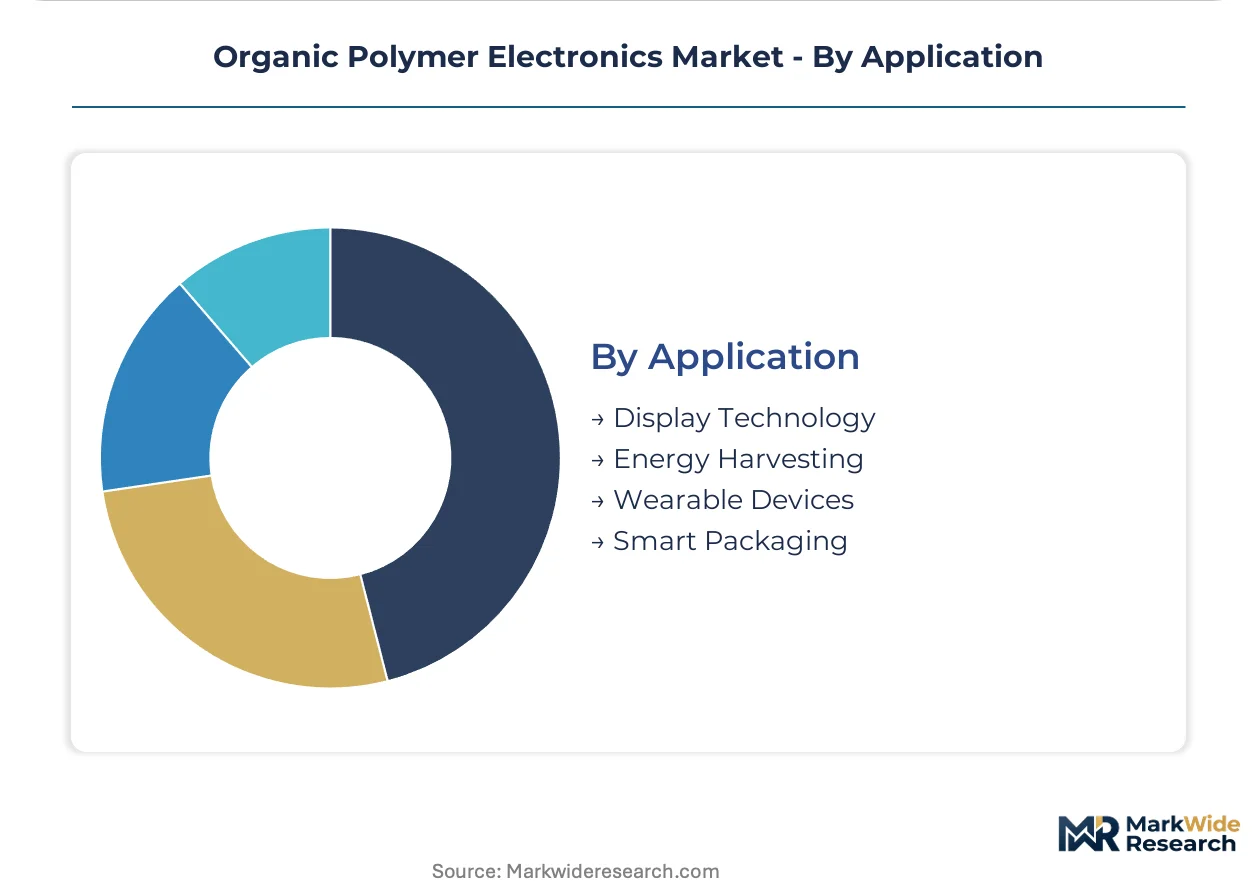
Application:
Display technology absorbs premium pricing, while energy harvesting and smart packaging compete on cost parity.
- Display Technology:Gen 8.5 substrate processing and phosphorescent emitter architectures demand the most sophisticated deposition equipment and cleanroom infrastructure. Thermal evaporation systems with sub-nanometer control absorb substantial capital allocation.
- Energy Harvesting:Indoor photovoltaic integration in IoT sensors and building facades scales through module efficiency improvements and manufacturing cost reduction.
- Wearable Devices:Skin-conformable form factors exploit polymer mechanical properties incompatible with brittle silicon alternatives.
- Smart Packaging:Printed RFID and freshness indicators target high-volume, cost-sensitive logistics applications.
Display technology leads in value concentration, with energy harvesting showing the steepest volume growth curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul-Gumi corridor concentrates the world's most sophisticated organic polymer electronics fabrication infrastructure, pulling material supply chains and cleanroom technician expertise into a tightly integrated manufacturing ecosystem.
South Korea
Foldable smartphone specifications below 3mm bend-radius drive phosphorescent emitter volumes through qualified supply chains. The Ministry of Trade, Industry and Energy administers national display-industry support frameworks influencing capacity allocation decisions by domestic panel makers. Seoul and Gumi host Samsung Display and LG Display operations that anchor global OLED production.
China
Indium tin oxide smelter concentration creates transparent electrode supply dependencies for panel fabricators worldwide. MIIT and GB standards regulate novel polymer introductions, shaping commercial qualification cycles for new emissive materials. Beijing and Shanghai house BOE Technology Group facilities expanding Gen 8.5 substrate processing capacity.
Germany
Building-integrated photovoltaic installations on commercial facades generate demand for semi-transparent organic solar cell formats incompatible with silicon dimensions. ECHA REACH restrictions on halogenated solvents accelerate water-based ink formulation development. Dresden and Leipzig clusters specialize in organic photovoltaics module assembly and barrier film research.
United States
Smartphone OEMs establish dedicated organic semiconductor sourcing desks that bypass traditional display supply hierarchies. EPA TSCA reporting requirements govern novel polymer introductions, compressing material qualification timelines. California and Arizona host Universal Display Corporation operations specializing in phosphorescent emitter intellectual property licensing.
Japan
Automotive dashboard integrators qualify tandem OLED structures for sunlight-readable displays requiring peak luminance above 2000 nits. METI industrial policy supports advanced display technology development through targeted R&D funding. Chubu and Kansai regions concentrate precision deposition equipment manufacturing and materials research.
Organic Polymer Electronics Market Competitive Environment
Global majors compete with regional champions across emitter intellectual property, substrate fabrication, and encapsulation technology dimensions. The market structure consolidates around vertically integrated display fabricators holding captive chemistry operations, while specialized material suppliers compete through royalty-bearing technology licensing. Three archetypes dominate: integrated panel manufacturers with in-house emitter production, independent phosphorescent IP licensors, and solution-processed materials specialists. Capacity expansion and strategic technology licensing represent the dominant competitive moves as firms position for next-generation blue emitter commercialization.
Within the integrated fabrication tier, Samsung Display Co. Ltd and LG Display Co. Ltd exemplify vertically structured operations spanning substrate supply through encapsulation. Universal Display Corporation occupies a position as a specialized IP licensor focused on phosphorescent emitter and host system patents. Merck KGaA represents the diversified materials supplier archetype with broad organic semiconductor portfolios. Novaled GmbH and FlexEnable Ltd sit within the technology development specialist segment, each anchored to distinct technology vectors in organic electronics.
| Leading Market Players |
|---|
| Novaled GmbH |
| FlexEnable Ltd |
| Sony Corporation |
| Samsung Display Co. Ltd |
| LG Display Co. Ltd |
| AU Optronics Corp |
| Universal Display Corporation |
| BOE Technology Group Co. Ltd |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Foldable smartphone OEMs in South Korea specifying sub-3mm bend-radius requirements are forcing phosphorescent emitter suppliers to absorb qualification costs and accelerate volume commitments, compressing margins across qualified supply chains while elevating pricing power for captive chemistry operations.
Pricing Analysis
Input-cost pass-through from indium tin oxide electrode volatility and ECHA-mandated solvent reformulation runs through material supplier contracts, with pricing stratifying across premium phosphorescent stacks, standard fluorescent systems, and economy-grade conductive polymer alternatives. Price differentiation hinges on emitter efficiency tier and REACH compliance certification level. Cost compression in standard-tier emitter supply is intensifying because Chinese ITO smelter concentration exposes panel fabricators to export license uncertainty. Consumer electronics brands with dedicated organic semiconductor sourcing desks exhibit lowest price sensitivity; merchant material suppliers serving secondary panel makers face highest procurement pressure.
Supply Chain Analysis
Cleanroom technician scarcity in Seoul and Gumi constrains capacity expansion timelines for Korean panel makers, anchoring the world's most sophisticated organic polymer electronics fabrication in a tightly integrated corridor that draws from Japanese deposition equipment manufacturers and German barrier film specialists. Raw material dependencies center on iridium-based phosphorescent emitters, high-purity indium tin oxide, and fluorinated encapsulation precursors facing ECHA substitution deadlines. Single-source vulnerability in Chinese ITO smelter concentration represents the dominant structural risk. Distribution runs through vertically integrated panel manufacturers with captive chemistry operations, bypassing traditional merchant material hierarchies as smartphone OEMs establish direct procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Korean display-industry support frameworks and European REACH compliance costs, with material suppliers capturing margin advantages by locating formulation facilities in tariff-advantaged export platforms while maintaining EU market access through pre-emptive solvent reformulation.
For Market Incumbents: Deploy backward integration into phosphorescent emitter host synthesis to defend against direct procurement encroachment by smartphone OEMs. Capture capacity expansion in India's PLI-subsidized display module assembly corridors to secure tariff-advantaged export positioning ahead of competitor qualification programs. For New Entrants and Emerging Players: Solution-processed organic thin-film transistor inks for wearable health patch applications offer the most penetrable white-space target outside traditional display supply chains. Target continuous glucose monitoring device manufacturers with conformable electrochemical transistor arrays. Pursue joint development agreements with medical device firms to bypass cleanroom technician scarcity constraints in Korean manufacturing clusters. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized phosphorescent IP licensors holding verified blue emitter host-dopant combinations, as cross-licensing complexity delays commercialization and extends royalty capture windows. Long-term viability hinges on patent estate breadth across tandem stack architectures and solvent-free deposition pathways. Watch for ECHA SVHC candidate list expansion affecting fluorinated encapsulation precursors as inflection indicator for alternative barrier chemistry valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Gen 8.5 substrate processing investments in Seoul-Gumi corridor absorb capital allocation from Samsung Display and LG Display. |
| Backward Integration | Captive phosphorescent emitter production shields Korean panel makers from direct OEM procurement encroachment. |
| Technology Licensing | Royalty-bearing phosphorescent IP agreements with Universal Display Corporation structure competitive economics for emerging panel makers. |
| Geographic Expansion | India PLI scheme incentives attract emitter material qualification programs seeking tariff-advantaged export platforms. |
| Green Manufacturing Transition | Water-based ink formulations for organic thin-film transistors respond to ECHA halogenated solvent restrictions. |
Study Parameters
Multiple input streams — primary interviews with deposition equipment engineers, material supplier R&D directors, and display procurement executives; secondary validation through ECHA regulatory filings, Korean Ministry of Trade industry support announcements, and SEC disclosures from listed panel makers; plus customs trade data for indium tin oxide and iridium precursor flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the analysis window employed segmented modeling by product type, technology platform, end-user industry, and regional regulatory cluster, with CAGRs derived from slope-logic regression against historical capacity deployment and announced fabrication investments. Forecast inputs incorporated phosphorescent emitter efficiency roadmaps, ECHA SVHC restriction timelines, and foldable panel bend-radius specification trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to blue emitter commercialization delays, indium supply disruption from Chinese export licensing, and divergence between Korean industrial policy and EU chemical regulation. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Gaas Wafer Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Semiconductor IP Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Semiconductor Clock Market
Semiconductors
United States Discrete Semiconductors Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
India Semiconductor Market
Semiconductors
Digital Semiconductors Market