
 Semiconductor Production Equipment Market | 2026-2036
Semiconductor Production Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Production Equipment Market Analysis
The shift from single-source lithography dependency to multi-source qualification strategies is restructuring procurement timelines across leading fabs. Applied Materials leverages its broad process equipment portfolio to sustain service revenue growth. ASML anchors extreme ultraviolet lithography supply through its proprietary light source architecture. Lam Research competes in plasma etch with differentiated 3D NAND tooling.
Semiconductor production equipment encompasses the specialized machinery used to fabricate integrated circuits, including systems capable of sub-7 nanometer patterning precision and atomic-scale film deposition control. This equipment enables the transformation of silicon wafers into functional chips through hundreds of sequential process steps. Lithography equipment commands the largest capital allocation share among product types due to its irreplaceable role in resolution scaling. Deposition systems and etch systems represent the fastest-expanding equipment categories as three-dimensional device architectures multiply process steps per wafer. Test equipment occupies a mature but strategically essential position in the value chain.
Export administration regulations administered by the US Department of Commerce, the EU Dual-Use Regulation, and Japan's Foreign Exchange and Foreign Trade Law collectively shape equipment market access and technology transfer boundaries. These frameworks fragment supply chains by restricting certain deposition and lithography platforms from specified destinations. Stakeholders must monitor evolving multilateral alignment on semiconductor equipment controls when assessing long-term manufacturing footprint decisions.
Market Dynamics
Advanced node lithography is automating process control across leading fabs, compressing qualification timelines while export administration regulations administered by the US Department of Commerce fragment equipment procurement corridors between allied and restricted destinations.
Growth Catalysts
- CHIPS Act subsidies:The United States is directing federal capital toward domestic fabrication facilities, accelerating foundry buildouts in Arizona and Texas. Equipment vendors are qualifying tools for these greenfield sites ahead of volume ramps.
- Gate-all-around transistor architectures:The transition from finFET to nanosheet designs multiplies deposition and etch steps per wafer. Process tool intensity rises proportionally with each additional atomic layer deposition cycle.
- Japan's Foreign Exchange and Foreign Trade Law alignment:Tokyo's tightening of deposition and lithography export licensing to specified destinations is redirecting procurement toward non-restricted vendor alternatives in South Korea and Taiwan.
Market Restraints
- Extreme ultraviolet light source scarcity:ASML's proprietary laser-produced plasma architecture remains the sole qualified source for sub-7 nanometer patterning. Single-supplier dependency creates concentration risk across Taiwan, South Korea, and Intel's Oregon operations.
- Fluorinated gas input volatility:Etch process chemistries depend on NF3 and CF4 supplies whose pricing fluctuates with energy costs and environmental levies under the EU F-Gas Regulation.
- Technical limitation in high-NA EUV resists:Chemically amplified resist platforms face resolution-line edge roughness tradeoffs at 0.33 numerical aperture, delaying full exploitation of scanner capability.
Strategic Opportunities
- India's semiconductor mission:The country's PLI scheme for electronic components is attracting foundry joint ventures in Gujarat and Assam. Tool vendors can establish early relationships before capacity commitments harden.
- Compound semiconductor expansion:Silicon carbide and gallium nitride power device fabrication requires specialized epitaxy and implant equipment distinct from silicon CMOS toolsets.
- Equipment refurbishment and secondary market formalization:Mature node fabs in Southeast Asia are creating certified pre-owned tool channels to access deposition and metrology systems at reduced capital outlay.
Industry Challenges
- Process engineer talent scarcity:Atomic-scale film deposition control and plasma etch recipe development require PhD-level specialists. Universities in Taiwan and Dresden are expanding cleanroom training programs to narrow this gap.
- Legacy tool integration with Industry 4.0 architectures:200mm fabs running 20-year-old platforms face sensor retrofit complexity when connecting to predictive maintenance networks and automated material handling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Production Equipment Market |
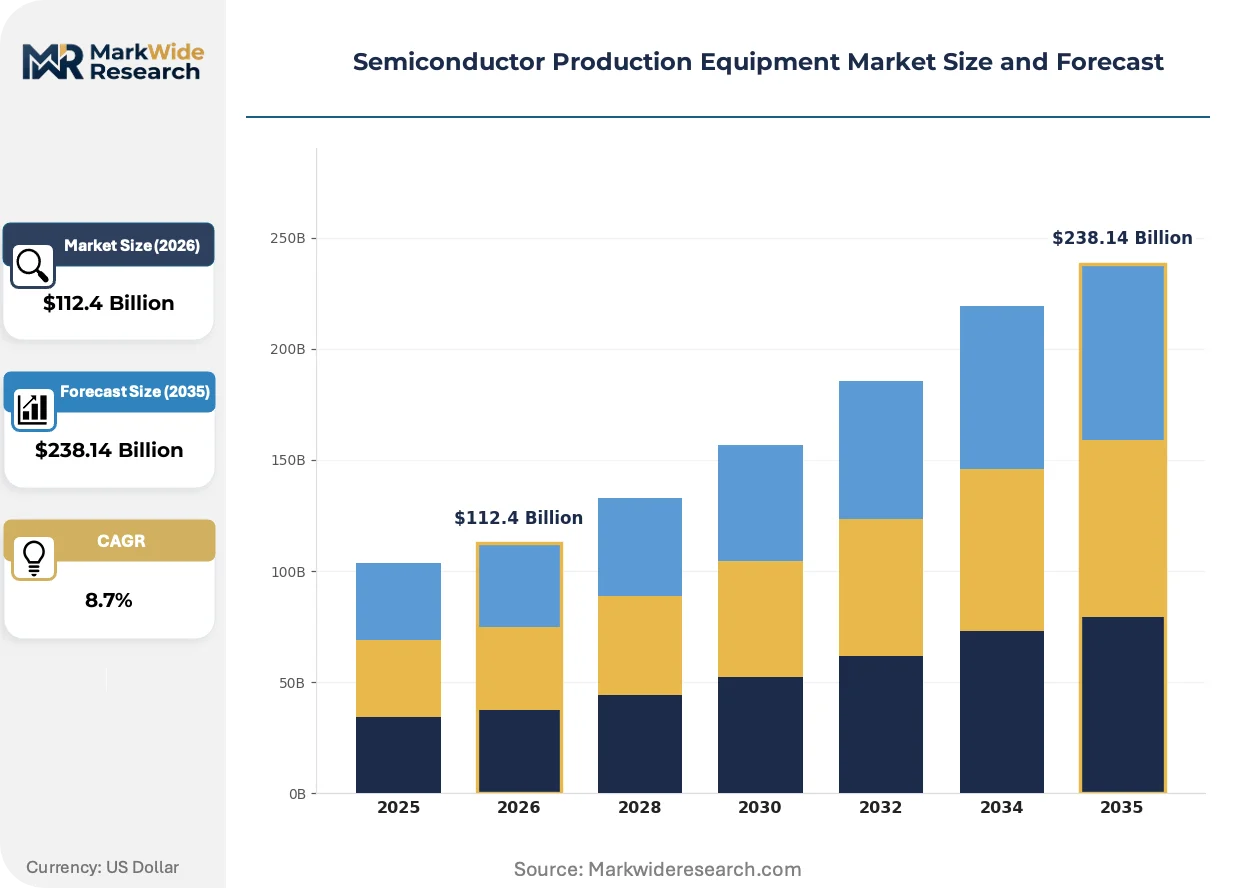
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $238.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Etch Systems, Deposition Systems, Lithography Equipment, Test Equipment End User: Foundries, IDMs, Fabless Companies, Integrated Circuits Technology: Dry Etching, Chemical Vapor Deposition, Photolithography, Atomic Layer Deposition Application: Consumer Electronics, Automotive, Telecommunications, Industrial Automation |
| Companies Covered | Applied Materials, ASML, Lam Research, Tokyo Electron, KLA Corporation, SCREEN Holdings, Teradyne, ASM International, Advantest Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Production Equipment Market Emerging Trajectories
Equipment intelligence layers are automating fault detection and classification, reducing unplanned downtime while process data feeds tighten feedback loops between lithography, etch, and deposition modules.
Machine learning inference engines deployed at the process chamber edge are automating real-time endpoint detection and predictive maintenance scheduling. Memory fabs in South Korea are adopting these systems fastest, compressing mean time to repair by enabling automated recipe adjustments before wafer scrap occurs.
The EU Dual-Use Regulation's 2024 amendments expanded licensing requirements for certain atomic layer deposition platforms and plasma etch systems with specified precision thresholds. European equipment vendors now face extended approval timelines for shipments to designated destinations, prompting some to restructure contract manufacturing footprints.
Consolidated procurement consortia among second-tier foundries are displacing individual tool qualification programs. These buyers now negotiate framework agreements covering multiple technology nodes and equipment categories, concentrating vendor management resources while demanding standardized service level agreements across lithography, deposition, and metrology platforms in Southeast Asia.
Semiconductor Production Equipment Market Segmentation
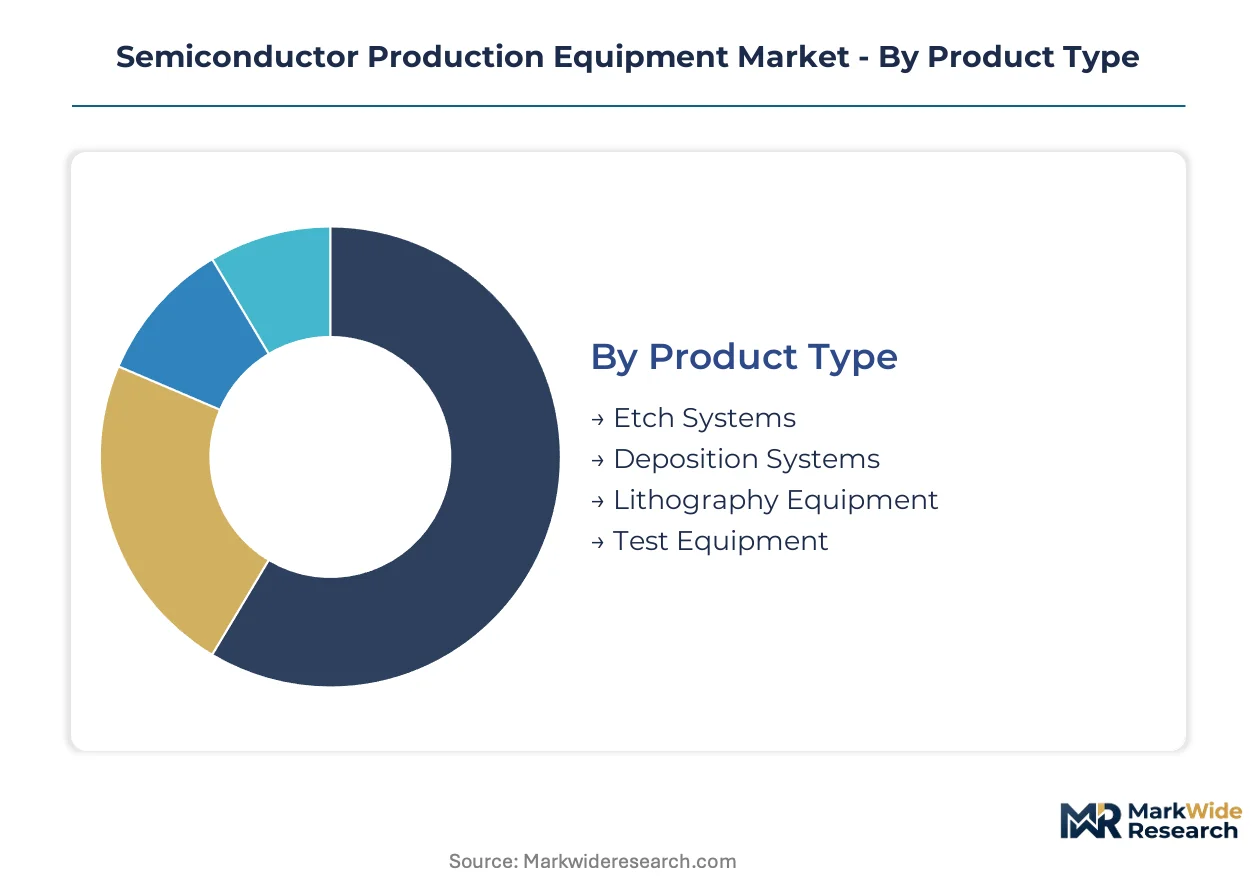
Capital allocation patterns across semiconductor fabs diverge sharply by equipment category, with lithography tools commanding single-unit costs exceeding $150 million while deposition and etch systems scale through volume deployment. Process complexity at sub-7 nanometer nodes multiplies tool intensity per wafer, reshaping procurement priorities across foundry and IDM operations.
Product Type:
Lithography equipment demands the highest upfront capital commitment per unit, with extreme ultraviolet scanners requiring dedicated facility infrastructure and vibration isolation systems that compound total installed cost.
- Lithography Equipment:Extreme ultraviolet and deep ultraviolet systems pattern silicon wafers with sub-7 nanometer resolution using proprietary laser-produced plasma light sources. Taiwan and South Korea concentrate demand as TSMC and Samsung Foundry expand advanced node capacity, though ASML's sole-supplier position creates procurement queue risks extending twelve to eighteen months.
- Deposition Systems:Atomic layer deposition and chemical vapor deposition platforms deposit angstrom-precise dielectric and metal films for gate-all-around transistor architectures. Tool intensity rises with each additional ALD cycle required for nanosheet stacking, driving fastest category expansion across Intel's Oregon and Arizona fabs.
- Etch Systems:Plasma etch chambers selectively remove material to define three-dimensional NAND string and finFET structures.
- Test Equipment:Parametric and functional test systems verify die yield before dicing and packaging operations.
Lithography equipment absorbs the bulk of installed capacity investment; deposition systems are expanding most quickly as three-dimensional architectures multiply process steps.
End User:
Purchasing power clusters by manufacturing model, with foundries committing capital in multi-billion-dollar annual cycles while fabless companies access capacity through service agreements rather than direct equipment procurement.
- Foundries:Pure-play contract manufacturers including TSMC, Samsung Foundry, and GlobalFoundries purchase equipment to service diversified customer portfolios across node generations. Taiwan and South Korea dominate capital deployment, with Arizona and Texas emerging as secondary sites under CHIPS Act subsidies that accelerate tool qualification timelines.
- IDMs:Integrated device manufacturers such as Intel and Texas Instruments combine design and fabrication operations, enabling tighter process-tool feedback loops. Memory-focused IDMs in South Korea deploy etch and deposition systems at highest density for 3D NAND string stacking, where vertical layer counts exceed two hundred.
- Fabless Companies:Design houses without captive fabrication rely on foundry capacity rather than direct equipment ownership.
- Integrated Circuits:Captive production units within diversified electronics conglomerates.
Foundries absorb the bulk of installed capacity; IDMs are gaining share fastest as Intel pursues foundry services and memory manufacturers expand 3D NAND layer counts.
Technology:
Process control requirements stratify by patterning precision, with atomic-scale deposition and sub-nanometer etch selectivity commanding premium pricing against mature dry etching platforms.
- Atomic Layer Deposition:Sequential self-limiting surface reactions enable angstrom-level thickness control for high-k gate dielectrics and metal barrier layers. South Korean memory fabs deploy ALD most intensively for 3D NAND wordline tungsten fill, where conformality requirements exceed ninety-nine percent across extreme aspect ratios.
- Dry Etching:Plasma-based material removal using fluorocarbon and halogen chemistries defines transistor gates and interconnect vias. Taiwan leads installed base volume for finFET and nanosheet profile control, though fluorinated gas supply volatility under EU F-Gas Regulation creates input cost uncertainty.
- Chemical Vapor Deposition:Thermally activated gas-phase reactions deposit polysilicon, silicon nitride, and tungsten films for interconnect and isolation structures.
- Photolithography:Optical patterning using chemically amplified resists and scanner projection systems.
Dry etching retains the bulk of installed capacity; atomic layer deposition is climbing the fastest as gate-all-around architectures multiply film stack complexity.
Application:
End-use demand concentrates where silicon content per unit rises fastest, with automotive and telecommunications applications outpacing mature consumer electronics segments.
- Automotive:Electric vehicle powertrains and advanced driver-assistance systems drive demand for silicon carbide MOSFETs and high-voltage BCD processes. Germany and Japan anchor qualification programs for automotive-grade reliability, where zero-defect requirements extend test equipment deployment.
- Telecommunications:5G baseband processors and millimeter-wave RF front-ends require finFET and silicon-germanium BiCMOS platforms. United States and South Korea lead capital commitment for sub-6 GHz and mmWave infrastructure deployment.
- Consumer Electronics:Smartphone application processors and memory modules.
- Industrial Automation:Motor drives, power supplies, and sensor interfaces.
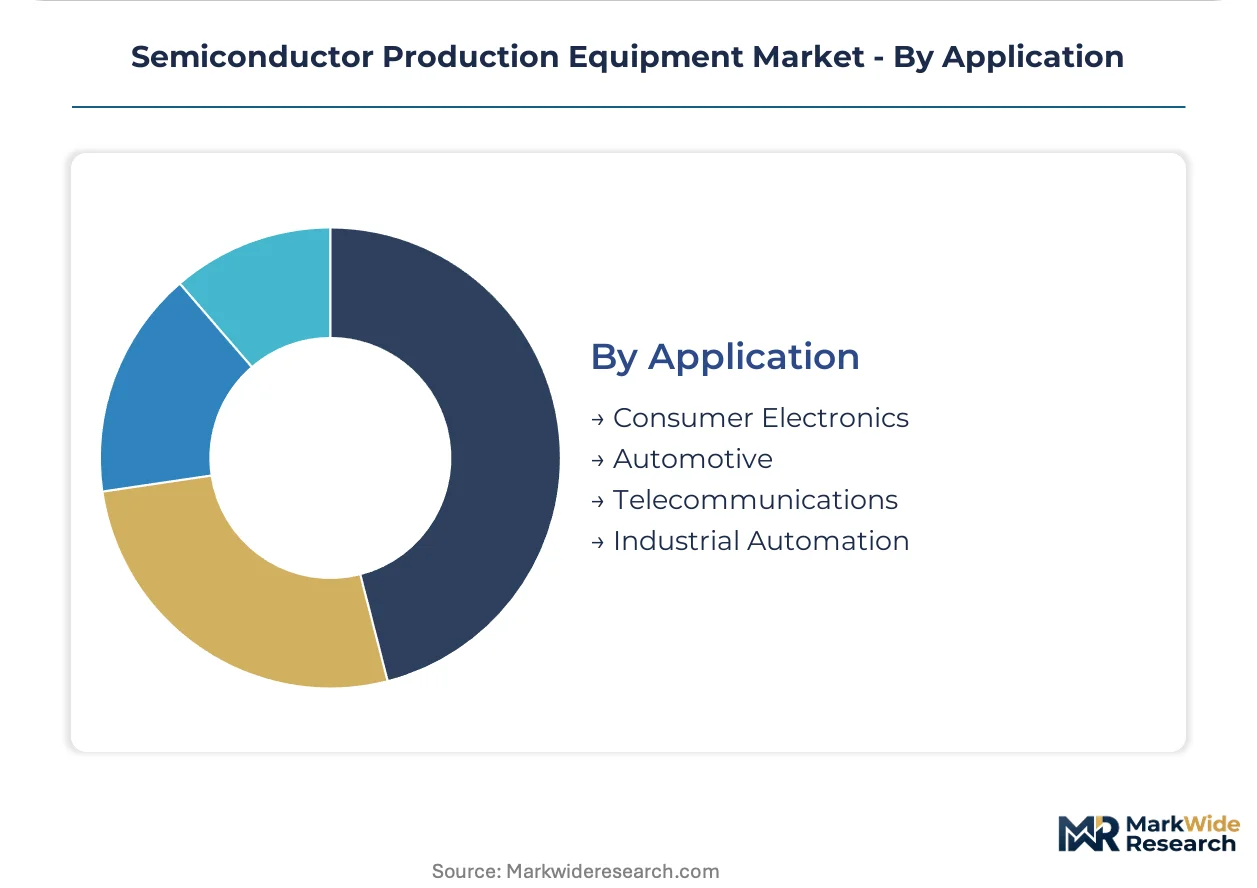
Consumer electronics retains the bulk of installed capacity; automotive is expanding most quickly as electrification multiplies semiconductor content per vehicle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer manufacturing clusters in Taiwan, South Korea, and the United States anchor equipment procurement volumes. Government subsidy programs and export control frameworks are redistributing fabrication investments across these three production centers.
Taiwan
TSMC's N3 and N2 node ramps drive lithography scanner demand exceeding twelve units annually. The National Science and Technology Council coordinates domestic equipment vendor development under the Chip Implementation Act. Hsinchu Science Park concentrates the island's largest cleanroom expansions, with new facilities breaking ground in Taichung and Kaohsiung.
South Korea
Samsung Foundry and SK Hynix deploy atomic layer deposition systems most intensively for 3D NAND wordline stacking. The Ministry of Trade, Industry and Energy allocates KRW 26 trillion through 2030 under the K-Semiconductor Belt initiative. Yongin and Pyeongtaek host memory-focused mega-fabs where vertical layer counts now exceed two hundred.
United States
Intel's Oregon and Arizona sites plus TSMC's Phoenix fab absorb the bulk of CHIPS Act equipment subsidies. The Department of Commerce administers export licensing under the Export Administration Regulations for deposition and lithography platforms. Greater Phoenix and Hillsboro anchor the largest greenfield tool qualification programs outside Asia.
Japan
Tokyo Electron and SCREEN Holdings supply etch and cleaning equipment to global foundries while domestic consumption remains modest. The Ministry of Economy, Trade and Industry tightened deposition and lithography export licensing under the Foreign Exchange and Foreign Trade Law alignment. Kyoto and Osaka prefectures concentrate precision component manufacturing for EUV light source subsystems.
China
Domestic equipment vendors serve mature node fabs as advanced lithography platforms face procurement restrictions. The Ministry of Industry and Information Technology channels investment through the National Integrated Circuit Industry Investment Fund. Shanghai and Beijing anchor indigenous tool development programs targeting 28 nanometer and above process capabilities.
Semiconductor Production Equipment Market Vendor Landscape
Portfolio diversification dominates the current landscape as equipment vendors extend service revenue streams and software attach rates. The market structure concentrates around three to five integrated platform providers controlling lithography, deposition, and etch categories. Two strategic archetypes prevail: full-stack process equipment suppliers spanning multiple fabrication steps, and specialists commanding single-point dominance in patterning or inspection. Competitive moves center on multi-year service contracts and geographic expansion into subsidized greenfield fabs.
Within the full-stack archetype, Applied Materials exemplifies breadth across deposition and etch platforms, while ASML occupies a position as the sole qualified extreme ultraviolet lithography source. Lam Research anchors the plasma etch specialist tier. These three companies represent the structural concentration that defines procurement negotiations with leading foundries.
| Leading Market Players |
|---|
| Applied Materials |
| ASML |
| Lam Research |
| Tokyo Electron |
| KLA Corporation |
| SCREEN Holdings |
| Teradyne |
| ASM International |
| Advantest Corporation |
| Others |
Supply Flow & Price Mechanics
Captive integration of EUV light source subsystems in the Netherlands and precision component manufacturing in Japan anchors both supply security and pricing power for lithography platforms. This concentration pattern forces foundries into long-term service contracts that bundle warranty coverage with predictive maintenance algorithms.
Pricing Analysis
Warranty and service-bundling arrangements dominate equipment procurement, with multi-year maintenance contracts often exceeding the initial capital outlay. Pricing stratifies across premium, standard, and economy tiers based on tool sophistication and geographic delivery complexity. Cost compression in mature node deposition systems is intensifying because certified pre-owned channels in Southeast Asia expand buyer alternatives. Memory fabs exhibit highest price sensitivity due to cyclical capacity planning, while leading-edge foundries prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and the United States shape manufacturing location decisions for precision component fabrication. The supply chain draws from fluorinated gas production in Japan, specialized ceramics in Germany, and precision optics in the Netherlands. Single-source vulnerability concentrates in ASML's laser-produced plasma architecture for EUV sources. Distribution runs through direct vendor-foundry relationships with minimal intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor production equipment sits in a technology-transition phase as gate-all-around transistor architectures displace finFET designs and multiply process tool intensity.
For Market Incumbents: Acquire atomic layer deposition specialist firms to consolidate process control expertise before independent vendors gain traction in nanosheet stacking applications. Strengthen service revenue streams through predictive maintenance software attach rates. Build captive training facilities in Dresden and Hsinchu to counter process engineer scarcity threatening tool utilization rates. For New Entrants and Emerging Players: The CHIPS Act in the United States opens a window for equipment vendors to establish early relationships with greenfield fabs in Arizona and Texas before capacity commitments harden. Target compound semiconductor epitaxy equipment for silicon carbide power devices, where incumbent tooling gaps persist. Pursue joint development agreements with India's PLI scheme beneficiaries in Gujarat to secure anchor customer status. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-stack platform providers seeking deposition and etch capability gaps. Five-to-ten year viability favors vendors with demonstrated multi-node qualification records rather than single-point technology bets. Watch for ASML's high-NA EUV shipment timing as inflection indicator for capital intensity shifts across leading fabs.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Lithography Qualification | Reduces ASML dependency risk for TSMC and Samsung Foundry procurement teams. |
| Gate-All-Around Process Tool Expansion | Multiplies ALD and etch steps per wafer at Intel's Oregon development lines. |
| India Greenfield Fab Partnership | Positions vendors before PLI scheme capacity commitments solidify in Gujarat. |
| Predictive Maintenance Platform Launch | Compresses mean time to repair for SK Hynix memory fab operations. |
| Compound Semiconductor Equipment Line | Captures silicon carbide MOSFET demand from automotive electrification programs. |
Methodological Framework
SEC filings, EU Dual-Use Regulation licensing records, and foundry capital expenditure disclosures formed the secondary backbone for this analysis. Primary interviews with fab equipment procurement directors, process engineering leads, and aftermarket service managers combined with this documentary base. Bottom-up tool shipment tallies and top-down fab capacity buildout projections were triangulated to establish market sizing.
Historical trendline analysis of capital intensity per wafer tracked node migration patterns across the projection horizon. Segmentation modeling incorporated equipment category, end-user archetype, technology precision tier, and regional regulatory cluster dimensions. CAGRs derived from equipment shipment run-rates and announced fab construction timelines, with sensitivity testing against CHIPS Act subsidy disbursement schedules and Japan's Foreign Exchange and Foreign Trade Law licensing velocity.
The model assumes a particular technology adoption path; alternative pathways for high-NA EUV resist platforms would alter the outlook for lithography scanner deployment density. Forecasts reflect assumptions regarding multilateral export control alignment and fluorinated gas supply stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Semiconductor Capital Equipment Market