
 Global Sputtering Equipment Market | 2026-2036
Global Sputtering Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sputtering Equipment Market Outlook
The EU F-Gas Regulation is decoupling European semiconductor manufacturing from high-global-warming-potential process gases, creating replacement demand for physical vapor deposition systems with smaller environmental footprints. Applied Materials leverages its installed base in logic fabs to sustain service revenue and tool upgrades. ULVAC anchors Asian display panel manufacturing with specialized large-area sputtering platforms. Kurt J. Lesker Company differentiates through its catalog breadth in research-scale systems for university and national laboratory customers.
Sputtering equipment deposits thin films by ejecting material from a target through ionized gas bombardment, typically operating at vacuum levels below 10^-3 mbar and enabling precise thickness control from nanometers to micrometers. The technology serves semiconductor interconnect metallization, optical coating, and protective wear-resistant layers across industrial applications. Magnetron sputtering dominates volume shipments due to its deposition rate advantages in production environments, while high power impulse magnetron sputtering captures growing interest for dense, low-defect coatings in aerospace turbine blade applications. RF sputtering occupies the insulating target segment where DC power supplies prove ineffective, though its lower throughput constrains it to niche optoelectronics and sensor manufacturing.
The US EPA regulates hazardous air pollutants from electronics manufacturing under the National Emission Standards for Hazardous Air Pollutants, affecting sputtering tool ventilation and abatement system design. Japan's METI promotes domestic semiconductor reshoring through subsidy programs that specify energy efficiency benchmarks for qualified deposition equipment. China's MIIT enforces GB standards for vacuum equipment safety and electromagnetic compatibility that foreign suppliers must satisfy for market access. Stakeholders must monitor how divergent regional efficiency mandates reshape equipment specification sheets and after-sales service requirements.
Market Dynamics
Semiconductor fabs are compressing interconnect pitches below 7nm while EU F-Gas Regulation forces abandonment of fluorinated greenhouse gases in deposition processes, creating simultaneous precision and environmental compliance pressures.
Growth Catalysts
- Advanced node logic expansion:Foundries in Taiwan and South Korea are adding EUV lithography capacity that requires ultra-low-resistance barrier seed layers, pulling high-throughput magnetron sputtering systems into production lines.
- EU F-Gas Regulation phase-down:The European framework mandates 98% reduction in hydrofluorocarbon emissions by 2050, eliminating chemical vapor deposition alternatives and redirecting capex toward physical vapor deposition platforms.
- High-bandwidth memory stacking:Three-dimensional DRAM architectures demand atomic-layer-precise tungsten and ruthenium metallization, expanding sputtering duty cycles in memory fabs.
Market Restraints
- Target material cost volatility:Tantalum and ruthenium supply concentrates in Central African mining operations, exposing consumables budgets to geopolitical disruption and price spikes.
- Technical throughput ceilings:RF sputtering for insulating targets operates at deposition rates one-tenth of DC magnetron configurations, constraining scale-up in optoelectronics manufacturing.
- Abatement system retrofit burden:Legacy tools require nitrogen trifluoride destruction unit upgrades to meet EPA National Emission Standards, extending payback periods for installed base refresh decisions.
Strategic Opportunities
- Indian semiconductor subsidy window:The country's PLI scheme for electronics manufacturing specifies domestic value-add thresholds, creating first-mover positioning for deposition equipment localized assembly.
- Aerospace turbine blade coating:High power impulse magnetron sputtering is expanding into thermal barrier deposition for single-crystal superalloys, displacing electron beam physical vapor deposition in aviation MRO networks.
- Japan METI reshoring incentives:Subsidy programs for Kumamoto and Hokkaido fab clusters prioritize energy-efficient vacuum equipment, advantaging next-generation sputtering platforms with regenerative power supplies.
Industry Challenges
- Vacuum technician scarcity:Semiconductor fabs face 18-month backlogs for trained cryogenic pump maintenance specialists, extending unplanned downtime intervals.
- Legacy tool integration friction:New cluster tools must interface with 200mm wafer handling systems from the 1990s, requiring custom mechanical adapters that delay qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sputtering Equipment Market |
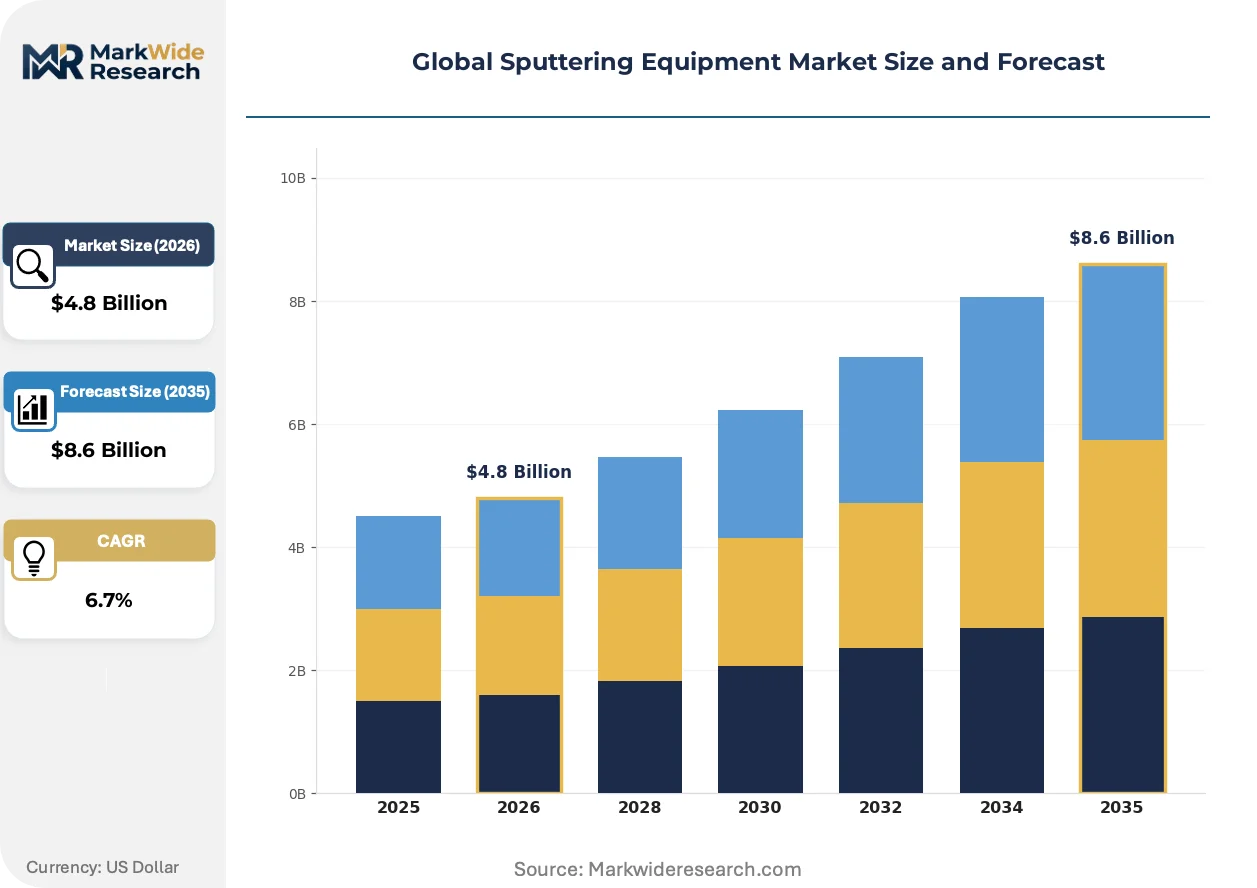
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetron Sputtering, DC Sputtering, RF Sputtering, High Power Impulse Magnetron Sputtering End User: Semiconductors, Optoelectronics, Aerospace, Data Storage Technology: PVD, CVD, ALD, Sputter Deposition Application: Thin Film Coating, Decorative Coating, Solar Cells, Sensors |
| Companies Covered | Applied Materials, Veeco Instruments, Kurt J. Lesker Company, ULVAC, OC Oerlikon, Canon Anelva Corporation, Semicore Equipment, Bühler AG, Impact Coatings AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sputtering Equipment Market Strategic Shifts
Equipment architectures are converging around modularity and predictive maintenance, while regulatory pressure and buyer consolidation reshape competitive differentiation.
High power impulse magnetron sputtering is expanding into aerospace and medical implant manufacturing by delivering ionization levels exceeding 90% for dense, adherent coatings. Tier-one aviation suppliers in France and Germany are qualifying these systems for low-pressure turbine blade thermal protection. The technology is expanding into markets previously served by electron beam physical vapor deposition, compressing equipment supplier margins in legacy coating segments.
China's MIIT enforcement of GB standards for vacuum equipment electromagnetic compatibility is compelling foreign suppliers to establish in-country testing partnerships. The regulation mandates conducted emissions limits below 30 MHz that exceed IEC baseline specifications. European and Japanese equipment vendors are responding by pre-certifying control cabinets through Shanghai-based compliance laboratories, adding six-month lead times to standard delivery schedules.
After-sales service unbundling is fragmenting traditional revenue streams as foundries negotiate predictive maintenance algorithms separately from hardware contracts. Taiwan-based buyers now demand API access to vacuum pump vibration data for integration into proprietary factory automation systems. This pattern is most visible in Hsinchu Science Park operations, where equipment vendors face pressure to open sensor architectures or sacrifice renewal rates.
Global Sputtering Equipment Market Segmentation
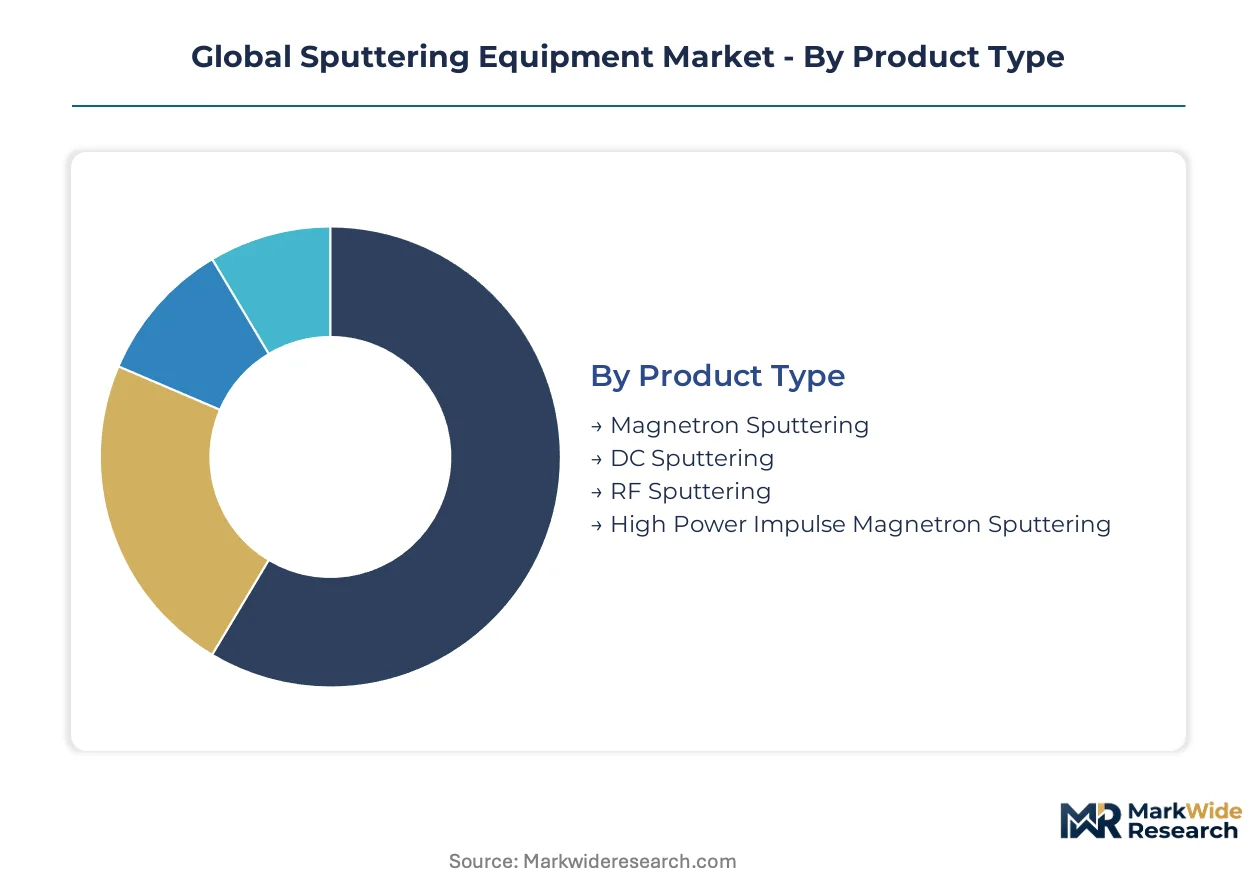
Equipment specification varies sharply across deposition physics and end-use precision requirements. Buyers select platforms based on film thickness tolerance, substrate compatibility, and integration with existing fab automation layers.
Product Type:
Magnetron configurations dominate wafer-throughput economics while pulsed-power architectures command premium pricing for defect-sensitive applications.
- Magnetron Sputtering:Permanent magnet arrays confine plasma near target surfaces, boosting ionization efficiency and deposition rates by an order of magnitude over planar diode configurations. Taiwan foundries specify these systems for copper barrier-seed layers at advanced logic nodes where wafer-per-hour metrics determine line economics.
- High Power Impulse Magnetron Sputtering:Microsecond-duration pulses at kilowatt peak power generate plasma densities exceeding 10^18 ions per cubic meter, enabling fully ionized flux for conformal coating of high-aspect-ratio features. Aerospace turbine blade manufacturers in France and Germany are qualifying these platforms for thermal barrier deposition previously served by electron beam physical vapor deposition.
- DC Sputtering:Direct-current power supplies drive conductive target sputtering for metal interconnect layers at lowest equipment cost.
- RF Sputtering:Radio-frequency excitation overcomes insulating target charge accumulation, restricting deployment to dielectric optical coatings and piezoelectric sensor manufacturing.
Today's leader: Magnetron Sputtering. Tomorrow's challenger: High Power Impulse Magnetron Sputtering.
End User:
Semiconductor fabs drive equipment refresh cycles while aerospace qualification timelines stretch replacement revenue recognition.
- Semiconductors:Logic and memory fabs deploy cluster tools with multiple sputtering chambers for sequential barrier-adhesion-seed deposition. South Korea and Taiwan account for dominant demand concentration as EUV lithography deployment pulls ultra-low-resistance metallization requirements.
- Aerospace:Engine OEMs and MRO networks specify high-power impulse systems for thermal barrier coating of single-crystal superalloy turbine blades. Qualification protocols extend sales cycles but lock in decade-long consumables and service relationships.
- Optoelectronics:LED and laser diode manufacturers utilize sputtering for distributed Bragg reflector stacks and transparent conductive oxide layers.
- Data Storage:Hard disk drive media fabrication requires precise magnetic layer stacking on aluminum or glass substrates.
Semiconductor fabs absorb the highest equipment unit volumes. Aerospace applications generate the steepest expansion trajectory for high-value system configurations.
Technology:
Sputter deposition platforms compete with chemical vapor deposition for film uniformity, trading throughput for lower thermal budget and reduced precursor toxicity.
- Sputter Deposition:Physical vapor transport from solid targets eliminates liquid or gaseous precursor handling, simplifying abatement and reducing EPA National Emission Standards compliance burden for US-based electronics manufacturing.
- PVD:Broad category encompassing evaporation and sputtering techniques, with sputtering subsuming dominant share in semiconductor metallization.
- CVD:Chemical vapor deposition delivers superior step coverage for high-aspect-ratio features but faces EU F-Gas Regulation pressure on fluorinated greenhouse gas emissions.
- ALD:Atomic layer deposition achieves angstrom-level thickness control for gate dielectrics and emerging memory selectors, competing at the precision frontier.
Sputter Deposition anchors current fab capacity. ALD platforms are climbing the fastest in memory-specific metallization applications.
Application:
Thin film functional coatings generate recurring revenue through target consumables while decorative applications concentrate in lower-margin batch tooling.
- Thin Film Coating:Semiconductor interconnects, optical filters, and protective wear layers demand thickness uniformity below 5% across 300mm wafers or meter-scale substrates. Japan's display panel manufacturers specify large-area sputtering platforms for indium tin oxide deposition on Gen 10.5 glass.
- Solar Cells:Cadmium telluride and copper-indium-gallium-selenide photovoltaic manufacturing requires sequential sputtering of multiple compound semiconductor layers. China's MIIT domestic content requirements favor locally assembled deposition equipment for gigawatt-scale cell fabrication.
- Decorative Coating:Architectural hardware and consumer electronics utilize titanium nitride and chromium nitride sputtering for abrasion-resistant aesthetic finishes.
- Sensors:MEMS accelerometers, pressure transducers, and gas detection elements employ sputtered piezoelectric and catalytic metal layers.
Thin Film Coating commands the installed base. Solar Cell applications are expanding most quickly on renewable energy manufacturing subsidies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sputtering equipment manufacturing traces its industrial lineage to post-war vacuum technology development in the United States and Japan, with subsequent scaling concentrated in East Asian semiconductor corridors.
United States
Domestic demand flows from Intel's Arizona and Oregon fabrication expansions plus Department of Defense trusted foundry programs. EPA National Emission Standards for Hazardous Air Pollutants mandate nitrogen trifluoride abatement retrofits on legacy tools. Greater Phoenix anchors Intel's $20 billion advanced packaging campus, pulling high-throughput cluster tools into production qualification.
Taiwan
TSMC's N2 and N3 node ramps consume barrier-seed sputtering systems for copper interconnect scaling. The island's EPA enforces volatile organic compound emission caps on electronics manufacturing equipment. Hsinchu Science Park concentrates foundry capex, where Applied Materials and ULVAC compete for chamber upgrade contracts tied to EUV lithography deployment.
South Korea
Samsung Electronics and SK Hynix expand DRAM and NAND capacity requiring atomic-layer-precise ruthenium metallization. METI-style efficiency benchmarks from Seoul's Ministry of Trade, Industry and Energy favor regenerative power supply configurations. Pyeongtaek's semiconductor cluster absorbs the highest unit volumes of magnetron systems for memory-specific deposition cycles.
Japan
Canon Anelva and ULVAC supply domestic reshoring initiatives while exporting to Asian foundries. METI subsidy programs for Kumamoto and Hokkaido fab clusters specify energy efficiency thresholds for qualified vacuum equipment. Kyushu's Silicon Island hosts Rapidus's 2nm pilot line, importing specialized high-power impulse systems for advanced interconnect development.
China
Domestic equipment procurement accelerates under MIIT domestic content requirements for memory and logic fabs. GB standards for electromagnetic compatibility mandate conducted emissions below 30 MHz, compelling foreign vendors through Shanghai certification laboratories. Yangtze River Delta fabs in Shanghai and Wuxi drive replacement demand as US export controls constrain tool access.
Global Sputtering Equipment Market Competitive Environment
Capital-heavy integrated equipment manufacturers compete with asset-light specialists designing modular subsystems for licensed production. The market structure consolidates around three tier-one vendors controlling wafer-processing platform architectures, while mid-tier specialists fragment across research-scale and display-panel niches. Strategic archetypes span full-stack platform vendors, consumables-anchored service integrators, and application-specific technology licensors. Competitive moves concentrate on predictive maintenance algorithm unbundling and regional certification pre-positioning.
Among diversified industrial conglomerates, OC Oerlikon and Bühler AG occupy positions spanning precision coating equipment into adjacent surface engineering markets. Applied Materials anchors the premium-tier logic fab segment through installed base leverage, while ULVAC exemplifies the display-specialist archetype with large-area platform dominance. Kurt J. Lesker Company represents the research-scale catalog breadth model serving university and national laboratory procurement channels.
| Leading Market Players |
|---|
| Applied Materials |
| Veeco Instruments |
| Kurt J. Lesker Company |
| ULVAC |
| OC Oerlikon |
| Canon Anelva Corporation |
| Semicore Equipment |
| Bühler AG |
| Impact Coatings AB |
| Others |
Value Chain & Pricing Dynamics
Captive magnetron cathode production by Applied Materials and ULVAC anchors both supply security and pricing power for high-throughput wafer processing platforms. This backward integration into consumables manufacturing insulates tier-one vendors from tantalum and ruthenium spot volatility while forcing mid-tier competitors to absorb target material cost swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EUV-compatible cluster tools from refurbished legacy systems and research-scale benchtop units. Price differentiation rests on chamber count and automation integration, with Taiwan foundries least sensitive due to EUV lithography pull-through economics. Cost compression in standard-tier magnetron systems is intensifying because Chinese domestic vendors are qualifying GB-compliant alternatives. Research laboratories exhibit highest price sensitivity, driving catalog discounting for Kurt J. Lesker and Semicore benchtop configurations.
Supply Chain Analysis
Single-source vulnerability sits with Central African tantalum concentrate and Russian ruthenium sponge refining, exposing consumables budgets to geopolitical disruption. Equipment manufacturing draws from Japanese permanent magnet arrays, German turbo-molecular pump assemblies, and US RF power supply modules. Tariff exposure on Chinese steel vacuum chambers is forcing Southeast Asian final assembly migration. Distribution runs through direct foundry account teams for semiconductor fabs and regional distributors for research and aerospace customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sputtering Equipment Market compounds steadily as EU F-Gas Regulation phase-down mandates physical vapor deposition capex redirection across European semiconductor manufacturing.
For Market Incumbents: Deploy predictive maintenance algorithm unbundling to defend renewal rates against Taiwan foundry demands for API-accessible vacuum pump data. Incumbents should deepen backward integration into ruthenium target recycling to offset Central African supply concentration risk. Canon Anelva and ULVAC must accelerate Kumamoto and Hokkaido localization to capture METI reshoring subsidies before qualification windows close. For New Entrants and Emerging Players: Enter via aerospace turbine blade coating qualification in France and Germany, where high power impulse magnetron sputtering displaces electron beam physical vapor deposition with decade-long consumables lock-in. India's PLI scheme for electronics manufacturing offers first-mover positioning for domestic assembly of research-scale systems below tariff thresholds. Target university procurement channels with modular platforms supporting rapid target exchange for materials science departments. For Investors and Strategic Acquirers: Roll-up economics work for consumables-anchored service integrators because foundry consolidation is compressing equipment vendor count while expanding aftermarket revenue pools. Five-to-ten year viability hinges on EU F-Gas Regulation enforcement trajectory and Chinese domestic equipment substitution rates. Watch for inflection in Hsinchu Science Park cluster tool upgrade cycles as TSMC N2 node ramps accelerate chamber refresh decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Algorithm Licensing | TSMC and Samsung demand API access to vibration data for factory automation integration. |
| Ruthenium Target Recycling Infrastructure | Canon Anelva and ULVAC secure consumables margin against Central African supply disruption. |
| India PLI Scheme Localization | Domestic assembly thresholds qualify equipment vendors for electronics manufacturing subsidies. |
| Aerospace MRO Network Qualification | Safran and MTU Aero Engines validate high power impulse systems for turbine blade coating. |
| Shanghai EMC Pre-Certification | European and Japanese vendors add six-month lead times to satisfy MIIT GB standards. |
Study Parameters
Multiple input streams — equipment vendor technical specifications, foundry capex disclosure filings, and national subsidy program documentation — were reconciled through structured primary interviews and secondary validation. Conversations with vacuum equipment engineering directors, semiconductor fab procurement managers, and aerospace coating specialists supplied qualitative demand parameters. Secondary sources included EPA National Emission Standards regulatory texts, METI subsidy program guidelines, MIIT GB standard certifications, and customs trade data for sputtering target material flows. Bottom-up unit economics and top-down sectoral allocation were cross-checked for triangulation.
Data-stream reconciliation across product type, end user, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. Segmentation modeling captured magnetron versus high power impulse power supply configurations, logic versus memory fab deposition cycles, and EU F-Gas versus EPA emission compliance pathways. CAGRs were derived from installed base refresh rates, node transition timelines, and subsidy program budget allocations. Forecast inputs incorporated EUV lithography deployment schedules and aerospace thermal barrier coating qualification protocols.
Inputs from equipment vendor order backlogs and foundry construction permits were available through the study window; gaps in Chinese domestic equipment market share data introduce uncertainty bands around MIIT substitution rate assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and node transition cadences. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Focused Ion Beam Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Photolithography Market