
 Automatic Flip Chip Bonders Market | 2026-2036
Automatic Flip Chip Bonders Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Flip Chip Bonders Market Insights
Market Context
South Korea is narrowing the gap with Taiwan in advanced packaging equipment deployment as Samsung Foundry and SK Hynix expand flip chip capacity at Pyeongtaek. ASMPT leverages its die bonder portfolio to sustain technology leadership in high-accuracy placement systems. BESI anchors European supply through precision thermocompression platforms for automotive-grade modules. Kulicke & Soffa competes aggressively on cost-adjusted throughput for mid-range consumer electronics applications.
Technical Definition and Segment Structure
An automatic flip chip bonder is a precision assembly system that inverts bare semiconductor dies and aligns them face-down onto substrates using solder bumps, gold studs, or copper pillars with placement accuracy typically below 5 micrometers, enabling high-density electrical interconnection for advanced packaging. Multi-array configurations command premium positioning as heterogeneous integration demands parallel processing of chiplets in AI accelerator and 5G baseband modules. Die bonding technology leads volume shipments across consumer electronics and telecommunications, while wafer-level packaging segments capture outsized margin pools as IDMs and foundries migrate fan-out and 3D stacking workflows from research organizations into contract manufacturer production lines.
Regulatory Environment and Outlook
Japan's METI coordinates domestic equipment standards through JIS certification requirements that constrain non-compliant imports, while South Korea's MFDS and K-Battery regulations indirectly shape cleanroom and materials-handling specifications for automotive electronics bonders. The EU F-Gas Regulation and REACH chemical restrictions are tightening flux and underfill material compliance burdens for European-bound equipment. Stakeholders must monitor how China's SAMR GB standards evolve for dual carbon-aligned equipment efficiency metrics, as these will determine market access trajectories for foreign bonder suppliers serving domestic contract manufacturers.
Market Dynamics
Chiplet architectures are forcing equipment suppliers to reconfigure placement systems for parallel die handling, as heterogeneous integration shifts bonders from single-die to multi-array processing platforms.
Growth Catalysts
- Automotive electronics qualification:ADAS modules and EV powertrain controllers require automotive-grade flip chip assembly, expanding addressable equipment demand beyond consumer handsets.
- MIIT dual carbon alignment:China's energy efficiency mandates for semiconductor manufacturing equipment accelerate replacement cycles among domestic contract manufacturers.
- Copper pillar migration:Foundries are transitioning from solder bump to copper pillar interconnects, necessitating higher-force thermocompression bonders with sub-3-micron accuracy.
Market Restraints
- Precision motion component concentration:Linear motors and air-bearing stages rely heavily on Japanese and German suppliers, creating input bottlenecks during demand surges.
- EU F-Gas compliance costs:REACH and F-Gas restrictions on flux chemistries force equipment redesigns for European-bound systems, extending validation timelines.
- Plasma dicing substitution:Laser-based stealth dicing and plasma etching approaches threaten mechanical die singulation, reducing downstream bonder throughput requirements in some packaging flows.
Strategic Opportunities
- India semiconductor ecosystem:PLI scheme incentives for display and semiconductor manufacturing create first-mover positioning for bonder suppliers establishing local service infrastructure.
- Photonics packaging convergence:Silicon photonics transceivers for AI clusters combine optical and electrical die assembly, opening specialized multi-process bonder configurations.
- Wafer-level fan-out expansion:IDMs are migrating embedded die packaging from research to high-volume production, requiring bonders compatible with reconstituted wafer handling.
Industry Challenges
- Multi-physics simulation expertise:Thermomechanical modeling for chiplet warpage prediction requires scarce talent pools combining packaging engineering and computational mechanics.
- Cleanroom retrofit complexity:Legacy fabs face floor-loading and vibration isolation constraints when upgrading to next-generation high-accuracy bonders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Flip Chip Bonders Market |
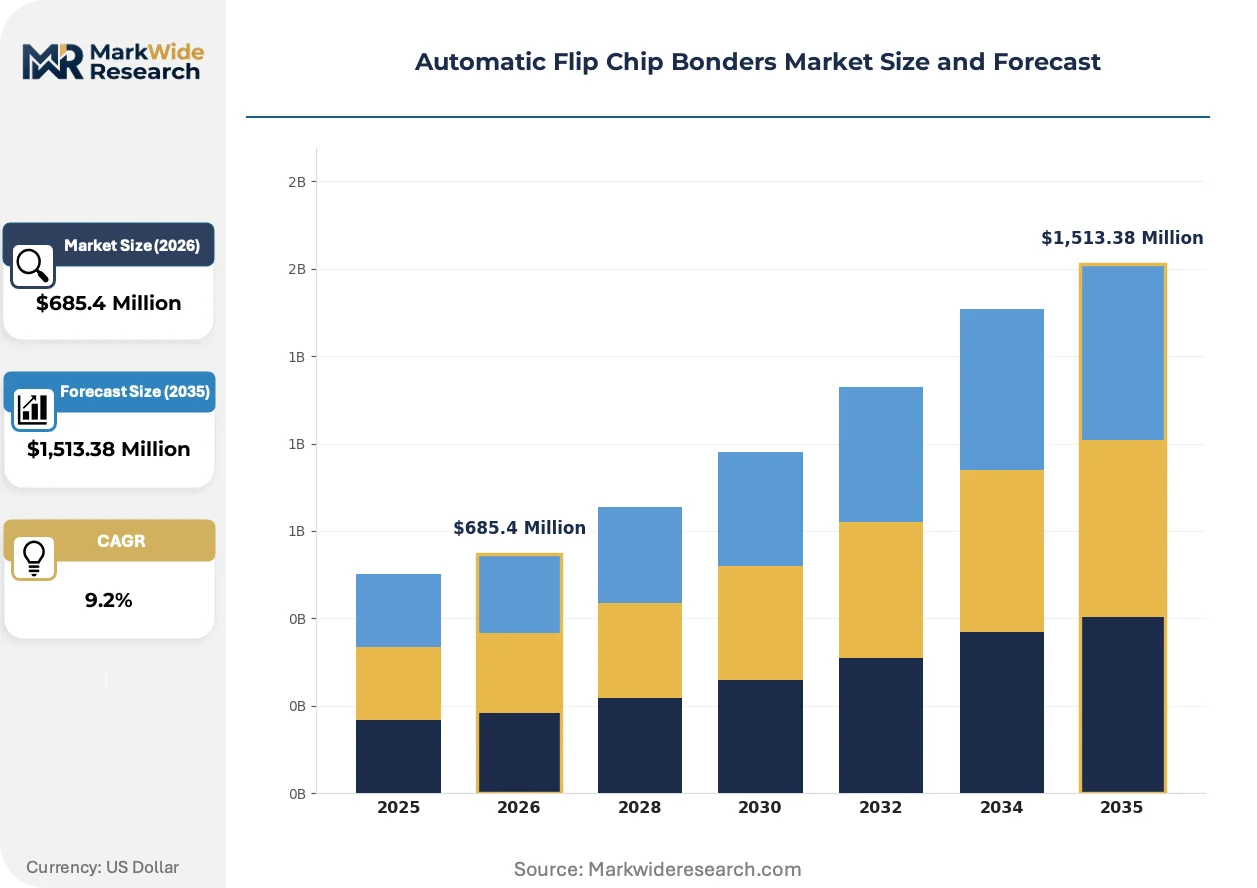
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,513.38 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Array, Dual Array, Multi-Array, Custom Design Application: Consumer Electronics, Telecommunications, Automotive Electronics, Industrial Automation End User: OEMs, Contract Manufacturers, Research Organizations, Electronic Component Suppliers Technology: Die Bonding, Chip-on-Board, Flip Chip, Wafer-Level Packaging |
| Companies Covered | ASMPT, BESI, Kulicke & Soffa, SHIBUYA CORPORATION, Hamni, Muehlbauer, AMICRA Microtechnologies, Shibaura, SET, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Flip Chip Bonders Market Trends and Innovations
Thermocompression bonding is converging with mass reflow techniques as equipment architectures adapt to mixed interconnect requirements across AI accelerators and automotive modules.
Hybrid bonding technology is hybridizing conventional thermocompression with direct copper-to-copper bonding for 3D stacking applications. Memory manufacturers at Pyeongtaek and Hsinchu are piloting these systems for HBM4 production ramps. The approach is compressing equipment supplier R&D cycles as die-to-wafer and wafer-to-wafer variants require divergent handling mechanisms.
Japan's METI has tightened JIS certification requirements for semiconductor manufacturing equipment, mandating traceable calibration protocols for placement accuracy. Domestic suppliers gain preferential access to NEDO-funded advanced packaging consortia. Foreign bonder manufacturers must establish local validation centers to maintain qualification status for Japanese IDM procurement lists.
IDM procurement teams are consolidating vendor relationships from equipment-specific to platform-level agreements covering die bonders, inspection systems, and process software. This consolidation is displacing standalone equipment vendors in favor of integrated solution providers with captive process development capabilities. South Korean memory houses have pioneered this model, now spreading to Taiwan foundry operations.
Automatic Flip Chip Bonders Market Segmentation
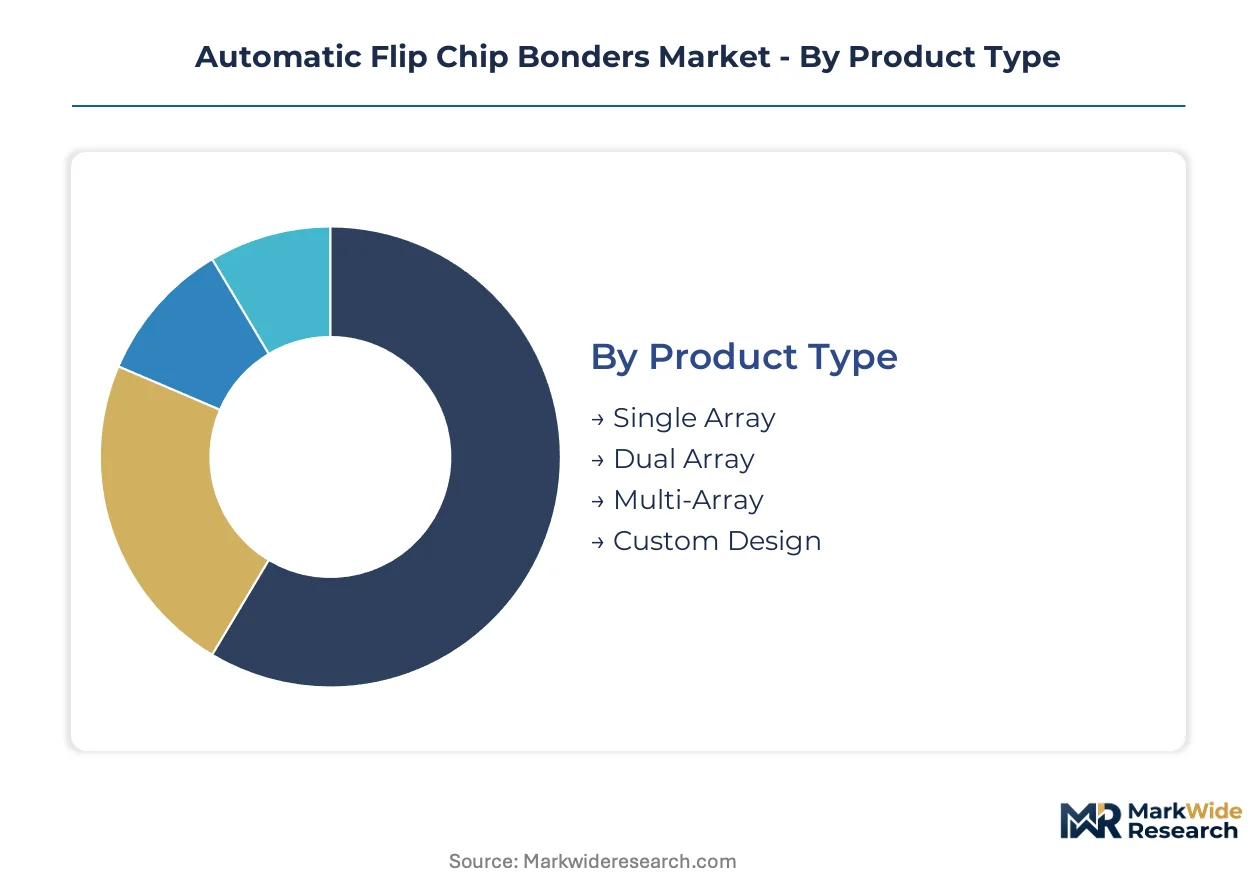
Equipment configuration and end-use specialization dictate bonder selection across semiconductor packaging workflows. Segment boundaries reflect divergent accuracy requirements, throughput demands, and regulatory compliance burdens that reshape supplier competitive positioning.
Product Type:
Cost tier determines accessibility for fabs at varying scale and technology nodes.
- Multi-Array:Parallel die handling architectures process multiple chiplets simultaneously with sub-3-micron placement accuracy. AI accelerator and 5G baseband module production at Samsung Foundry Pyeongtaek and TSMC Hsinchu drives concentrated demand for these premium systems.
- Single Array:Sequential placement systems serve mid-volume consumer electronics and legacy automotive module assembly. Domestic Chinese contract manufacturers under MIIT dual carbon mandates are retiring older units for energy-efficient replacements, sustaining replacement demand despite single-die throughput limitations.
- Dual Array:Balanced throughput-accuracy platforms target heterogeneous integration workflows requiring moderate parallelism.
- Custom Design:Application-specific configurations address silicon photonics and MEMS packaging with non-standard die geometries.
Multi-Array holds installed capacity. Custom Design is rotating up the share rankings.
Application:
End-use specifications create divergent qualification barriers and margin structures.
- Automotive Electronics:ADAS modules and EV powertrain controllers require AEC-Q100 qualified bonders with traceable calibration protocols. South Korea's K-Battery regulations and MFDS cleanroom specifications constrain equipment selection for domestic IDM procurement teams at Hyundai Mobis and LG Innotek.
- Consumer Electronics:High-volume smartphone and wearable assembly prioritizes cost-adjusted throughput over extreme accuracy. China's contract manufacturers dominate equipment absorption for this segment, though margin compression limits supplier pricing power.
- Telecommunications:5G infrastructure and optical transceiver modules demand precision placement for RF and photonic die integration.
- Industrial Automation:Ruggedized control systems and sensor modules require extended temperature range specifications.
Consumer Electronics holds installed capacity. Automotive Electronics is climbing the fastest.
End User:
Customer type shapes procurement patterns and service relationship intensity.
- Contract Manufacturers:OSATs and pure-play packaging houses purchase equipment in volume with platform-level vendor consolidation. Taiwan's ASE Group and Amkor Technology have shifted from equipment-specific to integrated solution agreements covering bonders, inspection, and process software.
- OEMs:Captive packaging operations at IDMs like Intel and Samsung maintain direct supplier relationships with dedicated field engineering support. These accounts demand co-development partnerships for next-node packaging roadmaps.
- Research Organizations:IMEC, CEA-Leti, and university consortia pilot emerging hybrid bonding and wafer-level fan-out workflows.
- Electronic Component Suppliers:Passive and interconnect manufacturers deploy bonders for module-level subsystem assembly.
Contract Manufacturers holds installed capacity. OEMs is gaining share fastest.
Technology:
Process maturity and integration depth segment equipment architectures.
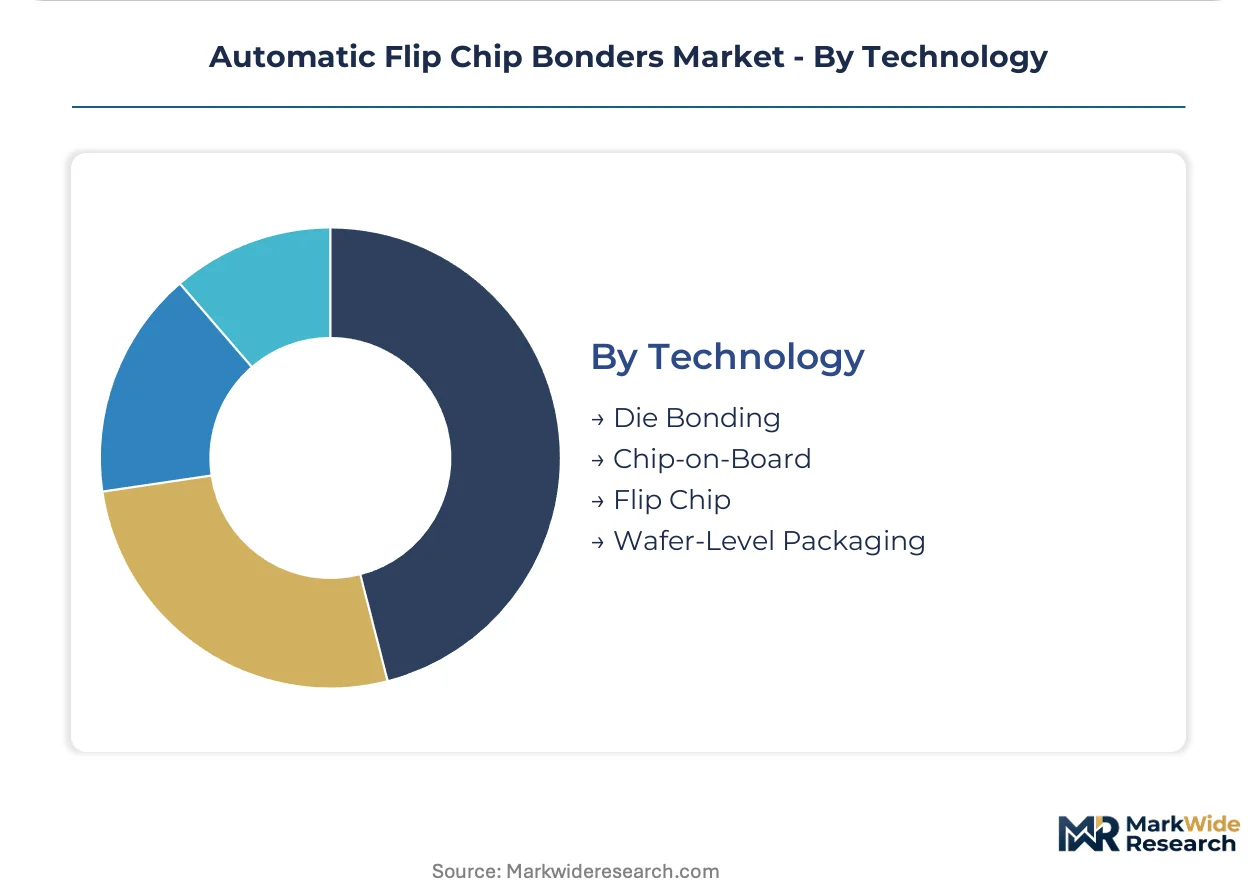
- Wafer-Level Packaging:Fan-out and 3D stacking workflows on reconstituted wafers command premium positioning as IDMs migrate from research to high-volume production. Japan's METI JIS certification requirements and NEDO consortium funding favor domestic suppliers for these advanced platforms.
- Die Bonding:Conventional face-down assembly with solder bumps or copper pillars remains the volume leader across consumer and telecommunications applications. Equipment suppliers compete on throughput optimization and flux chemistry compatibility under EU F-Gas and REACH constraints.
- Flip Chip:Thermocompression and mass reflow hybrid systems serve mixed interconnect requirements.
- Chip-on-Board:Direct die attach to PCB substrates targets cost-sensitive module applications.
Die Bonding holds installed capacity. Wafer-Level Packaging is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment suppliers concentrate advanced packaging system deployment around East Asian semiconductor manufacturing clusters, with foundry capacity expansion in Taiwan, South Korea, and China absorbing the majority of new bonder installations.
China
Domestic contract manufacturers under MIIT dual carbon mandates are retiring legacy bonders for energy-efficient replacements. SAMR GB standards for equipment efficiency metrics constrain foreign supplier market access. Yangtze River Delta packaging houses in Suzhou and Wuxi drive concentrated demand for mid-range single-array systems.
South Korea
Samsung Foundry and SK Hynix are expanding flip chip capacity at Pyeongtaek for AI accelerator and HBM production. MFDS cleanroom specifications and K-Battery regulations shape equipment selection for automotive electronics bonders. Seoul Capital Area fabs anchor premium multi-array system procurement.
Taiwan
TSMC Hsinchu operations and ASE Group facilities sustain the highest density of advanced packaging equipment globally. Procurement teams have shifted from equipment-specific to platform-level vendor agreements covering bonders, inspection, and process software. Taichung and Tainan packaging subsidiaries extend capacity for fan-out and 3D stacking workflows.
Japan
METI coordinates domestic equipment standards through JIS certification requirements that constrain non-compliant imports. NEDO-funded advanced packaging consortia favor domestic suppliers for wafer-level platforms. Nagoya and Osaka industrial corridors maintain precision motion component supply chains for linear motors and air-bearing stages.
United States
Intel captive packaging operations and emerging domestic foundry capacity under CHIPS Act incentives drive selective bonder procurement. EPA and OSHA regulations shape cleanroom and materials-handling specifications. Arizona and New Mexico fab sites concentrate new equipment installations for advanced node packaging.
Automatic Flip Chip Bonders Market Competitive Landscape
Precision-platform specialists and throughput-optimized suppliers split the market between premium accuracy tiers and cost-adjusted volume segments. The vendor base clusters around three strategic archetypes: integrated solution providers with captive process development, precision-motion equipment specialists leveraging Japanese and German component supply chains, and regional cost-optimized fabricators serving mid-range consumer electronics. Dominant competitive moves include platform-level vendor consolidation by contract manufacturers and co-development partnerships between IDMs and equipment suppliers for next-node roadmaps.
Within the integrated solution tier, ASMPT and BESI occupy positions exemplifying technology leadership in high-accuracy placement systems and precision thermocompression platforms respectively. Kulicke & Soffa sits within the throughput-optimized archetype, representing competitive positioning on cost-adjusted throughput metrics for mid-range applications. These three companies anchor the competitive structure through their respective specialization vectors.
| Leading Market Players |
|---|
| ASMPT |
| BESI |
| Kulicke & Soffa |
| SHIBUYA CORPORATION |
| Hamni |
| Muehlbauer |
| AMICRA Microtechnologies |
| Shibaura |
| SET |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japanese linear motor suppliers and German air-bearing stage manufacturers compresses pricing tier spreads while forcing equipment vendors toward regional qualification investments. This input bottleneck simultaneously elevates premium system costs and constrains mid-range pricing flexibility as buyers absorb compliance premiums for MIIT dual carbon alignment and METI JIS certification.
Pricing Analysis
EU F-Gas and REACH regulations dictate the pricing tier structure across the European equipment segment, forcing redesign costs into premium configurations. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified multi-array systems from single-array units and custom photonics platforms. Cost compression in the standard tier intensifies because Chinese contract manufacturers prioritize energy efficiency replacements over accuracy upgrades. Consumer electronics buyers exhibit highest price sensitivity, while automotive OEMs accept premium positioning for AEC-Q100 qualified systems with traceable calibration protocols.
Supply Chain Analysis
Linear motors from Japan, air-bearing stages from Germany, and precision granite structures from Switzerland anchor upstream feedstock concentration for high-accuracy bonders. Equipment architectures rest on ceramic ball screws, piezoelectric actuators, and thermocompression bonding heads sourced from specialized component houses. Single-source vulnerability concentrates around Japanese motion control suppliers, creating input bottlenecks during Pyeongtaek and Hsinchu capacity expansions. Distribution runs through direct OEM procurement for IDM captive operations and platform-level agreements with OSAT consolidation at ASE Group and Amkor Technology.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic flip chip bonders market operates as a defensive-moat arena where METI JIS certification requirements and MIIT GB standards create regulatory entrenchment that protects incumbents through multi-year qualification timelines and switching costs that lock IDM procurement teams into validated supplier relationships.
For Market Incumbents: Entrench technology leadership through captive process development partnerships with Samsung Foundry and TSMC for next-node hybrid bonding roadmaps. Deepen upstream control over precision motion component supply by qualifying secondary Japanese and German suppliers to mitigate single-source vulnerability during demand surges. Lock in platform-level agreements with Taiwan OSATs before competitor integrated solutions displace standalone equipment vendors. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized semiconductor ecosystem by building local service infrastructure ahead of display and packaging fab ramps. Target silicon photonics packaging as the most penetrable application, where non-standard die geometries and multi-process configurations favor specialized equipment over incumbent mass-market platforms. Lead with co-development partnerships for AI cluster transceiver modules rather than competing on throughput metrics. For Investors and Strategic Acquirers: China's evolving SAMR GB standards for dual carbon-aligned equipment efficiency metrics reshape the acquisition landscape by determining foreign supplier market access trajectories. Long-term viability centers on platform-level integrated solution providers with captive software and inspection capabilities, displacing standalone equipment vendors. Monitor IDM procurement consolidation from equipment-specific to vendor-platform agreements as the primary inflection signal for valuation compression among pure-play bonder manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Platform Development | SK Hynix and Samsung memory pilots for HBM4 production compress supplier R&D cycles. |
| JIS Certification Validation Centers | Foreign manufacturers secure METI qualification status for Japanese IDM procurement lists. |
| India Local Service Infrastructure | PLI scheme incentives create first-mover positioning for packaging equipment vendors. |
| Platform-Level Vendor Consolidation | Taiwan OSATs shift from equipment-specific to integrated solution agreements covering bonders and inspection. |
| Copper Pillar Thermocompression Systems | Sub-3-micron accuracy bonders capture margin pools as foundries migrate from solder bump interconnects. |
Research Methodology
Desk research of semiconductor equipment trade databases, METI JIS certification registries, and MIIT policy filings preceded structured interviews with packaging equipment procurement managers at Taiwan OSATs, process engineering directors at South Korean memory houses, and calibration protocol specialists at Japanese IDMs. Secondary validation drew from customs import records for precision motion components, SEC filings of listed equipment vendors, and NEDO consortium funding disclosures. Bottom-up equipment shipment estimates triangulated against top-down fab capacity expansion announcements across Pyeongtaek, Hsinchu, and Yangtze River Delta clusters.
Forecast assumptions held fixed the current regulatory compliance burden trajectory for EU F-Gas, REACH, and China's dual carbon mandates while varying semiconductor capital expenditure cycles and chiplet architecture adoption rates across the analysis window. Segmentation dimensions modeled include equipment configuration tier, end-use application qualification requirements, and customer procurement pattern archetype. CAGRs were derived from installed base replacement dynamics and greenfield capacity absorption rates, with specific inputs for copper pillar migration timelines and wafer-level fan-out production ramps.
Stress conditions across precision component supply availability, MIIT equipment efficiency standard enforcement intensity, and plasma dicing substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding heterogeneous integration adoption and automotive electronics qualification expansion. Cross-checking against SEMI equipment spending surveys and foundry capex guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Chip Conveyors Market