
 Solder Ball Mounter Market | 2026-2036
Solder Ball Mounter Market Size, Share, and Industry Trends Forecast 2026-2036
Solder Ball Mounter Market Insights
East Asian capital equipment supply is consolidating around precision motion control and thermal management capabilities. Kulicke and Soffa Industries leverages its wire bonding heritage to extend into advanced packaging ball placement systems. ASM Pacific Technology anchors its position through integrated solutions spanning die attach through final test. Panasonic Corporation competes with proprietary linear motor stages that sustain sub-micron placement repeatability across high-volume memory packaging lines.
A solder ball mounter precisely positions solder spheres onto substrate pads using flux-assisted or laser-assisted bonding, achieving placement accuracies of ±15 micrometers at throughputs exceeding 30,000 units per hour for flip-chip and wafer-level package assembly. The automatic product category dominates capital procurement as electronics manufacturers pursue line integration with AOI and reflow systems. Rotary technology leads throughput metrics for standard ball grid arrays while laser technology captures premium positioning in fine-pitch copper pillar and micro-bump applications where thermal budget constraints prohibit conventional reflow profiles.
Japan's METI coordinates domestic equipment maker certification through JIS standards for semiconductor manufacturing apparatus, while China's MIIT enforces GB standards and local content requirements for imported mounter qualification. The US Commerce Department export controls on advanced packaging equipment to designated entities reshape supplier qualification pathways for multinational OEMs. Stakeholders must monitor evolving dual-use technology classifications and regional subsidy qualification criteria when configuring geographic manufacturing footprints and service network deployments.
Market Dynamics
Ball grid array packaging for high-performance computing is concentrating procurement power among semiconductor foundries and OSATs, forcing equipment makers to align roadmaps with advanced packaging node transitions rather than discrete component assembly cycles.
Growth Catalysts
- High-performance computing demand:AI accelerator chips and data center processors require dense interconnects that only flip-chip and wafer-level packages can deliver, sustaining capital equipment orders from TSMC, Samsung Foundry, and Intel.
- MIIT semiconductor directives:China's push for domestic packaging capability triggers localized mounter procurement with GB standards compliance as a qualification gate for imported equipment.
- Laser-assisted bonding adoption:Fine-pitch copper pillar applications in mobile processors and networking ASICs displace conventional reflow methods where thermal budgets constrain process windows.
Market Restraints
- Precision motion control supply concentration:Linear motor stages and granite base frames source predominantly from German and Japanese specialists, creating single-source vulnerability for sub-micron repeatability specifications.
- Technical limitation at extreme pitch:Below 40-micrometer bump pitch, solder ball mounters face fundamental physics constraints from sphere diameter minima and flux patterning resolution that laser direct bonding must address.
- Export control friction:US Commerce Department dual-use technology classifications restrict advanced packaging equipment shipments to designated Chinese entities, fragmenting supplier qualification pathways for multinational OEMs.
Strategic Opportunities
- India OSAT greenfield expansion:Micron Technology's Gujarat assembly and test facility and Tata Electronics' Karnataka packaging campus create first-mover positioning for mounter vendors ahead of PLI scheme maturation.
- Automotive power module packaging:Silicon carbide inverter substrates for electric vehicles require soldered die-attach processes that rotary ball placement systems can adapt with thermal profile modifications.
- Photonics packaging convergence:Co-packaged optics for AI clusters merges semiconductor ball placement with optical fiber alignment, opening equipment cross-selling to datacom transceiver manufacturers.
Industry Challenges
- Mechatronics skill scarcity:Integration of vision systems, motion stages, and thermal subsystems demands cross-functional engineers rare in both equipment makers and customer fabs.
- Qualification timeline compression:JIS and GB certification cycles for semiconductor manufacturing apparatus now overlap with customer tape-out schedules, squeezing field validation windows.
- Legacy wire bonding line retrofit:OSATs with installed Kulicke and Soffa or ASM Pacific wire bonders face capital allocation conflicts between upgrading existing platforms and greenfield advanced packaging investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solder Ball Mounter Market |
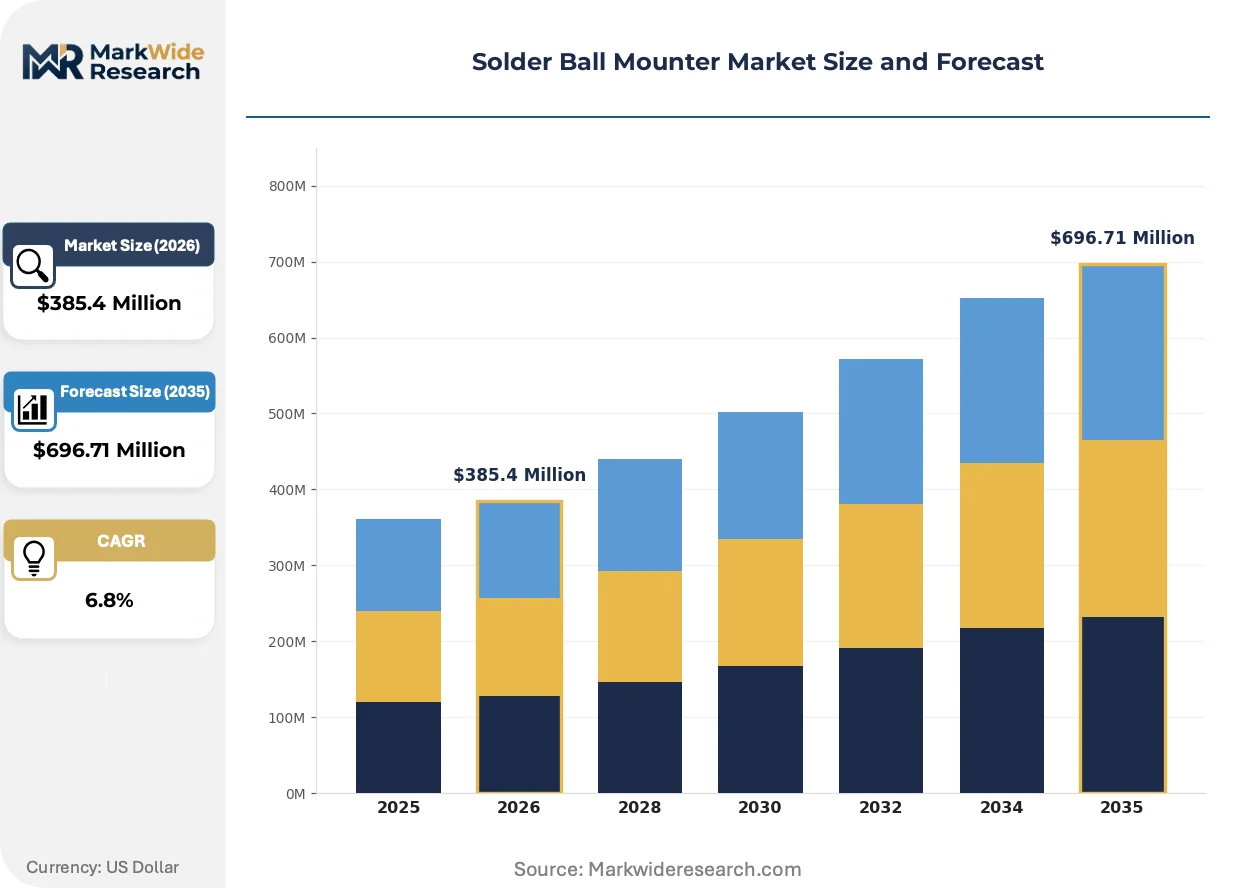
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Hybrid Technology: Orbital, Rotary, Laser, Heat Transfer End User: Electronics Manufacturers, Contract Manufacturers, SMAs, Research Institutions Application: PCB Assembly, Semiconductor Packaging, Optical Devices, IoT Devices |
| Companies Covered | Kulicke and Soffa Industries, ASM Pacific Technology, Seiko Epson Corporation, Panasonic Corporation, Tokyo Electron Limited, Hitachi, SHIBUYA, ASM Assembly Systems GmbH, Yamaha Robotics Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solder Ball Mounter Market Trends and Innovations
Equipment architecture is fragmenting between high-throughput rotary systems for commodity memory and precision laser platforms for heterogeneous integration, with software-defined process control emerging as the common layer.
Fluxless laser bonding is decentralizing thermal management responsibility from the reflow oven to the placement head itself. Memory packaging lines at Samsung and SK Hynix are piloting this approach for DDR5 module assembly. The technology is compressing factory floor footprints by eliminating separate flux deposition and cleaning stations while raising throughput ceilings for standard ball grid arrays.
METI's JIS B 9920 semiconductor manufacturing apparatus standards are tightening particulate and vibration specifications for equipment sold into Japanese fabs. Domestic makers like Panasonic must recertify existing platforms while foreign vendors face extended qualification timelines. The regulation most impacts laser-based systems where optical path stability determines placement yield, pushing suppliers toward active isolation stages.
Capital equipment purchasing is consolidating through foundry-direct contracts rather than OSAT distributor channels. TSMC and Intel now specify mounter performance metrics in their equipment purchase agreements, bypassing traditional packaging house procurement autonomy. Taiwan and South Korea exhibit this pattern most acutely, where advanced packaging capacity concentrates among vertically integrated IDMs and captive foundry operations.
Solder Ball Mounter Market Segmentation
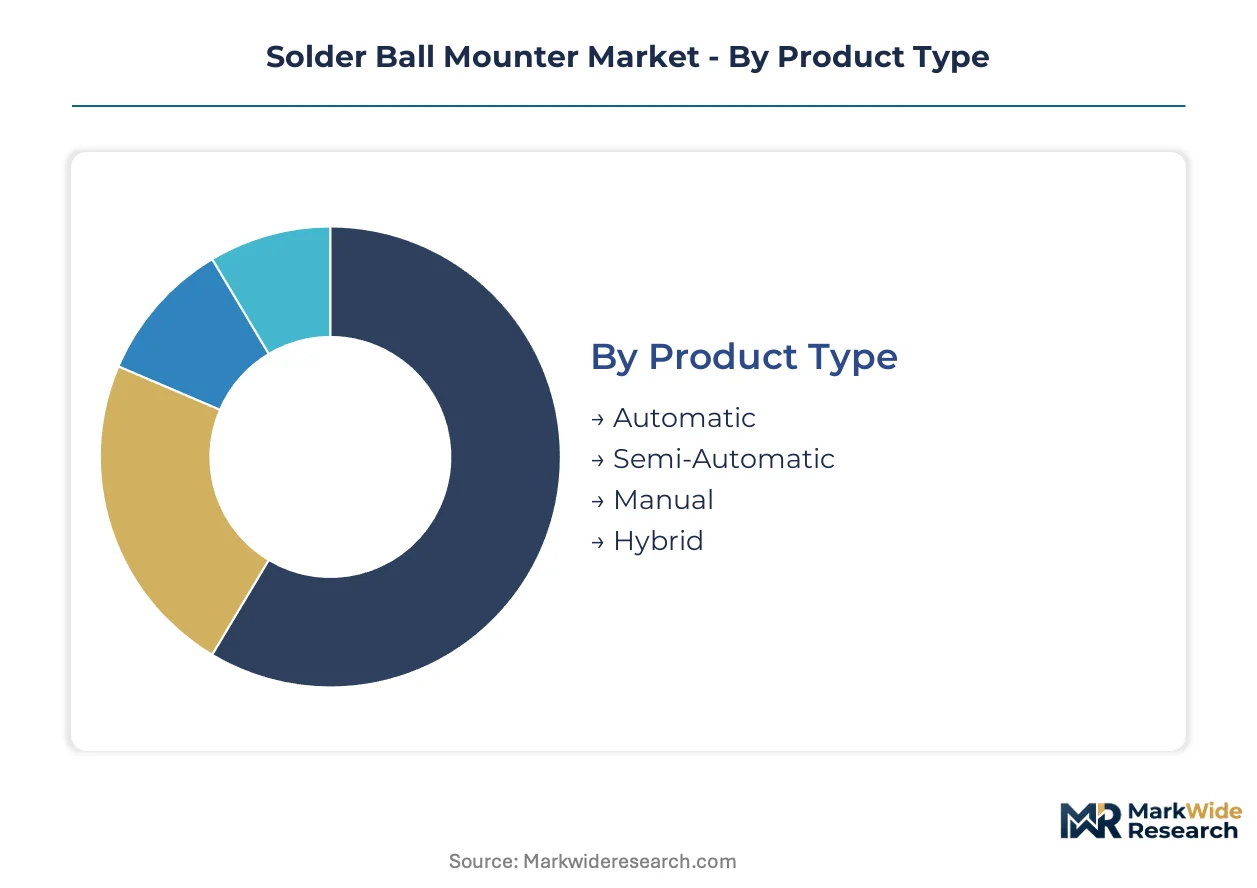
Segmentation in solder ball mounters reflects the tension between throughput maximization for commodity memory and precision positioning for heterogeneous integration. Equipment architecture diverges sharply across product categories, with automation levels and bonding technologies determining addressable process windows.
Product Type:
The customization-standardization spectrum runs from fully programmable automatic systems to operator-dependent manual stations, with procurement patterns splitting between line integration mandates and low-volume prototyping needs.
- Automatic:Programmable multi-axis platforms achieve ±15 micrometer placement accuracy at throughputs exceeding 30,000 units per hour. TSMC and Samsung Foundry specify automatic systems for flip-chip and wafer-level package assembly, with AOI and reflow integration now mandatory in purchase agreements.
- Semi-Automatic:Operator-assisted loading with automated placement cycles bridges qualification volumes and production ramp. OSATs in Taiwan deploy semi-automatic systems for customer tape-out validation before committing to full automatic line purchases.
- Manual:Benchtop units with micrometer stages serve research prototyping and legacy component repair. University cleanrooms and failure analysis labs in Japan maintain manual systems for process development without capital-intensive automation.
- Hybrid:Configurable architectures allow automatic mode for standard ball grid arrays and semi-automatic override for experimental substrates. Equipment makers in South Korea promote hybrid platforms to capture both production and R&D budgets within single capital allocations.
Most installed capacity flows through Automatic systems. Expansion is steepest in Hybrid configurations.
Technology:
Cost tier separation distinguishes high-throughput mechanical platforms from premium thermal-direct bonding, with price multiples exceeding threefold between commodity rotary and precision laser systems.
- Rotary:Turret-based indexing delivers highest throughput for standard pitch ball grid arrays in memory packaging. SK Hynix and Micron Technology deploy rotary systems for DDR5 module assembly where thermal budgets accommodate conventional reflow profiles.
- Laser:Direct bonding eliminates flux deposition and cleaning stations, compressing factory footprints. Fine-pitch copper pillar applications in mobile processors at Apple and Qualcomm suppliers drive laser adoption where sphere diameter minima constrain mechanical placement.
- Orbital:Planar motion stages with vision feedback serve mid-range accuracy requirements in automotive power modules. German automotive tier-1 suppliers specify orbital technology for silicon carbide inverter substrates requiring thermal profile modifications.
- Heat Transfer:Thermode bonding for localized reflow in thermally sensitive substrates. Medical device manufacturers in Switzerland utilize heat transfer systems for implantable electronics where adjacent component temperature limits prohibit bulk oven exposure.
Rotary technology holds the largest installed base. Laser platforms are climbing the fastest as heterogeneous integration pitch requirements tighten.
End User:
Customer type determines specification authority, with foundry-direct contracts bypassing traditional OSAT procurement autonomy and consolidating vendor selection power.
- Electronics Manufacturers:IDMs and captive packaging operations specify mounter roadmaps aligned with advanced packaging node transitions. Intel and Texas Instruments maintain direct equipment development partnerships with placement system vendors.
- Contract Manufacturers:Flex and Jabil negotiate fleet pricing across multiple customer programs, prioritizing platform commonality over process optimization for individual products. Their procurement emphasizes service network density and spare parts availability.
- SMAs (Surface Mount Assembly houses):Regional subcontractors in Southeast Asia purchase refurbished or entry-level automatic systems for commodity PCB assembly. Price sensitivity drives 5-7 year equipment lifecycles versus 3-year replacement at leading-edge facilities.
- Research Institutions:University labs and national research centers acquire manual and semi-automatic systems through grant funding with extended procurement timelines. METI and MIIT research programs in Japan and China specify domestic equipment preferences in funding awards.
Electronics Manufacturers control the dominant share of new equipment orders. SMAs represent the most price-elastic demand segment.
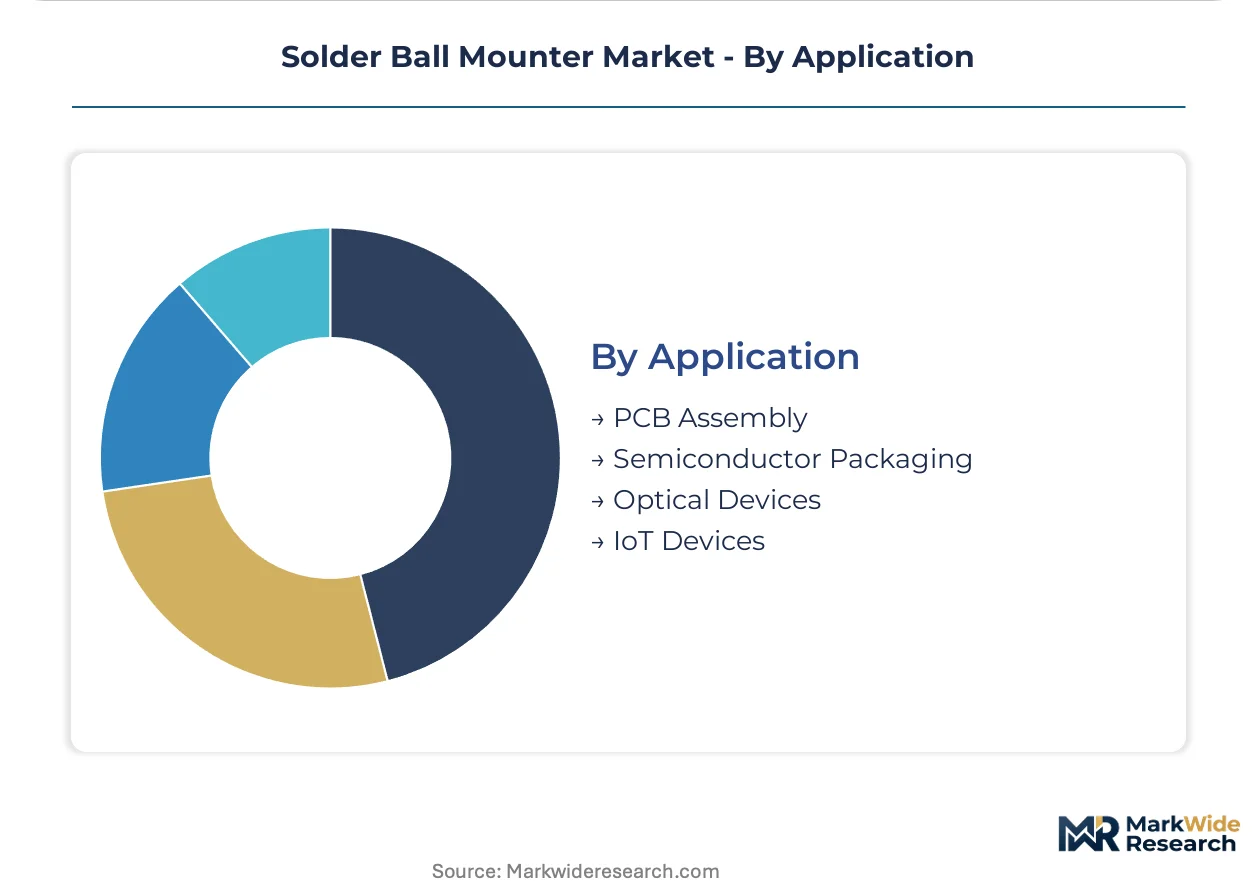
Application:
Maturity gradients separate established PCB assembly from emerging photonics packaging, with equipment makers adapting motion control architectures to address optical fiber alignment requirements.
- Semiconductor Packaging:Flip-chip, wafer-level, and 2.5D/3D integration drive sub-micron repeatability specifications. Co-packaged optics for AI clusters merges ball placement with photonics alignment, opening cross-selling to datacom transceiver manufacturers.
- PCB Assembly:Standard ball grid array mounting for motherboards and networking equipment represents the volume base. Chinese EMS providers in Shenzhen and Dongguan concentrate procurement for consumer electronics and telecommunications infrastructure.
- Optical Devices:Silicon photonics and LiDAR module assembly require placement accuracy beyond conventional solder sphere limits. Ansys and Lumentum suppliers specify hybrid mechanical-optical alignment stages for transceiver packaging.
- IoT Devices:Miniaturized sensors and wearable electronics drive demand for compact footprint equipment with quick changeover capabilities. Nordic Semiconductor module subcontractors prioritize small-batch flexibility over peak throughput.
Semiconductor Packaging absorbs the majority of capital expenditure. Optical Devices are gaining share fastest as co-packaged optics penetrate AI infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing solder ball mounter procurement as cost-of-compliance gaps widen between jurisdictions with divergent semiconductor equipment standards and subsidy qualification rules.
China
MIIT semiconductor self-sufficiency directives are accelerating localized packaging capacity buildout in Jiangsu and Guangdong provinces. GB standards compliance now gates imported mounter qualification, extending field validation timelines for foreign vendors. Shanghai's Zhangjiang Hi-Tech Park concentrates domestic equipment trials as Yangtze Memory Technologies and Hua Hong Semiconductor expand captive advanced packaging lines.
Japan
METI chip supply chain resilience programs are reinforcing domestic equipment maker preference through JIS B 9920 certification requirements. Sub-micron vibration and particulate specifications for semiconductor manufacturing apparatus favor established domestic suppliers. Kyushu's Kumamoto Prefecture hosts TSMC's JASM fab complex, driving localized mounter procurement with Japanese content thresholds.
Taiwan
Foundry-direct equipment specification authority is consolidating vendor selection power at TSMC and ASE Technology. The Hsinchu Science Park anchors the densest advanced packaging equipment cluster globally, with mounter roadmaps synchronized to 2.5D/3D integration node transitions. Taichung's Central Taiwan Science Park is absorbing secondary packaging capacity expansion as land constraints tighten in Hsinchu.
South Korea
Samsung Foundry and SK Hynix are specifying automatic mounter performance metrics directly in equipment purchase agreements, bypassing traditional OSAT procurement channels. The Yongin semiconductor cluster in Gyeonggi Province is concentrating laser-assisted bonding pilot lines for DDR5 and HBM3 module assembly. Busan's packaging equipment supply base is pivoting from wire bonding heritage toward flip-chip and wafer-level package assembly systems.
United States
Commerce Department export controls on advanced packaging equipment to designated Chinese entities are fragmenting supplier qualification pathways for multinational OEMs. Intel's Arizona and Oregon fabs are driving domestic mounter procurement for heterogeneous integration roadmaps. Texas Instruments' Richardson campus maintains direct equipment development partnerships with placement system vendors for automotive and industrial packaging applications.
Solder Ball Mounter Market Competitive Landscape
Japanese producers anchor the precision-tier equipment segment; German motion control specialists hold critical subcomponent supply positions that determine placement repeatability specifications. The vendor base splits between consolidated capital equipment conglomerates with wire bonding heritage and focused advanced packaging specialists. Three archetypes dominate: integrated semiconductor equipment conglomerates, precision motion control specialists, and packaging-line integration providers. Competitive positioning hinges on M&A-driven portfolio expansion and foundry-direct partnership structures that bypass traditional OSAT channels.
Within the integrated equipment tier, Kulicke and Soffa Industries and ASM Pacific Technology exemplify archetypes leveraging legacy wire bonding platforms to extend into ball placement systems. Panasonic Corporation occupies a position representing Japanese precision manufacturing heritage through proprietary linear motor stage capabilities. These three companies collectively illustrate how equipment makers are repositioning around advanced packaging node transitions rather than discrete component assembly cycles.
| Leading Market Players |
|---|
| Kulicke and Soffa Industries |
| ASM Pacific Technology |
| Seiko Epson Corporation |
| Panasonic Corporation |
| Tokyo Electron Limited |
| Hitachi |
| SHIBUYA |
| ASM Assembly Systems GmbH |
| Yamaha Robotics Holdings |
| Others |
Pricing and Supply Chain Analysis
Rotary-to-laser technology bifurcation creates distinct pricing echelons that map directly onto supply chain configurations, with premium laser platforms commanding threefold multiples over commodity rotary systems while sourcing precision motion stages exclusively from German and Japanese specialists. Foundry-direct procurement at TSMC and Samsung Foundry compresses channel margins for equipment vendors, whereas OSAT distributor channels retain markup layers for refurbished rotary systems serving Southeast Asian SMAs.
Pricing Analysis
Distributor margin compression distinguishes foundry-direct contracts from OSAT channel sales, with automatic mounter procurement bypassing traditional equipment distributors entirely at leading-edge facilities. Three-tier pricing structure across premium laser, standard rotary, and economy refurbished levels differentiates by placement accuracy certification and GB/JIS compliance tier. Cost compression in rotary memory packaging lines intensifies as Chinese EMS providers extend equipment lifecycles to 5-7 years. SMAs in Vietnam and Indonesia exhibit highest price sensitivity, while captive foundry operations at Intel and Texas Instruments prioritize specification authority over unit cost.
Supply Chain Analysis
Refurbishment flows for legacy wire bonding platforms extend equipment economic life, with Kulicke and Soffa and ASM Pacific aftermarket services capturing recurring revenue from installed base upgrades. Precision motion control supply concentrates in Germany, Japan, and Switzerland, with linear motor stages and granite base frames drawing from Schneeberger, THK, and Aerotech specialists. Single-source vulnerability for sub-micron repeatability specifications creates qualification bottlenecks when JIS B 9920 recertification cycles overlap customer tape-out schedules. Distribution runs through foundry-direct contracts for advanced packaging and regional equipment distributors for commodity PCB assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in laser-assisted bonding platforms where fluxless process elimination reduces customer factory footprint costs, justifying premium pricing against conventional rotary systems. Equipment vendors capturing foundry-direct specification authority at TSMC and Samsung Foundry secure multi-year procurement visibility unavailable through OSAT channels.
For Market Incumbents: To counter precision motion control supply concentration risks, deepen backward integration into linear motor stage production or secure dual-source qualification with Swiss and German motion specialists ahead of JIS B 9920 recertification waves. Foundry-direct partnership structures with Intel and Texas Instruments provide defensive moats against emerging Asian equipment challengers. For New Entrants and Emerging Players: Launch via hybrid platform configurations targeting South Korean R&D budgets, where automatic-to-semi-automatic mode switching captures both production and qualification equipment allocations within single capital purchases. White-space opportunity sits with photonics packaging convergence, where co-packaged optics for AI clusters merges semiconductor ball placement with optical fiber alignment capabilities underserved by incumbent wire bonding heritage vendors. For Investors and Strategic Acquirers: Asymmetric upside sits with precision motion control specialists possessing JIS-certified vibration isolation stages, as METI particulate specifications tighten and foreign vendor qualification timelines extend. Long-term viability favors acquisition targets with software-defined process control layers enabling retrofit upgrades to installed automatic bases. Monitor MIIT domestic content threshold adjustments for early signals of Chinese equipment vendor preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Fluxless Laser Bonding Platform Launch | Eliminates flux deposition stations, compressing Samsung and SK Hynix factory footprints. |
| JIS B 9920 Recertification Investment | Secures Panasonic access to TSMC's Kumamoto JASM fab procurement specifications. |
| Foundry-Direct Partnership Structure | Bypasses ASE Technology procurement autonomy with TSMC equipment purchase agreement terms. |
| Photonics Packaging Capability Acquisition | Captures Ansys and Lumentum datacom transceiver alignment requirements. |
| India OSAT Greenfield Service Network | Positions ahead of Micron Gujarat and Tata Electronics Karnataka facility ramp schedules. |
Research Methodology
Bottom-up semiconductor packaging equipment modeling reconciled against top-down capital expenditure tracking forms the analytical core, combining primary interviews with OSAT procurement directors, foundry equipment engineers, and precision motion control specialists alongside secondary validation through SEMI equipment market data, SEC 10-K filings of listed vendors, and MIIT/METI subsidy disclosure records. Triangulation across end-user specification authority patterns and supplier qualification pathway documentation grounds volume and value estimates.
Historical trendline analysis of wire bonding-to-ball placement technology transitions informs projection frameworks across the modeling period, with segmentation dimensions covering automation level, bonding technology, end-user type, and application maturity. CAGRs derive from equipment procurement cycle analysis and advanced packaging node transition roadmaps, incorporating foundry capex disclosure patterns and OSAT capacity expansion announcements as forward indicators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control expansion scenarios or abrupt JIS/GB standard harmonization shifts. Practitioners should monitor Commerce Department entity list updates and MIIT domestic content threshold adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Global Wafer Cleaning Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Slide Processing System Market