
 Sample Preparation Equipment Market | 2026-2036
Sample Preparation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sample Preparation Equipment Market Analytics
ISO 17025 accreditation is unwinding competitive access for uncertified vendors across clinical and environmental testing verticals. Thermo Fisher Scientific leverages its captive chromatography consumables portfolio to lock in recurring revenue on installed prep systems. Danaher Corporation anchors its position through Beckman Coulter centrifuge platforms that dominate pharmaceutical quality control workflows. Agilent Technologies specializes in mass spectrometry-compatible sample prep automation, competing directly with Merck KGaA's Milli-Q water purification-integrated workflows.
Sample preparation equipment encompasses instruments that reduce heterogeneous specimens to analytically uniform states through mechanical disruption, thermal digestion, chemical extraction, or biological enzymatic treatment, typically operating at throughputs from single-tube to 384-well microplate formats for downstream spectroscopic or chromatographic analysis. Centrifuge systems retain the largest installed base but face margin compression from commoditized rotor designs, while homogenizer demand accelerates in food safety laboratories confronting mycotoxin and allergen testing backlogs. Mechanical technology still occupies the majority of unit shipments, though biological preparation protocols—cell lysis, nucleic acid extraction—command premium pricing in research laboratories sequencing SARS-CoV-2 variants and emerging pathogens.
FDA 21 CFR Part 11 electronic records requirements and EPA Method 1664 oil and grease protocols shape equipment specifications for US laboratories, while EU REACH chemical restriction lists and the MDR's analytical performance requirements filter which vendors access European clinical diagnostics procurement. China's NMPA revised in vitro diagnostic regulations now mandate traceable sample handling documentation, forcing domestic labs toward automated prep platforms with audit trails. Stakeholders must weigh captive consumables economics against open-system flexibility as laboratories renegotiate total cost of ownership frameworks.
Market Dynamics
Automation protocols are compressing replacement cycles as pharmaceutical manufacturers retool for FDA 21 CFR Part 11 electronic records compliance, forcing synchronous upgrades of consumables and software across installed bases.
Growth Catalysts
- GLP-certified facility expansion:Contract research organizations in Germany and the United States are commissioning automated prep lines to handle biologics stability testing volumes.
- EPA Method 1664 oil and grease protocols:Environmental laboratories face mandatory equipment recertification, triggering rotor and vial replacement demand in wastewater analysis segments.
- Microfluidic integration:Single-cell genomics workflows are pulling 384-well format homogenizers into academic sequencing centers processing SARS-CoV-2 variant surveillance.
Market Restraints
- Stainless steel and rare-earth magnet input costs:Centrifuge rotor manufacturing faces margin compression from commodity price volatility in precision metal supply chains.
- Consumables lock-in economics:Captive vial and filter cartridge ecosystems from dominant vendors create switching friction for mid-sized clinical laboratories.
- Biological protocol complexity:Cell lysis method standardization gaps across tissue types slow nucleic acid extraction platform adoption in hospital pathology departments.
Strategic Opportunities
- China NMPA traceability mandates:Domestic IVD laboratories require audit-trail-capable automation, opening replacement windows for compliant foreign equipment vendors.
- Food safety mycotoxin testing backlogs:European reference laboratories are unbundling homogenizer service contracts to accelerate allergen analysis throughput.
- Mass spectrometry-LC/MS convergence:Automated solid-phase extraction systems are penetrating environmental PFAS monitoring workflows previously served by manual protocols.
Industry Challenges
- ISO 17025 assessor scarcity:Accreditation body capacity constraints are extending certification timelines for equipment vendors seeking clinical laboratory access.
- Legacy LIMS integration:Robotic sample prep platforms require custom middleware development to synchronize with decade-old laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sample Preparation Equipment Market |
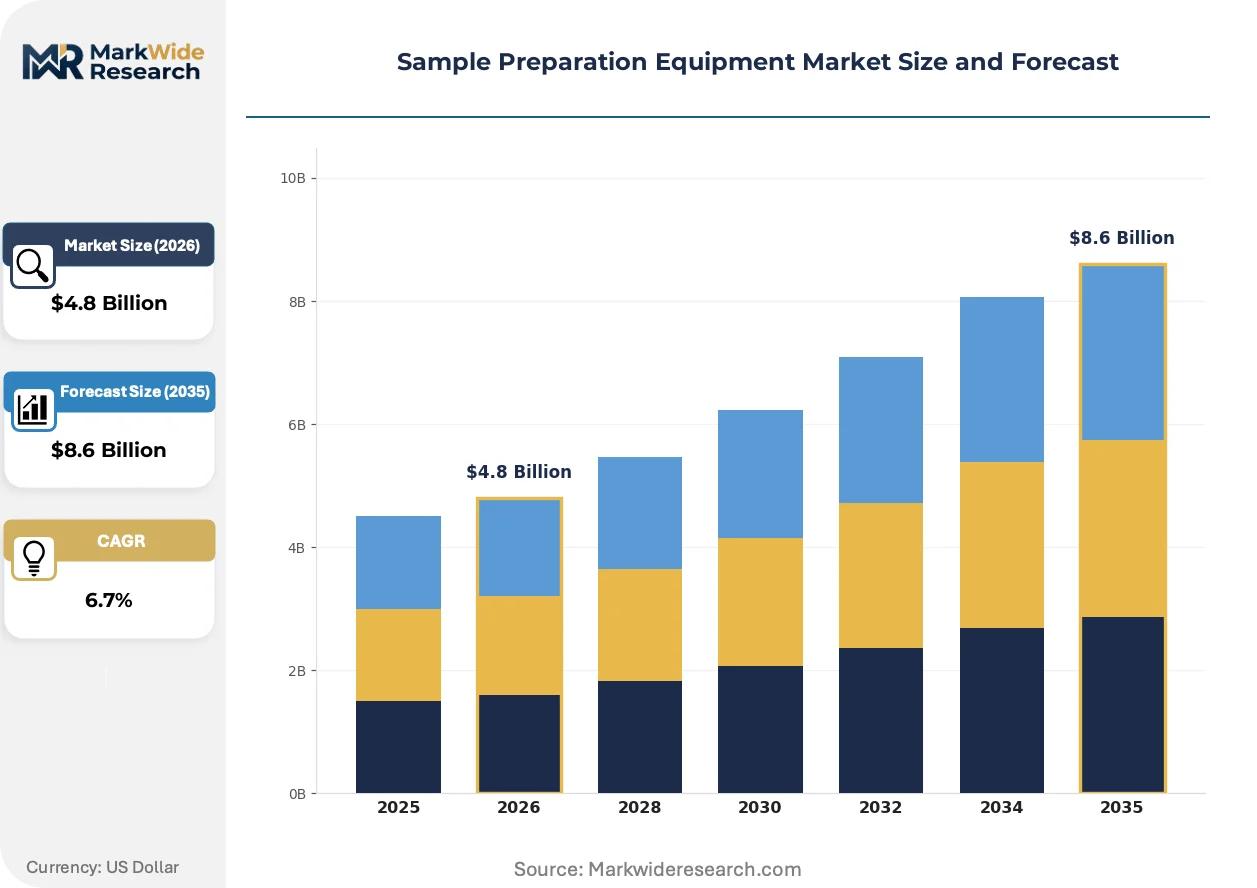
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homogenizers, Centrifuges, Dispensers, Mixers Application: Pharmaceuticals, Food Testing, Environmental Analysis, Material Science End User: Research Laboratories, Quality Control Labs, Clinical Labs, Academic Institutions Technology: Mechanical, Thermal, Chemical, Biological |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Merck KGaA, Danaher Corporation, QIAGEN, PerkinElmer, Bio-Rad Laboratories, Tecan Group, Hamilton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sample Preparation Equipment Market Evolving Landscape
Workflow digitization is fragmenting equipment purchasing decisions, separating hardware procurement from software and consumables contracting across pharmaceutical quality control departments.
Acoustic liquid handling is fragmenting traditional pipetting automation in high-throughput screening facilities. Biopharma discovery groups at Merck KGaA and contract research organizations are retrofitting compound management libraries with touchless dispensers. The technology is fragmenting incumbent liquid handler installed bases by eliminating cross-contamination risks in precious sample workflows.
EU MDR analytical performance requirements are compressing equipment validation timelines for in vitro diagnostic manufacturers. CE-marked sample prep modules must now demonstrate traceable uncertainty budgets before European commercialization. German notified bodies are prioritizing review capacity for automated nucleic acid extraction platforms serving oncology companion diagnostics.
Service unbundling is separating maintenance contracts from capital equipment financing in United States hospital laboratory procurement. Third-party ISO 17025-certified service providers are capturing centrifuge calibration and rotor inspection work previously captive to OEM channels. Academic medical centers in Boston and San Francisco are piloting outcome-based uptime guarantees independent of original equipment vendor relationships.
Sample Preparation Equipment Market Segmentation
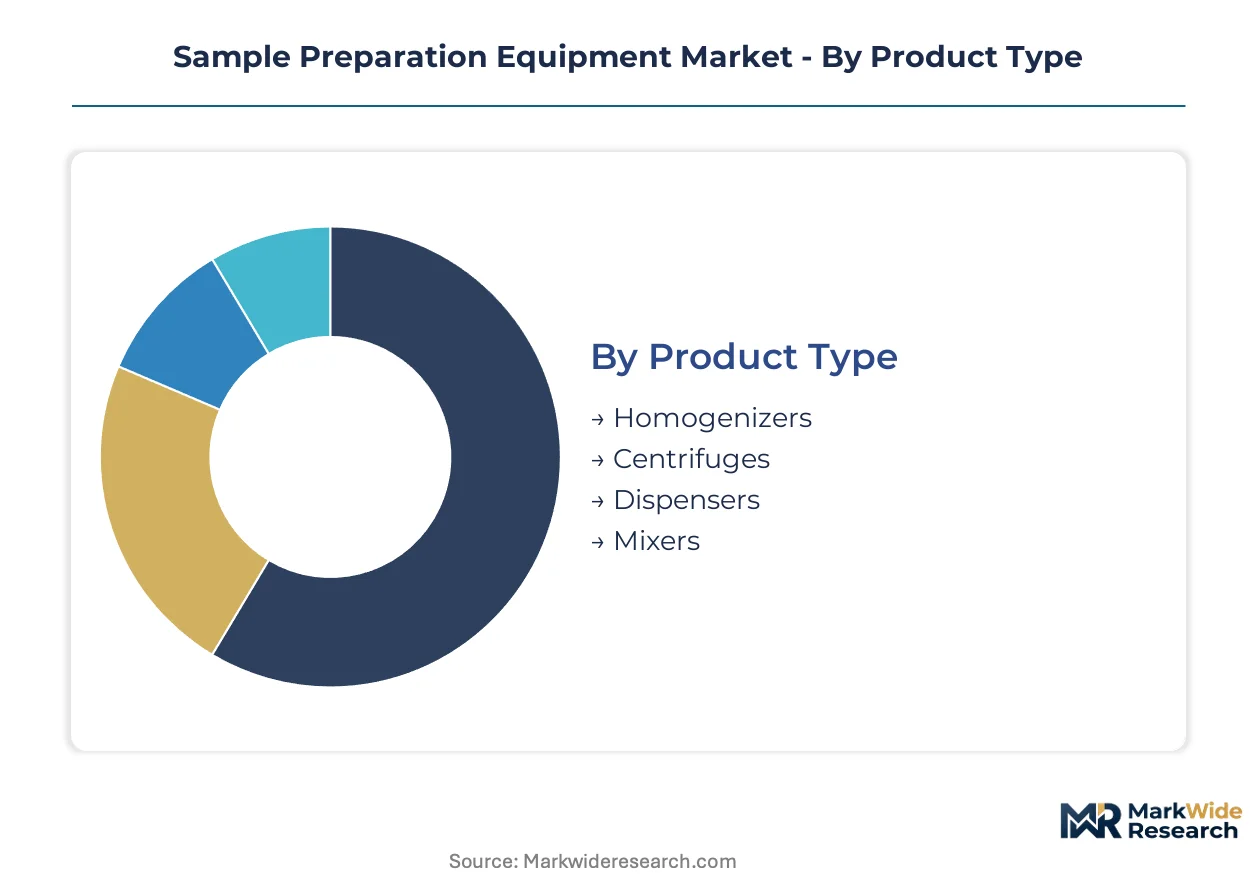
Segmentation reveals where equipment vendors capture recurring revenue versus one-time capital sales. Understanding technology-application pairings exposes which laboratories face the steepest switching costs when migrating between prep protocols.
Product Type:
Margin pools concentrate in consumables-anchored systems where rotor replacements and specialized vessels generate multi-year revenue streams.
- Centrifuges:Rotor-based separation systems dominate pharmaceutical quality control workflows with refrigerated units commanding premium positioning. Beckman Coulter and Eppendorf maintain captive installed bases in United States and Germany where GLP-certified facilities require traceable calibration documentation.
- Homogenizers:Mechanical disruption equipment processes tissue and cellular samples through bead-beating, blade, or ultrasonic mechanisms. European reference laboratories confronting mycotoxin testing backlogs are unbundling service contracts to accelerate food safety throughput.
- Dispensers:Liquid handling modules range from single-channel pipettes to 384-well acoustic systems.
- Mixers:Orbital and vortex platforms standardize reagent distribution across microplate formats.
Centrifuges hold installed capacity. Homogenizers are rotating up the share rankings.
Application:
Volume concentrates in regulated verticals where FDA and EPA mandates force synchronous equipment upgrades.
- Pharmaceuticals:Biologics stability testing and quality control workflows demand automated prep lines with 21 CFR Part 11 electronic records compliance. Contract research organizations in Germany and the United States are commissioning high-throughput screening infrastructure.
- Environmental Analysis:Wastewater laboratories execute EPA Method 1664 oil and grease protocols requiring mandatory rotor recertification. PFAS monitoring workflows are migrating from manual solid-phase extraction to automated platforms.
- Food Testing:Allergen and mycotoxin detection drives homogenizer demand.
- Material Science:Sample prep for spectroscopic analysis spans metals, polymers, and composites.
Pharmaceuticals anchors revenue concentration. Environmental Analysis is climbing the fastest on regulatory recertification cycles.
End User:
Customer type determines purchasing authority structure and total cost of ownership frameworks.
- Quality Control Labs:Pharmaceutical and food manufacturing QC departments operate under strict protocol standardization with ISO 17025 accreditation requirements filtering vendor access. These facilities prioritize uptime guarantees and preventive maintenance contracts.
- Research Laboratories:Academic and discovery settings sequencing SARS-CoV-2 variants require flexible biological preparation protocols including cell lysis and nucleic acid extraction.
- Clinical Labs:Hospital pathology departments face cell lysis method standardization gaps.
- Academic Institutions:University core facilities balance capital constraints against multi-user accessibility.
Quality Control Labs dominates replacement demand. Research Laboratories is gaining share fastest on single-cell genomics expansion.
Technology:
Maturity curves separate commodity mechanical systems from premium biological protocols.
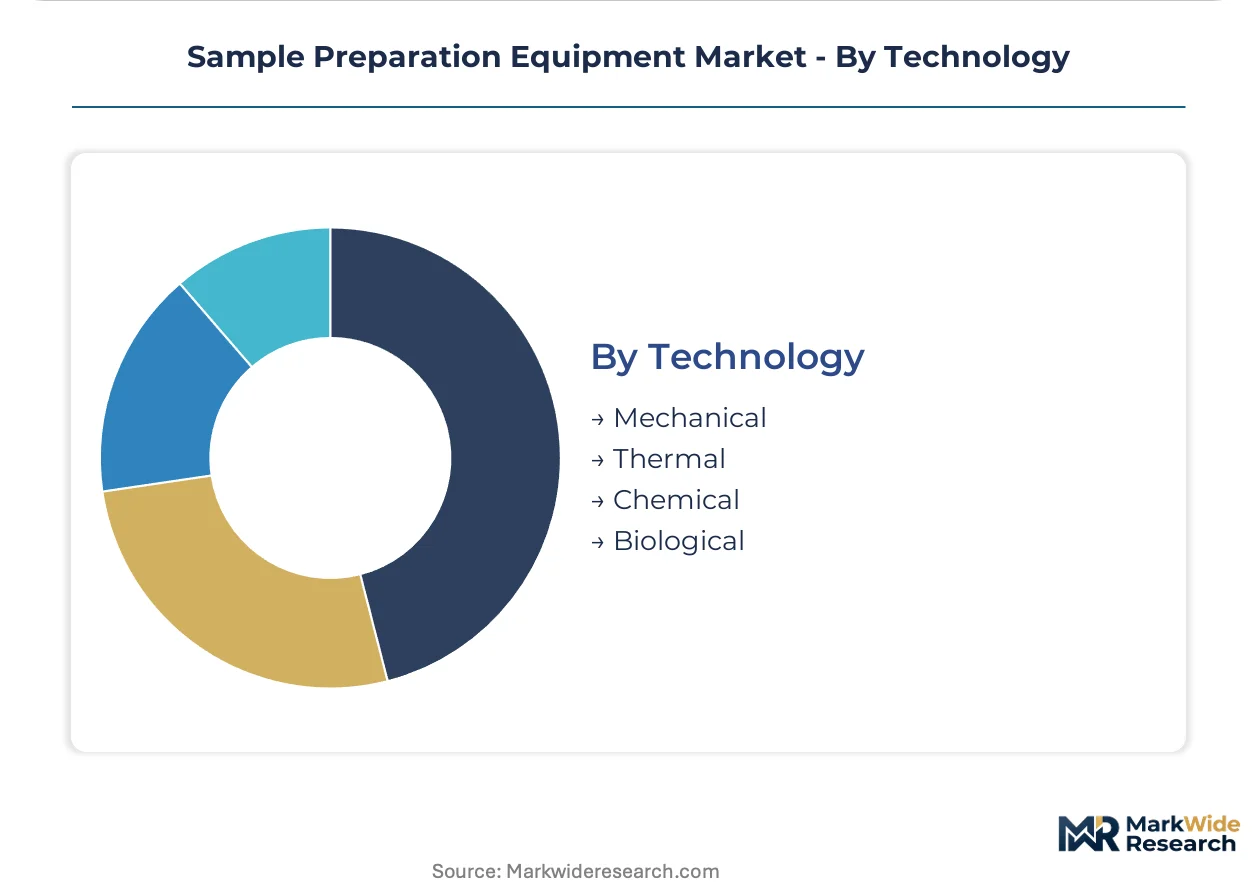
- Biological:Enzymatic treatment and nucleic acid extraction platforms command premium pricing in research settings processing emerging pathogens. China's NMPA traceability mandates are forcing domestic IVD laboratories toward automated prep with audit trails.
- Mechanical:Centrifugation, grinding, and homogenization occupy the majority of unit shipments but face margin compression from commoditized rotor designs and stainless steel input cost volatility.
- Thermal:Digestion and ashing systems prepare samples for elemental analysis.
- Chemical:Extraction and derivatization protocols support chromatographic downstream workflows.
Mechanical technology holds shipment volume leadership. Biological preparation is rotating up the share rankings on sequencing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical logistics infrastructure underwrites Europe's sample prep equipment throughput, while the Shanghai Yangshan deep-water port anchors Asia-Pacific distribution. These maritime gateways connect GLP-certified manufacturing clusters to regulated laboratory networks.
United States
FDA 21 CFR Part 11 compliance deadlines are accelerating replacement cycles in pharmaceutical quality control facilities. EPA Method 1664 oil and grease protocols mandate rotor recertification for environmental laboratories. The Boston-Cambridge biotech corridor commissions automated prep lines for biologics stability testing.
Germany
Contract research organizations in Baden-Württemberg expand GLP-certified capacity for European pharmaceutical clients. EU MDR analytical performance requirements compress validation timelines for in vitro diagnostic equipment vendors. The Rhine-Main biotech cluster drives demand for nucleic acid extraction automation.
China
NMPA traceability mandates for in vitro diagnostics force domestic laboratories toward audit-trail-capable automation platforms. Dual carbon goals pressure manufacturers to retrofit thermal digestion systems for energy efficiency. The Suzhou biomedical industrial park attracts foreign equipment vendors seeking NMPA-compliant installation bases.
Japan
PMDA quality management system inspections drive synchronization of sample prep workflows with electronic batch records. METI funding for advanced analytical instrumentation supports academic sequencing centers processing pathogen surveillance. The Kobe biomedical innovation cluster integrates robotic prep platforms with mass spectrometry infrastructure.
United Kingdom
MHRA post-Brexit regulatory divergence creates parallel certification requirements for equipment serving UK and EU markets. The UK Research and Innovation funding framework prioritizes automated sample handling in national genomics initiatives. The Cambridge life sciences cluster negotiates outcome-based service contracts independent of OEM channels.
Sample Preparation Equipment Market Competitive Landscape
Listed leaders compete with private specialists across consumables-anchored business models, creating tiered competitive dynamics. The installed base concentrates around chromatography-integrated and mass spectrometry-compatible platform vendors. Three archetypes dominate: diversified life science conglomerates with captive consumables portfolios, precision instrumentation specialists with rotor-based separation expertise, and liquid handling automation firms with microfluidic integration capabilities. Competitive moves center on consumables lock-in economics and service contract unbundling to capture third-party calibration revenue.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify consumables-captive strategies that generate recurring revenue on installed prep systems. Agilent Technologies occupies a position among mass spectrometry-compatible automation specialists. These three listed entities anchor competitive positioning through contrasting approaches to laboratory workflow integration and regulatory compliance documentation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Merck KGaA |
| Danaher Corporation |
| QIAGEN |
| PerkinElmer |
| Bio-Rad Laboratories |
| Tecan Group |
| Hamilton Company |
| Others |
Value Network & Pricing Analysis
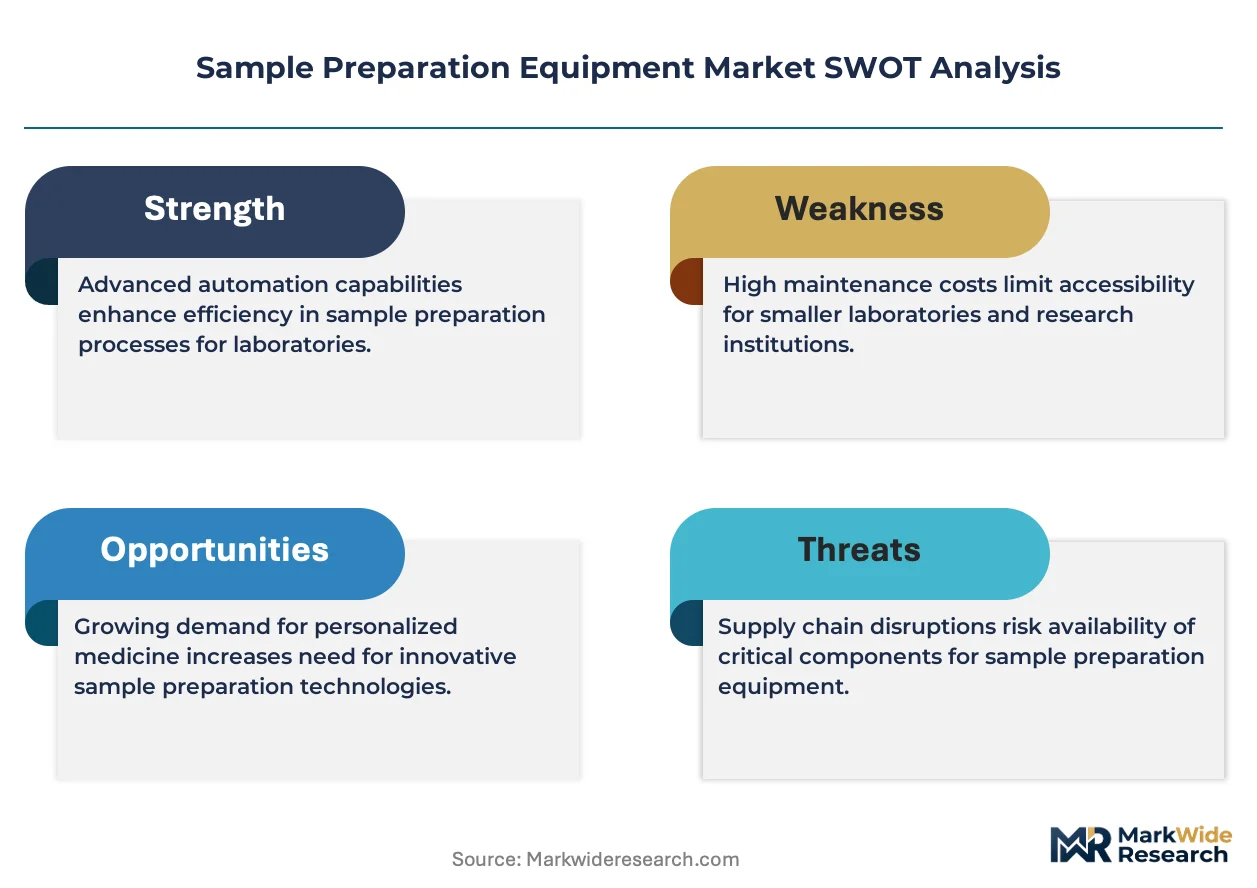
ISO 17025 accreditation gates both vendor qualification and price differentiation in sample preparation equipment, forcing uncertified suppliers into steep discounts while GLP-compliant platforms command maintenance-contract premiums from pharmaceutical quality control departments.
Pricing Analysis
Certification level creates the primary spread across the market, with FDA 21 CFR Part 11-compliant automation systems pricing at substantial premiums over standard laboratory equipment. Three-tier pricing structure across premium, standard, and economy levels separates GLP-validated platforms with audit-trail software from basic mechanical units. Cost compression in the centrifuge rotor segment is intensifying because stainless steel and rare-earth magnet input volatility squeezes manufacturer margins. Contract research organizations show the least price sensitivity due to regulatory compliance mandates, while mid-sized clinical laboratories face acute switching friction from captive consumables ecosystems.
Supply Chain Analysis
Shanghai Yangshan deep-water port throughput anchors Asia-Pacific distribution for precision instrumentation, connecting Chinese component manufacturers to global laboratory networks. Manufacturing concentrates in Germany, the United States, and China, with rotor forging and microfluidic chip fabrication drawing from specialized precision metal and polymer supply bases. Single-source vulnerability in rare-earth magnet sourcing for centrifuge motors creates exposure to export restriction shocks. Distribution runs through authorized dealer networks with ISO 17025-certified calibration capabilities, though third-party service unbundling is fragmenting aftermarket revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors who control scarce calibration expertise and captive consumables workflows, while laboratories struggle to reconcile total cost of ownership against locked-in proprietary formats.
For Market Incumbents: Compound installed base advantages by deepening consumables-anchored revenue streams through specialized rotor and vessel designs that resist third-party replacement. Accelerate software companion development for legacy LIMS integration to defend against robotic automation entrants. Prioritize ISO 17025 assessor certification investments to extend competitive moats as accreditation timelines lengthen. For New Entrants and Emerging Players: Anchor in China's NMPA traceability mandate window, where domestic IVD laboratories seek audit-trail-capable automation without incumbent switching costs. Target food safety mycotoxin testing backlogs in European reference laboratories unbundling homogenizer service contracts. Pursue outcome-based uptime guarantee pilots with academic medical centers in Boston and San Francisco to bypass OEM channel capture. For Investors and Strategic Acquirers: EU MDR analytical performance requirements reshape the acquisition landscape by compressing validation timelines and favoring platforms with existing CE-marked nucleic acid extraction modules. Long-term viability centers on recurring consumables economics rather than capital equipment sales velocity. Monitor ISO 17025 assessor capacity expansion as the inflection signal for vendor market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Portfolio Expansion | Captive rotor and vessel designs lock in recurring revenue on installed Beckman Coulter and Eppendorf centrifuge bases. |
| Software Companion Development | Custom middleware for legacy LIMS integration defends robotic prep platforms against acoustic liquid handling disruption. |
| Third-Party Service Certification | ISO 17025-certified calibration capabilities capture centrifuge maintenance work previously captive to OEM channels. |
| Microfluidic Integration Partnership | Single-cell genomics workflow alignment pulls 384-well format homogenizers into academic sequencing centers. |
| NMPA Compliance Fast-Track | Audit-trail-capable automation platforms access replacement windows in China's domestic IVD laboratory infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EPA Method validation documents, and EU MDR technical dossiers. Interviews with pharmaceutical quality control managers, clinical laboratory directors, and biomedical equipment procurement officers at GPOs and academic medical centers informed demand-side dynamics. Secondary validation drew from SEC 10-K equipment revenue disclosures, ISO 17025 accreditation body records, and NMPA in vitro diagnostic registration databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type and application segments.
Segmentation dimensions modeled include product type, application vertical, end-user category, and technology protocol across the projection horizon. Pharmaceutical quality control workflow automation rates and environmental laboratory EPA Method 1664 recertification cycles served as key demand-side forecast inputs. CAGRs derived from logistic adoption curves fitted to regulatory compliance deadline schedules and replacement cycle compression patterns.
Decision-makers should treat outputs as directional under assumptions of stable regulatory enforcement intensity and no material trade restriction expansion; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ISO 17025 assessor capacity constraints and rare-earth supply chain disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market