
 Vacuum & Low Pressure Diffusion Furnace Market | 2026-2036
Vacuum & Low Pressure Diffusion Furnace Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum & Low Pressure Diffusion Furnace Market Insights
Defense manufacturers are unwinding reliance on commercial semiconductor supply chains, redirecting capital toward captive diffusion furnace installations for radiation-hardened chip production. Tokyo Electron leverages its installed base in 300mm wafer processing to sustain aftermarket service contracts across Japanese and Korean fabs. NAURA Technology Group anchors its position through in-house production of vacuum pump subsystems, reducing lead times for domestic Chinese customers. Centrotherm competes on batch furnace configurations optimized for silicon carbide epitaxy, a process gaining traction in power electronics.
Vacuum and low pressure diffusion furnaces are hermetically sealed thermal processing systems operating at pressures below atmospheric, typically incorporating quartz process tubes, multi-zone resistance heating elements, and gas injection manifolds to achieve precise dopant profiles in semiconductor substrates. The primary industrial purpose centers on controlled thermal diffusion of impurities into silicon wafers to create p-n junctions essential for transistor and photovoltaic cell function. Low pressure furnaces dominate current procurement volumes for mainstream logic and memory fabrication, while vacuum batch configurations represent the fastest-growing segment as wide-bandgap semiconductor research intensifies. Hybrid heating technology captures concentrated margin pools by combining infrared preheating with resistance soak zones, reducing thermal budget violations in sub-7nm node processing.
EPA NESHAP standards for hazardous air pollutants from semiconductor manufacturing constrain furnace exhaust scrubbing architectures, while EU REACH Annex XVII restrictions on perfluorinated compounds limit process gas chemistries available for doping operations. China's SAMR enforces GB standards on industrial vacuum equipment safety interlocks, creating compliance barriers for imported systems lacking localized certification. Stakeholders must monitor evolving F-Gas Regulation phase-down schedules in Europe, as hydrofluorocarbon-based process gases face substitution pressures that will redefine furnace gas delivery system specifications.
Market Dynamics
EUV lithography node migration below 7nm is compressing thermal budget tolerances, forcing foundries to retire legacy atmospheric furnaces and recalibrate procurement specifications around multi-zone pressure control architectures.
Growth Catalysts
- Silicon Carbide Epitaxy Expansion:Power electronics manufacturers in automotive and renewable energy sectors are scaling SiC device fabrication, requiring low-pressure batch configurations with precise temperature uniformity for wide-bandgap substrate processing.
- EU F-Gas Regulation Phase-Down:Hydrofluorocarbon substitution mandates are accelerating furnace gas delivery system retrofits as fabs seek compliant chemistries for doping operations without process degradation.
- East Asian Manufacturing Cluster Concentration:Taiwan's Hsinchu Science Park and South Korea's Giheung semiconductor corridor concentrate demand for 300mm wafer-compatible vacuum diffusion systems with sub-atmospheric process control.
Market Restraints
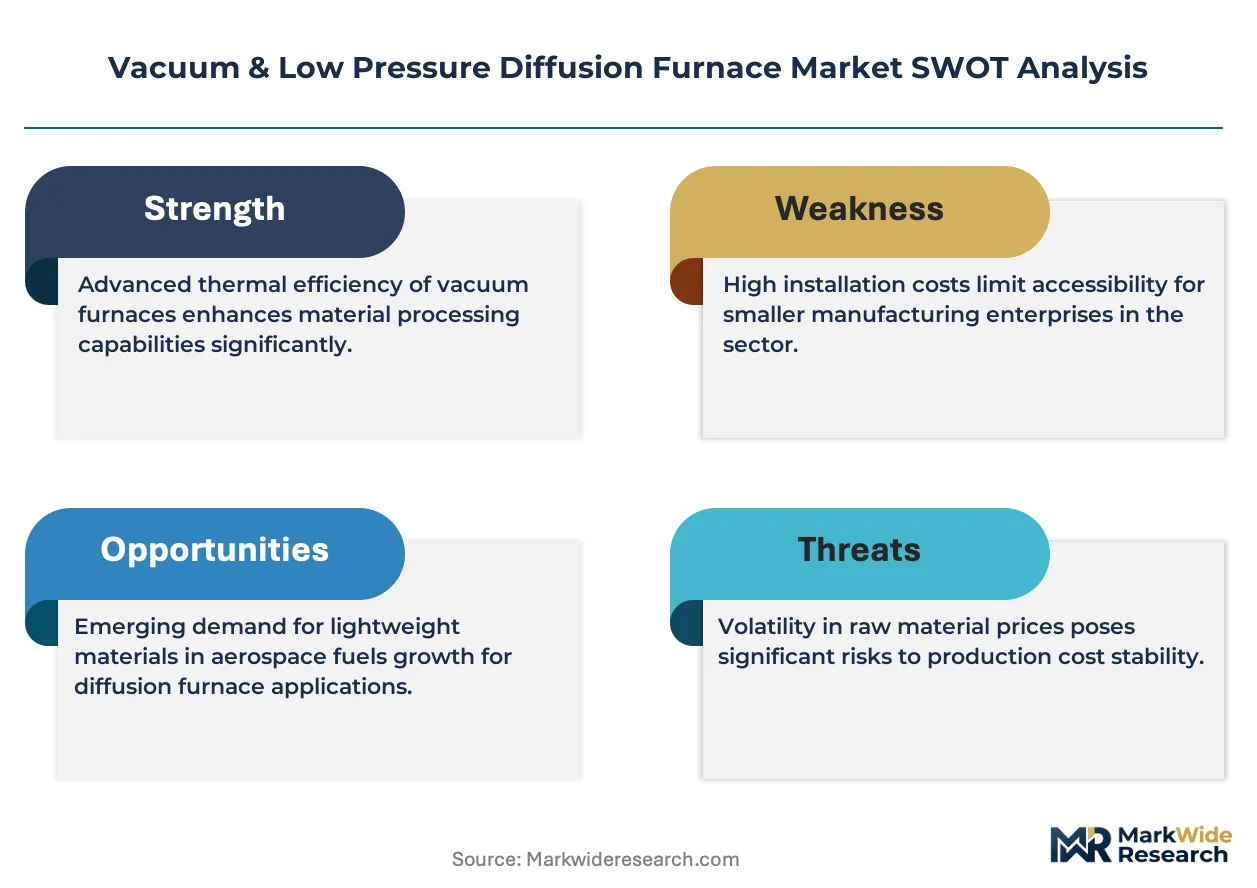
- Quartz Process Tube Supply Concentration:High-purity synthetic quartz production concentrates among Japanese and German suppliers, creating input bottlenecks when geopolitical friction disrupts cross-border material flows.
- EPA NESHAP Compliance Architecture:Hazardous air pollutant scrubbing requirements for semiconductor exhaust systems add capital intensity to furnace installations without direct process performance returns.
- Atmospheric Furnace Substitute Persistence:Legacy vertical and horizontal atmospheric diffusion systems retain installed base in trailing-edge node production, delaying replacement cycles in cost-sensitive analog and power semiconductor fabs.
Strategic Opportunities
- India Semiconductor Mission Incentives:Central and state-level capital subsidy frameworks for domestic fab construction create first-mover positioning for furnace vendors establishing local service infrastructure.
- Hybrid Infrared-Resistance Heating Convergence:Combining rapid thermal preheating with conventional resistance soak zones addresses sub-7nm thermal budget constraints while extending equipment applicability across node generations.
- Radiation-Hardened Chip Captive Production:Defense and aerospace end-users are building dedicated diffusion capacity outside commercial supply chains, opening specialized procurement channels with distinct certification requirements.
Industry Challenges
- Vacuum Pump Subsystem Integration Complexity:Matching turbomolecular and dry scroll pump specifications to multi-zone furnace architectures requires application engineering expertise scarce outside incumbent equipment vendors.
- China GB Standards Certification Timeline:SAMR safety interlock and pressure vessel compliance testing for imported systems extends sales cycles by 8-14 months versus domestic equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum & Low Pressure Diffusion Furnace Market |
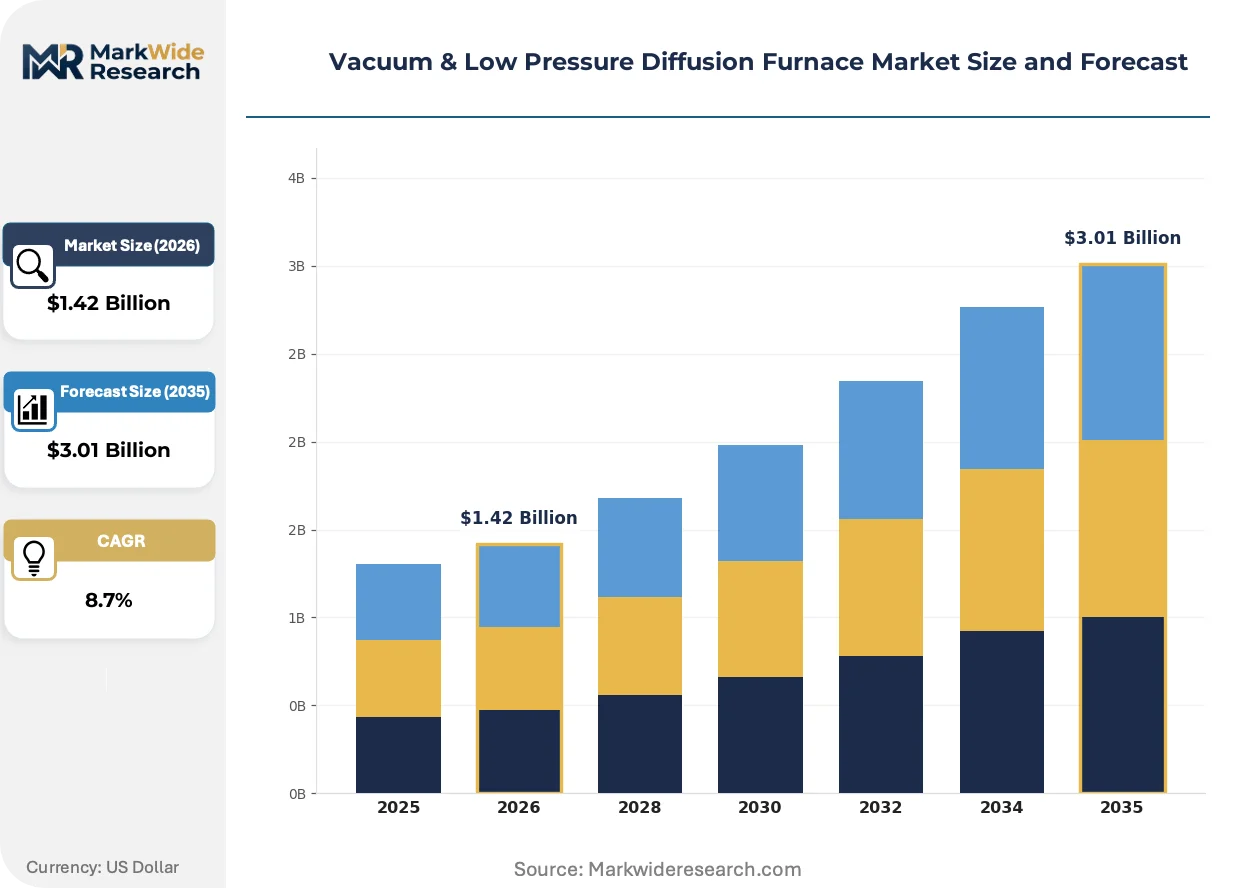
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
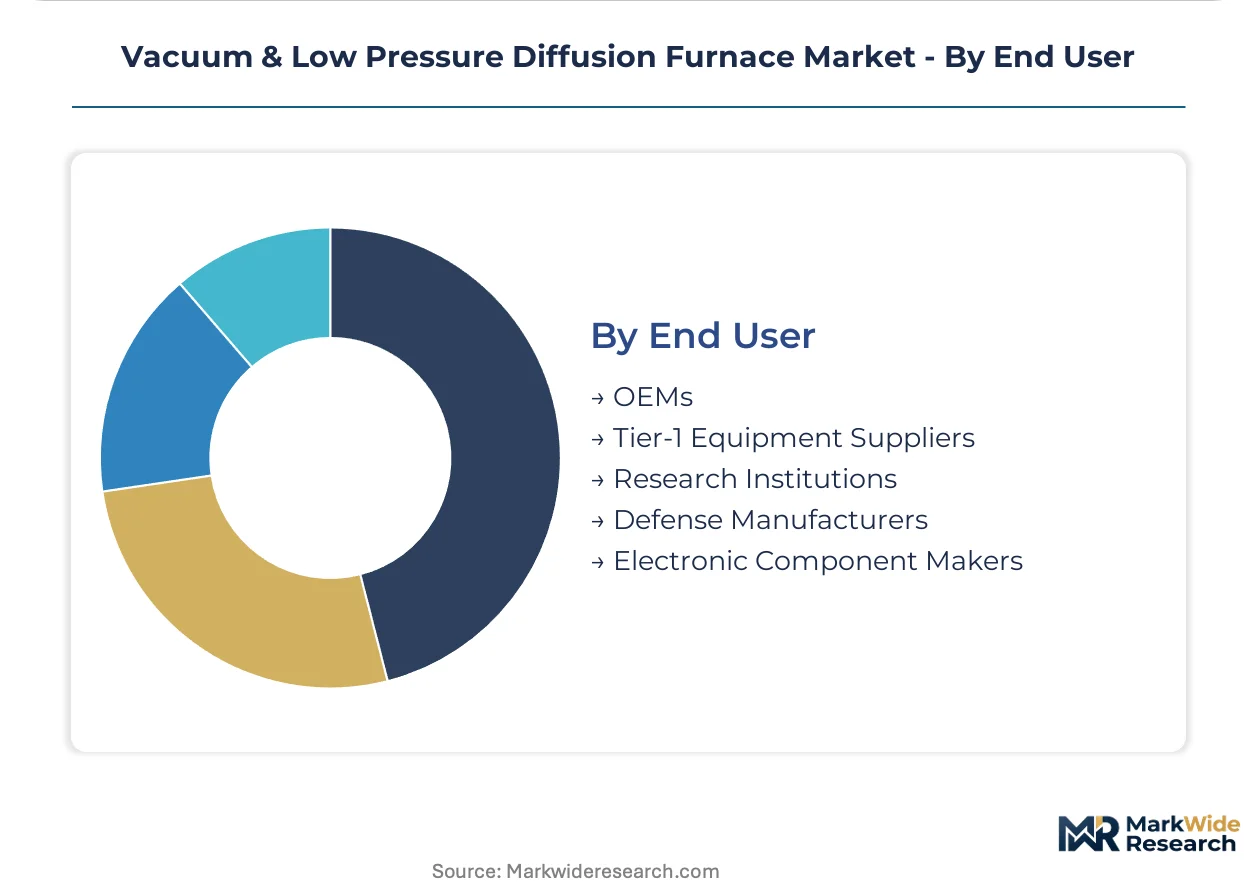
| Segmentation | Product Type: Vacuum Furnaces, Low Pressure Furnaces, Batch Furnaces, Continuous Furnaces Technology: Infrared Heating, Resistance Heating, Induction Heating, Gas Heating, Hybrid Heating Application: Semiconductor Processing, Solar Cell Manufacturing, LED Production, Aerospace Component Fabrication, Research Laboratories End User: OEMs, Tier-1 Equipment Suppliers, Research Institutions, Defense Manufacturers, Electronic Component Makers |
| Companies Covered | Axcelis, Tokyo Electron, Mattson, Thermco Systems, Centrotherm, SVCS, HKE, Sandvik, NAURA Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum & Low Pressure Diffusion Furnace Market Trends and Innovations
Thermal process equipment architectures are fragmenting between legacy batch platforms and emerging single-wafer alternatives as node economics and compound semiconductor requirements diverge.
Hybrid heating technology is bifurcating furnace product strategies across the supplier base. Infrared preheating modules combined with resistance soak zones enable rapid thermal ramp rates without quartz tube thermal shock. Memory and logic foundries at 5nm and below are specifying these configurations to minimize dopant diffusion length variations. The technology is bifurcating vendor R&D allocation between trailing-edge cost optimization and leading-edge thermal precision.
REACH Annex XVII perfluorinated compound restrictions are constraining process gas chemistries available for boron and phosphorus doping operations. ECHA substance evaluation timelines are compressing the window for qualifying alternative precursor compounds in production environments. European fabs are responding with accelerated gas delivery system redesigns to accommodate fluorine-free chemistries without throughput penalties.
Aftermarket service contract unbundling is fragmenting traditional equipment procurement relationships. Foundries are separating hardware acquisition from preventive maintenance and spare parts agreements, pressuring OEM service margins. This pattern concentrates in Japanese and Korean 300mm fabs where Tokyo Electron's installed base density supports third-party service competition.
Vacuum & Low Pressure Diffusion Furnace Market Segmentation
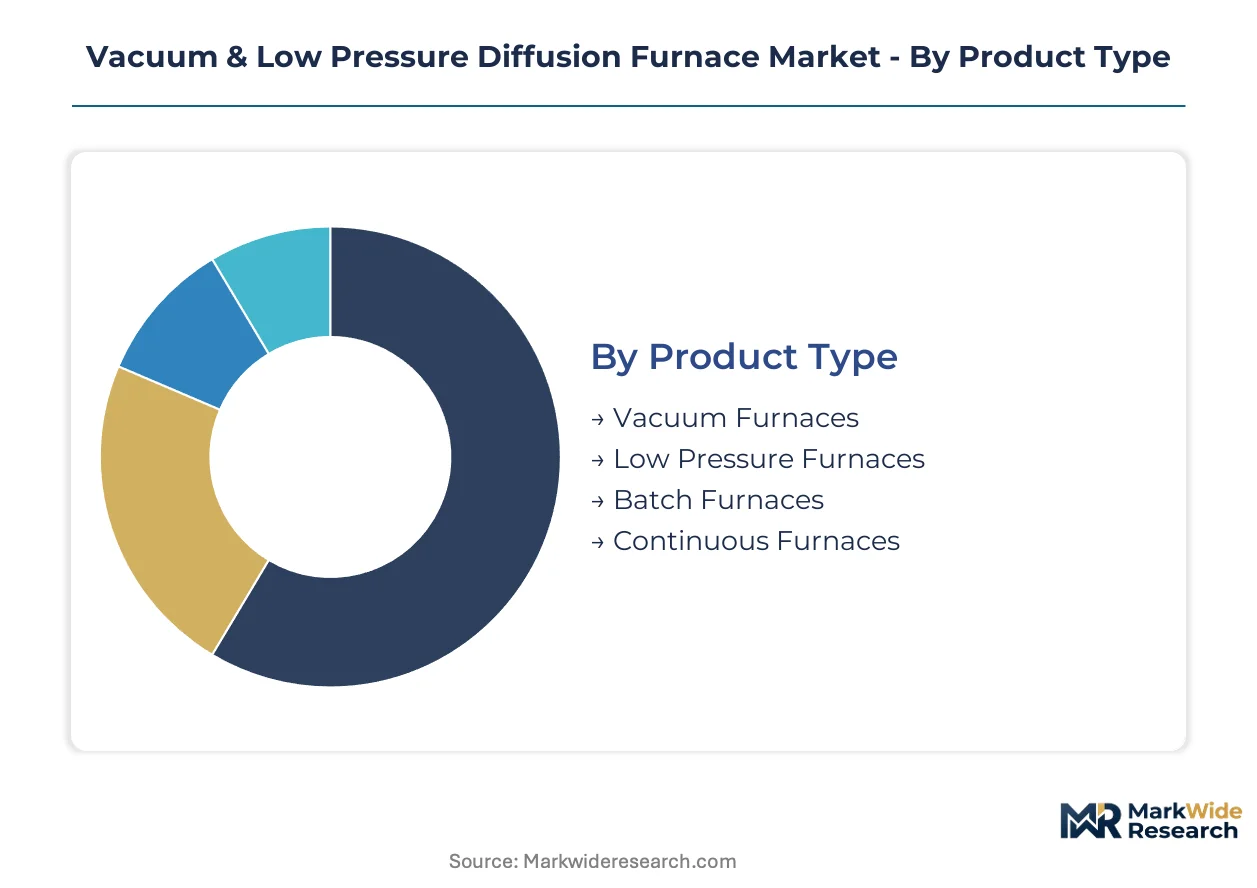
Segmentation in vacuum and low pressure diffusion furnaces reveals how equipment specifications diverge across thermal budget requirements, wafer throughput needs, and regulatory compliance architectures. Procurement channels fragment between direct OEM sales for greenfield fabs, distributor networks for research laboratories, and defense contracting vehicles for radiation-hardened chip production.
Product Type:
Channel distribution varies sharply by furnace configuration, with vacuum batch systems flowing through specialized semiconductor equipment distributors while continuous furnaces move via direct OEM engagement with high-volume solar manufacturers.
- Vacuum Furnaces:Hermetically sealed systems operating below atmospheric pressure with turbomolecular pump subsystems and multi-zone temperature control. Demand concentrates in Taiwan's Hsinchu Science Park for sub-7nm logic node processing where thermal budget constraints mandate precise pressure control. EU F-Gas Regulation phase-down is accelerating retrofit demand for compliant gas delivery architectures.
- Low Pressure Furnaces:Systems maintaining partial vacuum conditions for mainstream dopant diffusion with reduced oxidation. Procurement clusters in South Korea's Giheung semiconductor corridor for DRAM and NAND memory fabrication where cost-efficiency balances thermal precision. EPA NESHAP scrubbing requirements add capital intensity to installations serving US-based fabs.
- Batch Furnaces:Multi-wafer processing platforms optimized for silicon carbide epitaxy in power electronics applications.
- Continuous Furnaces:Inline thermal processing systems deployed in high-throughput solar cell manufacturing lines.
Vacuum Furnaces dominate installed base. Low Pressure Furnaces are where expansion concentrates.
Technology:
Cost tier stratification separates premium hybrid configurations from standard resistance heating, with infrared modules commanding price premiums for sub-7nm node compatibility.
- Hybrid Heating:Combines infrared preheating zones with resistance soak sections to achieve rapid thermal ramp rates without quartz tube thermal shock. Memory foundries at 5nm and below specify these systems to minimize dopant diffusion length variations. The technology is climbing the fastest as leading-edge thermal precision requirements displace legacy configurations.
- Resistance Heating:Conventional multi-zone resistance elements delivering uniform temperature profiles across wafer batches. Trailing-edge analog and power semiconductor fabs in China retain these systems where cost sensitivity outweighs thermal budget constraints. SAMR GB standards certification timelines extend procurement cycles for imported configurations.
- Infrared Heating:Rapid thermal processing modules for single-wafer or small-batch applications requiring minimal thermal mass.
- Induction Heating:Electromagnetic field-based heating for specialized compound semiconductor processing.
- Gas Heating:Combustion-based thermal systems constrained by emissions regulations in European installations.
Resistance Heating retains volume leadership. Hybrid Heating is where technology investment flows.
Application:
Customer type differentiation separates capital-intensive fab equipment from research-scale systems, with semiconductor processing commanding dedicated application engineering support.
- Semiconductor Processing:Controlled thermal diffusion for p-n junction formation in silicon wafers across logic, memory, and analog device fabrication. East Asian manufacturing clusters in Taiwan and South Korea concentrate demand for 300mm-compatible systems. EUV lithography node migration is compressing thermal budget tolerances and forcing atmospheric furnace retirements.
- Solar Cell Manufacturing:Phosphorus and boron diffusion for photovoltaic cell emitter formation. Chinese domestic production scales drive procurement of cost-optimized batch configurations with reduced automation. India's Semiconductor Mission incentives are redirecting some capital toward domestic solar-grade silicon processing.
- LED Production:Epitaxial layer thermal processing for gallium nitride and related compound semiconductors.
- Aerospace Component Fabrication:Specialized thermal treatment for radiation-hardened and high-reliability electronics.
- Research Laboratories:Flexible-configured systems for wide-bandgap semiconductor development and process chemistry qualification.
Semiconductor Processing anchors revenue. Solar Cell Manufacturing is where volume expansion accelerates.
End User:
Margin structure varies by buyer sophistication, with defense manufacturers accepting premium pricing for specialized certification and research institutions driving aftermarket service unbundling.
- OEMs:Integrated device manufacturers and foundries operating captive diffusion capacity for internal wafer processing. Japanese and Korean 300mm fabs are separating hardware acquisition from preventive maintenance contracts, pressuring OEM service margins. Tokyo Electron's installed base density supports third-party service competition in this channel.
- Defense Manufacturers:Captive production facilities for radiation-hardened chips outside commercial supply chains. These buyers require distinct certification protocols and accept extended procurement timelines for security-cleared installation personnel. The segment commands premium pricing for specialized vacuum pump redundancy and hardened control architectures.
- Tier-1 Equipment Suppliers:Subsystem integrators sourcing furnace modules for larger process tool platforms.
- Research Institutions:Universities and national laboratories qualifying next-generation process chemistries and wide-bandgap materials.
- Electronic Component Makers:Discrete device and analog semiconductor manufacturers with trailing-edge process requirements.
OEMs dominate transaction volume. Defense Manufacturers are where pricing power concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Taichung high-speed rail corridor underwrites Taiwan's central role in semiconductor equipment logistics, while the Trans-Siberian rail link enables German quartz suppliers to reach East Asian fabs within 14 days. These infrastructure assets anchor regional demand concentration.
United States
Defense manufacturers in Arizona and Texas are building captive diffusion capacity for radiation-hardened chips outside commercial supply chains. EPA NESHAP standards constrain exhaust scrubbing architectures for new installations. The Phoenix-Tucson semiconductor corridor concentrates procurement for 300mm wafer-compatible systems.
China
Domestic fab construction under the 14th Five-Year Plan is redirecting capital toward NAURA Technology Group and other local equipment vendors. SAMR enforces GB standards on industrial vacuum equipment safety interlocks, extending sales cycles for imported systems. The Yangtze River Delta cluster around Shanghai drives volume demand for cost-optimized batch configurations.
Japan
High-purity synthetic quartz production concentrates among domestic suppliers, creating input bottlenecks when geopolitical friction disrupts material flows. METI industrial policy supports equipment vendors maintaining installed base density in 300mm fabs. The Kyushu-Tokyo manufacturing axis anchors aftermarket service contract competition.
South Korea
Memory foundries at Samsung and SK Hynix are specifying hybrid heating configurations to address sub-7nm thermal budget constraints. The Giheung semiconductor corridor concentrates demand for low-pressure systems with precise temperature uniformity. National industrial policy prioritizes domestic equipment sourcing for new greenfield investments.
Germany
Centrotherm anchors European supply for batch furnace configurations optimized for silicon carbide epitaxy. EU REACH Annex XVII restrictions on perfluorinated compounds limit process gas chemistries available for doping operations. The Saxony semiconductor cluster around Dresden drives qualification of fluorine-free precursor compounds.
Vacuum & Low Pressure Diffusion Furnace Market Competitive Landscape
Concentration sits with diversified semiconductor equipment conglomerates and specialized thermal processing vendors. The vendor base fragments across three tiers: integrated process tool platforms, standalone furnace specialists, and regional equipment fabricators serving captive domestic demand. Two strategic archetypes dominate—vertically integrated conglomerates with vacuum pump subsystem capabilities, and technology licensors partnering with local manufacturers for geographic expansion. Competitive moves center on aftermarket service contract unbundling and hybrid heating technology licensing.
Among diversified equipment conglomerates, Tokyo Electron and NAURA Technology Group exemplify contrasting geographic anchoring strategies. Tokyo Electron leverages installed base density in Japanese and Korean 300mm fabs to sustain service revenue streams, while NAURA Technology Group reduces lead times through in-house vacuum pump production for domestic Chinese customers. Centrotherm occupies a position within the European specialist tier, representing batch furnace expertise for wide-bandgap semiconductor applications.
| Leading Market Players |
|---|
| Axcelis |
| Tokyo Electron |
| Mattson |
| Thermco Systems |
| Centrotherm |
| SVCS |
| HKE |
| Sandvik |
| NAURA Technology Group |
| Others |
Pricing and Supply Chain Analysis
Hydrofluorocarbon substitution chemistries are displacing legacy process gases across European fabs, simultaneously rerouting procurement toward certified gas delivery system vendors and compressing margin structures for furnace OEMs unable to retrofit installed bases. This substitution dynamic concentrates pricing power with subsystem specialists while fragmenting equipment bundling economics.
Pricing Analysis
Volume-discount tiering separates captive foundry procurement from research-scale installations, with three-tier pricing structure across premium, standard, and economy levels anchored to certification grade and after-sales service bundling. Premium hybrid heating configurations command 40-60% markups over resistance-only systems due to sub-7nm node compatibility. Pricing pressure stems from aftermarket service contract unbundling as Japanese and Korean fabs separate hardware acquisition from preventive maintenance agreements. Research institutions exhibit highest price sensitivity, while defense manufacturers accept extended procurement timelines for security-cleared installation personnel.
Supply Chain Analysis
Strait of Malacca transit routes underwrite quartz process tube logistics from Japanese and German suppliers to Taiwan's Hsinchu Science Park and South Korea's Giheung corridor. High-purity synthetic quartz production draws from Shin-Etsu and Heraeus facilities, with turbomolecular pump subsystems sourced from Edwards and Pfeiffer Vacuum. Single-source vulnerability concentrates in synthetic quartz feedstock, where geopolitical friction disrupts cross-border material flows. Distribution runs through specialized semiconductor equipment distributors for vacuum batch systems, while continuous furnace configurations move via direct OEM engagement with solar manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap semiconductor research is accelerating furnace demand beyond silicon carbide epitaxy into gallium nitride and related compound materials, signaling early-cycle expansion with penetration headroom in power electronics and RF applications.
For Market Incumbents: Fortify aftermarket service density in 300mm Japanese and Korean fabs to offset hardware margin compression from contract unbundling. Deepen backward integration into vacuum pump subsystems to match NAURA Technology Group's lead time advantages in China. Prioritize GB standards certification investment to preempt SAMR compliance barriers for imported systems. For New Entrants and Emerging Players: Lead with silicon carbide epitaxy batch furnace configurations targeting India's Semiconductor Mission subsidy window, where domestic fab construction lacks established equipment vendor relationships. Penetrate the defense radiation-hardened chip segment through security-cleared installation partnerships, leveraging extended procurement timelines that disadvantage incumbents optimized for commercial foundry velocity. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors subsystem specialists with vacuum pump integration capabilities over pure-play furnace fabricators. Long-term viability hinges on hybrid heating technology licensing positions and geographic diversification beyond East Asian manufacturing clusters. Monitor EU F-Gas Regulation phase-down schedules as inflection indicator for gas delivery system retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Heating Technology Licensing | Enables foundries at 5nm and below to minimize dopant diffusion length variations without quartz tube thermal shock. |
| GB Standards Certification Investment | Reduces SAMR safety interlock compliance timelines from 8-14 months for imported vacuum diffusion systems. |
| Vacuum Pump Subsystem Integration | Matches turbomolecular and dry scroll pump specifications to multi-zone furnace architectures for leading-edge thermal precision. |
| Aftermarket Service Contract Unbundling | Separates hardware acquisition from preventive maintenance agreements, pressuring OEM service margins in Japanese and Korean fabs. |
| Silicon Carbide Epitaxy Capacity Expansion | Addresses power electronics demand from automotive and renewable energy sectors requiring low-pressure batch configurations. |
Research Methodology
Cross-validation between primary interviews with fab process engineers, equipment procurement managers, and aftermarket service directors anchors the qualitative findings, while secondary validation draws from SEMI equipment market data, EPA NESHAP regulatory filings, and EU REACH substance restriction updates. Bottom-up triangulation aggregates furnace shipment data by configuration and geography, reconciled against top-down semiconductor capital expenditure disclosures from foundry operators.
Sensitivity analysis around EU F-Gas Regulation phase-down timelines and China GB standards enforcement intensity tests forecast robustness across the projection horizon. Segmentation dimensions span product type, heating technology, application, and end-user archetype, with node migration below 7nm and wide-bandgap material adoption as industry-specific demand drivers. CAGRs derive from equipment replacement cycle modeling and greenfield fab construction pipelines.
Forecasts assume regulatory continuity in EU REACH and China SAMR regimes; material policy shifts would require re-modeling. Specific risks include quartz supply disruption from geopolitical friction and hydrofluorocarbon substitution chemistry qualification delays. Practitioners should keep alternative scenarios live as EPA NESHAP enforcement intensity and India Semiconductor Mission subsidy disbursement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Sputtering Equipment Cathode Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Plasma Etching Equipment Market