
 Lithography Equipment Market | 2026-2036
Lithography Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Lithography Equipment Market Intelligence
The adoption of Extreme Ultraviolet (EUV) lithography for sub-7 nanometer process nodes is reorganizing the competitive landscape for semiconductor fabrication equipment. ASML Holding N.V. dominates this high-end segment with its proprietary technology. In parallel, Nikon Corporation and Canon Inc. sustain strong positions in the deep ultraviolet (DUV) and i-line stepper markets. Carl Zeiss SMT GmbH provides critical optical components, anchoring the supply chain for leading-edge tools.
Lithography equipment refers to the machinery that projects geometric patterns from a photomask onto a light-sensitive photoresist on a substrate. This process is fundamental to microfabrication, with resolution capabilities extending below 10 nanometers using advanced EUV systems. While EUV Lithography is the highest-value product type for leading-edge semiconductor manufacturers, Deep Ultraviolet technology remains the workhorse for a broad range of integrated circuits and microelectromechanical systems.
Export controls, such as those administered by governments in the United States and the Netherlands, significantly influence market access and technology transfer. Industry standards from organizations like SEMI, alongside environmental regulations such as the EU's RoHS directive, shape equipment design and material usage. Navigating the complex interplay between national security interests and the semiconductor industry's supply chain requirements will define strategic decision-making for equipment vendors and foundries.
Market Dynamics
Intensive capital requirements and extreme technological concentration define the lithography equipment market. The necessity for foundries to invest billions in single EUV systems to remain competitive creates a high barrier to entry, consolidating market power with a few key vendors.
Growth Catalysts
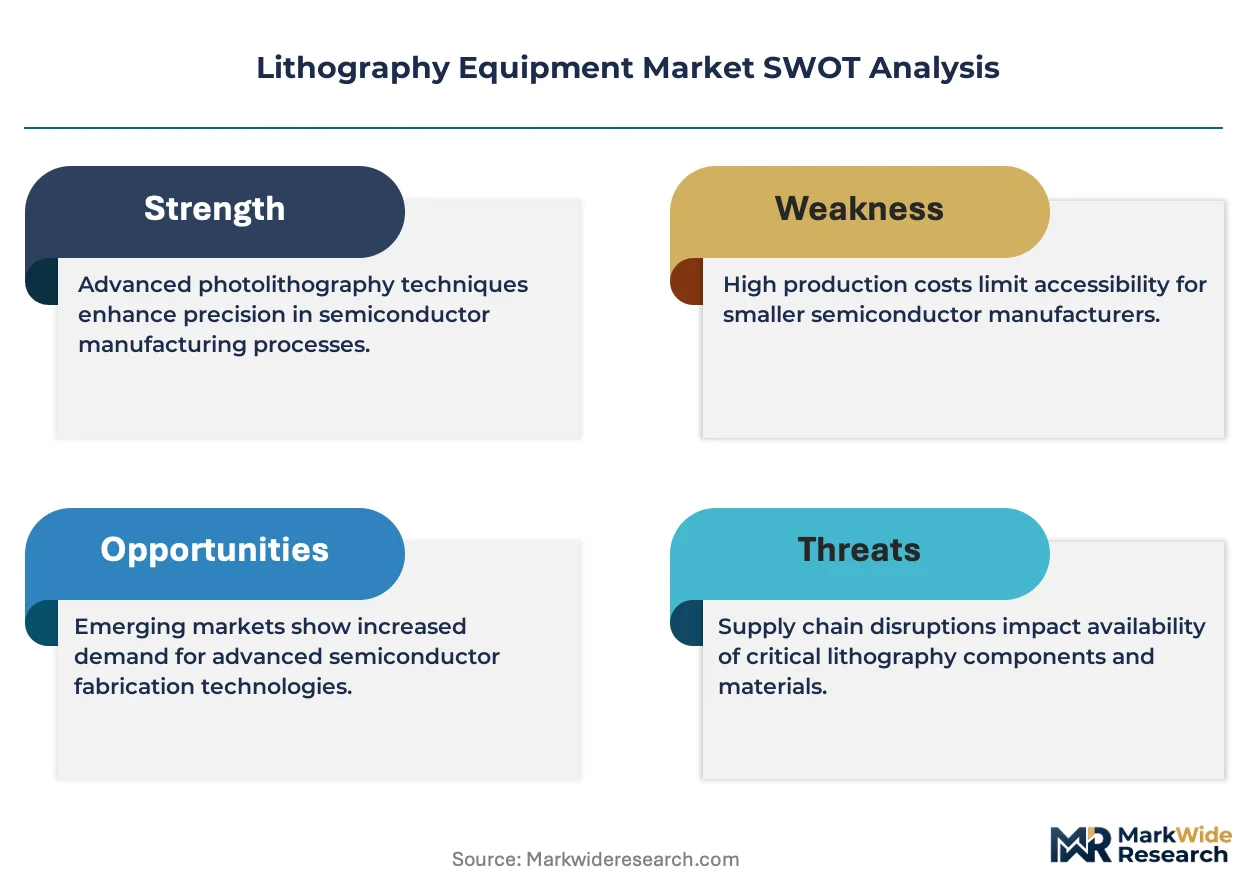
- Next-Generation Computing:Demand for advanced semiconductors for artificial intelligence, high-performance computing (HPC), and data centers necessitates the adoption of EUV lithography to produce sub-7nm process nodes.
- Geopolitical Diversification:National semiconductor initiatives, such as the US CHIPS Act and the EU Chips Act, are stimulating the construction of new fabrication plants in North America and Europe, creating localized demand for a full range of lithography tools.
- Automotive and IoT Expansion:The proliferation of electronics in vehicles and Internet of Things (IoT) devices drives sustained demand for mature-node lithography equipment, including DUV and i-line systems, for manufacturing microcontrollers and sensors.
Market Restraints
- Extreme System Cost:The prohibitive acquisition and operational costs of EUV lithography systems limit their adoption to only the most well-capitalized semiconductor manufacturers, constraining broader market access.
- Single-Source Dependency:The EUV segment's reliance on a single commercial supplier creates a significant supply chain bottleneck and strategic vulnerability for the entire semiconductor ecosystem.
- Export Controls:Technology transfer restrictions, such as those implemented by governments in the Netherlands and the United States, limit the sale of advanced lithography systems to certain countries, fragmenting the market geographically.
Strategic Opportunities
- Alternative Lithography Techniques:Developing and commercializing technologies like nanoimprint lithography (NIL) for niche applications such as photonics or memory creates opportunities outside the mainstream CMOS roadmap.
- Directed Self-Assembly (DSA):The integration of DSA as a complementary patterning technique with DUV or EUV systems offers a pathway to enhance resolution and reduce process complexity for future nodes. *Mature Node Specialization: Servicing the growing demand for 200mm and 300mm tools for power, analog, and MEMS devices provides a stable revenue stream for vendors with strong DUV and i-line portfolios.
Industry Challenges
- Talent Scarcity:A critical shortage of physicists, optical engineers, and service technicians with the specialized skills to develop, install, and maintain next-generation lithography systems hampers industry expansion.
- Optical Component Bottlenecks:The intricate supply chain for critical components, particularly the large, flawless optics and complex light sources required for EUV tools, is susceptible to disruption and long lead times.
- Integration with Metrology:Ensuring precise pattern overlay and critical dimension uniformity requires increasingly sophisticated and tightly integrated metrology and inspection systems, adding to process complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithography Equipment Market |
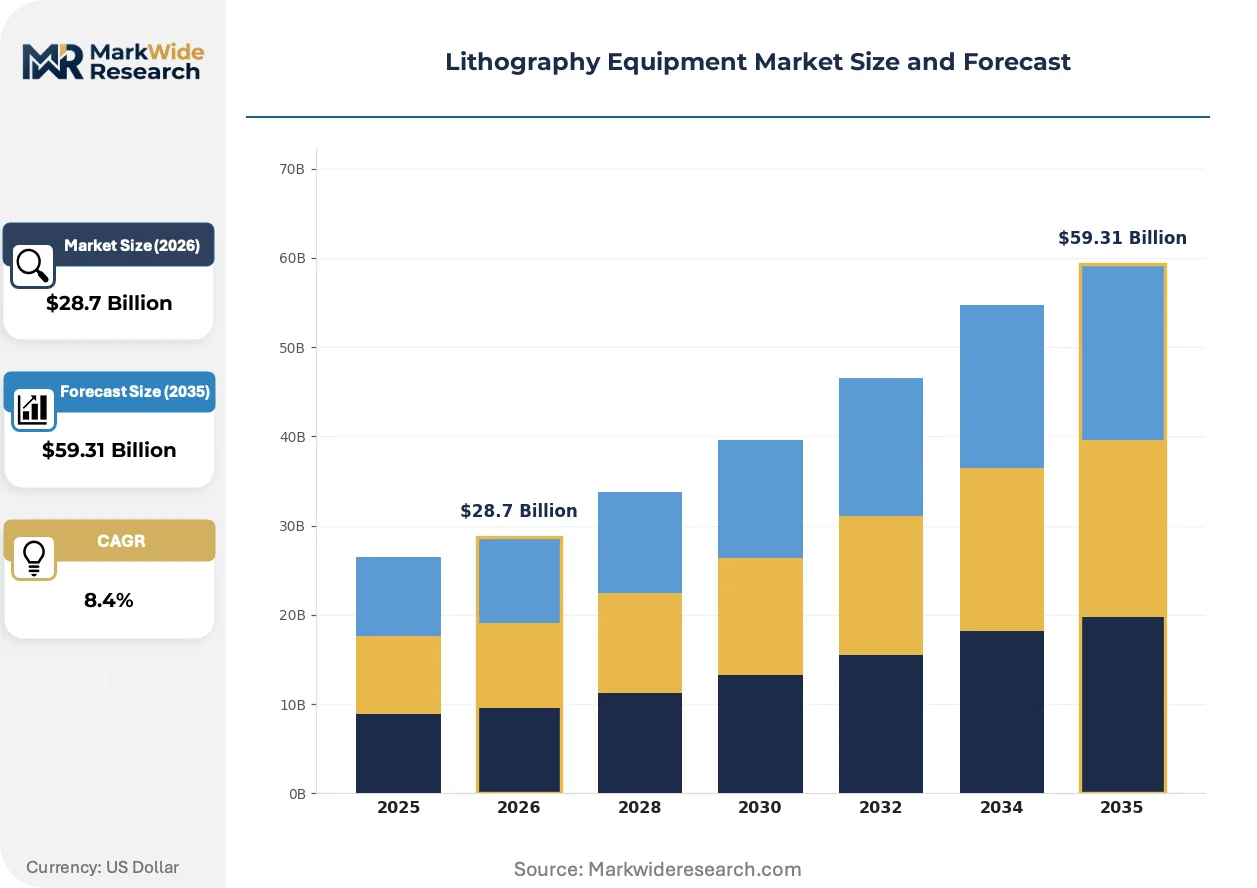
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photolithography, Maskless Lithography, EUV Lithography, Nanoimprint Lithography Technology: Extreme Ultraviolet, Deep Ultraviolet, Near Ultraviolet, Electron Beam End User: Semiconductor Manufacturers, Research Institutes, Display Manufacturers, Academic Institutions Application: Integrated Circuits, Photonic Devices, Microelectromechanical Systems, Flat Panel Displays |
| Companies Covered | ASML Holding N.V., Nikon Corporation, Canon Inc., Veeco Instruments Inc., SUSS MicroTec SE, EV Group, SCREEN Holdings Co., Ltd., Carl Zeiss SMT GmbH, JEOL Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithography Equipment Market Strategic Shifts & Innovations
The market is advancing on two fronts: relentless innovation at the leading edge with next-generation EUV, and the strategic optimization of mature DUV technology for a diverse and expanding range of applications in automotive and industrial electronics.
High-NA (Numerical Aperture) EUV lithography represents the next frontier in semiconductor patterning. This technology is designed to project circuit features with even greater precision than current EUV systems. Leading-edge logic and memory manufacturers are planning initial deployments to support their roadmaps. Ultimately, this technology is miniaturizing transistor structures to the sub-2-nanometer scale, enabling unprecedented device density and performance.
The Wassenaar Arrangement, a multilateral export control regime, provides the framework for national regulations governing advanced technology transfer. Unilateral controls from the United States and the Netherlands specifically restrict the sale of EUV and advanced DUV immersion systems to certain destinations based on national security assessments. Consequently, semiconductor manufacturers in affected regions face significant hurdles in accessing leading-edge fabrication capabilities, influencing global supply chain strategies.
A bifurcation in foundry purchasing models is becoming more pronounced. This separates procurement strategies for cutting-edge EUV systems from those for mature-node DUV and i-line tools. This dynamic creates two distinct markets: one driven by performance at any cost for AI and HPC, and another driven by cost-effectiveness and reliability for automotive, power management, and IoT chips. This demand-side split is most evident in China and Europe, where significant investment is flowing into new fabs dedicated to these specialized, non-leading-edge technologies.
Lithography Equipment Market Segmentation
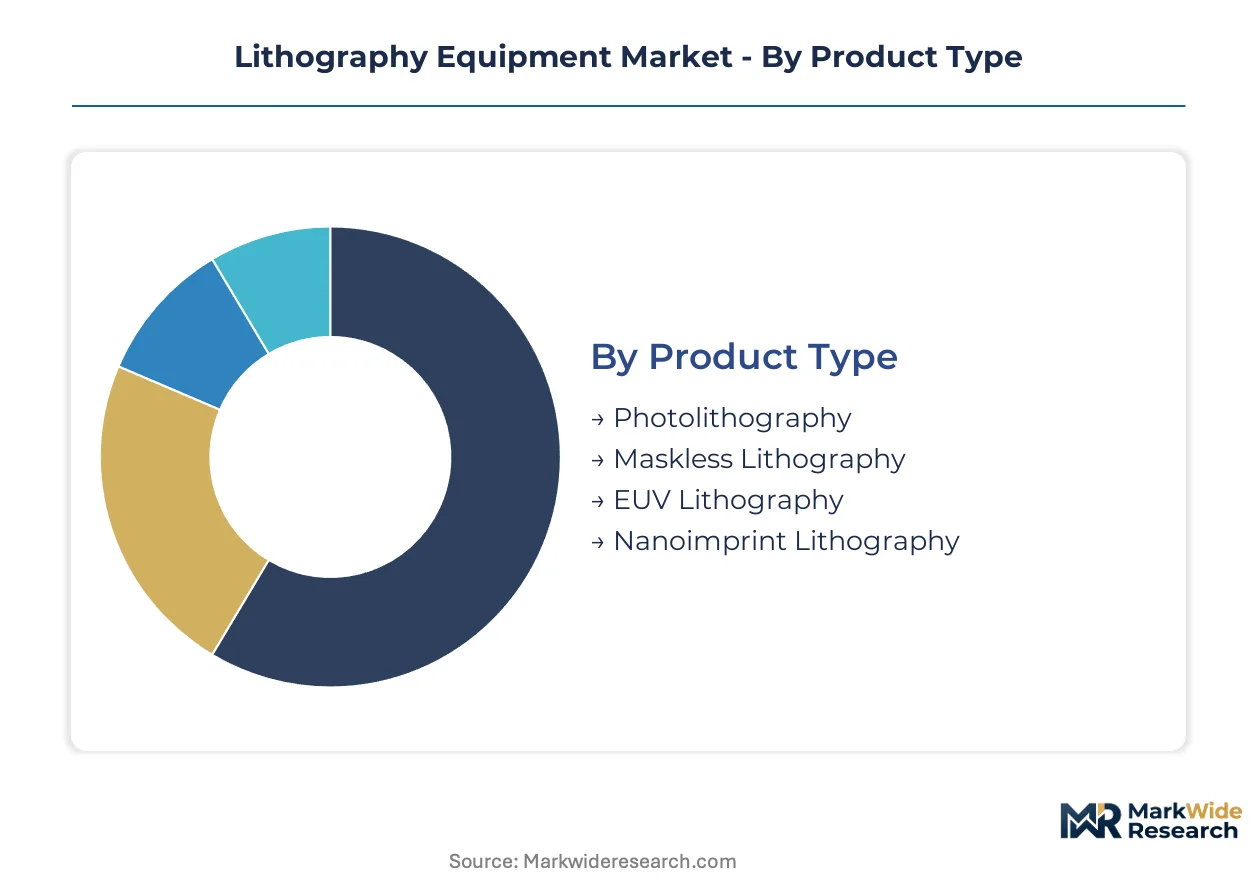
Understanding the lithography equipment market through segmentation reveals critical demand patterns and technological concentrations. This detailed breakdown highlights where investment capital flows and which technologies are indispensable for various microfabrication needs. Analyzing these segments provides a clear picture of the market's underlying structure and competitive dynamics.
Product Type:
Margin pools within the product type category are heavily concentrated in advanced patterning solutions, reflecting the high value of precision manufacturing.
- EUV Lithography:This cutting-edge technique utilizes extreme ultraviolet light to create features below 7 nanometers, enabling the most advanced integrated circuits. Demand concentrates in Taiwanese and South Korean foundries producing chips for artificial intelligence and high-performance computing.
- Photolithography:This foundational process projects patterns onto a resist using various light sources, forming the basis for microfabrication across multiple nodes. Manufacturers of mature-node semiconductors for automotive and IoT devices drive consistent demand globally.
- Maskless Lithography:This method uses direct-write electron or laser beams to pattern wafers without a physical mask, offering flexibility for prototyping and low-volume production.
- Nanoimprint Lithography:This technique physically deforms a resist material using a mold, finding niche applications in photonics and memory devices for cost-effective patterning.
Photolithography holds installed capacity. EUV Lithography is rotating up the share rankings.
Technology:
The application focus across technology types distinguishes between leading-edge performance and broad-market utility for device manufacturing.
- Extreme Ultraviolet:This technology employs 13.5 nm wavelength light, essential for patterning critical layers in sub-7 nanometer semiconductor devices. Leading foundries in South Korea and Taiwan require EUV for next-generation processors and memory.
- Deep Ultraviolet:DUV systems use wavelengths like 248 nm (KrF) or 193 nm (ArF) for patterning features down to 28 nanometers, serving as the workhorse for mainstream integrated circuits. Automotive and industrial electronics sectors in Europe and North America drive DUV demand.
- Near Ultraviolet:NUV lithography utilizes wavelengths around 365-436 nm, commonly employed for less critical layers or microelectromechanical systems.
- Electron Beam:E-beam lithography uses a focused electron beam for direct writing, providing ultra-high resolution for photomask fabrication and specialized research.
The Deep Ultraviolet segment dominates volume, while Extreme Ultraviolet drives technological advancement.
End User:
Volume concentration among end users clearly favors large-scale semiconductor fabrication operations globally.
- Semiconductor Manufacturers:These entities operate foundries and integrated device manufacturers to produce a vast array of chips, requiring a full spectrum of lithography tools. Global demand from major players like TSMC and Samsung underpins the market's growth.
- Display Manufacturers:These companies produce flat panel displays for televisions, smartphones, and other devices, utilizing lithography for patterning display circuitry. Asian manufacturers, particularly in China and South Korea, represent significant demand.
- Research Institutes:Academic and government-funded research bodies use lithography equipment for materials science, nanotechnology, and experimental device fabrication.
- Academic Institutions:Universities and technical colleges utilize lithography systems for educational purposes and fundamental research into micro- and nanofabrication.
Investment in Semiconductor Manufacturers is expanding rapidly, while Academic Institutions maintain a steady demand profile.
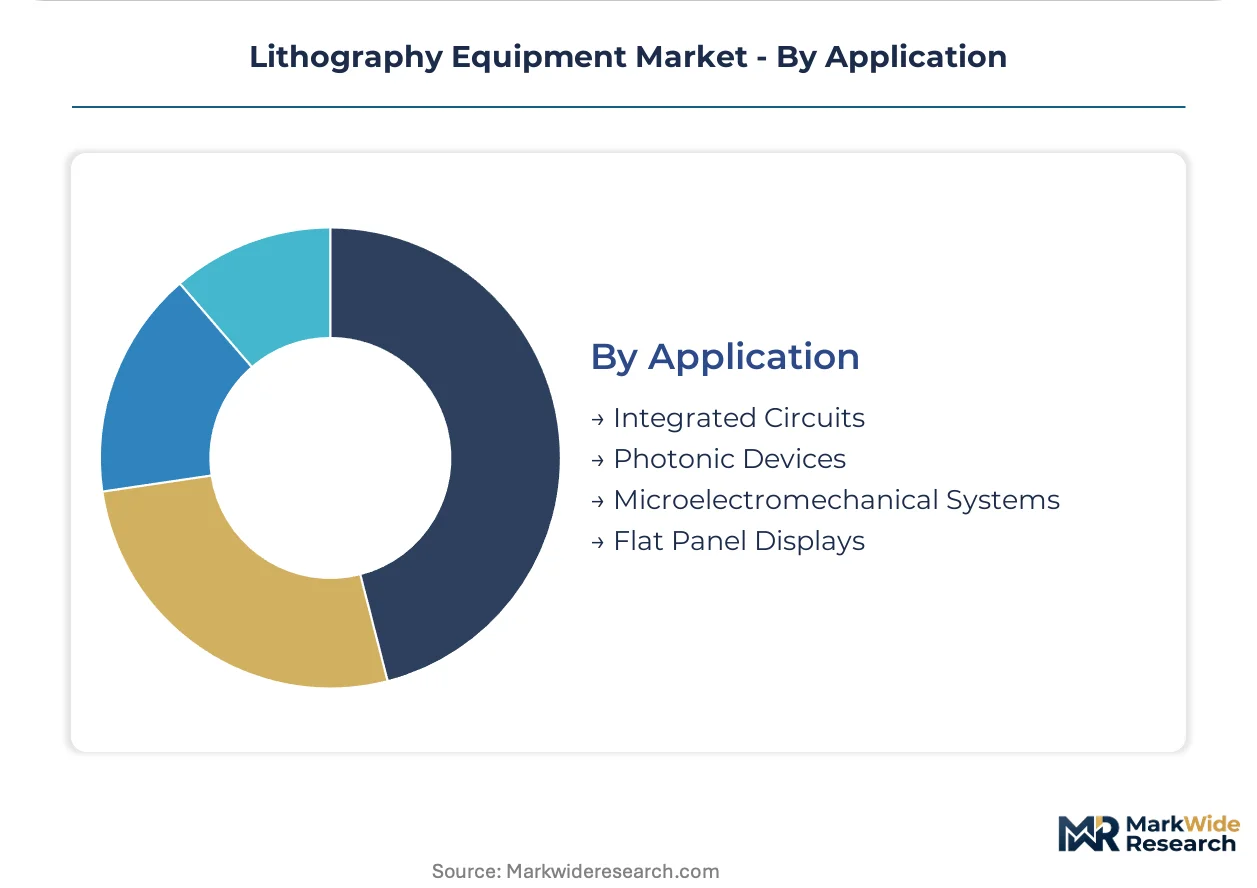
Application:
The maturity level of applications dictates the specific lithography requirements, from cutting-edge to established processes.
- Integrated Circuits:This application involves the fabrication of microprocessors, memory chips, and other complex electronic components, primarily driving demand for advanced EUV and DUV systems. Artificial intelligence and high-performance computing necessitate increasingly dense integrated circuits.
- Microelectromechanical Systems:MEMS devices, such as sensors and actuators, require lithography for their intricate three-dimensional structures, often utilizing DUV and NUV systems. Automotive and medical sectors contribute significantly to MEMS demand.
- Photonic Devices:These components manipulate light, including optical sensors and waveguides, and often require high-resolution patterning for their precise structures.
- Flat Panel Displays:Lithography is fundamental to creating the pixel arrays and thin-film transistor layers in LCD and OLED panels.
The Integrated Circuits segment commands the largest market share, with Photonic Devices showing significant potential for future growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The interplay between technology export controls and domestic manufacturing initiatives significantly shapes regional lithography equipment demand. Governments worldwide balance national security with the need for advanced semiconductor capabilities. This dynamic creates distinct purchasing patterns and strategic priorities across key geographical markets.
United States
Demand for leading-edge lithography tools in the United States stems from advanced computing and defense applications. The US CHIPS Act incentivizes domestic fabrication, stimulating new fab construction. Arizona and New York are emerging as critical hubs for semiconductor manufacturing investment.
Netherlands
The Netherlands plays a unique role due to ASML's dominance in EUV technology. Dutch export controls, often aligned with US policy, restrict advanced lithography sales to certain regions. Eindhoven's Brainport region serves as a global center for lithography equipment innovation and production.
Taiwan
Foundries in Taiwan maintain robust demand for the most advanced EUV systems to support global chip production. The country's strong semiconductor industry benefits from government support for R&D and infrastructure. Hsinchu Science Park remains the epicenter for integrated circuit manufacturing and advanced patterning.
South Korea
South Korean semiconductor manufacturers are primary consumers of cutting-edge EUV lithography for memory and logic chips. The Ministry of Trade, Industry and Energy supports the national semiconductor strategy to secure technological leadership. Gyeonggi Province hosts major fabrication facilities driving demand for high-volume production tools.
Germany
German industrial electronics and automotive sectors drive sustained demand for DUV and i-line lithography equipment. European initiatives like the EU Chips Act aim to bolster regional semiconductor production capabilities. Dresden and Munich are key centers for microelectronics research and manufacturing, requiring diverse lithography solutions.
Lithography Equipment Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of lithography technology, from leading-edge EUV to mature DUV systems. The market structure exhibits high concentration at the extreme ultraviolet segment, where few players command significant technological expertise. In contrast, deep ultraviolet and i-line sectors show broader vendor participation, serving diverse industrial needs. Strategic archetypes include integrated system providers, critical optical component specialists, and niche application toolmakers. Companies primarily focus on technology innovation and strategic partnerships to maintain competitive advantage and secure supply chains.
Dominant system providers like ASML Holding N.V. exemplify the concentrated power in high-value EUV lithography, representing the pinnacle of precision manufacturing for sub-7 nanometer nodes. Nikon Corporation and Canon Inc. occupy strong positions in the established deep ultraviolet and i-line markets, catering to a broad base of integrated circuit and MEMS manufacturers. Carl Zeiss SMT GmbH anchors the supply chain as a critical optical component specialist, underscoring the intricate interdependencies within the industry and enabling advanced patterning solutions.
| Leading Market Players |
|---|
| ASML Holding N.V. |
| Nikon Corporation |
| Canon Inc. |
| Veeco Instruments Inc. |
| SUSS MicroTec SE |
| EV Group |
| SCREEN Holdings Co., Ltd. |
| Carl Zeiss SMT GmbH |
| JEOL Ltd. |
| Others |
Cost & Logistics Intelligence
Scale economies in EUV system manufacturing create high barriers to entry, concentrating production among a few vendors. This concentration directly influences pricing power and establishes high price floors for leading-edge lithography equipment.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for lithography equipment. Price differentiation stems from customization levels for specific process nodes and bundled after-sales service agreements, reflecting the technology's complexity. Pricing softness for mature DUV systems reflects increased competition among a broader vendor base and the commoditization of older nodes. Foundries in emerging regions exhibit greater price sensitivity for established technologies, while leading-edge semiconductor manufacturers prioritize performance at any cost.
Supply Chain Analysis
Long lead times for specialized optical components characterize the lithography equipment supply chain, impacting delivery schedules for advanced systems. Supply concentration centers in the Netherlands, Japan, and Germany for critical subsystems, including light sources and precision optics. The industry sources from a limited number of suppliers for high-NA mirrors and extreme ultraviolet light sources, creating single-source vulnerability. Distribution runs through direct sales channels to major semiconductor foundries and research institutions globally, ensuring specialized support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithography market exhibits a platform-economics inflection, driven by the tight interoperability required between EUV systems and advanced metrology tools. This ecosystem dependency shapes strategic opportunities across the semiconductor fabrication landscape.
For Market Incumbents: Secure long-term supply agreements for critical optical components to mitigate optical component bottlenecks. Invest heavily in R&D for High-NA EUV technology to counter potential competitive threats from alternative lithography techniques. Expand specialized talent development programs to address talent scarcity, ensuring the continuous innovation and maintenance of advanced systems. This proactive approach defends market share against emerging patterning solutions.
For New Entrants and Emerging Players: Certification fast-tracks for niche applications like photonics or memory devices offer a pathway into the market. Target the mature-node DUV and i-line segments in regions with national semiconductor initiatives, such as Europe. Specialize in providing complementary patterning solutions like Directed Self-Assembly to enhance existing DUV or EUV systems. A go-to-market angle focused on cost-effective, specialized tools for non-leading-edge applications provides differentiation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized optical component manufacturers and advanced metrology system providers. Long-term viability over the next decade favors companies with proprietary technology in critical sub-systems for EUV. Acquire firms offering Directed Self-Assembly or nanoimprint lithography for diversification beyond mainstream CMOS. Watch for increased government funding for domestic semiconductor supply chains as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV R&D Acceleration | This initiative pushes patterning capabilities beyond current EUV systems, enabling sub-2nm transistor structures for leading-edge logic. |
| Talent Development Programs | Addressing the critical shortage of optical engineers and service technicians sustains the long-term growth of the lithography industry. |
| Partnerships in Metrology | Integrating advanced metrology systems ensures precise pattern overlay and critical dimension uniformity for complex integrated circuits. |
| Localized Manufacturing Investments | National semiconductor initiatives like the US CHIPS Act stimulate new fab construction and regional demand for lithography tools. |
| Nanoimprint Lithography Commercialization | This technology offers cost-effective patterning solutions for niche applications such as photonics and memory devices. |
Research Approach
Initial hypotheses were tested against primary input from lithography equipment engineers, foundry procurement leads, and optical component R&D directors, then refined through iterative analysis. This involved combining insights from direct interviews with secondary validation from SEMI industry reports, government technology assessments, and corporate financial disclosures. Bottom-up market sizing was triangulated with top-down macroeconomic indicators to ensure comprehensive data coverage.
Variance decomposition identified key drivers impacting market growth across the analysis window. Segmentation dimensions modeled included product type, technology, end user, application, and regional manufacturing capacity. Compound annual growth rates were derived from historical trends and projected adoption rates of next-generation EUV systems. Foundry capital expenditure plans and national semiconductor initiatives served as critical forecast inputs.
The analysis sits within stated boundaries; outcomes outside major shifts in export control policies or unforeseen technological breakthroughs would require recalibration. Forecasts reflect documented assumptions regarding semiconductor demand and manufacturing investment. Geopolitical instability and sudden supply chain disruptions represent key risk factors that could revise these forecasts; outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Global Semiconductor Photolithography Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Electron Beam Lithography Machine Market