
 Photolithography Equipment Market | 2026-2036
Photolithography Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Photolithography Equipment Market Intelligence
Direct sales channels between toolmakers and foundry operators is reshaping how photolithography equipment reaches end users, bypassing traditional distributor networks that once handled spare parts and service contracts. ASML Holding N.V. dominates extreme ultraviolet system deliveries through captive supply agreements that lock in multi-year order queues. Tokyo Electron Limited leverages its coater/developer platform installed base to sustain aftermarket revenue streams alongside lithography cell integration. Nikon Corporation competes in ArF immersion segments where price-performance thresholds still favor multi-patterning strategies at mature nodes.
Photolithography equipment projects circuit patterns onto photosensitive substrates using controlled light sources, with EUV systems operating at 13.5nm wavelength to print features below 7nm resolution for advanced logic and memory fabrication. Step-and-scan platforms command the dominant share of capital expenditure as foundries prioritize throughput and overlay precision in high-volume manufacturing. EUV technology represents the fastest-expanding category as chipmakers transition from DUV multi-patterning to single-expose processes, though DUV systems retain substantial installed base for trailing-edge and specialty chip production. Mask aligners serve research institutions and compound semiconductor labs where flexibility outweighs absolute resolution requirements.
The U.S. Department of Commerce export controls under the CHIPS Act restrict EUV and advanced DUV tool shipments to Chinese fabs, redirecting equipment flows toward Malaysia, Vietnam, and U.S. greenfield sites. The EU F-Gas Regulation pressures toolmakers to phase down fluorinated compounds used in laser light source cooling and chamber chemistry, accelerating alternative refrigerant and dry vacuum pump development. Japan's METI coordinates domestic lithography component supply security through designated critical technology partnerships. Stakeholders must monitor how divergent national subsidy regimes and technology access tiers fragment the addressable customer base for each equipment generation.
Market Dynamics
The transition from deep ultraviolet multi-patterning to single-expose extreme ultraviolet lithography is compressing tool replacement cycles and concentrating capital deployment among foundries capable of sub-7nm production.
Growth Catalysts
- CHIPS Act reshoring incentives:U.S. fabs in Arizona and Texas are accelerating EUV procurement timelines to capture federal tax credits and facility construction grants.
- Logic node migration:Advanced foundry operators are retiring 193nm immersion systems for 13.5nm wavelength platforms capable of printing sub-7nm transistor gates.
- Hsinchu cluster density:Taiwan's science park ecosystem generates concentrated demand for lithography cell integration services and coater/developer upgrades.
Market Restraints
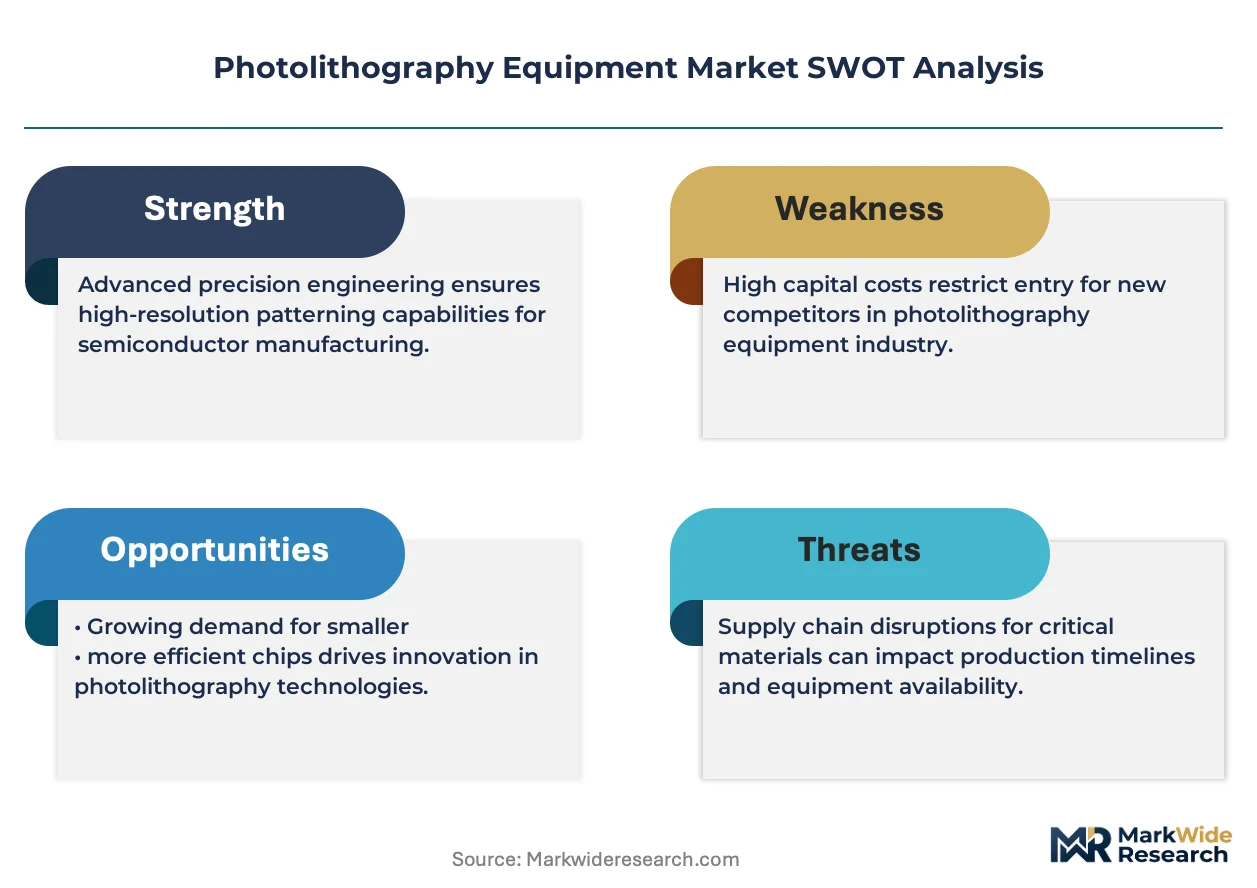
- Optical component supply concentration:German and Dutch precision optics suppliers face capacity constraints on aspheric mirror production for EUV projection systems.
- F-Gas phase-down requirements:The EU F-Gas Regulation mandates refrigerant transitions that extend laser light source qualification timelines by 18-24 months.
- Mask blank scarcity:Defect-free multilayer reflector substrates for EUV reticles remain bottlenecked at two qualified suppliers.
Strategic Opportunities
- Malaysia backend integration:Penang and Kulim industrial zones are attracting lithography module assembly investments as Chinese fab access tightens.
- High-NA EUV commercialization:0.55 numerical aperture systems enable single-expose patterning at 2nm nodes for memory and logic applications.
- Direct service contracting:Toolmakers are bypassing regional distributors to capture lifecycle revenue through captive maintenance and upgrade subscriptions.
Industry Challenges
- EUV source engineer scarcity:Laser-produced plasma system specialists command premium compensation as foundries compete for qualified installation and field service teams.
- Legacy DUV fab retooling:Trailing-edge operators face capital allocation conflicts between extending 193nm immersion throughput and migrating to advanced packaging lithography.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photolithography Equipment Market |
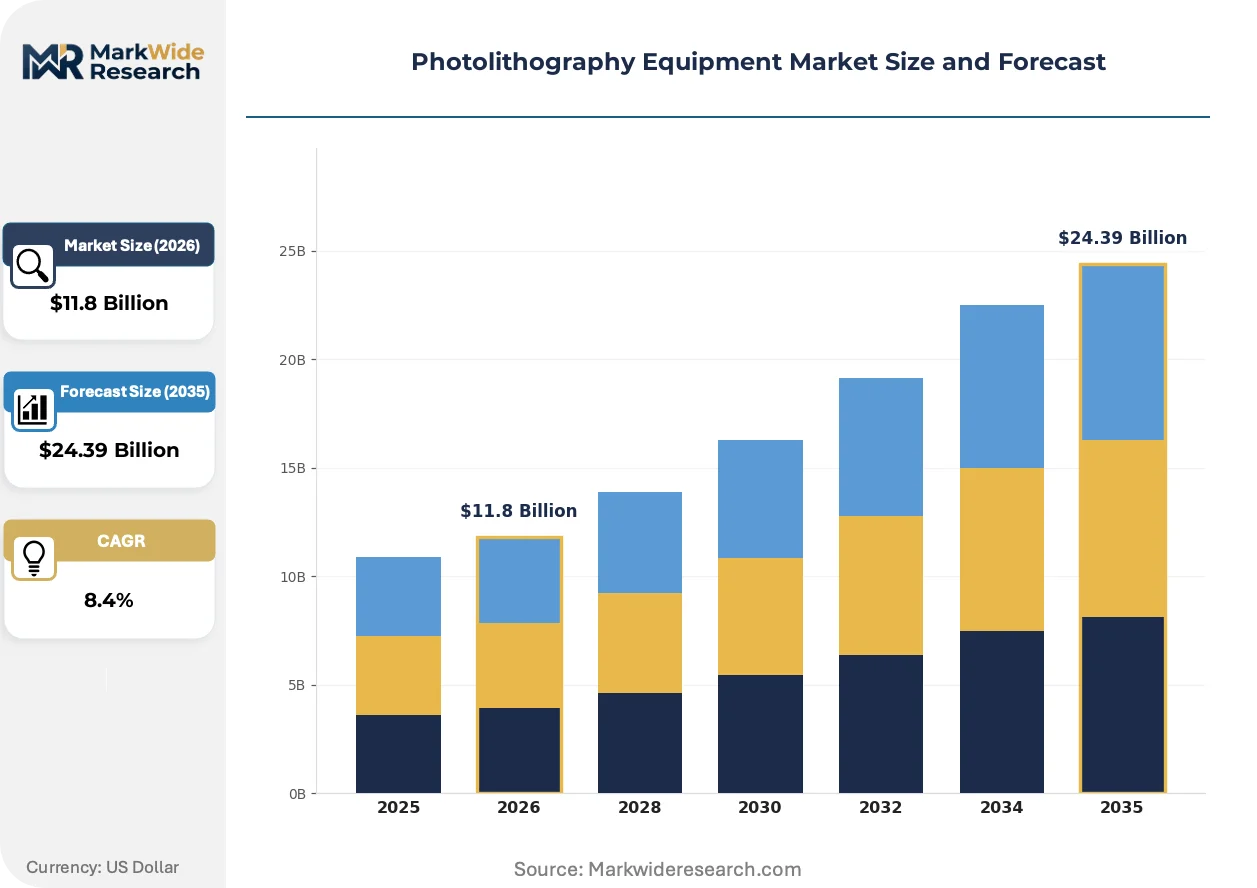
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mask Aligners, Step-and-Repeat, Step-and-Scan, Exposure Systems Technology: PAT, EUV, DUV, Optical Lithography Application: Semiconductor Production, IC Fabrication, Flat Panel Display, Microelectronics End User: Foundries, Outsourced Semiconductor Assembly and Test, Integrated Device Manufacturers, Research Institutions |
| Companies Covered | Applied Materials, Inc., KLA Corporation, ASML Holding N.V., EV Group, Tokyo Electron Limited, Nikon Corporation, Veeco Instruments Inc., SUSS MicroTec SE, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photolithography Equipment Market Strategic Shifts & Innovations
Computational lithography and machine learning overlay correction are merging with hardware platforms to squeeze resolution limits without wavelength reduction. These converging capabilities are redefining competitive differentiation beyond raw optical specifications.
High-NA EUV architecture is collapsing the economic viability of self-aligned quadruple patterning at 3nm nodes. Samsung and Intel are qualifying 0.55NA systems for 2026 production ramps, compressing the process window advantage that TSMC built through DUV multi-patterning mastery. The technology is collapsing capital efficiency thresholds for second-tier foundries attempting node parity.
The EU F-Gas Regulation is forcing refrigerant transitions in laser cooling subsystems and vacuum pump seal technologies. Toolmakers are redesigning thermal management architectures to accommodate hydrofluoroolefin alternatives with lower global warming potential. Japanese and Korean fabs face accelerated compliance deadlines that compress qualification schedules for next-generation light source platforms.
Foundry procurement teams are consolidating lithography cell purchases into single-source platform agreements rather than best-of-breed component sourcing. This behavior concentrates negotiating leverage with integrated coater/developer/stepper suppliers and marginalizes standalone mask aligner vendors. The shift is most pronounced in Taiwan's Hsinchu corridor, where TSMC's supplier consolidation ripples through allied packaging and test houses.
Photolithography Equipment Market Segmentation
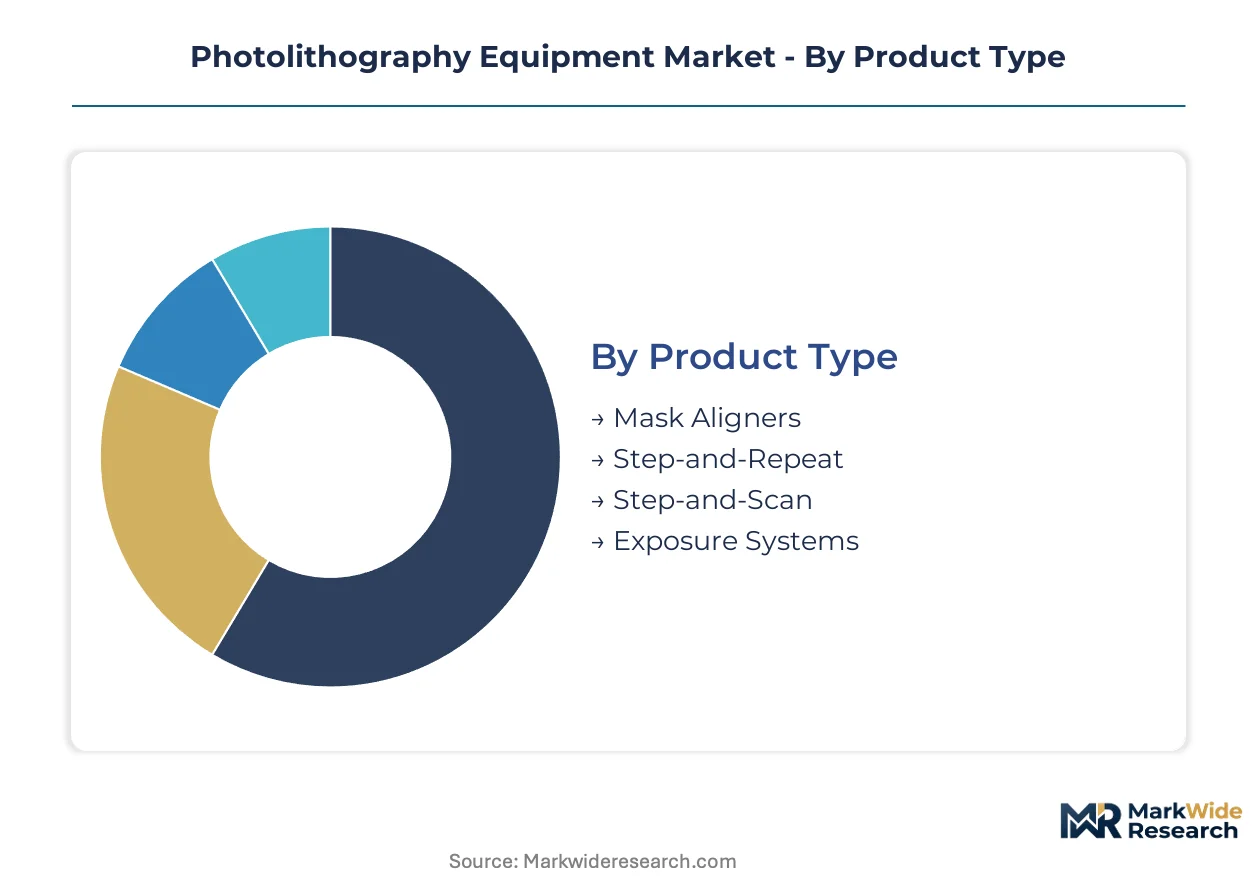
Segmentation in photolithography equipment reveals how capital deployment cycles, technology roadmaps, and customer procurement power concentrate revenue across distinct equipment categories. Foundry procurement teams prioritize throughput and overlay precision metrics that favor specific platform architectures over others.
Product Type:
Replacement velocity varies dramatically across platform architectures, with high-throughput systems turning over every 3-4 years while specialty aligners operate on decade-long depreciation schedules.
- Step-and-Scan:Wafer-stage scanning synchronized with reticle movement enables sub-nanometer overlay accuracy at production throughputs exceeding 200 wafers per hour. Taiwan's Hsinchu Science Park cluster accounts for the densest installed base globally as TSMC and allied suppliers anchor multi-billion-dollar procurement cycles.
- Step-and-Repeat:Field-by-field exposure architecture dominates trailing-edge logic and memory fabs where die-size economics still favor mature-node production. Malaysian backend facilities in Penang and Kulim are absorbing retired systems from Korean and Taiwanese foundries upgrading to EUV platforms.
- Mask Aligners:Contact and proximity exposure systems serve compound semiconductor labs and research institutions where pattern flexibility outweighs absolute resolution requirements.
- Exposure Systems:Broad-category platforms encompass both projection and direct-write architectures for photomask fabrication and advanced packaging applications.
Step-and-Scan platforms anchor the volume base while Step-and-Repeat systems gain share at the steepest rate in Southeast Asian expansion zones.
Technology:
Capital intensity stratifies sharply across wavelength generations, with single-tool price tags spanning from sub-million-dollar optical systems to EUV platforms requiring multi-billion-dollar fab infrastructure.
- EUV:13.5nm wavelength laser-produced plasma sources enable single-expose patterning of sub-7nm transistor features. U.S. CHIPS Act reshoring incentives are accelerating procurement timelines for Arizona and Texas greenfield fabs seeking federal tax credits.
- DUV:193nm ArF immersion systems retain substantial installed base for trailing-edge logic, DRAM, and NAND production where multi-patterning economics remain viable. Japanese and Korean memory houses are extending DUV utilization through advanced self-aligned patterning techniques.
- Optical Lithography:I-line and G-line mercury vapor sources serve MEMS, power semiconductor, and analog chip fabrication where feature sizes exceed 90nm.
- PAT:Process analytical technology platforms integrate metrology and control systems for real-time lithography cell optimization.
DUV technology anchors the volume base while EUV platforms gain share at the steepest rate as foundries retire multi-patterning strategies.
Application:
Fab utilization rates and capital allocation priorities diverge across end-use applications, with logic foundries running at 90%+ capacity while display panel makers cycle through boom-bust investment waves.
- Semiconductor Production:Logic and memory wafer fabrication commands the dominant capital expenditure share. Taiwan and South Korean foundries are concentrating EUV procurement for sub-5nm node ramps.
- IC Fabrication:Discrete and analog integrated circuit production leverages mature-node equipment with extended depreciation horizons. European automotive chip suppliers are expanding 28nm and 40nm capacity under EU Chips Act subsidies.
- Flat Panel Display:Large-area lithography for OLED and LCD backplanes requires specialized stepper architectures with extended field sizes. Chinese panel makers are absorbing display lithography capacity as Korean manufacturers pivot to semiconductor-focused investments.
- Microelectronics:Sensors, RF components, and photonic devices utilize proximity aligners and projection scanners tailored to non-silicon substrates.
Semiconductor Production anchors the volume base while IC Fabrication gains share at the steepest rate in European and U.S. reshoring corridors.
End User:
Procurement scale and technical specification authority concentrate differently across customer types, with integrated device manufacturers wielding captive engineering resources that foundries outsource to equipment vendors.
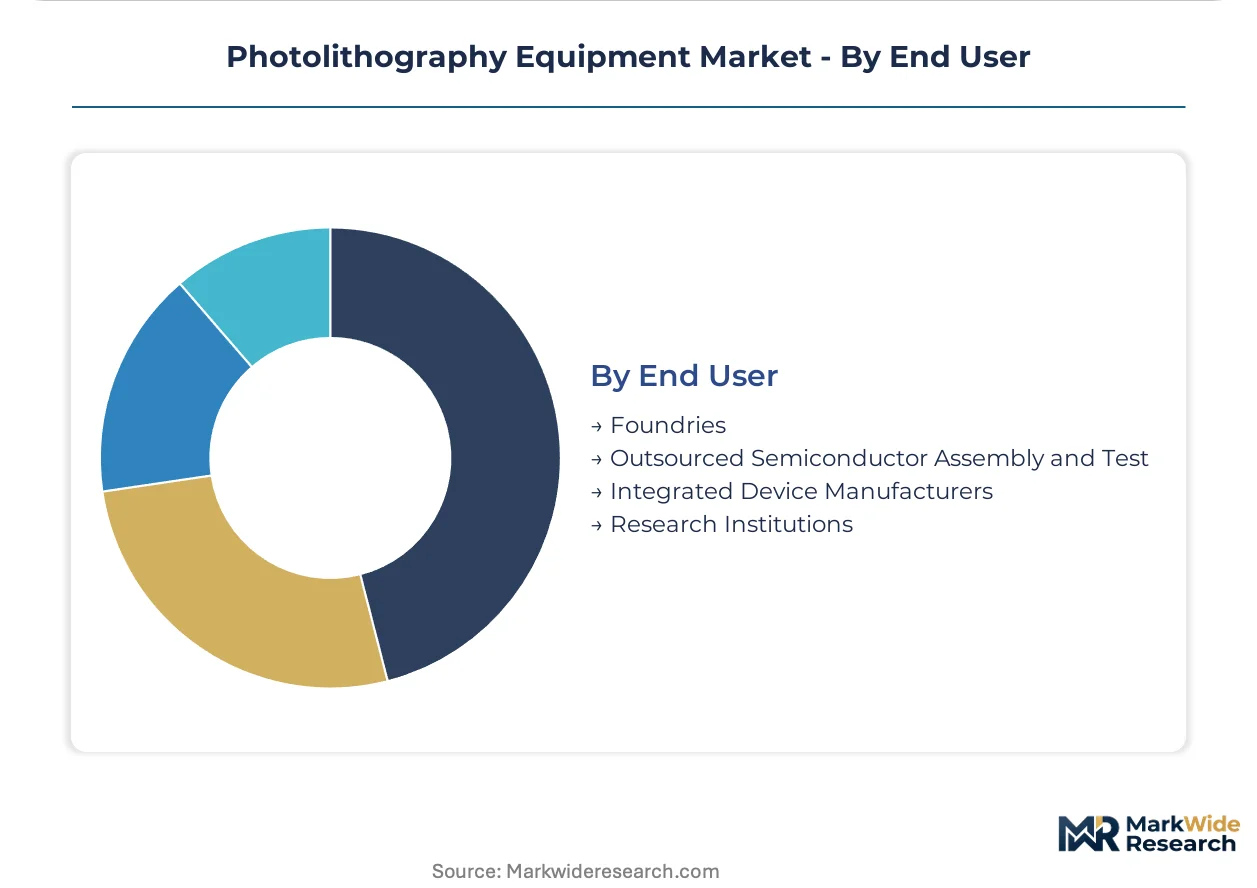
- Foundries:Pure-play wafer fabrication operators command the largest lithography tool procurement volumes through multi-year capacity expansion cycles. TSMC's supplier consolidation strategy in Taiwan's Hsinchu corridor ripples through allied packaging and test houses.
- Integrated Device Manufacturers:Captive fab operators at Intel, Samsung, and Texas Instruments maintain in-house process development teams that co-design equipment specifications with toolmakers. IDMs are leveraging CHIPS Act grants to accelerate EUV adoption timelines.
- Outsourced Semiconductor Assembly and Test:OSAT providers are expanding advanced packaging lithography capacity for chiplet integration and 3D stacking applications. Malaysian and Vietnamese backend facilities are attracting lithography module assembly investments.
- Research Institutions:University cleanrooms and national laboratories operate lower-throughput systems where experimental flexibility outweighs manufacturing economics. EU and U.S. research consortia are qualifying high-NA EUV prototypes through public-private partnerships.
Foundries anchor the volume base while OSAT providers gain share at the steepest rate in Southeast Asian backend integration zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates sharply between Taiwan's Hsinchu corridor and U.S. greenfield sites, where CHIPS Act subsidies compress procurement timelines against Taiwanese cluster density advantages. Equipment flows redirect from Chinese fabs toward Malaysia, Vietnam, and Arizona under tightening export control regimes.
United States
Arizona and Texas fabs accelerate EUV procurement to capture CHIPS Act tax credits and facility construction grants. The Department of Commerce restricts advanced tool shipments to Chinese fabs under export control frameworks. Intel's Oregon and Arizona campuses anchor domestic High-NA EUV qualification timelines for 2026 production ramps.
Taiwan
TSMC's supplier consolidation strategy generates concentrated demand for lithography cell integration services. The National Development Council coordinates science park expansion permits for Hsinchu and Tainan clusters. Hsinchu Science Park maintains the densest EUV tool installation base globally as allied packaging houses follow foundry procurement patterns.
South Korea
Samsung and SK Hynix extend DUV utilization through advanced self-aligned patterning while qualifying High-NA systems. The Ministry of Trade, Industry and Energy designates lithography components as critical technology items under supply security frameworks. Pyeongtaek and Yongin semiconductor complexes concentrate memory and logic fab investments.
Japan
Tokyo Electron and Nikon anchor domestic coater/developer and ArF immersion segments through co-design partnerships with toolmakers. METI coordinates precision optics and laser source component supply security through designated technology partnerships. Kumamoto and Hiroshima prefectures host trailing-edge and power semiconductor fab expansions.
Malaysia
Penang and Kulim industrial zones attract lithography module assembly investments as Chinese fab access tightens. The Malaysian Investment Development Authority grants pioneer status incentives for semiconductor equipment manufacturing. Backend facilities absorb retired DUV systems from Korean and Taiwanese foundries upgrading to EUV platforms.
Photolithography Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in optical, laser, and vacuum subsystems where German and Dutch suppliers face capacity constraints. The vendor base stratifies into three tiers: captive EUV system suppliers with multi-year order backlogs, integrated lithography cell providers leveraging coater/developer installed bases, and standalone aligner vendors marginalized by procurement consolidation. Dominant competitive moves include direct service contracting that bypasses regional distributors and captive supply agreements that lock in multi-year order queues.
Within the integrated platform tier, ASML Holding N.V. and Tokyo Electron Limited exemplify divergent strategies for capturing lifecycle revenue. Nikon Corporation occupies a position in ArF immersion segments where price-performance thresholds favor multi-patterning approaches. Among U.S.-based equipment specialists, Applied Materials, Inc. and KLA Corporation represent archetypes for process control and materials engineering integration adjacent to lithography cells.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| KLA Corporation |
| ASML Holding N.V. |
| EV Group |
| Tokyo Electron Limited |
| Nikon Corporation |
| Veeco Instruments Inc. |
| SUSS MicroTec SE |
| Canon Inc. |
| Others |
Cost & Logistics Intelligence
The Kaohsiung-to-Los Angeles transpacific corridor carries EUV system modules where freight surcharges compound with customs valuation disputes, compressing margins for toolmakers while amplifying price spreads between configured-to-order and standard-platform deliveries. This logistics chokepoint concentrates negotiating leverage with integrated platform suppliers who bundle installation and lifecycle services into single-source contracts.
Pricing Analysis
Configured-to-order EUV systems command substantial premiums over standard-platform DUV configurations, with price differentiation driven by laser source customization levels and after-sales service bundling. Contract-based long-term offtake agreements dominate procurement patterns as foundries lock in multi-year capacity allocations. Cost compression in trailing-edge DUV segments is intensifying because Malaysian backend facilities absorb retired systems at distressed valuations. Memory fabs exhibit highest price sensitivity due to cyclical capital allocation constraints, while logic foundries prioritize throughput metrics over unit economics.
Supply Chain Analysis
U.S. Department of Commerce export controls restrict EUV and advanced DUV tool shipments to designated destinations, fragmenting equipment flows toward Malaysia, Vietnam, and Arizona greenfield sites. German precision optics and Dutch laser source components anchor upstream supply, with mirror substrate fabrication drawing from Zeiss and ASML captive operations. Single-source vulnerability concentrates in aspheric mirror production where qualified suppliers number fewer than three. Distribution runs through direct manufacturer-to-foundry channels that bypass traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through export licensing regimes and multi-year qualification timelines protects incumbent positions against displacement.
For Market Incumbents: Harden supplier consolidation strategies through captive coater/developer platform agreements that raise switching costs for foundry customers. Deepen backward integration into precision optics supply by securing designated critical technology partnerships under Japan's METI frameworks. Threat vectors include emerging Chinese lithography development programs and F-Gas refrigerant transition delays that extend competitor qualification windows. For New Entrants and Emerging Players: Establish a beachhead in mask aligner segments serving compound semiconductor labs and research institutions where flexibility requirements outweigh resolution specifications. White-space targets include advanced packaging lithography for chiplet integration and dry vacuum pump alternatives to fluorinated refrigerant systems. Go-to-market positioning should emphasize modular upgrade paths that extend deprecated DUV system lifecycles in Southeast Asian backend zones. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with captive supply relationships in laser-produced plasma sources and aspheric projection optics. Long-term viability over the next decade hinges on High-NA EUV commercialization timelines and reshoring subsidy durability. Acquisition targets should display process analytical technology integration capabilities. The signal to monitor is foundry capital expenditure guidance revisions following CHIPS Act disbursement schedules.| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV Platform Qualification | Intel's Oregon and Arizona campuses anchor domestic 0.55NA system validation for logic and memory production ramps. |
| Direct Service Contracting Expansion | ASML and Tokyo Electron bypass regional distributors to capture lifecycle revenue through captive maintenance subscriptions. |
| Malaysia Backend Integration | Penang and Kulim industrial zones attract lithography module assembly investments as Chinese fab access tightens. |
| F-Gas Alternative Development | Toolmakers redesign thermal management architectures to accommodate hydrofluoroolefin refrigerants under EU regulatory deadlines. |
| Computational Lithography Integration | Machine learning overlay correction merges with hardware platforms to squeeze resolution limits without wavelength reduction. |
Research Approach
Initial hypotheses were tested against primary input from fab procurement directors, EUV source engineers, coater/developer platform specialists, and precision optics manufacturing leads and refined through secondary validation against SEC equipment supplier filings, SEMI capital expenditure databases, EU F-Gas Regulation compliance disclosures, and CHIPS Act grant award announcements. Bottom-up demand modeling from foundry expansion schedules was cross-checked against top-down market sizing from tool shipment tracking.
Demand-supply balance analytics across the analysis window integrated wafer capacity buildouts, node migration timelines, and equipment replacement velocity into segmentation models spanning wavelength generation, platform architecture, application category, and end-user procurement archetype. CAGRs were derived from equipment shipment trajectories and fab capital intensity ratios, with inputs including laser source qualification schedules and mask blank defectivity improvement curves.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, reshoring subsidy continuity, or export control enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding High-NA EUV adoption rates and trailing-edge DUV utilization extensions. Material shifts in Chinese domestic lithography development progress or EU refrigerant phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Laser Annealing System Market