
 Africa Extreme Ultraviolet Lithography (EUVL) Systems Market | 2026-2036
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market Analytics
Extreme ultraviolet source technology is fragmenting across multiple wavelength architectures and power scaling approaches, complicating how lithography systems integrate into African fab environments. ASML Holding N.V. dominates the scanner supply chain through its monopoly on EUV light source partnerships. ZEISS Group leverages its mirror and optical subsystem expertise to sustain positioning in the high-NA transition. Applied Materials Inc. competes in the adjacent process equipment layer that feeds into EUV-enabled workflows.
Africa Extreme Ultraviolet Lithography (EUVL) Systems deploy 13.5 nm wavelength light generated by laser-produced plasma to pattern semiconductor wafers at sub-7 nm resolution, requiring vacuum chambers and reflective optics due to EUV absorption by air and conventional lenses. The equipment serves semiconductor manufacturers and foundries seeking to fabricate advanced logic and memory devices. Low-NA EUV technology currently anchors installed base economics in early African adopters, while high-NA EUV represents the fastest-growing technology dimension as foundries plan node transitions. Source equipment captures concentrated margin pools due to its technical complexity and limited supplier base, whereas simulation software segments expand through research institution demand for process modeling capabilities.
South Africa's National Regulator for Compulsory Specifications enforces equipment safety and electromagnetic compatibility standards that shape EUV system import and installation protocols. The African Union's Single African Air Transport Market and broader digital economy frameworks influence cross-border technology transfer rules affecting lithography equipment deployment timelines. Stakeholders must monitor how local content requirements and skills development mandates interact with the specialized technician dependencies inherent to EUV system operations.
Market Dynamics
The transition from low-NA to high-NA EUV architecture is compressing equipment replacement cycles across African semiconductor fabrication facilities, forcing capital deployment decisions ahead of revenue maturation from prior node investments.
Growth Catalysts
- South Africa's Western Cape semiconductor cluster:Foundry investments from domestic and European capital partners are creating concentrated demand for advanced lithography equipment.
- African Union digital transformation frameworks:Technology transfer mandates embedded in continental digital economy policies are accelerating EUV system import approvals and skills development programs.
- Laser-produced plasma source advancement:Power scaling improvements in 13.5 nm wavelength generation are reducing cost-per-wafer economics for sub-7 nm production.
Market Restraints
- Single-source dependency for EUV scanners:ASML's monopoly on commercial EUV lithography systems creates supply concentration risk with no qualified alternative suppliers.
- Zeiss mirror subsystem bottleneck:Reflective optics manufacturing capacity constraints limit scanner production rates regardless of downstream demand signals.
- Import tariff structures:South African Revenue Service classification of lithography equipment under capital goods categories imposes duty burdens that inflate total cost of ownership.
Strategic Opportunities
- Nigeria's emerging fab corridor:Greenfield semiconductor manufacturing investments in Lagos and Abuja represent first-mover positioning for equipment suppliers before competitor saturation.
- Research institution partnerships:Collaborative programs between African universities and European equipment vendors create captive demand for EUV process simulation software.
- High-NA EUV transition window:Foundries planning node migrations present upgrade revenue potential distinct from new installation economics.
Industry Challenges
- Vacuum technician scarcity:EUV system maintenance requires specialized expertise in ultra-high vacuum chamber operations that African technical training institutions have not yet scaled.
- Electromagnetic compatibility certification:South Africa's National Regulator for Compulsory Specifications imposes testing timelines that extend equipment commissioning by months.
- Legacy DUV integration complexity:Hybrid fab environments running 193 nm immersion lithography alongside EUV create workflow orchestration challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Extreme Ultraviolet Lithography (EUVL) Systems Market |
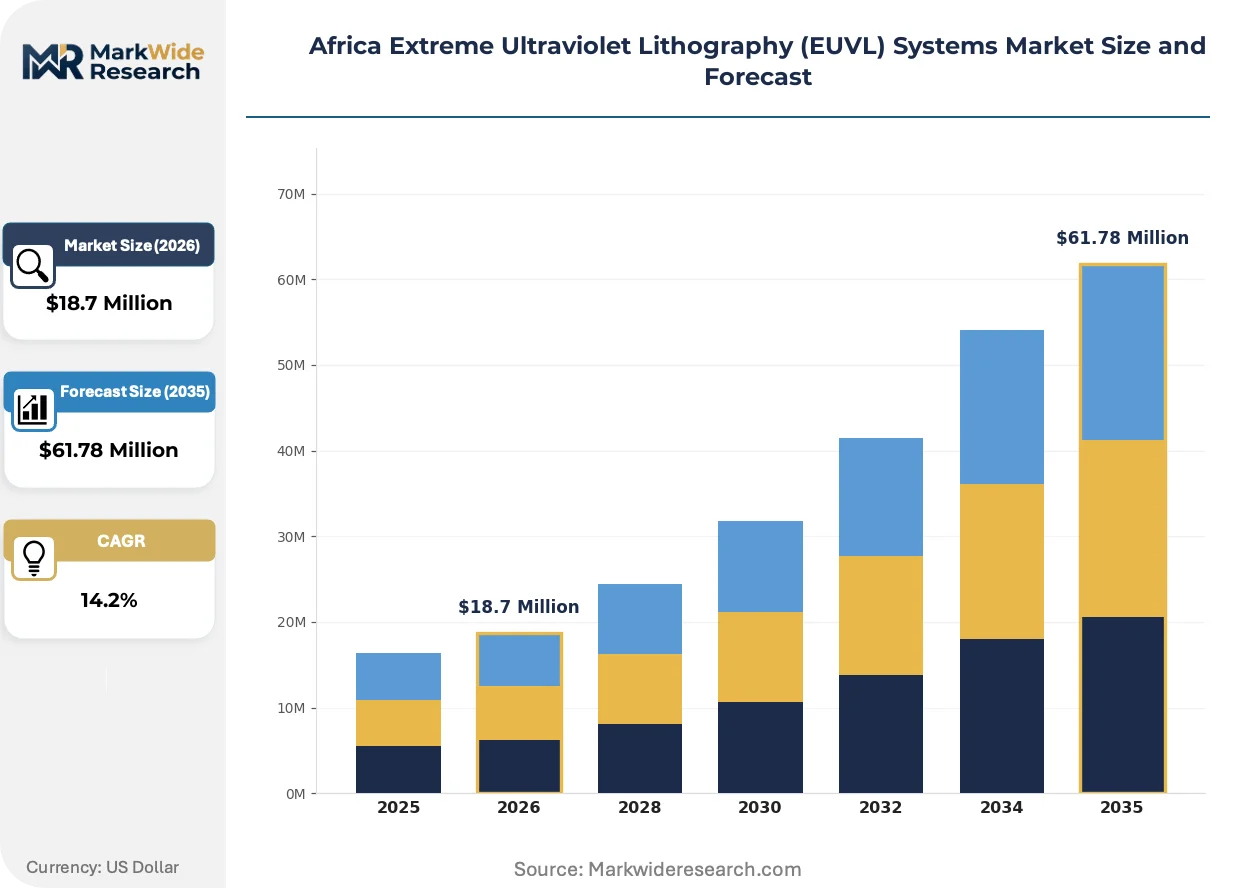
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mask/Etch Equipment, Source, Wafer Handling, Simulation Software End User: Semiconductor Manufacturers, Research Institutions, Foundries, IC Developers Application: Microchips, Sensors, Photonics, Nanotechnology Technology: High-NA EUV, Low-NA EUV, Extreme Ultraviolet Masking, Advanced Imaging |
| Companies Covered | ZEISS Group, Toppan Holdings Inc., ASML Holding N.V., KLA Corporation, Applied Materials Inc., Nikon Corporation, Ushio Inc., Lasertec Corporation, Canon Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market Evolving Landscape
Computational lithography and machine learning are converging with hardware advances to redefine process control economics. These developments are compressing development timelines and redistributing value capture across the equipment stack.
High-NA EUV technology is collapsing the resolution limits that previously constrained single-patterning approaches for advanced logic nodes. South African foundries planning 2 nm-class production are prioritizing high-NA scanner reservations over low-NA capacity expansion. The technology is collapsing the economic viability of multi-patterning techniques that dominated the 7 nm to 3 nm transition, redirecting capital toward source power and mirror subsystem investments.
South Africa's National Regulator for Compulsory Specifications has tightened electromagnetic compatibility testing protocols for imported semiconductor equipment. The regulations now mandate local certification laboratory engagement for EUV system approvals, extending deployment timelines. Foundry operators are responding by pre-qualifying equipment configurations during procurement negotiations to compress post-delivery validation periods.
Buyer concentration among African foundry operators is consolidating procurement leverage and reshaping vendor relationship terms. Large-scale purchasers are unbundling service contracts from equipment sales, creating separate competitive arenas for maintenance and upgrade services. This pattern is most visible in South Africa's Western Cape cluster, where foundry consortiums negotiate collective spare parts inventory agreements.
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market Segmentation
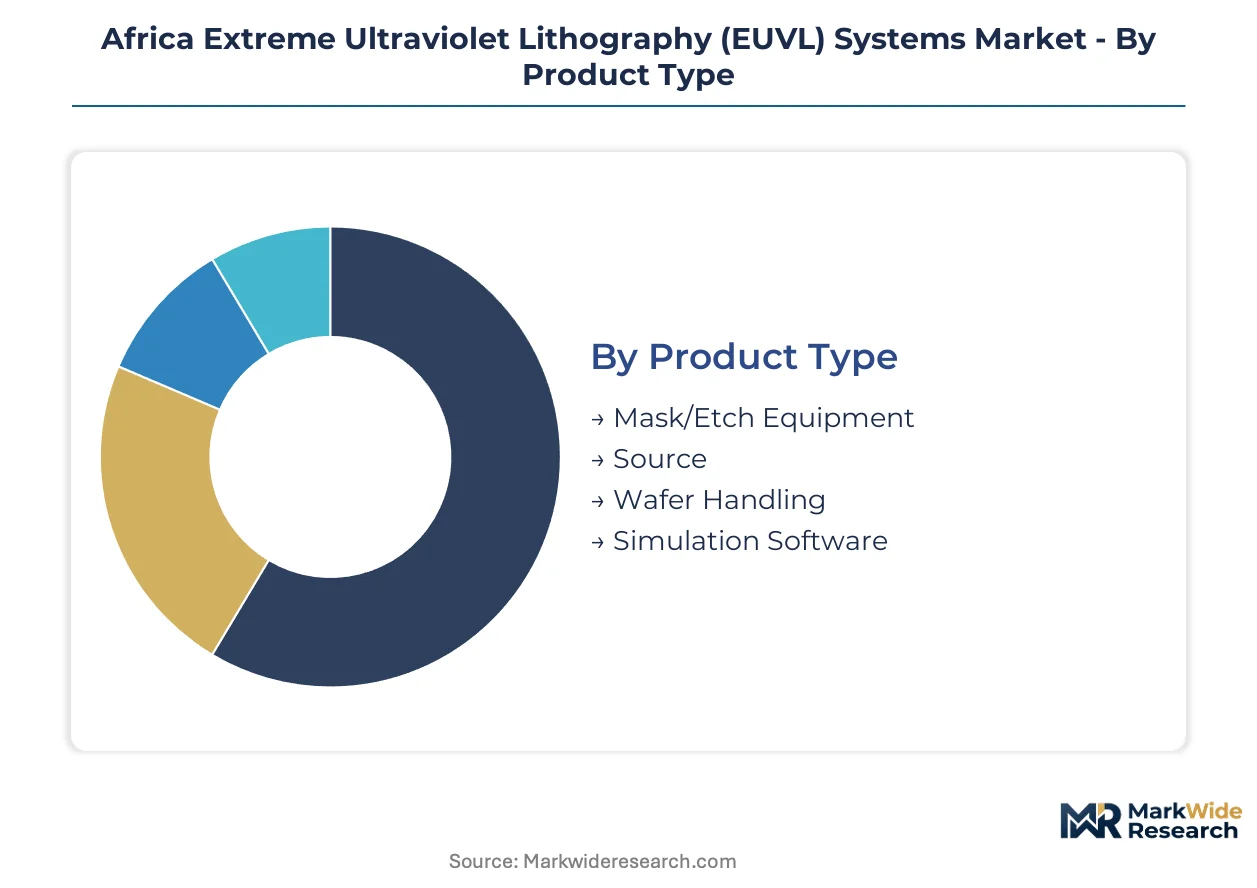
EUVL system procurement in Africa fragments across equipment subsystems, buyer categories, and technology generations that each impose distinct commercial requirements. Understanding how demand concentrates within these dimensions clarifies where capital deployment priorities and vendor relationships diverge.
Product Type:
Equipment cost tiers separate capital-intensive hardware subsystems from software-enabled process layers that scale through licensing rather than physical manufacturing.
- Source:Laser-produced plasma systems generating 13.5 nm wavelength light constitute the highest-value subsystem, with power scaling capabilities determining wafer throughput economics. South Africa's Western Cape foundries concentrate procurement here due to source equipment's direct impact on cost-per-wafer metrics for sub-7 nm production.
- Simulation Software:Computational lithography platforms enable process modeling and overlay correction without cleanroom floor space requirements. Research institutions in Nigeria and South Africa drive demand through partnerships with European equipment vendors seeking technology transfer compliance.
- Mask/Etch Equipment:Reflective mask patterning and plasma etching systems process EUV-exposed wafers through subsequent fabrication steps.
- Wafer Handling:Vacuum-compatible robotic transport and alignment systems maintain contamination control during 13.5 nm exposure sequences.
Source equipment holds installed capacity. Simulation software is rotating up the share rankings.
End User:
Customer type determines procurement scale, technical specification authority, and service contract structures across the African market.
- Foundries:Merchant semiconductor manufacturers serving fabless chip designers purchase complete scanner systems with multi-year service agreements. South Africa's Western Cape cluster anchors regional demand through foundry investments from domestic and European capital partners planning 2 nm-class production.
- Research Institutions:Universities and national laboratories acquire simulation software and limited hardware access for process development rather than volume manufacturing. Collaborative programs between African universities and European equipment vendors create captive demand for EUV process modeling capabilities.
- Semiconductor Manufacturers:Integrated device manufacturers with captive fabrication facilities procure full EUV system stacks for internal chip production.
- IC Developers:Fabless chip design houses influence foundry equipment selection through technology node requirements without direct capital expenditure.
Foundries dominate current procurement volumes. Research institutions are gaining contract share through technology transfer mandates.
Application:
End-use application segments separate high-volume logic and memory production from specialized device categories with distinct resolution and throughput requirements.
- Microchips:Advanced logic and memory devices at sub-7 nm nodes constitute the primary demand driver, with single-patterning economics determining EUV adoption thresholds. South African foundries prioritize microchip applications for smartphone and data center processor production.
- Photonics:Silicon photonics and optical interconnect devices leverage EUV resolution for waveguide patterning at dimensions impractical with 193 nm immersion lithography.
- Sensors:Image sensors and MEMS devices utilize EUV for pixel-dense architectures requiring sub-wavelength feature control.
- Nanotechnology:Emerging applications in quantum devices and advanced materials research access EUV through research institution partnerships rather than production-scale deployment.
Microchip applications command the majority of installed base. Photonics is climbing the fastest as silicon photonics investments accelerate.
Technology:
Technology maturity segments separate established low-NA architectures from high-NA transitions that reconfigure optical subsystems and numerical aperture specifications.
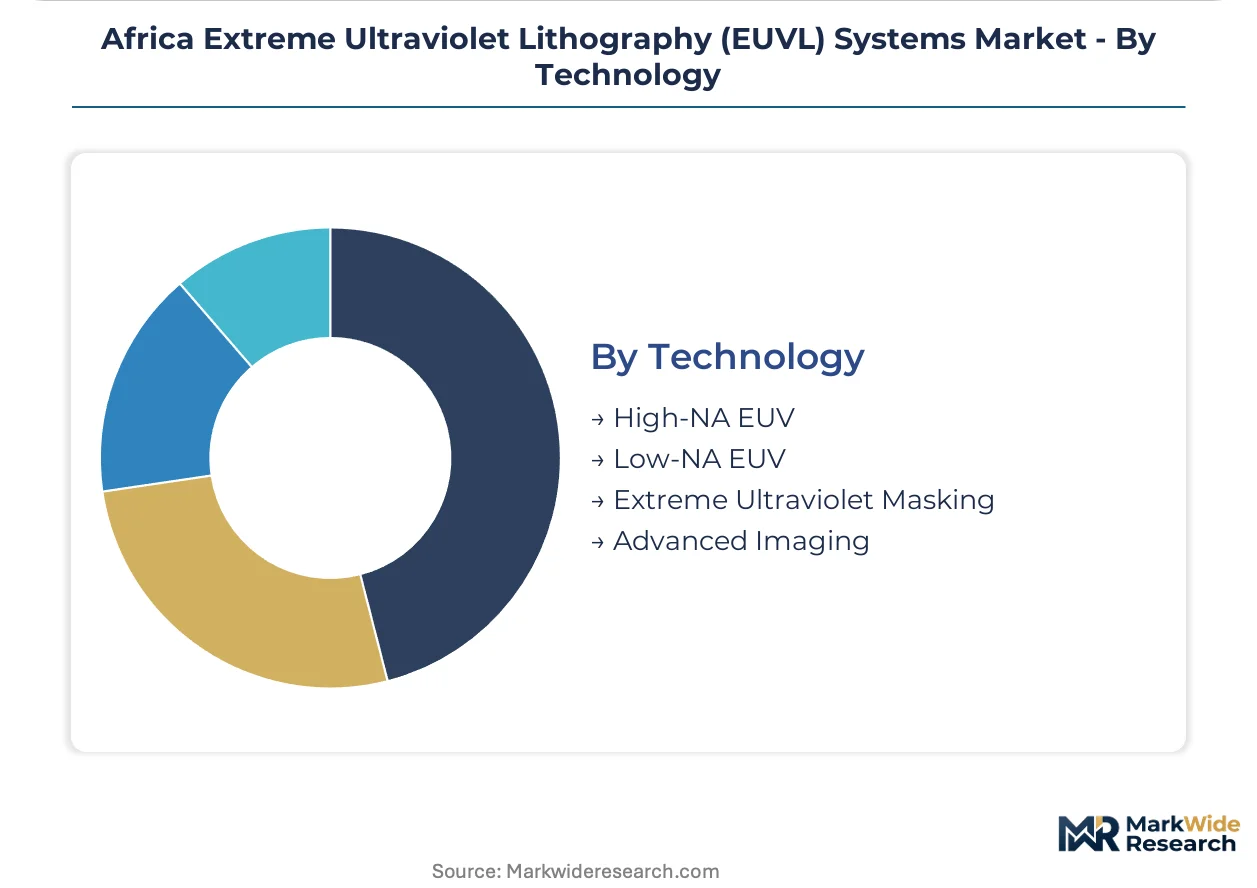
- High-NA EUV:0.55 numerical aperture systems enabling single-patterning at 2 nm-class nodes through anamorphic imaging and new mirror configurations. South African foundries planning node migrations prioritize high-NA scanner reservations over low-NA capacity expansion due to collapsed multi-patterning economics.
- Low-NA EUV:0.33 numerical aperture systems anchor current installed base economics across early African adopters, with established supply chains and technician training protocols.
- Extreme Ultraviolet Masking:Reflective mask technologies and pellicle systems enabling defect-free pattern transfer at 13.5 nm wavelengths.
- Advanced Imaging:Computational overlay and aberration correction algorithms extending effective resolution beyond raw optical limits.
Low-NA EUV retains installed capacity leadership. High-NA EUV is expanding most quickly as node transition plans solidify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch lithography equipment exports flow primarily toward South African foundry operators, with secondary demand emerging from Nigerian research institutions and Egyptian technology transfer programs. Cross-border equipment movements face regulatory fragmentation across national customs regimes.
South Africa
Western Cape semiconductor foundries drive concentrated scanner procurement for sub-7 nm logic production. The National Regulator for Compulsory Specifications enforces electromagnetic compatibility certification that extends equipment commissioning timelines. Cape Town anchors the continent's only operational EUV-ready fab cluster, with Stellenbosch University partnerships supplying process modeling talent.
Nigeria
Lagos and Abuja host greenfield fab investments targeting domestic microchip supply security. The country's national technology regulator coordinates import protocols for vacuum chamber equipment under industrial development frameworks. The Lekki Free Trade Zone concentration attracts European equipment vendors seeking first-mover positioning before competitor saturation.
Egypt
Smart Village technology park outside Cairo houses semiconductor research facilities accessing EUV simulation software. The country's investment promotion authority administers capital goods duty exemptions for lithography equipment under special economic zone statutes. New Cairo's emerging tech corridor partners with European universities for technician training programs.
Morocco
Casablanca-Settat region automotive electronics suppliers create indirect demand through foundry outsourcing relationships. The national investment development agency facilitates technology transfer agreements under industrial acceleration plans. Tangier Med port infrastructure supports equipment transshipment to sub-Saharan African destinations.
Kenya
Nairobi's Konza Technology City hosts semiconductor design houses influencing upstream foundry equipment specifications. The country's communications authority implements spectrum management rules affecting cleanroom electromagnetic environment standards. Mombasa port modernization reduces lithography subsystem import lead times for East African research consortia.
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across equipment subsystems, with source technology and reflective optics commanding concentrated margin pools. The supplier base exhibits extreme consolidation at the scanner system level, fragmenting across adjacent process layers. Two strategic archetypes dominate: integrated lithography platform vendors and optical subsystem specialists. Competitive moves center on high-NA transition partnerships and captive supply arrangements for mirror manufacturing capacity.
Within the integrated platform tier, ASML Holding N.V. and Nikon Corporation occupy positions defined by scanner system architecture control. Among optical subsystem specialists, ZEISS Group exemplifies the reflective optics archetype. These three companies represent the core competitive anchors around which African foundry procurement decisions revolve, with equipment availability timelines and service contract structures shaping vendor selection criteria.
| Leading Market Players |
|---|
| ZEISS Group |
| Toppan Holdings Inc. |
| ASML Holding N.V. |
| KLA Corporation |
| Applied Materials Inc. |
| Nikon Corporation |
| Ushio Inc. |
| Lasertec Corporation |
| Canon Inc. |
| Others |
Value Network & Pricing Analysis
ASML's monopoly on EUV scanner systems and Zeiss's reflective optics manufacturing concentration in Germany concentrate upstream margin capture, funneling pricing power toward source equipment and mirror subsystems while African foundries absorb downstream cost compression through extended service contracts and captive spare parts agreements.
Pricing Analysis
High-NA EUV scanner reservations command substantial premiums over low-NA installed base economics, while simulation software licensing tiers stratify across research institution and commercial foundry access levels. Price differentiation rests on source power specifications and vacuum chamber complexity grades. Cost compression in low-NA source equipment intensifies because South African foundries delay replacement cycles amid high-NA transition planning. Research institutions exhibit highest price sensitivity due to budget constraints under technology transfer mandates, whereas Western Cape foundry consortiums demonstrate lowest sensitivity through collective procurement leverage.
Supply Chain Analysis
Zeiss's Oberkochen mirror manufacturing facilities and ASML's Veldhoven scanner assembly plants anchor contract-manufacturing concentration for reflective optics and integrated lithography platforms. The EUV supply chain draws from German precision optics, Dutch system integration, and South Korean laser component suppliers. Raw material dependencies center on high-purity silicon for mirror substrates, specialty gases for laser-produced plasma generation, and advanced ceramics for vacuum chamber construction. Single-source vulnerability for EUV scanners creates structural risk regardless of downstream demand signals. Distribution runs through direct vendor-foundry relationships with embedded field service engineering rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's EUVL market represents early-cycle expansion anchored by South Africa's Western Cape semiconductor cluster and Nigeria's greenfield fab corridor, with technology transfer mandates from African Union digital economy frameworks accelerating equipment import approvals and skills development programs.
For Market Incumbents: Build captive service technician training moats through Stellenbosch University and Lagos-based technical institute partnerships to preempt vacuum specialist scarcity threats. Secure backward integration into reflective optics inventory pre-positioning within the Western Cape cluster to compress commissioning timelines threatened by South Africa's National Regulator for Compulsory Specifications electromagnetic compatibility certification delays. Deepen source equipment power scaling R&D collaboration with African research institutions to lock in technology transfer compliance advantages. For New Entrants and Emerging Players: Pursue EUV process simulation software licensing opportunities at Nigerian universities and Egypt's Smart Village research facilities where incumbent penetration remains shallow. Target research institution partnerships as the most penetrable segment given technology transfer mandates creating captive demand. Deploy European equipment vendor collaboration frameworks as the primary go-to-market angle, positioning as local certification and training capability extensions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European equipment vendors holding African Union technology transfer program relationships and established South African installation footprints. Long-term viability across the analysis window hinges on high-NA transition timing and foundry node migration execution. Monitor high-NA scanner reservation conversion rates at Western Cape foundries as the critical inflection signal distinguishing capacity expansion from replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV Scanner Reservation | Western Cape foundries secure single-patterning economics for 2 nm-class production nodes. |
| Research Institution Partnership | Stellenbosch University collaborations create captive simulation software demand under technology transfer mandates. |
| Local Certification Pre-qualification | Foundry consortiums compress South African National Regulator for Compulsory Specifications validation timelines. |
| Captive Spare Parts Inventory Agreement | Western Cape cluster procurement collectives unbundle service contracts from equipment sales. |
| Vacuum Technician Training Program | Lagos technical institutes address technician scarcity constraining EUV system maintenance scaling. |
Research Methodology
The analysis maps EUV source equipment, simulation software, mask/etch systems, and wafer handling subsystems, each validated through semiconductor foundry procurement directors, research institution laboratory managers, and European equipment vendor regional sales executives. Primary interviews with cleanroom operations engineers and African Union technology policy officials combined with secondary validation from SEC equipment manufacturer filings, South African Revenue Service customs classifications, and African Union digital economy framework documents. Bottom-up installation tracking and top-down capital expenditure triangulation anchored market sizing.
Forecast assumptions held fixed the African Union technology transfer mandate enforcement intensity and South African National Regulator for Compulsory Specifications certification timeline parameters, while varying high-NA EUV adoption pacing and Nigerian greenfield fab construction completion rates. Segmentation modeling spanned product type, end user category, application, and technology generation dimensions. CAGRs derived from equipment replacement cycle compression analysis and node transition planning disclosures. Forecast inputs incorporated laser-produced plasma source power scaling roadmaps and reflective optics manufacturing capacity constraints.
Sensitivities concentrate around high-NA EUV reservation conversion delays, Nigerian regulatory approval timeline extensions, and vacuum technician training program scaling shortfalls. Forecasts reflect documented assumptions regarding technology transfer compliance enforcement and foundry capital commitment sequencing. Quarterly review of Western Cape foundry construction permits, African Union digital economy policy amendments, and Zeiss mirror manufacturing capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Solar Module Production Equipment Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
I-Line Lithography Market