
 Global DC Drives Market | 2026-2036
Global DC Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Global DC Drives Market Analysis
Digital integration with AC variable frequency drives is narrowing the performance gap that once protected DC drive incumbency in heavy-torque applications. ABB Ltd. leverages its installed base in metals processing to sustain aftermarket revenue streams. Siemens AG anchors its position through embedded diagnostics and predictive maintenance modules. Danfoss Group differentiates via compact regenerative drives targeting retrofit installations.
DC drives are electromechanical power conversion systems that regulate torque and speed in DC motors through controlled thyristor or transistor bridge firing angles, typically operating from 0.25 kW to multi-megawatt ratings. They serve primary industrial functions requiring sustained low-speed torque, precise speed control, and four-quadrant operation. Low and medium power ratings dominate unit volume due to proliferation in conveyor systems and machine tool spindles, while high power segments capture disproportionate margin pools in steel rolling and cement kiln applications. Industrial automation absorbs the largest share of deployment value, though electric vehicles represent an emerging vector as commercial fleets revisit DC motor architectures for specific duty cycles.
The US Department of Energy enforces minimum efficiency standards through NHTSA and industrial equipment guidelines, while China's MIIT mandates GB standard compliance for motor system energy consumption. The EU Ecodesign Directive and F-Gas Regulation collectively restrict inefficient drive-motor pairings and refrigerant-based cooling in HVAC-integrated units. Stakeholders must monitor whether silicon carbide power module cost curves erode the cost advantage DC drives retain in high-torque retrofit scenarios.
Market Dynamics
Silicon carbide power semiconductors are compressing the cost-performance tradeoff that historically protected DC drive incumbency in heavy-torque retrofit scenarios. The technology is forcing incumbent vendors to defend installed-base revenue through embedded diagnostics and predictive maintenance modules rather than hardware margins alone.
Growth Catalysts
- China's dual carbon goals:MIIT-mandated GB standard compliance for motor system energy consumption is accelerating replacement cycles in steel and cement installations.
- Four-quadrant operation:Regenerative braking requirements in crane and hoist applications sustain demand for DC drive architectures in port logistics and mining.
- Germany's automotive tooling:Precision spindle control in EV battery manufacturing lines is anchoring replacement demand from machinery OEMs.
Market Restraints
- Copper and rare earth magnet volatility:Input cost swings in motor construction materials compress margin predictability for drive-motor system integrators.
- AC variable frequency drive substitution:Vector control algorithms now replicate low-speed torque characteristics that previously required DC architectures.
- EU F-Gas Regulation:Restrictions on refrigerant-based cooling in HVAC-integrated drive units eliminate a cross-selling channel for multi-application vendors.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced manufacturing equipment create a subsidy window for DC drive localization in metals processing.
- Commercial fleet electrification:Specific duty cycles in urban delivery vehicles are revisiting DC motor architectures for cost-optimized torque delivery.
- Retrofit channel digitization:Remote monitoring platforms are collapsing service response times for aging installed bases in paper mills and textile plants.
Industry Challenges
- Thyristor bridge commissioning expertise:The retiring workforce proficient in analog firing angle calibration creates a talent bottleneck for legacy system maintenance.
- CE marking and EU Ecodesign Directive compliance:Extended certification timelines for multi-megawatt drive systems delay project revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DC Drives Market |
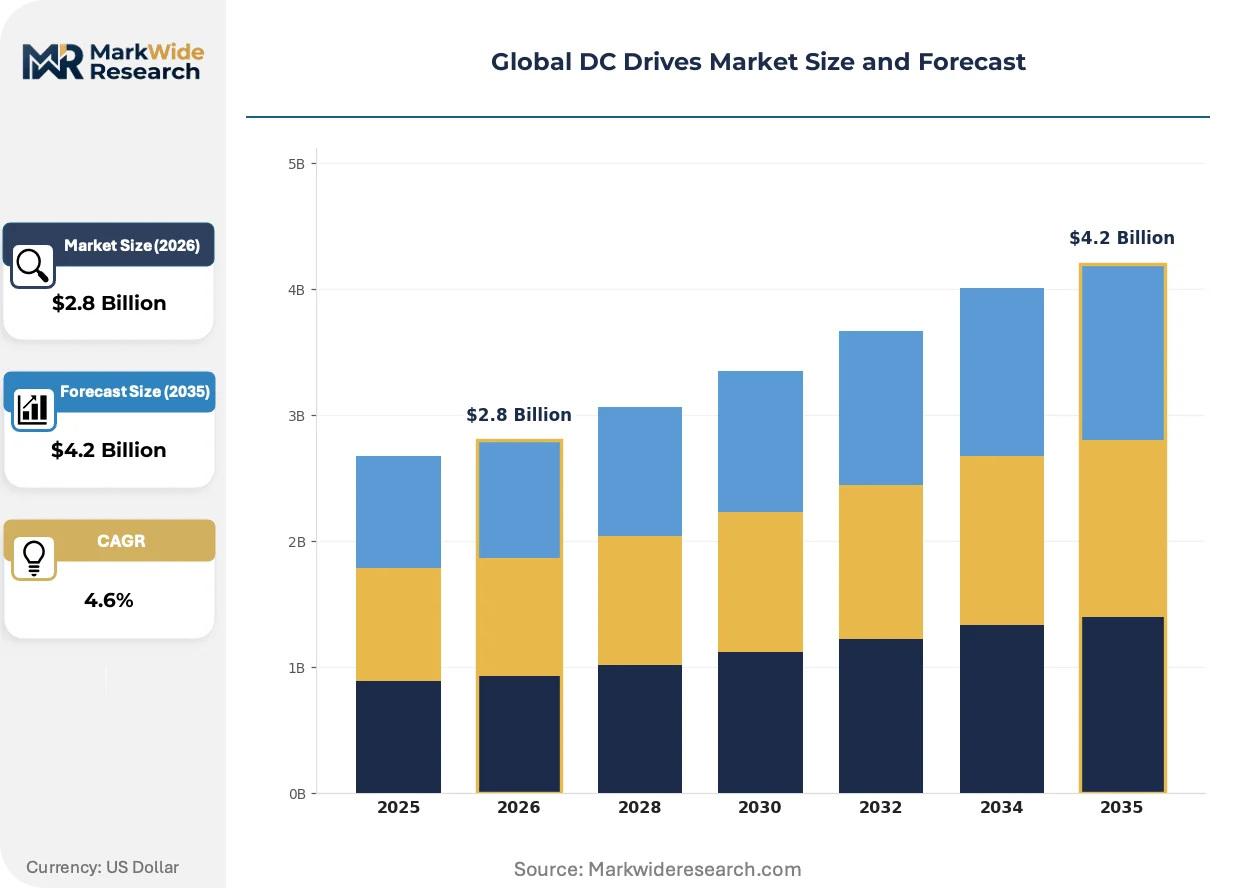
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Industrial Automation, HVAC Systems, Electric Vehicles, Robotics Power Rating: Low Power, Medium Power, High Power, Ultra High Power Deployment: Onshore, Offshore, Integrated Systems, Standalone Units End User: Manufacturing, Transportation, Renewable Energy, Mining |
| Companies Covered | ABB Ltd., Siemens AG, Schneider Electric SE, Rockwell Automation, Mitsubishi Electric Corporation, Danfoss Group, Parker Hannifin Co., Emerson Electric Co., Toshiba International Corporation Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DC Drives Market Emerging Trajectories
Power electronics architecture is undergoing a generational shift as wide-bandgap semiconductors rewrite cost curves. Three concurrent developments are reshaping competitive positioning and customer procurement criteria.
Silicon carbide MOSFET modules are collapsing the price-performance boundary between DC and AC drive systems in the 0.25 kW to 500 kW range. Steel mini-mills in India and Southeast Asia are piloting SiC-based DC regenerative drives for rolling mill stands. The technology is collapsing hardware margin pools that incumbent vendors relied upon for aftermarket service cross-subsidization.
The EU Ecodesign Directive and F-Gas Regulation are tightening in tandem to restrict inefficient drive-motor pairings and refrigerant-dependent cooling architectures. Industrial HVAC-integrated drive units face dual compliance burdens that favor air-cooled or liquid-cooled alternatives. Steel and cement installations in Germany and Poland are accelerating replacement cycles to preempt regulatory obsolescence.
After-sales service unbundling is separating hardware procurement from long-term maintenance contracts in metals processing. End-users in automotive stamping and aluminum extrusion are negotiating predictive analytics subscriptions independent of capital equipment purchases. This shift is most visible in Germany's Ruhr industrial cluster and Japan's Kansai manufacturing belt.
Global DC Drives Market Segmentation
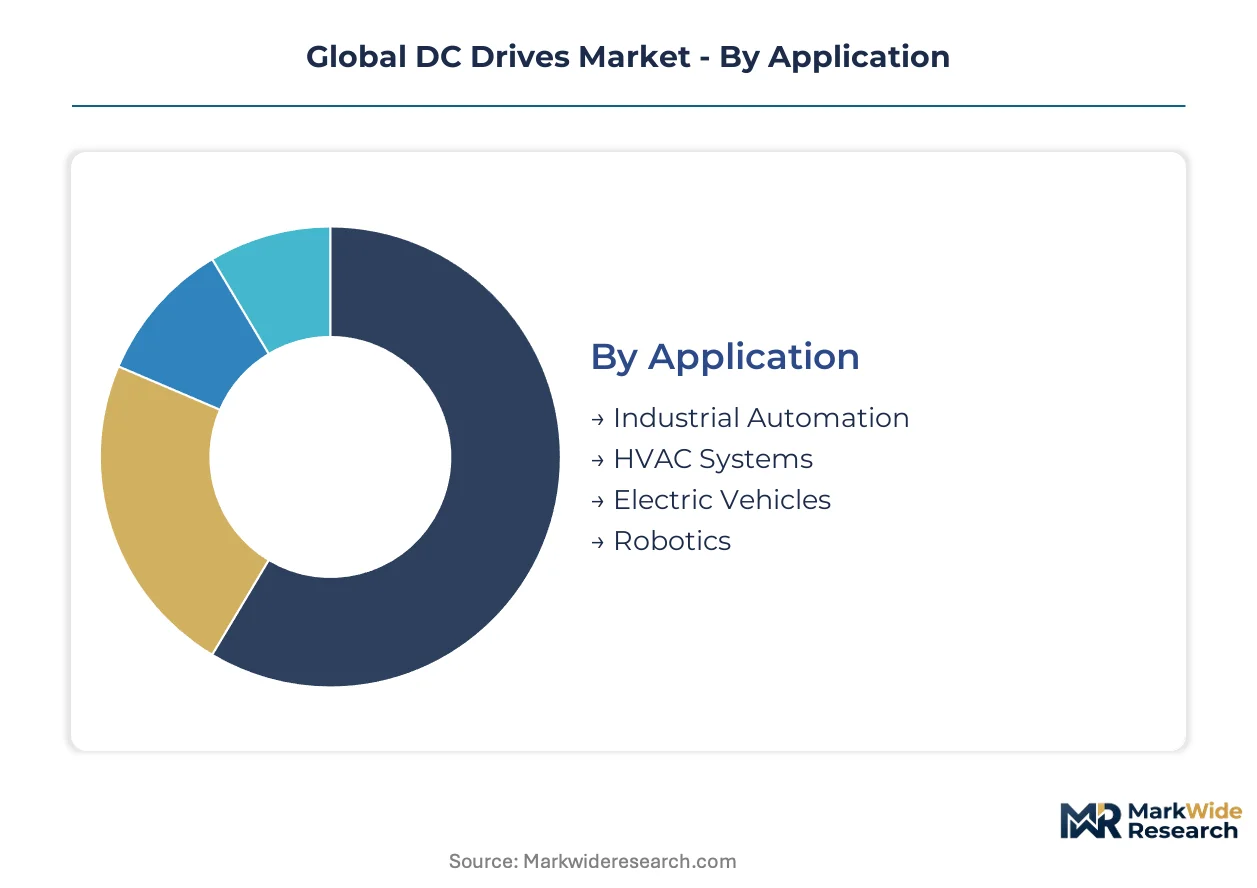
DC drives serve heterogeneous operational requirements across torque demands, environmental conditions, and integration complexity. Segmentation reveals where hardware margins concentrate versus where volume commoditization pressures dominate procurement behavior.
Application:
Application segmentation tracks where motor control precision commands premium pricing versus where standard configurations suffice.
- Industrial Automation:Conveyor systems, machine tool spindles, and packaging lines deploy DC drives for sustained low-speed torque with four-quadrant regenerative capability. German automotive battery manufacturing lines anchor replacement demand as machinery OEMs upgrade precision spindle control.
- HVAC Systems:Fan and pump motor regulation in commercial buildings and data centers. EU F-Gas Regulation restrictions on refrigerant-based cooling eliminate a cross-selling channel for multi-application vendors serving this segment.
- Electric Vehicles:Commercial fleet duty cycles in urban delivery vehicles revisit DC motor architectures for cost-optimized torque delivery.
- Robotics:Precision joint actuation and positioning systems requiring rapid torque response.
Industrial Automation commands the established base. The steepest expansion runs through Electric Vehicles.
Power Rating:
Power tiers separate volume-driven procurement from margin-protected engineered systems.
- Low Power:Units from 0.25 kW to approximately 5 kW proliferate in conveyor systems and small machine tool spindles. India's PLI scheme for advanced manufacturing equipment creates subsidy windows for localization in this tier.
- Medium Power:Ratings from 5 kW to 500 kW serve steel rolling stands and cement kiln drives. Silicon carbide MOSFET modules are collapsing price-performance boundaries against AC alternatives in this range.
- High Power:Multi-megawatt systems for heavy industrial process equipment.
- Ultra High Power:Specialized installations in mining hoists and port crane applications.
Medium Power captures disproportionate margin pools. Low Power expands most quickly through conveyor proliferation.
Deployment:
Deployment modes reflect integration depth and service accessibility tradeoffs.
- Onshore:Standard industrial installations with direct grid connection and local maintenance access.
- Offshore:Marine and subsea applications requiring sealed enclosures and remote diagnostics capability.
- Integrated Systems:DC drives embedded within larger process control architectures with unified HMI and predictive maintenance modules.
- Standalone Units:Discrete drive packages for retrofit installations in aging paper mills and textile plants where remote monitoring platforms collapse service response times.
Standalone Units command the established base. Integrated Systems gain share fastest through predictive analytics subscription unbundling.
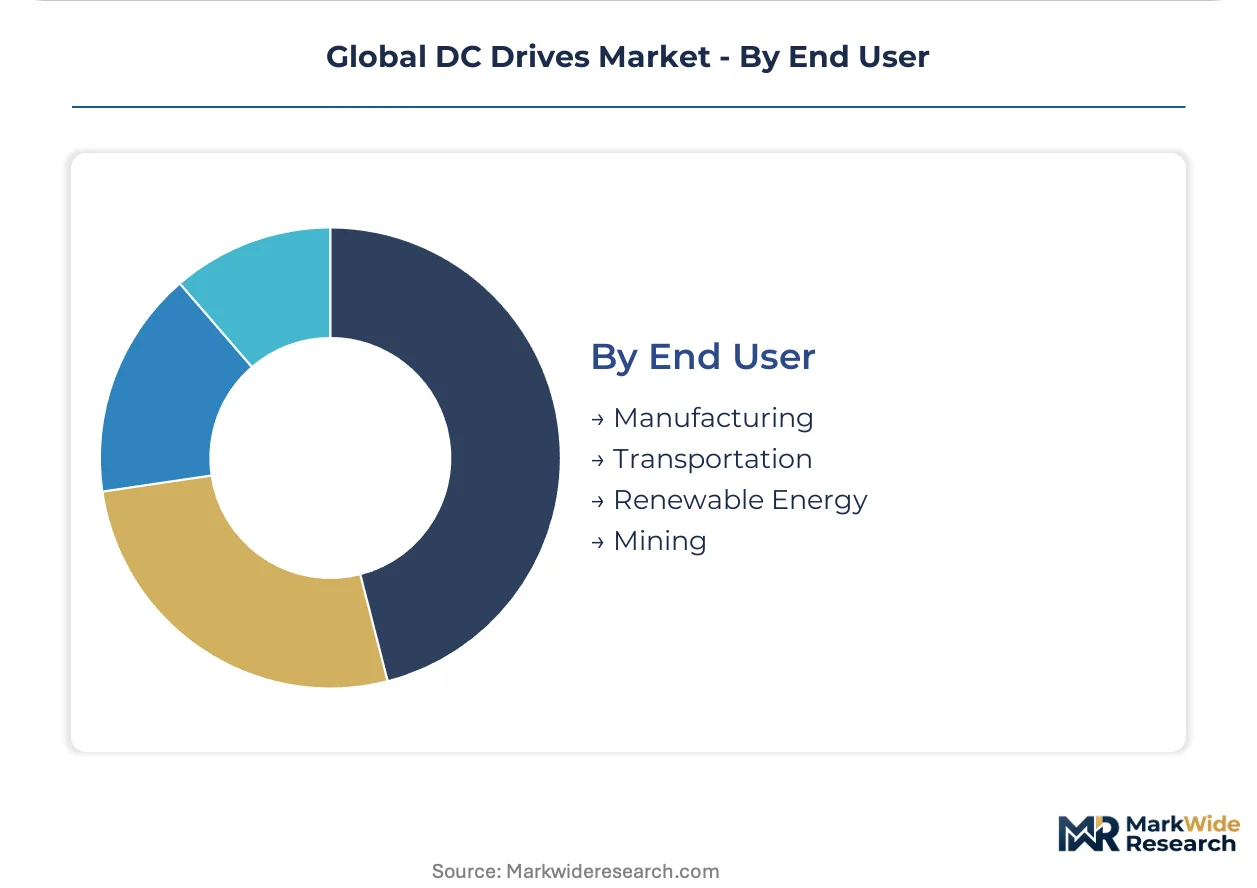
End User:
End user categories map regulatory exposure and replacement cycle timing.
- Manufacturing:Steel mills, paper mills, and automotive stamping operations. China's MIIT-mandated GB standard compliance accelerates replacement cycles in steel and cement installations.
- Transportation:Port logistics, mining haulage, and emerging commercial fleet electrification. Regenerative braking requirements in crane and hoist applications sustain DC drive architectures.
- Renewable Energy:Solar tracking systems and small-scale hydroelectric turbine regulation.
- Mining:Underground ventilation fans, conveyor systems, and hoisting equipment requiring explosion-proof enclosures.
Manufacturing commands the established base. Transportation climbs the fastest through port logistics modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel mills and automotive battery manufacturers concentrate DC drive procurement in Germany, China, and the United States, with India's metals processing sector emerging as a volume growth vector.
Germany
Automotive tooling and precision spindle control anchor replacement demand from machinery OEMs serving EV battery manufacturing lines. The EU Ecodesign Directive and F-Gas Regulation tighten compliance burdens for drive-motor pairings and refrigerant-dependent cooling. The Ruhr industrial cluster accelerates replacement cycles to preempt regulatory obsolescence in steel and aluminum extrusion operations.
China
Steel mills and cement installations expand DC drive procurement under MIIT-mandated GB standard compliance for motor system energy consumption. The country's dual carbon goals accelerate replacement cycles in heavy industrial process equipment. Yangtze River Delta manufacturing hubs pilot silicon carbide-based regenerative drives for rolling mill stands.
United States
Port logistics and mining haulage sustain demand for four-quadrant regenerative braking in crane and hoist applications. The Department of Energy enforces minimum efficiency standards through NHTSA and industrial equipment guidelines. Midwest automotive stamping operations anchor aftermarket service revenue for aging installed bases.
India
Production-linked incentives for advanced manufacturing equipment create subsidy windows for DC drive localization in metals processing. The country's BIS standards and CEA regulations shape compliance requirements for motor system energy consumption. Gujarat and Maharashtra industrial corridors attract capacity expansion for conveyor system deployments.
Japan
Machine tool spindles and robotics precision actuation sustain demand for rapid torque response architectures. METI industrial efficiency mandates and JIS standards govern drive-motor system procurement criteria. The Kansai manufacturing belt unbundles predictive analytics subscriptions from hardware purchases in aluminum extrusion and automotive stamping.
Global DC Drives Market Vendor Landscape
Channel-controlling players compete with product-specialist players across hardware procurement and aftermarket service revenue streams. The vendor base clusters around diversified industrial conglomerates with installed-base leverage and focused power electronics specialists with compact regenerative architectures. Three archetypes dominate: installed-base defenders monetizing predictive maintenance modules, retrofit-focused compact drive manufacturers, and integrated automation platform vendors. M&A activity targets predictive analytics capabilities, while capacity expansion concentrates on silicon carbide module integration for medium-power ratings.
Among European-based industrial conglomerates, ABB Ltd. and Siemens AG occupy positions as installed-base anchors in metals processing and automotive manufacturing. Danfoss Group exemplifies the compact regenerative specialist archetype targeting retrofit installations. These three entities represent the competitive spectrum from diversified platform breadth to focused hardware differentiation.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Schneider Electric SE |
| Rockwell Automation |
| Mitsubishi Electric Corporation |
| Danfoss Group |
| Parker Hannifin Co. |
| Emerson Electric Co. |
| Toshiba International Corporation Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in silicon carbide power module foundries is compressing lead times and inflating input costs for DC drive manufacturers, forcing vendors to pass through component premiums while accelerating qualification of second-source suppliers. This utilization squeeze simultaneously tightens hardware margins and reshapes procurement strategies across medium-power rating tiers.
Pricing Analysis
Cost-plus contracts indexed to copper and rare earth magnet price benchmarks dominate procurement between drive manufacturers and steel mill operators. Three-tier pricing structure across premium diagnostics-integrated, standard regenerative, and economy standalone configurations separates predictive maintenance bundling from bare hardware supply. Cost compression in low-power ratings is intensifying because silicon carbide MOSFET substitution erodes DC cost advantages against AC alternatives. Automotive battery manufacturing lines in Germany exhibit the least price sensitivity due to precision spindle control requirements, while Indian conveyor system deployments under PLI subsidies show the highest.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn Industrial Internet, Jabil Circuit, and Flex Ltd. for power electronics assembly and thermal management subsystem integration. Geographic supply concentration centers on China for thyristor bridge components, Germany for precision encoder feedback systems, and Japan for high-reliability capacitors. Raw material dependencies draw from copper busbar stock, silicon carbide wafers, and rare earth magnet alloys. Single-source vulnerability in silicon carbide substrate supply creates exposure to export licensing restrictions. Distribution runs through authorized industrial automation distributors with embedded field engineering capability rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DC drives market functions as a defensive-moat arena where regulatory entrenchment in EU Ecodesign Directive compliance creates high switching costs for installed-base customers. This structural advantage favors incumbents with certification legacy and embedded diagnostic platforms.
For Market Incumbents: Insulate aftermarket revenue streams by embedding predictive maintenance modules deeper into standalone retrofit units, countering silicon carbide-based AC substitution threats. Deepen backward integration into silicon carbide power module sourcing through joint development agreements with substrate foundries, securing supply priority as capacity constraints persist. For New Entrants and Emerging Players: Pursue India's metals processing corridor under PLI scheme subsidies, where localized DC drive assembly for conveyor systems faces limited entrenched competition. Target commercial fleet electrification duty cycles with compact regenerative architectures optimized for urban delivery torque profiles, leveraging direct OEM relationships rather than distributor channels. For Investors and Strategic Acquirers: Capital is best deployed toward predictive analytics platform specialists with proven deployment in paper mill and textile plant remote monitoring, where service unbundling trends concentrate value capture. Long-term viability hinges on silicon carbide cost curve trajectory; the signal to watch is Chinese mini-mill adoption rates for SiC-based regenerative rolling mill drives as inflection indicator for hardware margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Integration | Collapses price-performance gap with AC drives in 5-500 kW ratings at Yangtze River Delta pilots. |
| Predictive Maintenance Platform Launch | Unbundles service contracts from hardware in Germany's Ruhr industrial cluster aluminum extrusion operations. |
| India PLI Localization Partnership | Captures subsidy windows for conveyor system DC drive assembly in Gujarat industrial corridors. |
| CE Marking Acceleration Program | Preempts EU Ecodesign Directive obsolescence risk for multi-megawatt steel mill installations. |
| Commercial Fleet Duty Cycle Optimization | Revisits DC motor architectures for cost-optimized torque delivery in urban delivery electrification. |
Methodological Framework
Desk research of SEC 10-K filings, EU Ecodesign Directive compliance databases, and MIIT GB standard submissions preceded structured interviews with maintenance directors at steel mills, OEM procurement teams in automotive battery manufacturing, aftermarket service heads at industrial automation distributors, and plant engineers in cement kiln operations. Primary intelligence combined with secondary validation across customs trade data for thyristor bridge imports, FERC industrial efficiency filings, and production statistics from vehicle battery manufacturing lines. Bottom-up unit shipment estimates triangulated against top-down energy consumption projections for motor system installations.
Assumptions held fixed include current EU F-Gas Regulation enforcement intensity and MIIT dual carbon goal compliance timelines, while silicon carbide module cost curves and AC drive vector control algorithm advancement rates were varied across sensitivity scenarios. Segmentation dimensions modeled span power rating tiers, application categories from industrial automation through electric vehicles, deployment modes distinguishing standalone from integrated systems, and end-user industries with divergent regulatory exposure. CAGRs derived from regression against historical replacement cycle timing in German automotive tooling and Chinese steel mill modernization waves.
Sensitivities concentrate around silicon carbide substrate export licensing shifts and AC variable frequency drive substitution velocity in crane and hoist applications. Forecasts reflect documented assumptions on regulatory enforcement continuity and rare earth magnet price stability. Quarterly review of Chinese mini-mill SiC pilot adoption rates and EU CE marking backlog duration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Air Filters Market