
 High-Speed Electric Spindle Market | 2026-2036
High-Speed Electric Spindle Market Size, Share, and Industry Trends Forecast 2026-2036
High-Speed Electric Spindle Market Insights
Ceramic hybrid bearings is consolidating around high-speed electric spindles as silicon nitride balls replace steel in demanding applications, cutting centrifugal loading and extending operating speeds beyond conventional limits. NSK leverages its ceramic bearing supply chain to anchor premium spindle architectures across Asian machine tool markets. FISCHER Spindle sustains Swiss precision positioning through vertically controlled manufacturing of motorized spindle units. GMN Paul Müller Industrie dominates air-bearing spindle segments for semiconductor and optical grinding applications.
A high-speed electric spindle is an electromechanical rotating assembly designed to deliver rotational speeds typically exceeding 10,000 RPM, integrating a built-in motor or external drive system with precision bearings to maintain sub-micron runout tolerances during material removal or finishing operations. Magnetic Bearing technology commands the highest precision tier in semiconductor and optical grinding, where nanometer-level stability justifies capital intensity, while Belt Drive architectures retain cost advantages in mid-speed milling and drilling workflows. Motorized Spindle configurations capture expanding share in CNC Machining centers as machine tool builders integrate compact, thermally stable units to reduce transmission losses and improve surface finish predictability.
FCC electromagnetic compatibility standards and OSHA machine guarding requirements shape North American spindle design, mandating shielding and interlock architectures that add engineering overhead but prevent market exclusion. EMA medical device regulations and CE machinery directives constrain European suppliers to validated vibration profiles and documented failure modes for aerospace and surgical instrument applications. Buyers must weigh bearing technology selection against duty cycle profiles, as ceramic and magnetic solutions carry steeper upfront costs but deliver measurable total-cost advantages in continuous-operation environments.
Market Dynamics
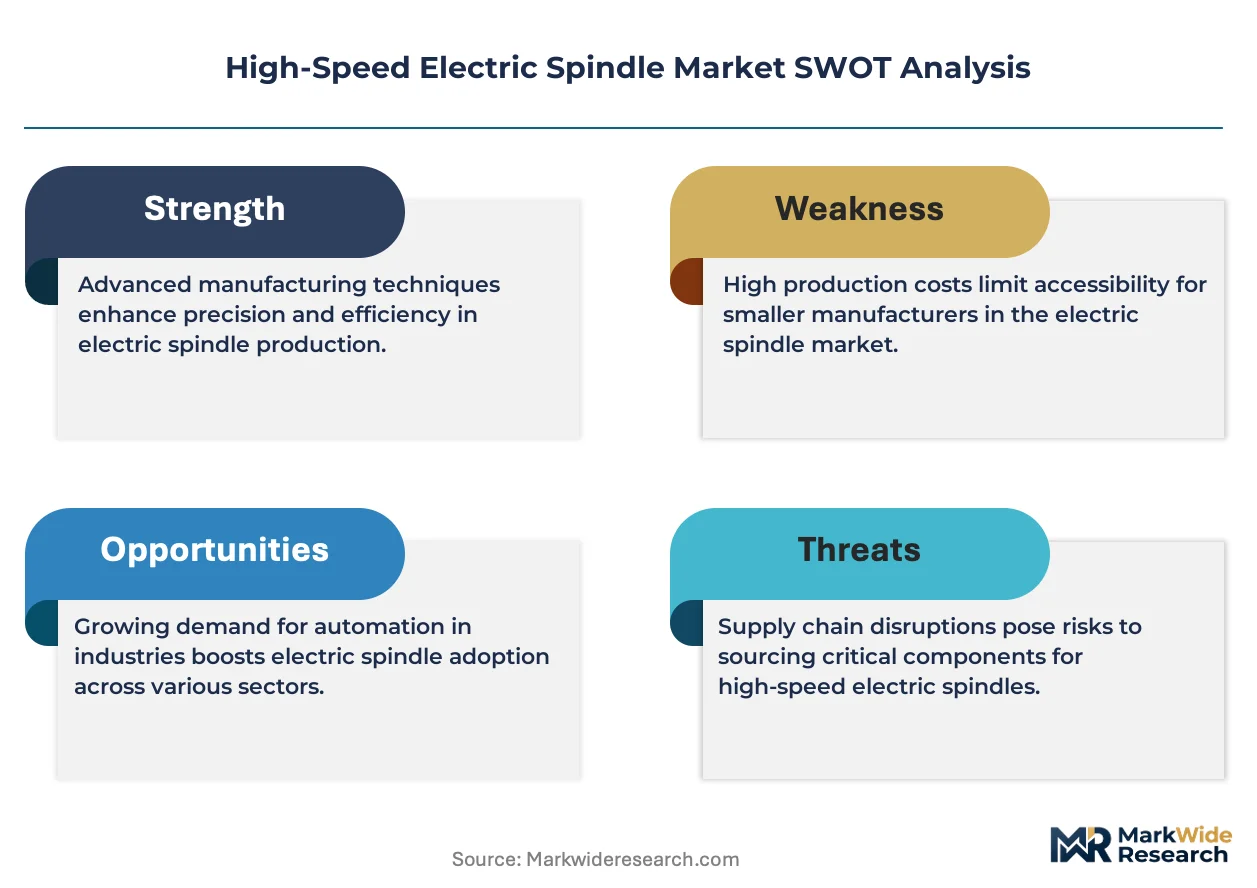
Ceramic bearing architectures and magnetic levitation systems are compressing maintenance intervals while extending operational ceilings, forcing spindle builders to re-engineer thermal management and control electronics around fundamentally different mechanical constraints.
Growth Catalysts
- Aerospace component miniaturization:Turbine blade root machining and structural bracket fabrication now demand spindle speeds above 40,000 RPM with sub-micron repeatability, pulling motorized spindle configurations into five-axis machining centers.
- F-Gas Regulation phase-down:The EU mandate on fluorinated greenhouse gases is eliminating oil-mist cooling systems in favor of minimal-lubrication or dry-running ceramic bearing designs that eliminate coolant dependency.
- Silicon nitride ball adoption:Hybrid ceramic bearings reduce centrifugal loading by 60% versus steel equivalents, enabling German and Japanese machine tool builders to specify 25% higher operating speeds without sacrificing bearing life.
Market Restraints
- Neodymium supply concentration:Permanent magnet motors depend on rare earth processing concentrated in Chinese refining facilities, exposing motorized spindle producers to input cost volatility and export quota uncertainty.
- Air-bearing technical ceiling:Load-carrying capacity limitations restrict air-bearing spindles to sub-5kW continuous operation, excluding them from heavy stock removal in titanium and Inconel aerospace workpieces.
- CE machinery directive compliance costs:Documented vibration monitoring and validated failure mode analysis add 12-18% engineering overhead for European-market spindle systems versus equivalent units certified for other jurisdictions.
Strategic Opportunities
- Indian aerospace supplier tier:Bangalore and Hyderabad machining clusters serving Airbus and Boeing offset programs remain underserved by high-speed spindle service infrastructure, creating white space for localized technical support partnerships.
- Battery electrode slitting:Lithium-ion cell manufacturing requires 80,000+ RPM air-bearing spindles for precision foil cutting, a specification tier where semiconductor-grade spindle builders can extend existing magnetic bearing expertise.
- EU Green Deal capital subsidies:Energy-efficient spindle retrofits qualify for national recovery fund allocations in Italy and Spain, accelerating replacement cycles in aging automotive supplier machine parks.
Industry Challenges
- Magnetic bearing control engineering scarcity:Active magnetic levitation systems require specialized mechatronics expertise combining rotor dynamics, power electronics, and real-time DSP programming that concentrates in Swiss and German university-industry clusters.
- ISO 230-7 runout certification timelines:Third-party thermal drift and axial stiffness validation for semiconductor-grade spindles extends delivery lead times by 8-14 weeks, compressing builder responsiveness to spot demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Speed Electric Spindle Market |
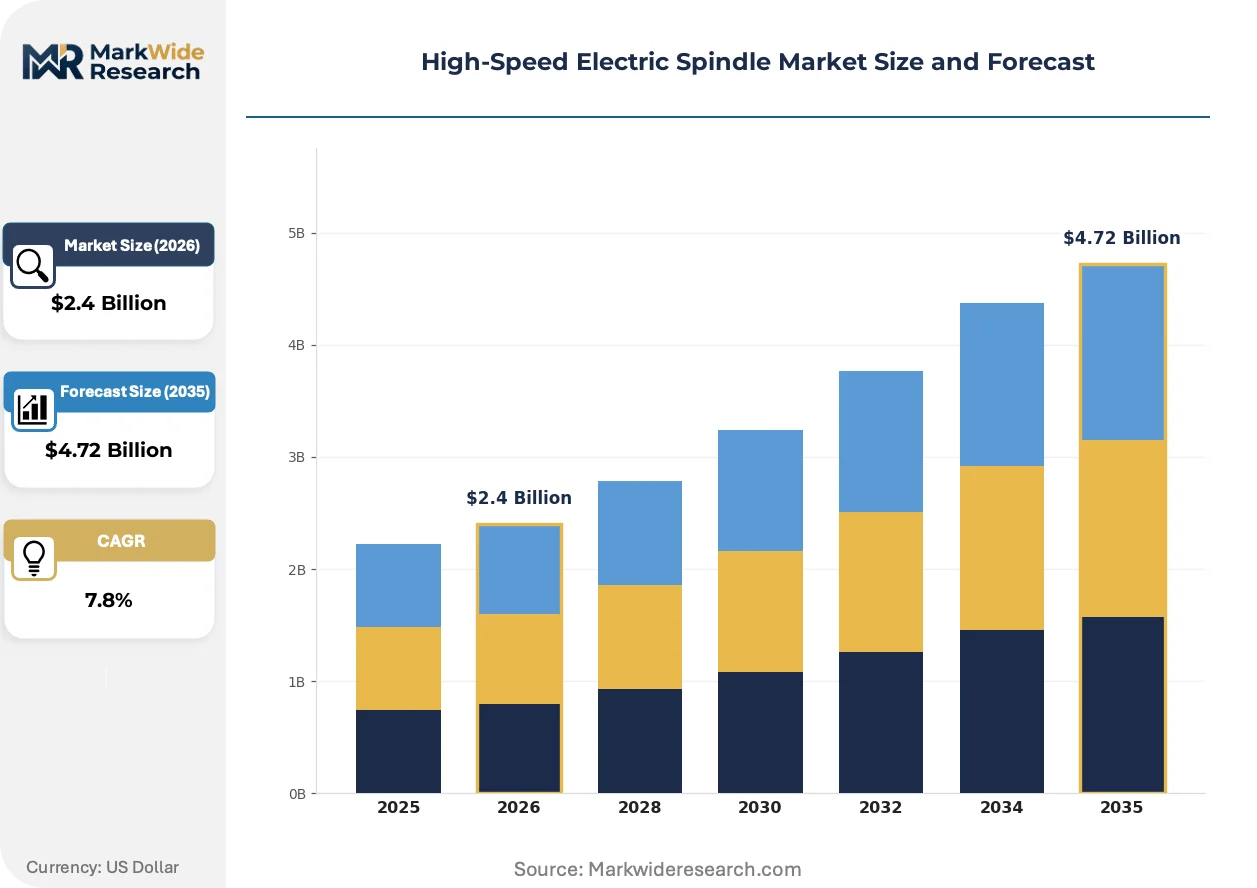
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precision Spindle, Motorized Spindle, HSK Spindle, BT Spindle, Capto Spindle Technology: Direct Drive, Belt Drive, Magnetic Bearing, Air Bearing, Hybrid Bearing Application: CNC Machining, Milling, Drilling, Grinding, Engraving End User Industry: Aerospace Manufacturing, Machine Tool Manufacturers, Electronics Production, Metal Fabrication, Tooling Workshops |
| Companies Covered | NAKANISHI, NSK, FISCHER Spindle, SETCO, POSA SPINDLE, GMN Paul Müller Industrie, IBAG, Kenturn, HSD SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Speed Electric Spindle Market Trends and Innovations
Spindle system architectures are fragmenting into interchangeable sub-assemblies that decouple bearing cartridges from motor windings and sensor packages, enabling field-reconfigurable units that adapt to shifting workpiece materials without full replacement.
Active magnetic bearing technology is modularizing around standardized 400V DC bus architectures and interchangeable stator-rotor cartridges. Semiconductor equipment manufacturers in South Korea and Taiwan now specify platform-compatible spindle families that share control electronics across 60,000 RPM grinding and 120,000 RPM dicing applications. This convergence is compressing vendor qualification timelines and forcing air-bearing specialists to integrate magnetic levitation modules or cede the highest-precision tier.
The EU F-Gas Regulation and accompanying national implementation acts are banning perfluorinated lubricant formulations used in high-speed bearing cooling. German spindle builders now engineer sealed-for-life ceramic bearing units with solid lubricant films that eliminate external coolant circuits entirely. Aerospace machining centers in Stuttgart and Munich machine tool clusters are the first application tier affected, with medical device manufacturers following under MDR cleanliness mandates.
Machine tool buyers now unbundle spindle service contracts from initial capital procurement, negotiating separate performance-based maintenance agreements with specialized rebuilders. Japanese automotive suppliers pioneered this separation, treating spindles as consumable precision assets with predictable replacement cycles rather than capital equipment. European CNC retrofitters are capturing this service layer, displacing OEM aftermarket programs through faster turnaround and localized inventory positioning.
High-Speed Electric Spindle Market Segmentation
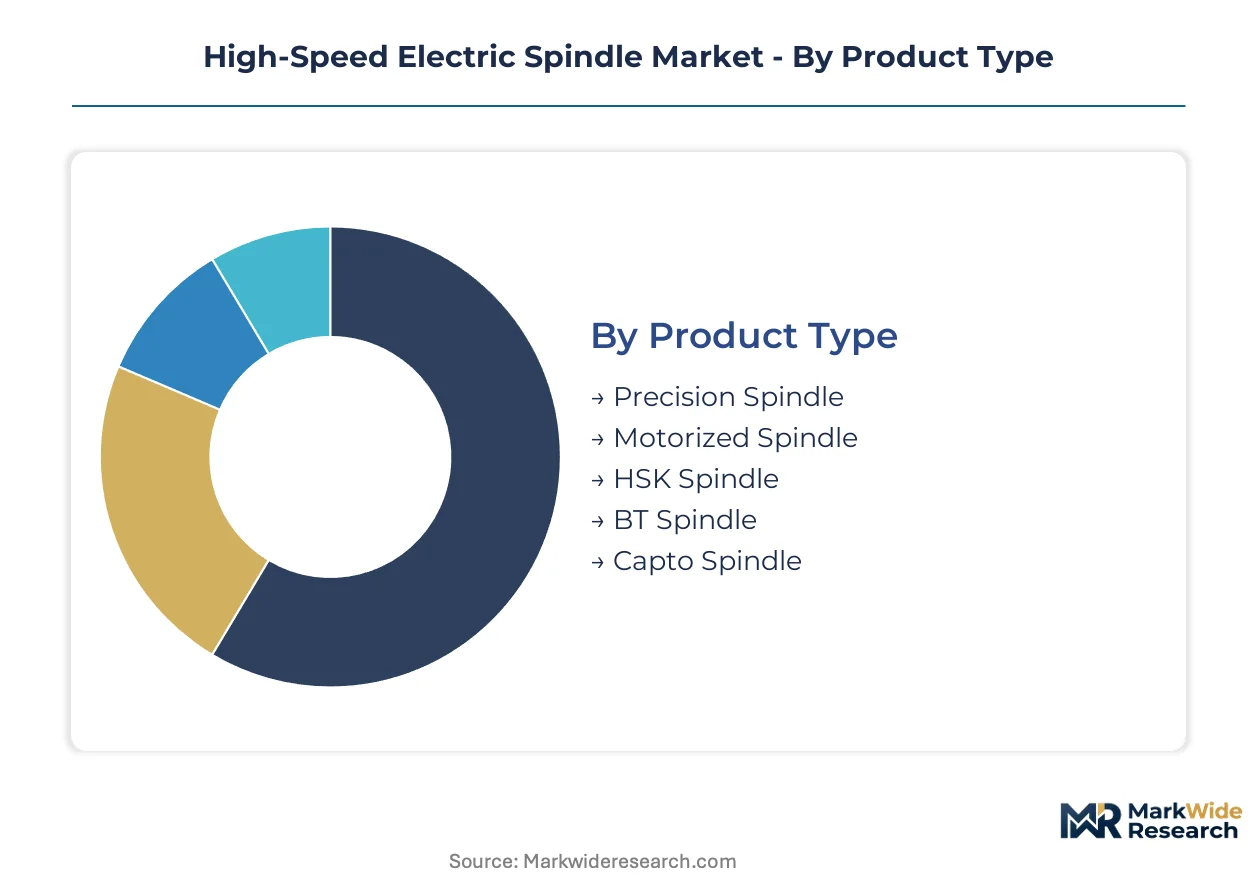
Spindle architectures fragment across bearing technologies, tool interfaces, and drive configurations that each carry distinct regulatory burdens and performance ceilings. Buyers select configurations based on duty cycle intensity, precision requirements, and coolant elimination mandates from environmental regulators.
Product Type:
Motorized Spindle and Precision Spindle configurations face CE machinery directive validation for vibration monitoring, while tool-interface variants must document ISO runout certification timelines that extend delivery schedules.
- Motorized Spindle:Integrates permanent magnet motors directly into the rotating assembly, eliminating belt transmission losses and thermal drift. Demand concentrates in German five-axis machining centers serving Airbus structural bracket programs, pulled by F-Gas Regulation mandates for minimal-lubrication designs.
- Precision Spindle:Delivers sub-micron runout tolerances through hybrid ceramic bearing architectures and thermally stabilized housings. Japanese semiconductor equipment manufacturers specify these for silicon wafer dicing applications, where nanometer-level stability justifies capital intensity.
- HSK Spindle:Hollow shank taper interface enables rapid tool change and superior torque transmission for heavy stock removal.
- BT Spindle:Japanese standard taper retains dominance in Asian machine tool retrofits and automotive supplier parks.
- Capto Spindle:Modular polygonal interface from Sandvik Coromant supports multi-function machining centers in Scandinavian tooling workshops.
Motorized Spindle sits at the top of the volume ranking, with Precision Spindle climbing the fastest.
Technology:
Cost tiers separate magnetic and air-bearing solutions at the premium end from belt-drive architectures serving mid-speed milling workflows with lower capital thresholds.
- Magnetic Bearing:Active levitation systems eliminate mechanical contact entirely, achieving nanometer stability for optical grinding and semiconductor lithography. Swiss and German university-industry clusters concentrate the specialized mechatronics expertise required for rotor dynamics and real-time DSP programming.
- Air Bearing:Pressurized film supports rotating assemblies without solid contact, enabling 80,000+ RPM operation for lithium-ion battery electrode slitting. South Korean and Taiwanese semiconductor equipment manufacturers now specify platform-compatible families sharing control electronics across grinding and dicing applications.
- Direct Drive:Eliminates transmission elements entirely, reducing maintenance intervals in continuous-operation environments.
- Belt Drive:Retains cost advantages in mid-speed drilling and roughing workflows where precision requirements relax.
- Hybrid Bearing:Combines ceramic balls with steel races to reduce centrifugal loading by 60% versus all-steel equivalents.
Air Bearing commands the highest price tier, with Magnetic Bearing expanding most quickly in semiconductor-grade applications.
Application:
Volume concentration tracks aerospace component miniaturization and medical device machining, where duty cycle profiles favor ceramic bearing investments over belt-drive alternatives.
- CNC Machining:Five-axis centers integrate motorized spindles for complex contouring of turbine blade roots and structural brackets. Stuttgart and Munich machine tool clusters anchor European procurement, with Bangalore and Hyderabad aerospace suppliers creating white space for localized technical support.
- Grinding:Surface and cylindrical grinding demand the highest precision tiers, pulling magnetic bearing architectures into semiconductor and optical applications. ISO 230-7 runout certification extends delivery lead times by 8-14 weeks for these specifications.
- Milling:Roughing and finishing operations span the full technology spectrum from belt-drive to direct-drive configurations.
- Drilling:High-volume holemaking in automotive and general fabrication favors cost-optimized spindle architectures.
- Engraving:Micro-machining applications require speed stability and minimal runout for fine detail reproduction.
CNC Machining absorbs the largest share of spindle volume, with Grinding gaining share fastest on semiconductor capital expansion.
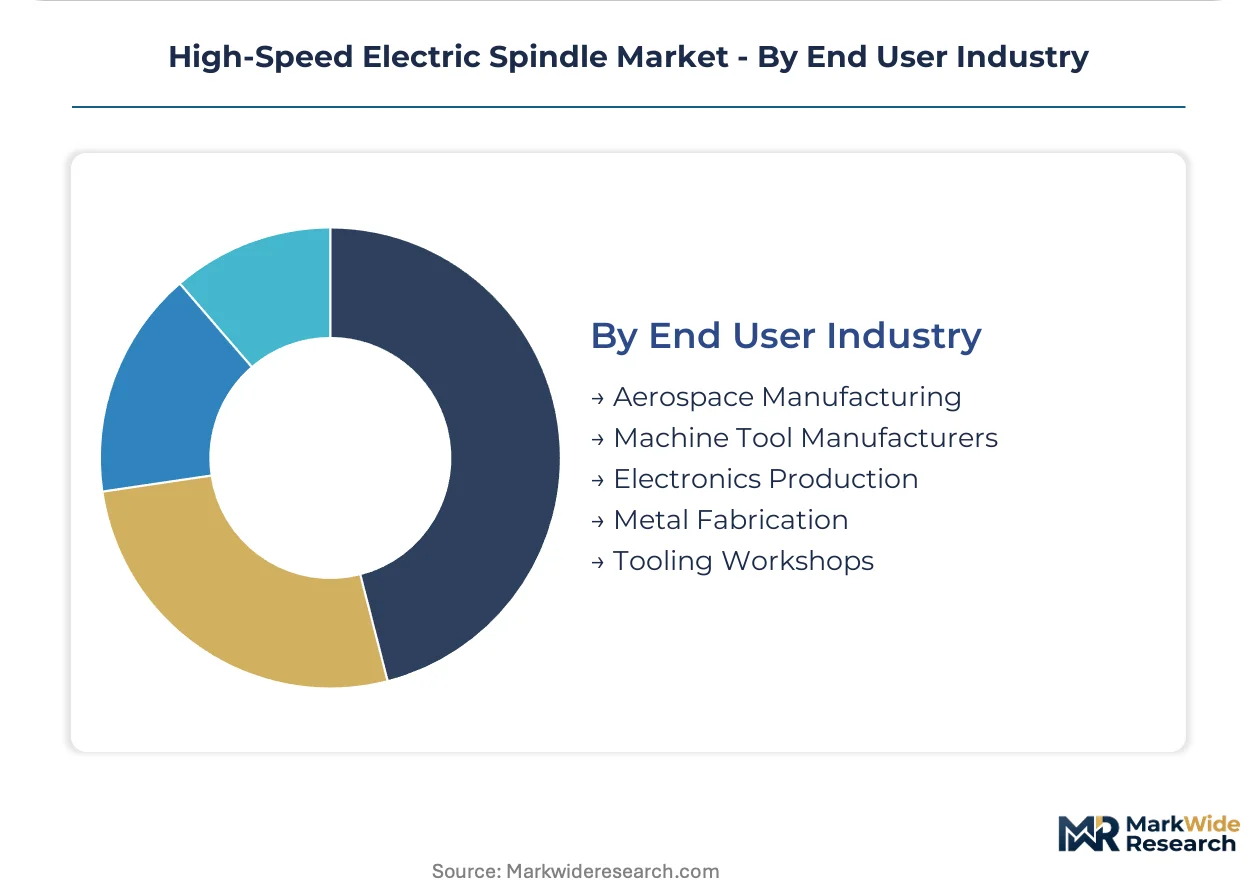
End User Industry:
Customer procurement maturity separates aerospace and electronics buyers with predictive maintenance programs from metal fabrication shops treating spindles as consumable precision assets.
- Aerospace Manufacturing:Turbine blade root machining and structural bracket fabrication demand spindle speeds above 40,000 RPM with sub-micron repeatability. EMA medical device regulations and CE machinery directives constrain suppliers to validated vibration profiles and documented failure modes.
- Electronics Production:Semiconductor wafer dicing and lithium-ion battery electrode slitting require 80,000+ RPM air-bearing spindles. FCC electromagnetic compatibility standards and OSHA machine guarding requirements shape North American design, mandating shielding and interlock architectures.
- Machine Tool Manufacturers:OEM integration of compact, thermally stable motorized units reduces transmission losses and improves surface finish predictability.
- Metal Fabrication:General machining shops prioritize capital efficiency and rapid service turnaround over absolute precision specifications.
- Tooling Workshops:Specialized regrinding and recoating operations require spindle stability for cutting tool edge preparation.
Aerospace Manufacturing leads procurement volume, with Electronics Production showing the steepest expansion trajectory on battery and semiconductor capacity builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Munich machine tool clusters anchor European procurement for high-speed electric spindles, while Asian manufacturing hubs and North American aerospace corridors shape complementary demand centers.
Germany
Airbus structural bracket programs and turbine blade root machining pull motorized spindle configurations into five-axis machining centers. The EU F-Gas Regulation eliminates oil-mist cooling systems, favoring minimal-lubrication ceramic bearing designs. Stuttgart and Munich clusters host machine tool builders specifying 25% higher operating speeds through silicon nitride ball adoption.
United States
FAA aerospace certification requirements and commercial aircraft backlog drive demand for spindles exceeding 40,000 RPM with sub-micron repeatability. FCC electromagnetic compatibility standards and OSHA machine guarding requirements mandate shielding and interlock architectures. Pacific Northwest and Southeast aerospace supplier parks concentrate precision component fabrication capacity.
China
Neodymium supply concentration in domestic refining facilities supports permanent magnet motor production for motorized spindle architectures. GB standards and MIIT industrial equipment mandates shape local certification requirements. Yangtze River Delta machine tool manufacturers integrate compact, thermally stable units to reduce transmission losses.
Japan
Semiconductor equipment manufacturers specify platform-compatible spindle families sharing control electronics across grinding and dicing applications. METI industrial technology roadmaps prioritize energy-efficient designs. Nagoya and Osaka precision manufacturing clusters anchor demand for nanometer-level stability in silicon wafer processing.
South Korea
Battery electrode slitting operations for lithium-ion cell manufacturing require 80,000+ RPM air-bearing spindles for precision foil cutting. MFDS medical device regulations and semiconductor capital expansion programs accelerate procurement. Seoul Capital Area equipment manufacturers extend magnetic bearing expertise into energy storage supply chains.
High-Speed Electric Spindle Market Competitive Landscape
Global majors compete with regional champions across bearing technology specialization and geographic service reach. The vendor base separates into three tiers: integrated machine tool OEMs with captive spindle production, specialized spindle builders with vertically controlled manufacturing, and precision bearing suppliers extending into finished spindle assemblies. Strategic moves concentrate on ceramic bearing supply chain control and magnetic levitation engineering partnerships.
Within the premium-tier vector, FISCHER Spindle and GMN Paul Müller Industrie occupy positions defined by Swiss and German precision manufacturing heritage. NSK represents the bearing-to-spindle integration archetype, leveraging ceramic supply chain assets across Asian machine tool markets. Japanese specialists including NAKANISHI and IBAG exemplify the compact high-speed configuration segment serving semiconductor and medical device applications.
| Leading Market Players |
|---|
| NAKANISHI |
| NSK |
| FISCHER Spindle |
| SETCO |
| POSA SPINDLE |
| GMN Paul Müller Industrie |
| IBAG |
| Kenturn |
| HSD SpA |
| Others |
Pricing and Supply Chain Analysis
Captive ceramic bearing production in Germany and Japan anchors premium spindle architectures, concentrating pricing power with vertically integrated builders who control silicon nitride ball supply chains. This integration insulates premium tiers from rare earth volatility while exposing mid-market belt-drive suppliers to neodymium cost pass-through pressures.
Pricing Analysis
Neodymium cost pass-through from Chinese refining facilities compresses margins on permanent magnet motorized spindles, forcing price adjustments across mid-tier configurations. Pricing stratifies across magnetic bearing premium, ceramic hybrid standard, and belt-drive economy tiers, with CE certification and ISO 230-7 validation adding measurable premiums. Price erosion runs through belt-drive architectures as automotive suppliers treat spindles as consumable precision assets with shortened replacement cycles. Machine tool OEMs show lowest price sensitivity for semiconductor-grade magnetic bearing units, while metal fabrication shops drive hard bargaining on standard HSK configurations.
Supply Chain Analysis
Refurbishment flows from Japanese automotive suppliers now feed secondary markets in Southeast Asia, extending spindle service life through specialized rebuilders who displace OEM aftermarket programs. Manufacturing concentrates in Germany, Japan, and China, with Stuttgart and Munich clusters hosting machine tool builders, Nagoya and Osaka anchoring semiconductor equipment integration, and Yangtze River Delta producers scaling motorized spindle output. Silicon nitride balls, rare earth permanent magnets, and precision-machined housings constitute critical input dependencies. Single-source vulnerability in Chinese neodymium refining exposes producers to export quota uncertainty. Distribution runs through machine tool OEM captive channels, specialized spindle builders, and emerging independent service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-speed electric spindle market compounds steadily as aerospace component miniaturization and F-Gas Regulation compliance create durable replacement demand across European and Asian manufacturing bases.
For Market Incumbents: Hedge against magnetic bearing control engineering scarcity by securing partnerships with Swiss and German university-industry clusters before competitors lock in rotor dynamics expertise. Deepen backward integration into ceramic bearing supply chains to defend margin position against NSK's Asian market expansion. Prioritize CE machinery directive pre-certification to compress delivery timelines for semiconductor-grade spindles. For New Entrants and Emerging Players: Solid lubricant film technology for sealed-for-life ceramic bearing units offers entry into EU Green Deal subsidy flows without competing head-to-head against FISCHER Spindle's precision positioning. Target Bangalore and Hyderabad aerospace machining clusters with localized technical support partnerships, exploiting the white space in Indian spindle service infrastructure. Pursue battery electrode slitting applications as the go-to-market angle, extending semiconductor-grade magnetic bearing expertise into lithium-ion manufacturing equipment. For Investors and Strategic Acquirers: Roll-up economics work for specialized spindle rebuilders with regional inventory positioning because Japanese automotive suppliers have already normalized treating spindles as consumable precision assets with predictable replacement cycles. The 5-10 year viability window favors platform-compatible spindle families sharing control electronics across grinding and dicing applications. Monitor F-Gas Regulation enforcement intensity as the inflection signal—accelerated coolant elimination mandates would accelerate replacement cycles in aging European machine parks.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Bearing Supply Chain Integration | Backward control over silicon nitride ball sourcing insulates premium tier pricing from rare earth volatility. |
| Magnetic Levitation Engineering Partnership | Swiss and German university alliances secure scarce mechatronics expertise for semiconductor-grade spindles. |
| Localized Technical Support Expansion | Indian aerospace clusters in Bangalore and Hyderabad remain underserved by existing service infrastructure. |
| Platform-Compatible Spindle Family Development | South Korean and Taiwanese semiconductor equipment manufacturers now specify shared control electronics. |
| EU Green Deal Retrofit Qualification | Energy-efficient spindle designs capture national recovery fund allocations in Italy and Spain. |
Research Methodology
Multiple input streams—primary interviews with machine tool OEM procurement teams, spindle builder engineering directors, and aftermarket service heads; secondary validation through customs/trade data, SEC filings of listed machine tool manufacturers, and CE machinery directive certification databases—were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Data-stream reconciliation anchored volume and value outputs across bearing technology, drive configuration, and end-use industry segmentation dimensions. CAGRs were derived from installed base depreciation modeling and replacement cycle acceleration factors. Aerospace component miniaturization requirements and F-Gas Regulation phase-down timelines served as industry-specific demand drivers throughout the projection horizon.
The model holds under stable aerospace capital expenditure and continued F-Gas Regulation enforcement; deviation in neodymium export quota policy or magnetic bearing control engineering availability would shift replacement cycle assumptions. Practitioners should monitor Chinese rare earth processing regulations and Swiss-German university partnership formation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Digital Load Indicator Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market