
 Dust Extraction System Market | 2026-2036
Dust Extraction System Market Size, Share, and Industry Trends Forecast 2026-2036
Dust Extraction System Market Analysis
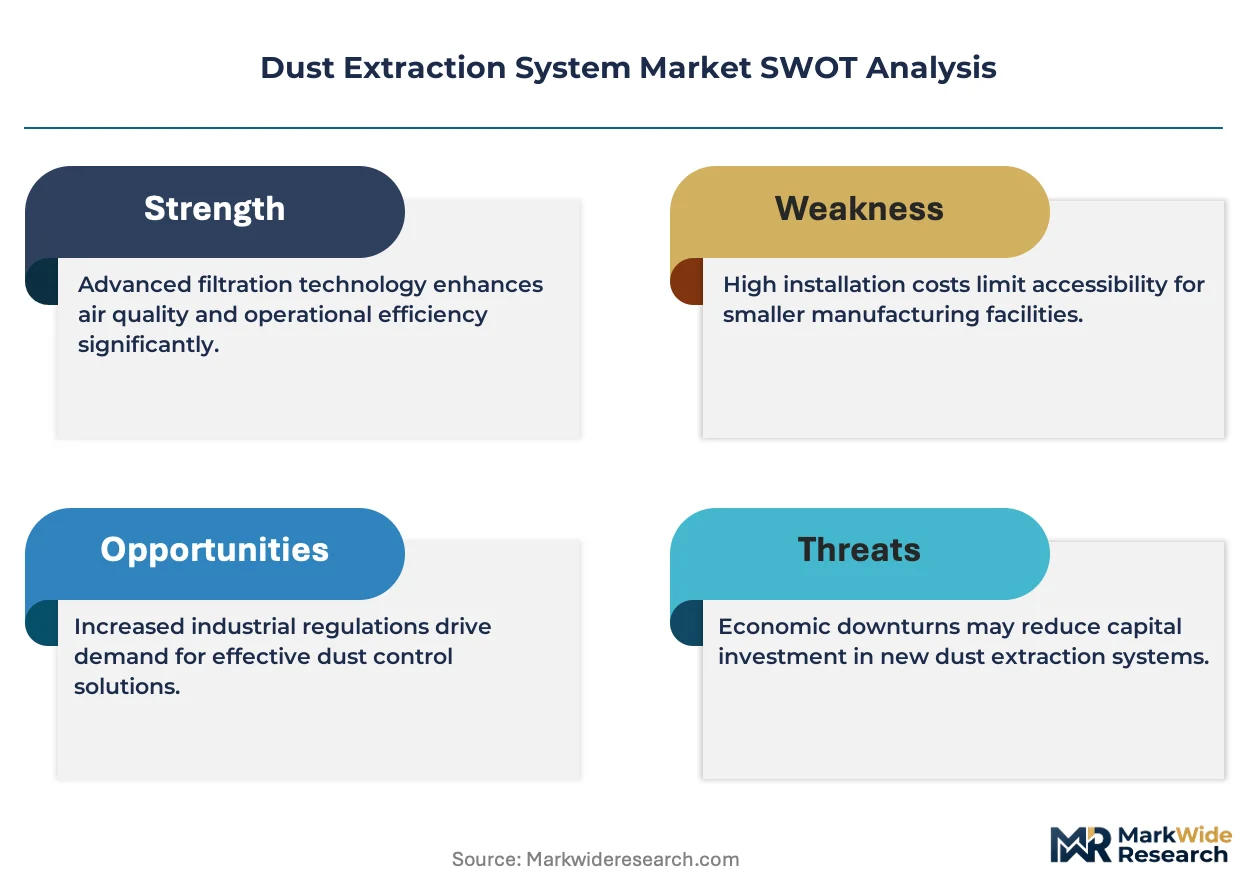
Premium specification-grade dust extraction systems is rebalancing away from commodity portable units as pharmaceutical and semiconductor cleanrooms demand validated HEPA performance with documented compliance trails. Donaldson Company, Inc. leverages its filtration science depth to anchor high-margin replacement cartridge streams. Bosch competes through integrated tool-extractor pairing that locks in brand ecosystems across construction and woodworking channels. Nederman specializes in centralized system architecture for metalworking facilities requiring source-capture at multiple machining stations.
A dust extraction system is an engineered air quality apparatus that captures, conveys, and separates particulate matter from industrial process air streams, typically achieving filtration efficiencies from five-micron pre-separation down to sub-micron HEPA-grade retention depending on application toxicity. The primary purpose is worker respiratory protection, equipment longevity, and process contamination control across manufacturing environments. Centralized systems command the largest installed base due to ducting economies and multi-point capture scalability, while portable extractors represent the fastest replacement cycle segment driven by construction mobility requirements. Electrostatic precipitator technology leads in heavy particulate load environments such as metalworking, though HEPA filtration dominates where toxic fine dust or pharmaceutical cross-contamination risks govern specification.
OSHA enforces permissible exposure limits that mandate engineering controls including local exhaust ventilation when silica or metal fume concentrations exceed threshold values, directly shaping system sizing and capture velocity requirements. The EPA National Emission Standards for Hazardous Air Pollutants constrain particulate discharge from industrial processes, pushing facilities toward high-efficiency bag filter and cartridge configurations with documented emission testing. Stakeholders must monitor evolving MSHA mine safety standards and state-level indoor air quality amendments that could extend extraction mandates to previously unregulated workshop categories.
Market Dynamics
OSHA's tightening permissible exposure limits for respirable crystalline silica are forcing metalworking and construction facilities to upgrade from commodity portable units to engineered local exhaust ventilation systems with documented capture velocity compliance.
Growth Catalysts
- OSHA Silica Rule Enforcement:Metal fabrication shops across the United States must install source-capture systems meeting specified airflow rates, converting compliance penalties into capital equipment procurement.
- Pharmaceutical Cleanroom Expansion:Sterile injectable manufacturing facilities require validated HEPA extraction with continuous monitoring to prevent cross-contamination between batch operations.
- Electrostatic Precipitator Advances:Heavy particulate load environments in steel processing now achieve sub-micron retention without filter media replacement, reducing lifecycle operating costs.
Market Restraints
- Stainless Steel Ducting Costs:Corrosion-resistant material specifications for chemical process industries have doubled raw material input costs versus galvanized alternatives.
- Filter Media Supply Concentration:Pleated synthetic cartridge production clusters in Germany and Japan, creating lead time vulnerability for North American system integrators.
- Wet Scrubber Water Treatment Burden:Slurry disposal regulations impose secondary wastewater infrastructure requirements that offset initial equipment savings.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO-mandated Schedule M compliance for domestic drug production is driving first-time extraction system installations in Ahmedabad and Hyderabad clusters.
- Battery Cell Dry Room Integration:Lithium-ion electrode coating operations require ultra-low humidity environments where dust extraction must operate without moisture introduction.
- CE Marking Mutual Recognition:European-certified systems gain accelerated approval pathways in Middle Eastern markets through harmonized technical standards.
Industry Challenges
- Commissioning Documentation Burden:FDA validation protocols for pharmaceutical installations require IQ/OQ/PQ documentation packages extending project timelines.
- Legacy Ductwork Retrofit Complexity:Existing facilities built before modern capture velocity standards face spatial constraints that prevent optimal hood placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust Extraction System Market |
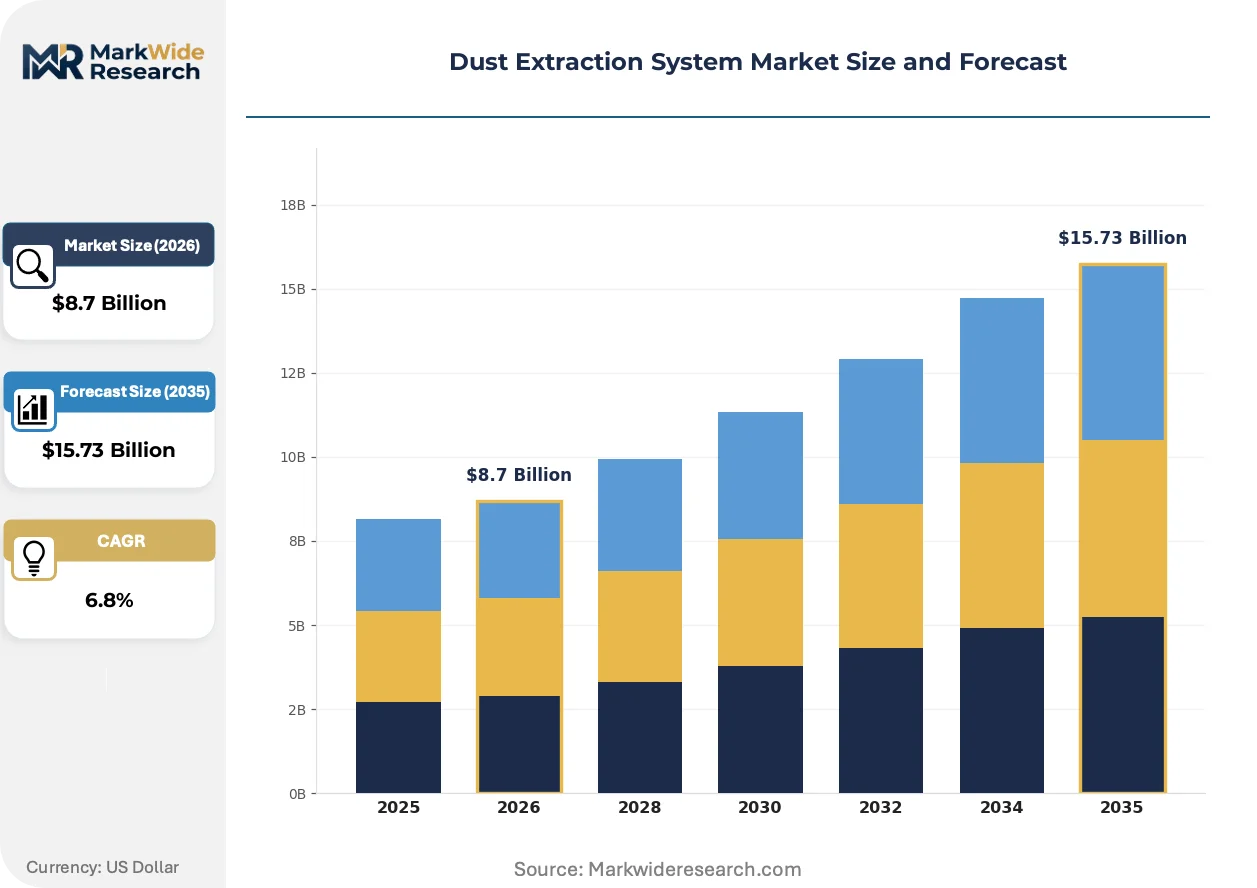
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Extractors, Centralized Systems, Wall-Mounted Units, Bench-Top Systems Application: Woodworking, Metalworking, Construction, Pharmaceuticals End User: Manufacturing Facilities, Construction Sites, Laboratories, Automotive Technology: HEPA Filters, Cyclone Separators, Electrostatic Precipitators, Bag Filters |
| Companies Covered | Bosch, Farr Air Pollution Control, Donaldson Company, Inc., MSGC Group Co., Ltd., Sly Inc., Camfil AB, Nederman, Schenck Process Holding GmbH, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust Extraction System Market Emerging Trajectories
Intelligent filtration monitoring and predictive maintenance architectures are displacing scheduled replacement intervals, while regulatory documentation requirements reshape system specification criteria across hazardous material handling sectors.
Plug-and-play cartridge filtration modules with integrated differential pressure sensors and automated pulse-cleaning cycles are modularizing system architecture. Pharmaceutical manufacturers in Switzerland and Germany adopt these configurations to minimize production downtime during media changeouts. The shift compresses maintenance windows from full shift interruptions to sub-hour exchanges.
REACH authorization procedures for hazardous substance containment are extending extraction system lifecycles in European chemical processing. Facilities must demonstrate continuous engineering control effectiveness rather than relying on personal protective equipment substitution. Metal finishing operations in Belgium and the Netherlands face the most stringent documentation requirements.
Buyer consolidation among contract manufacturing organizations is concentrating procurement authority at fewer decision points. Tier-one pharmaceutical services providers now specify unified extraction platforms across multi-site networks, displacing fragmented local vendor relationships. This pattern is most visible in Singapore and Ireland, where global CMOs cluster manufacturing capacity.
Dust Extraction System Market Segmentation
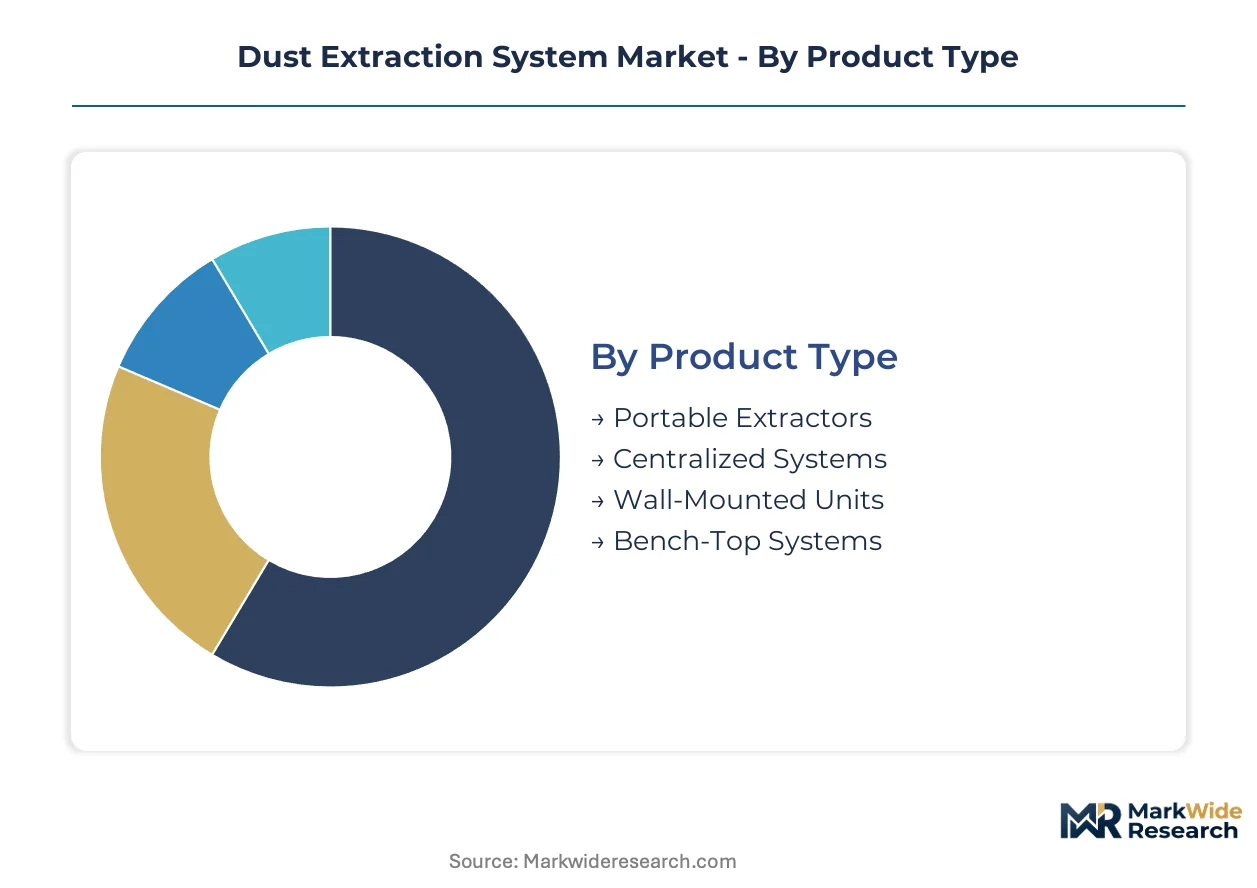
Dust extraction system procurement decisions split sharply between validated cleanroom infrastructure and commodity construction mobility. Specification-grade segments carry FDA, OSHA, or CE marking burdens that reshape supplier qualification timelines and lifecycle documentation requirements.
Product Type:
Certification intensity varies dramatically: pharmaceutical installations demand IQ/OQ/PQ validation packages, while construction portability prioritizes OSHA silica compliance documentation.
- Portable Extractors:Self-contained units with integrated filtration and mobility chassis for construction site deployment. Demand concentrates in German woodworking clusters where Bosch tool-extractor pairing locks brand ecosystems. OSHA silica rule enforcement converts rental fleet operators toward specification-grade pulse-cleaning models.
- Centralized Systems:Ducted architecture serving multiple capture points through common filtration banks. Metalworking facilities in Stuttgart and Munich specify these for machining station networks. Ducting economies drive installed base dominance despite higher upfront capital.
- Wall-Mounted Units:Fixed-position extractors for localized bench operations with minimal footprint requirements.
- Bench-Top Systems:Compact filtration for laboratory and precision assembly environments with sub-micron retention needs.
Leading the category by volume: Centralized Systems. Growing fastest: Portable Extractors.
Application:
Regulatory thresholds determine specification grade: pharmaceutical cleanrooms require continuous HEPA monitoring, while construction faces episodic silica exposure limits.
- Pharmaceuticals:Validated extraction for sterile injectable manufacturing with batch-to-batch contamination prevention. Swiss and German facilities adopt plug-and-play cartridge modules to compress maintenance windows. FDA validation protocols extend project timelines through mandatory documentation packages.
- Metalworking:Source-capture systems for welding fume and grinding dust with specified airflow rates. US fabrication shops convert compliance penalties into engineered local exhaust ventilation procurement. Electrostatic precipitator advances reduce filter replacement burdens in heavy load environments.
- Woodworking:Sawdust collection for milling and sanding operations with five-micron pre-separation baseline.
- Construction:Mobile silica control for concrete cutting and masonry demolition with rapid deployment requirements.
Margin concentration: Pharmaceuticals. Volume concentration: Metalworking.
End User:
Procurement authority centralizes differently: contract manufacturing organizations consolidate multi-site specifications, while automotive maintains fragmented plant-level decision making.
- Manufacturing Facilities:Permanent installation base across precision machining and assembly operations. Tier-one pharmaceutical services providers in Singapore and Ireland specify unified extraction platforms across networks. Buyer consolidation displaces fragmented local vendor relationships.
- Automotive:Paint booth and body shop ventilation with explosion-rated electrical specifications. Battery cell dry room integration creates ultra-low humidity extraction requirements for lithium-ion electrode coating.
- Construction Sites:Rental fleet and contractor-owned mobility for silica compliance.
- Laboratories:Research and quality control environments with cross-contamination prevention protocols.
Specification-grade investment: Manufacturing Facilities. Replacement cycle velocity: Construction Sites.
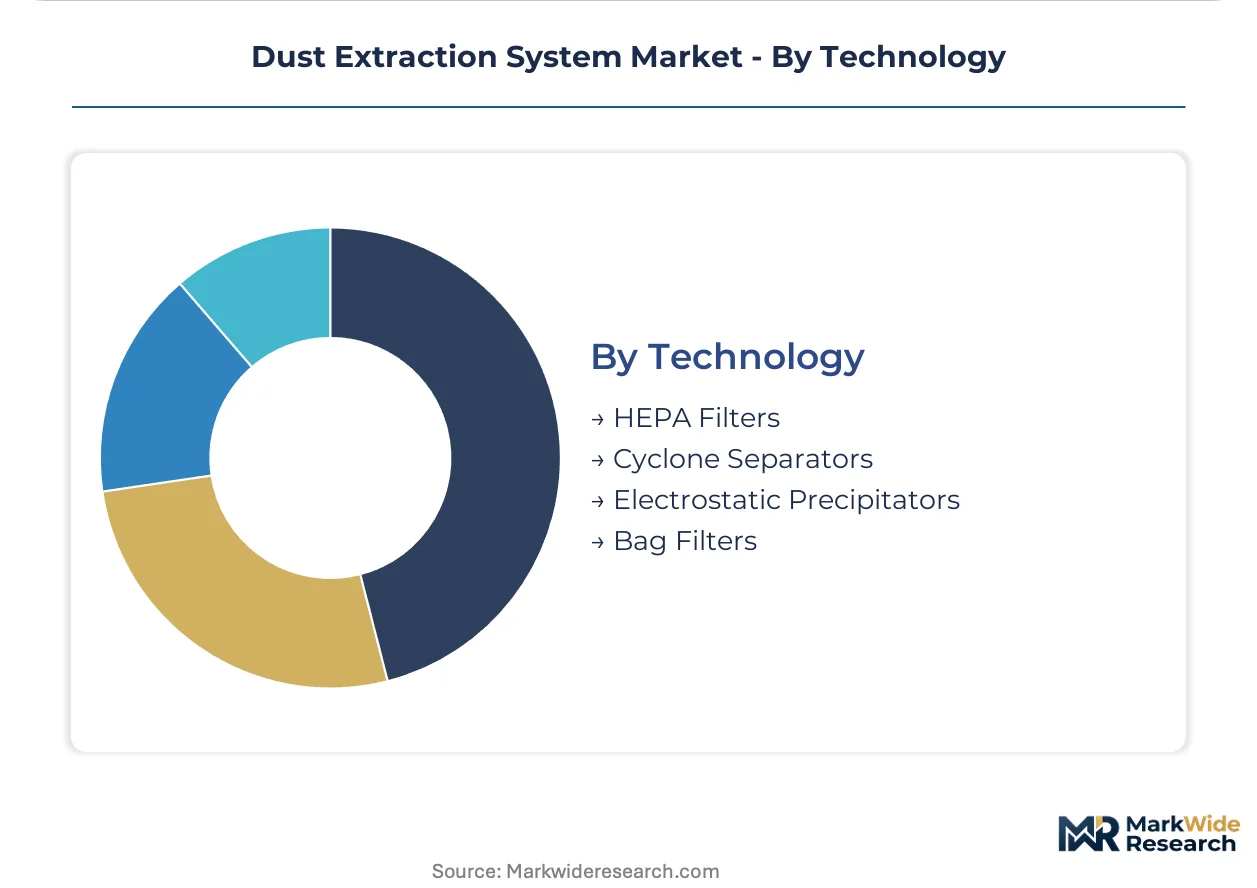
Technology:
Retention efficiency and maintenance burden trade off: HEPA dominates toxic fine dust, while electrostatic precipitation eliminates media replacement in heavy particulate loads.
- HEPA Filters:Sub-micron retention media for pharmaceutical cross-contamination and toxic dust environments. German and Japanese cartridge production clusters create lead time vulnerability for North American integrators. Pleated synthetic configurations with automated pulse-cleaning modularize system architecture.
- Electrostatic Precipitators:Ionization-based separation achieving fine retention without filter media replacement. Steel processing facilities adopt these for lifecycle operating cost reduction. Heavy particulate load performance anchors technology leadership.
- Cyclone Separators:Centrifugal pre-separation for coarse dust with minimal moving parts.
- Bag Filters:Woven media configurations for moderate load environments with established replacement protocols.
Highest specification burden: HEPA Filters. Lowest lifecycle cost: Electrostatic Precipitators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision manufacturing demand for specification-grade extraction systems, with machining clusters driving ducted centralized installations across German metalworking corridors.
United States
Metal fabrication shops convert OSHA silica compliance penalties into engineered local exhaust ventilation procurement. The EPA National Emission Standards for Hazardous Air Pollutants constrain particulate discharge from industrial processes. Houston and Detroit manufacturing corridors specify source-capture systems with documented capture velocity compliance.
Germany
Pharmaceutical cleanroom operations in Basel-adjacent Baden-Württemberg expand validated HEPA extraction infrastructure. REACH authorization procedures for hazardous substance containment extend system lifecycles through continuous engineering control mandates. Munich precision manufacturing clusters drive specification-grade cartridge procurement with automated pulse-cleaning configurations.
China
Battery cell dry room integration for lithium-ion electrode coating creates ultra-low humidity extraction requirements. GB standards and MIIT industrial air quality directives tighten particulate discharge thresholds for steel processing facilities. Yangtze River Delta manufacturing zones adopt electrostatic precipitator technology to reduce filter replacement burdens in heavy load environments.
India
CDSCO-mandated Schedule M compliance for domestic drug production drives first-time extraction system installations. Ahmedabad and Hyderabad pharmaceutical clusters require validated HEPA performance with continuous monitoring for batch-to-batch contamination prevention. Contract manufacturing organization consolidation concentrates procurement authority at fewer decision points across multi-site networks.
Switzerland
Sterile injectable manufacturing facilities adopt plug-and-play cartridge modules to compress maintenance windows from full shift interruptions to sub-hour exchanges. Swissmedic validation protocols extend project timelines through mandatory IQ/OQ/PQ documentation packages. Basel pharmaceutical services providers specify unified extraction platforms across global manufacturing networks.
Dust Extraction System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity, with validated pharmaceutical-grade systems commanding structural price premiums over construction-portable alternatives. The vendor base stratifies between filtration science specialists, integrated tool-extractor pairing providers, and centralized system architects. Three archetypes dominate: cartridge replacement stream anchors, brand ecosystem integrators, and multi-point capture scalability specialists. Competitive moves concentrate on M&A for geographic footprint expansion and strategic partnerships for regulatory documentation bundling.
Within the filtration science tier, Donaldson Company, Inc. and Camfil AB exemplify cartridge-based retention technology positioning. Bosch occupies a position as an integrated tool-extractor pairing provider leveraging brand ecosystem lock-in across construction and woodworking channels. Nederman anchors the centralized system architecture segment for metalworking facilities requiring source-capture at multiple machining stations.
| Leading Market Players |
|---|
| Bosch |
| Farr Air Pollution Control |
| Donaldson Company, Inc. |
| MSGC Group Co., Ltd. |
| Sly Inc. |
| Camfil AB |
| Nederman |
| Schenck Process Holding GmbH |
| 3M |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between validated pharmaceutical systems and commodity construction units manifests in pricing power concentration at German and Swiss filtration specialists, while supply chain configurations bifurcate between cartridge media clusters in Germany and Japan versus galvanized ducting networks serving price-sensitive metalworking segments.
Pricing Analysis
Value-based pricing anchors on documented compliance outcomes, with pharmaceutical buyers paying premiums for validated HEPA performance tied to batch yield protection and regulatory audit passage. Price differentiation rests on certification intensity (FDA/CE tier) and after-sales cartridge replacement bundling. Cost compression in portable construction segments intensifies as rental fleet operators consolidate procurement, while specification-grade buyers show minimal price sensitivity given penalty exposure from OSHA silica violations.
Supply Chain Analysis
Warehouse-distribution layers concentrate replacement cartridge inventory at regional hubs in Stuttgart and Munich to serve precision manufacturing clusters. Geographic supply concentration centers on Germany and Japan for pleated synthetic media, with China dominating galvanized ducting fabrication. Raw material dependencies span stainless steel for chemical process specifications, synthetic filter media, and corrosion-resistant coatings. Single-source vulnerability in specialized HEPA membrane production elevates risk exposure. Distribution runs through authorized system integrators for specification-grade installations, contrasting with direct-to-contractor channels for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent filtration monitoring architectures are displacing scheduled maintenance protocols, with predictive sensor networks replacing legacy interval-based cartridge replacement across pharmaceutical and semiconductor cleanrooms.
For Market Incumbents: Deepen cartridge replacement stream lock-in through predictive maintenance platform subscriptions that embed sensor hardware into long-term service contracts. Invest in backward integration into pleated synthetic media production to offset supply concentration risk from German and Japanese suppliers. Defend against integrated tool-extractor pairing competitors by certifying multi-brand compatibility.
For New Entrants and Emerging Players: CDSCO Schedule M compliance in India opens a window for specification-grade system installations in Ahmedabad and Hyderabad pharmaceutical clusters lacking established vendor relationships. Target battery cell dry room integration for lithium-ion electrode coating as the most penetrable segment, where ultra-low humidity extraction requirements create technology differentiation opportunities. Pursue CE marking mutual recognition pathways to accelerate Middle Eastern market entry.
For Investors and Strategic Acquirers: Re-rating potential sits with filtration science specialists given pharmaceutical cleanroom expansion and tightening OSHA silica enforcement. Long-term viability favors cartridge-based retention technology providers over commodity portable manufacturers facing margin compression. Watch FDA validation protocol complexity as an inflection signal favoring incumbents with established documentation capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media Production | German and Japanese cartridge supply concentration creates captive sourcing advantages for system integrators. |
| Predictive Maintenance Platform Launch | Intelligent sensor networks displace scheduled replacement intervals in Swiss pharmaceutical facilities. |
| CE Marking Mutual Recognition Expansion | Harmonized technical standards accelerate approval pathways in Saudi and UAE industrial markets. |
| Battery Cell Dry Room System Development | Ultra-low humidity extraction addresses lithium-ion electrode coating requirements in Yangtze River Delta zones. |
| Pharmaceutical Validation Documentation Bundling | IQ/OQ/PQ packages extend project timelines and lock in recurring compliance service revenue. |
Methodological Framework
Document review covered OSHA enforcement records, EPA emission standards filings, FDA validation guidance documents, and REACH authorization procedures, complemented by interviews with plant engineers at metalworking facilities, pharmaceutical manufacturing directors, aftermarket service heads at system integrators, and procurement leads at contract manufacturing organizations. Secondary sources included customs trade data for filtration equipment, SEC 10-K disclosures from listed component suppliers, and industrial air quality directive filings. Bottom-up installation data triangulated against top-down market sizing from regulatory compliance mandates.
Cross-referencing historical enforcement patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (portable, centralized, wall-mounted, bench-top), application (pharmaceutical, metalworking, woodworking, construction), technology (HEPA, electrostatic precipitator, cyclone, bag filter), and end user (manufacturing facilities, automotive, construction sites, laboratories). CAGRs derived from regulatory compliance-driven replacement cycles and capacity expansion announcements. Industry-specific inputs encompassed OSHA silica rule enforcement timelines and pharmaceutical cleanroom construction permits.
The model assumes a particular technology adoption path; alternative pathways for electrostatic precipitator advances in heavy particulate environments would alter the outlook for filter media replacement demand. Forecasts reflect stated assumptions regarding regulatory enforcement intensity and raw material supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Global Dicing Blades Market