
 TIG Torch Market | 2026-2036
TIG Torch Market Size, Share, and Industry Trends Forecast 2026-2036
TIG Torch Market Analytics
The gap between premium water-cooled systems and commodity air-cooled torches is expanding, with the former commanding higher margins due to precision thermal management requirements in automated welding cells. Lincoln Electric Holdings leverages its vertical integration into copper conductor manufacturing to sustain cost advantages in high-amperage torch lines. Fronius International GmbH differentiates through digital connectivity features that anchor its position in European aerospace supply chains.
A TIG torch is a manually or robotically operated welding tool that channels inert shielding gas—typically argon or helium—around a non-consumable tungsten electrode to create contamination-free fusion joints; critical specifications include maximum amperage rating (ranging from 150A for light-duty units to over 500A for heavy industrial models), torch body angle ergonomics, and gas lens or collet body configuration for flow laminarity. Water-cooled product types lead in high-duty-cycle industrial environments where thermal overload risks degrade electrode stability, while pulse technology variants represent the fastest-growing segment as manufacturers seek reduced heat-affected zones in thin-wall stainless and aluminum applications. Metal fabrication applications generate the largest volume base, though aerospace applications concentrate the highest margin pools due to certification-driven procurement standards.
FDA oversight of medical device welding equipment and EPA emissions standards for hexavalent chromium exposure shape product safety and workplace ventilation requirements in US manufacturing facilities. CE marking under the EU Machinery Directive and REACH substance restrictions on tungsten electrode coatings govern market access across European member states. Stakeholders must monitor evolving ISO 4063 welding process classification standards and regional carbon border adjustment mechanisms that could reshape torch sourcing decisions across integrated supply chains.
Market Dynamics
EU Green Deal industrial decarbonization mandates are accelerating precision welding investments across aerospace supply chains, compressing procurement cycles for high-amperage water-cooled systems while elevating thermal management specifications as a primary vendor selection criterion.
Growth Catalysts
- EU Green Deal mandates:Aerospace manufacturers in Germany and France face binding decarbonization targets that require precision TIG processes for lightweight alloy fabrication, driving specification upgrades across supplier tiers.
- Robotic TIG integration:Japanese automotive supplier clusters around Nagoya and Toyota City are deploying automated welding cells that demand water-cooled torch architectures with integrated digital feedback loops.
- Pulse technology advancement:Reduced heat-affected zone requirements in thin-wall stainless and aluminum applications are displacing conventional DC welding in medical device and semiconductor equipment fabrication.
Market Restraints
- Copper conductor volatility:Raw material price swings for high-purity copper directly compress margins on high-amperage torch lines, forcing manufacturers to absorb costs or risk volume loss.
- Tungsten supply concentration:Rare earth processing dependencies in limited geographies create electrode coating material bottlenecks that disrupt just-in-time production schedules.
- REACH substance restrictions:ECHA regulatory friction on thoriated and lanthanated electrode formulations forces costly reformulation cycles and regional product line fragmentation.
Strategic Opportunities
- Indian precision manufacturing:BIS certification alignment and PLI scheme incentives for medical device and aerospace component exports create first-mover positioning for water-cooled system providers.
- Digital twin convergence:Integration of torch-mounted sensors with welding data analytics platforms enables predictive maintenance contracts that capture recurring revenue streams.
- CE marking acceleration:EU Machinery Directive compliance automation services represent an adjacent revenue layer for vendors with established Notified Body relationships.
Industry Challenges
- Certified welder scarcity:AWS D17.1 aerospace welding qualification timelines extend 18-24 months, constraining production scaling for defense and commercial aviation contracts.
- Legacy system integration:Retrofit compatibility with existing robotic cells from diverse OEMs demands extensive custom engineering that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TIG Torch Market |
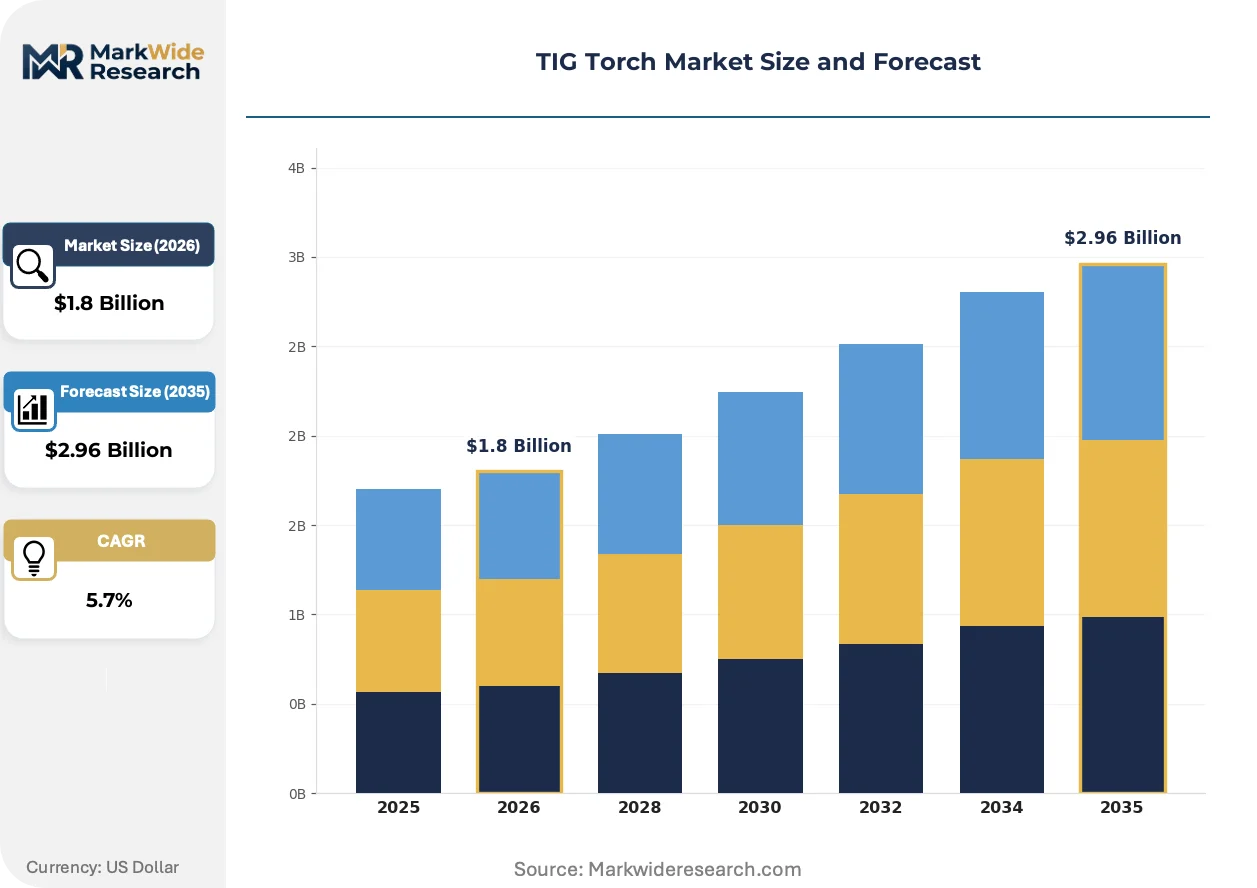
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, High-Frequency, Pulse Application: Metal Fabrication, Automotive, Aerospace, Construction End User: Manufacturers, Welders, Contractors, Hobbyists Technology: Inverter, Transformer, DC, AC |
| Companies Covered | Lincoln Electric Holdings, ESAB Corporation, Illinois Tool Works Inc., Fronius International GmbH, Panasonic Corporation, Miller Electric Manufacturing, Tokin Corporation, EWM AG, Kemppi Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TIG Torch Market Evolving Landscape
Sensor-embedded torch architectures and AI-driven weld parameter optimization are compressing the skill gap between operator experience and output consistency, while regulatory pressure on workplace emissions accelerates ventilation-integrated system designs.
Adaptive arc control systems using real-time current waveform modulation are automating penetration depth management in variable-gap joints. Tier-one automotive suppliers in Stuttgart and Wolfsburg are deploying these systems across battery tray and exhaust component lines. The technology is automating quality assurance steps previously requiring offline radiographic inspection, collapsing throughput times by eliminating rework loops.
EPA hexavalent chromium exposure limits under 29 CFR 1910.1026 are forcing fabrication facilities to specify integrated fume extraction torches or face operational shutdown risks. Metal fabrication shops in Michigan and Ohio are consolidating vendor relationships to secure EPA-compliant system bundles. Water-cooled configurations with laminar gas flow designs are capturing preference share as they simultaneously address thermal overload and airborne particulate capture requirements.
Direct procurement from torch manufacturers is displacing traditional welding distributor intermediaries for high-volume automated cell deployments. Automotive OEMs in Saitama and Toyota City are negotiating frame contracts that bundle hardware, consumables, and predictive maintenance software. This channel compression is most visible in Japanese automotive supplier clusters where robotic TIG integration mandates have eliminated spot-buying flexibility in favor of lifecycle cost agreements.
TIG Torch Market Segmentation
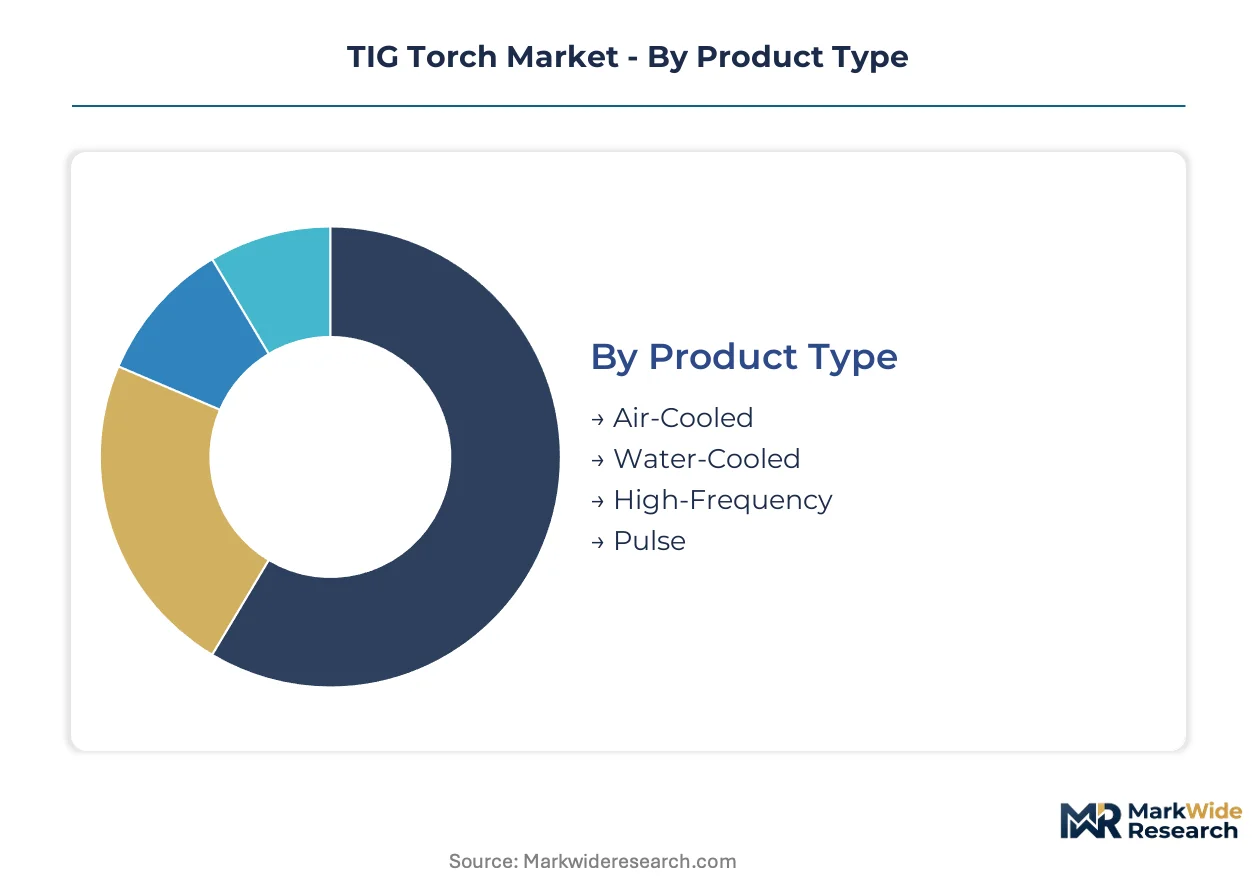
TIG torch procurement decisions hinge on thermal duty cycles and automation compatibility, with certification requirements varying sharply across aerospace, automotive, and medical end-uses. Segmentation reveals where margin pools concentrate versus where volume commoditization pressures dominate vendor economics.
Product Type:
FDA 21 CFR Part 820 quality system requirements govern medical device welding equipment, while EPA hexavalent chromium exposure standards under 29 CFR 1910.1026 mandate fume extraction capabilities in heavy-duty industrial configurations. CE marking under the EU Machinery Directive applies universally, though water-cooled systems face additional pressure vessel compliance scrutiny.
- Air-Cooled:Lightweight torch bodies with passive thermal dissipation through aluminum or brass conductor construction. Metal fabrication shops in Michigan and Ohio specify these for intermittent-duty applications where capital constraints limit water-cooling infrastructure investment.
- Water-Cooled:Closed-loop thermal management architectures enabling continuous operation above 250A without electrode degradation. Japanese automotive supplier clusters around Nagoya and Toyota City deploy these exclusively for robotic TIG cells where thermal stability determines weld consistency.
- High-Frequency:Arc initiation systems using high-voltage, high-frequency spark generation for non-contact starts without tungsten contamination.
- Pulse:Current waveform modulation technology reducing heat-affected zones in thin-wall stainless and aluminum applications.
Leading the category by volume: Air-Cooled. Growing fastest: Pulse.
Application:
Margin structures diverge sharply across these segments, with aerospace procurement cycles extending 18-24 months due to AWS D17.1 qualification requirements while automotive contracts emphasize lifecycle cost optimization.
- Metal Fabrication:General-purpose welding across carbon steel, stainless, and aluminum structures with variable joint configurations. Job shops in Ohio and Pennsylvania drive replacement demand for standard-duty torches with 150-200A ratings.
- Automotive:Battery tray, exhaust component, and chassis fabrication requiring automated cell integration and digital feedback compatibility. Stuttgart and Wolfsburg supplier parks specify adaptive arc control systems for variable-gap penetration management.
- Aerospace:Titanium and nickel superalloy fusion welding with radiographic inspection protocols and full traceability documentation. German and French manufacturers under EU Green Deal mandates upgrade to precision water-cooled systems for lightweight alloy programs.
- Construction:Field welding of structural steel and architectural metalwork with portable power source compatibility.
Volume concentrates in Metal Fabrication. Margin pools peak in Aerospace.
End User:
Procurement authority and technical specification involvement vary dramatically across these user types, dictating whether sales cycles emphasize distributor relationships or direct OEM negotiation.
- Manufacturers:Integrated production facilities with in-house welding engineering and preventive maintenance programs. Saitama automotive OEMs negotiate frame contracts bundling hardware, consumables, and predictive maintenance software.
- Welders:Individual operators or small shops prioritizing ergonomic torch body angles and gas lens configurations for manual dexterity. These users exhibit strong brand loyalty to consumables suppliers with local distributor presence.
- Contractors:Project-based fabrication services with mixed manual and semi-automated equipment portfolios.
- Hobbyists:Entry-level users in maker spaces and vocational training programs with price-sensitive purchasing behavior.
Direct procurement momentum is strongest among Manufacturers. Price sensitivity dominates Hobbyist segment economics.
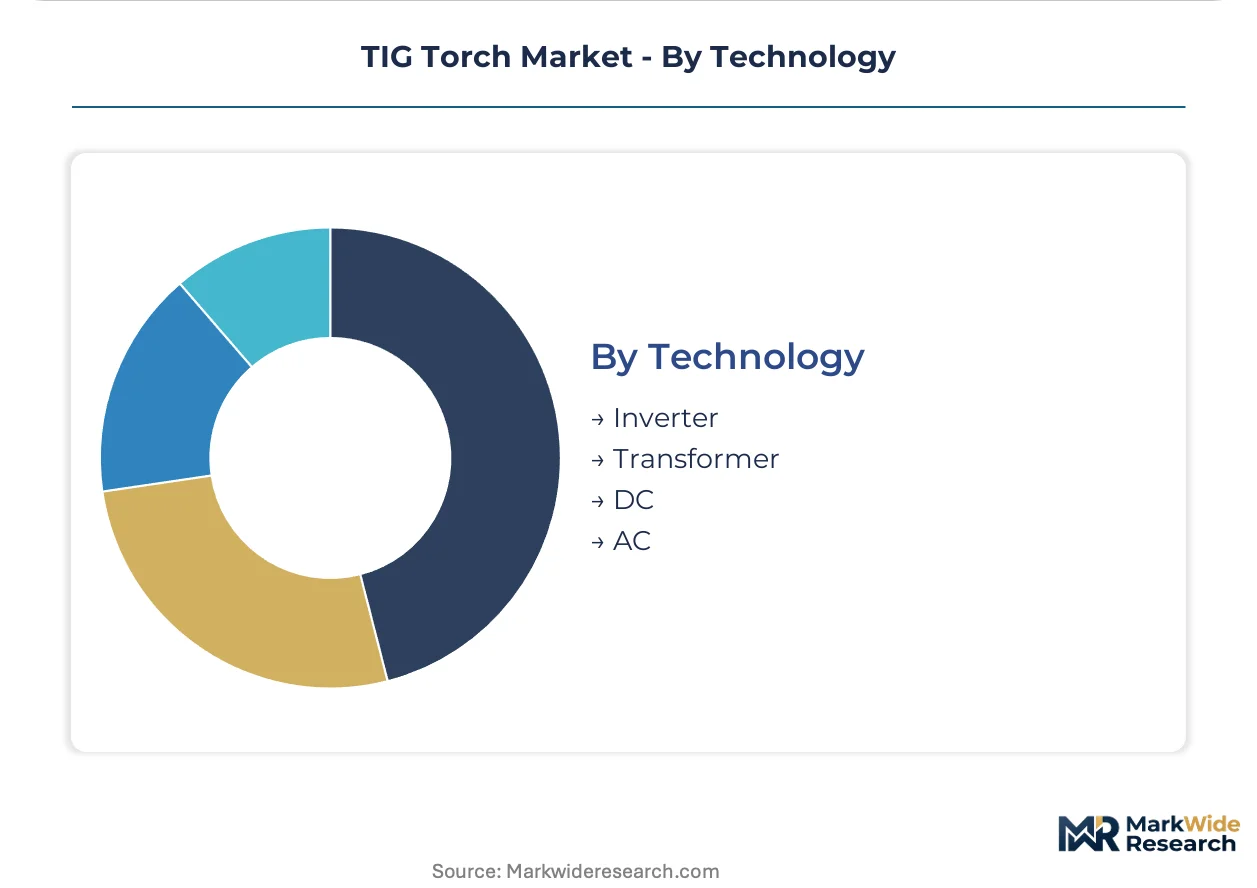
Technology:
Power source architecture determines arc stability characteristics and compatibility with advanced waveform control features, with inverter platforms displacing transformer-based systems in new equipment purchases.
- Inverter:High-frequency switching power electronics enabling precise current control and pulse waveform generation. Semiconductor equipment fabricators specify these for thin-wall stainless applications requiring reduced heat input.
- Transformer:Conventional magnetic core designs with robust field reliability but limited waveform modulation capability. Legacy infrastructure in developing manufacturing bases sustests residual demand for replacement units.
- DC:Direct current output optimized for ferrous metals and straight polarity tungsten electrode operation.
- AC:Alternating current with balanced or adjustable waveform for aluminum and magnesium oxide cleaning action.
Technology transition favors Inverter platforms. AC capability remains essential for non-ferrous specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nagoya anchors the most intensive TIG torch deployment globally, with Toyota City supplier clusters driving water-cooled system specifications for robotic welding cells. Germany and France concentrate aerospace precision welding investments under EU decarbonization mandates. The United States sustains heavy industrial demand through automotive and metal fabrication corridors. India emerges as a precision manufacturing destination with scheme-backed medical device and aerospace export incentives.
United States
Metal fabrication shops in Michigan and Ohio drive replacement demand for 150-200A rated torches, with EPA hexavalent chromium exposure limits under 29 CFR 1910.1026 forcing integrated fume extraction specifications. FDA 21 CFR Part 820 quality system requirements govern medical device welding equipment procurement. Greater Detroit automotive supplier parks specify adaptive arc control systems for battery tray fabrication lines.
Germany
Aerospace manufacturers in Stuttgart and Hamburg face binding EU Green Deal decarbonization targets requiring precision TIG processes for lightweight titanium and nickel superalloy fabrication. CE marking under the EU Machinery Directive applies universally, with additional pressure vessel compliance scrutiny for water-cooled configurations. Bavarian supplier tiers upgrade thermal management specifications as primary vendor selection criteria.
Japan
Automotive supplier clusters around Nagoya and Toyota City deploy water-cooled torch architectures exclusively for robotic TIG cells where thermal stability determines weld consistency. METI industrial automation incentives accelerate digital feedback loop integration. Saitama automotive OEMs negotiate frame contracts bundling hardware, consumables, and predictive maintenance software.
France
Toulouse and Bordeaux aerospace supply chains concentrate the highest margin procurement pools due to AWS D17.1 qualification requirements extending 18-24 months. ECHA REACH substance restrictions on thoriated and lanthanated electrode formulations force costly reformulation cycles. French manufacturers under EU Green Deal mandates upgrade precision water-cooled systems for lightweight alloy programs.
India
BIS certification alignment and PLI scheme incentives for medical device and aerospace component exports create first-mover positioning opportunities for water-cooled system providers. CDSCO medical device regulations shape welding equipment specifications for surgical instrument fabrication. Maharashtra and Gujarat precision manufacturing corridors attract vendor direct investment for localized production.
TIG Torch Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal management sophistication and certification depth, with aerospace-qualified vendors commanding 3-5x pricing multiples over standard fabrication equipment. The vendor base stratifies into three tiers: integrated welding power source manufacturers with captive torch lines, specialized thermal engineering houses focused on high-amperage water-cooled architectures, and regional fabricators serving price-sensitive replacement markets. Dominant competitive moves include backward integration into copper conductor manufacturing and strategic partnerships with robotic cell OEMs for pre-certified integration bundles.
Among North American-diversified industrial conglomerates, Lincoln Electric Holdings and Illinois Tool Works Inc. occupy positions anchoring the integrated power source-and-torch tier. ESAB Corporation exemplifies the transatlantic specialist archetype with European engineering heritage and North American operational scale. Fronius International GmbH represents the premium-tier Austrian-German precision engineering tradition. Panasonic Corporation and Tokin Corporation sit within the Japanese automation-integrated tier serving Toyota City and Nagoya supplier clusters directly.
| Leading Market Players |
|---|
| Lincoln Electric Holdings |
| ESAB Corporation |
| Illinois Tool Works Inc. |
| Fronius International GmbH |
| Panasonic Corporation |
| Miller Electric Manufacturing |
| Tokin Corporation |
| EWM AG |
| Kemppi Oy |
| Others |
Value Network & Pricing Analysis
EU Green Deal industrial decarbonization mandates gate qualified supply for aerospace-grade water-cooled systems while anchoring premium-tier pricing access for vendors with AWS D17.1 certification depth. Buyers in Stuttgart and Hamburg face compressed procurement cycles that elevate thermal management specifications as primary selection criteria, forcing specification upgrades that widen the margin gap between certified and commodity torch lines.
Pricing Analysis
Lifecycle cost-per-weld outcomes anchor value-based pricing for automated cell deployments, with Japanese automotive OEMs in Saitama negotiating frame contracts that bundle hardware, consumables, and predictive maintenance software. Price differentiation rests on certification grade and thermal duty cycle performance, with aerospace-qualified vendors commanding substantial premiums over standard fabrication equipment. Cost compression in air-cooled commodity tiers is intensifying because copper conductor volatility erodes margins on high-amperage lines. Hobbyist and small job-shop segments exhibit the highest price sensitivity, while manufacturers with robotic integration mandates prioritize uptime guarantees over unit cost.
Supply Chain Analysis
AWS D17.1 and CE marking under the EU Machinery Directive gate vendor participation in aerospace and European industrial procurement, concentrating qualified supply among Austrian-German precision engineering houses and Japanese automation-integrated specialists. Manufacturing draws from high-purity copper conductor sources in Germany and Japan, with tungsten electrode coatings dependent on rare earth processing concentrated in limited geographies. Single-source vulnerability for thoriated and lanthanated electrode formulations under REACH substance restrictions disrupts just-in-time production schedules. Distribution runs through direct OEM negotiation for high-volume automated deployments, displacing traditional welding distributor intermediaries in Japanese and German automotive supplier clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over copper conductor manufacturing and tungsten electrode supply chains determines cost position in high-amperage torch lines. Lincoln Electric Holdings exemplifies the upstream lever through backward integration into conductor production.
For Market Incumbents: Anticipate margin compression from commodity air-cooled tiers by accelerating certification depth for aerospace and medical device segments. Defend against emerging Asian specialists by securing Notified Body relationships for CE marking automation services. Prioritize captive supply of high-purity copper conductors to sustain cost advantages when raw material volatility spikes.
For New Entrants and Emerging Players: Capture first-mover positioning in Indian precision manufacturing corridors where BIS certification alignment and PLI scheme incentives for medical device exports create unguarded white space. Target Maharashtra and Gujarat for localized water-cooled system production to bypass import friction. Lead with digital twin convergence offerings that bundle torch-mounted sensors with welding data analytics platforms.
For Investors and Strategic Acquirers: METI industrial automation incentive announcements in Nagoya and Toyota City are the leading indicator that robotic TIG integration mandates will accelerate water-cooled system demand. Long-term viability favors vendors with established robotic cell OEM partnerships for pre-certified integration bundles. Watch for CDSCO medical device regulation expansions in India as the signal that precision welding equipment procurement will shift toward export-certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Conductor Manufacturing | Lincoln Electric Holdings sustains margin defense through captive high-purity conductor supply. |
| Digital Twin Convergence with Predictive Maintenance | Fronius International GmbH captures recurring revenue via welding data analytics platform integration. |
| CE Marking Compliance Automation Services | Established Notified Body relationships unlock adjacent revenue layers for European vendor tiers. |
| Robotic Cell Pre-Certified Integration Bundles | Panasonic Corporation anchors Toyota City supplier relationships through OEM partnership depth. |
| Localized Production in Indian Precision Corridors | BIS alignment and PLI scheme access position vendors for medical device export growth. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with welding engineering directors, robotic cell integration specialists, aerospace procurement managers, and aftermarket service heads. AWS certification databases, ECHA REACH substance restriction filings, FDA 21 CFR Part 820 quality system records, and METI industrial automation incentive disclosures provided validation layers. Bottom-up torch shipment analysis by product type and application converged with top-down welding equipment market sizing across the analysis window.
Segment-level modeling addressed thermal management architecture, automation compatibility, certification tier, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from shipment trajectory analysis adjusted for replacement cycle compression and specification upgrade elasticity. Forecast inputs incorporated EU Green Deal mandate implementation timelines, EPA hexavalent chromium exposure enforcement patterns, and robotic TIG penetration rates in Japanese automotive supplier parks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to tungsten supply concentration disruptions and REACH substance restriction expansions. A model refresh is warranted upon material change in ECHA regulatory friction on electrode formulations or METI incentive recalibration for industrial automation deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
North America Fans and Blowers Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Europe Fusion Splicer Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Global Vacuum Furnaces Market