
 Urinary Incontinence Therapeutics Market | 2026-2036
Urinary Incontinence Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
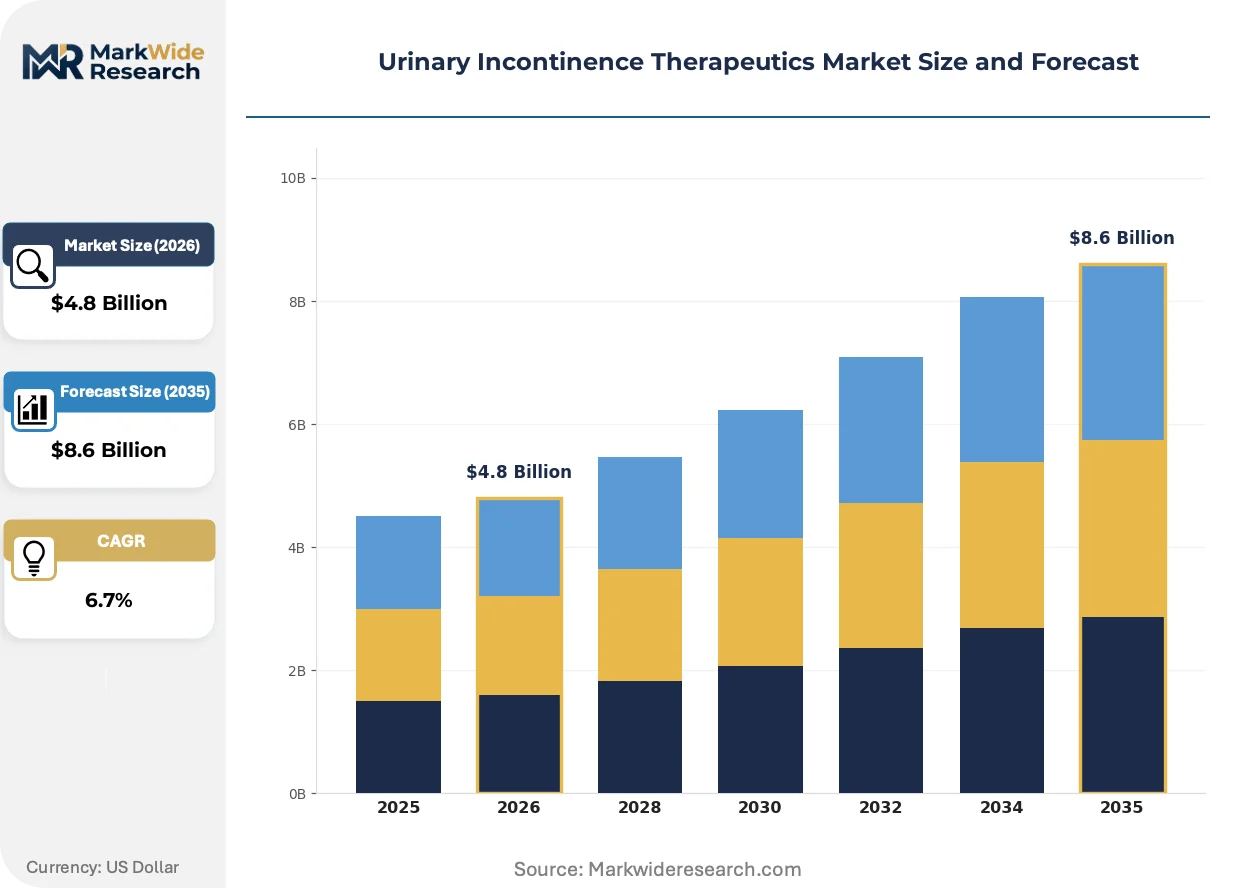
Urinary Incontinence Therapeutics Market Outlook
Home care settings is broadening as the fastest-expanding end-use channel for urinary incontinence therapeutics, pulling prescriptions away from hospitals and rehabilitation centers. Pfizer Inc. anchors its position through manufacturing scale across oral anticholinergic portfolios. Astellas Pharma Inc. differentiates via neuromodulation device specialization in urology clinics. Johnson & Johnson sustains brand strength in stress incontinence surgical adjuncts through channel control with integrated delivery networks.
Urinary incontinence therapeutics encompass pharmacological agents and neuromodulation devices that modulate detrusor muscle activity or sphincter function, with beta-3 agonists like mirabegron operating through selective adrenergic receptor activation to increase bladder capacity. These interventions serve to restore continence, reduce episode frequency, and improve quality of life in patients with stress, urge, or mixed etiologies. Anticholinergics retain the largest volume share but face margin compression from generic saturation, while beta-3 agonists command premium pricing due to superior dry-mouth tolerability profiles. Neuromodulation devices represent the fastest-growing delivery mode segment, driven by rechargeable implant miniaturization and expanded CMS reimbursement for ambulatory insertion procedures.
The FDA oversees new drug approvals and 510(k) device clearances, while the DEA regulates controlled-substance anticholinergics with abuse-liability scheduling. EMA's MDR requirements impose strengthened clinical evidence standards on neuromodulation devices entering European markets. Stakeholders must monitor FDA draft guidance on patient-reported outcome instruments for incontinence trials, as validated endpoints will determine label expansions and competitive positioning for emerging therapies.
Market Dynamics
The transition from anticholinergic dominance toward beta-3 agonist and neuromodulation alternatives is compressing traditional revenue pools while expanding device-based service lines across ambulatory settings. This therapeutic substitution is reshaping manufacturer portfolios and provider procurement patterns simultaneously.
Growth Catalysts
- 505(b)(2) FDA Pathway:The streamlined approval mechanism for generic anticholinergics accelerates market entry timelines, expanding affordable options and driving volume growth in managed care formularies.
- Rechargeable Implant Miniaturization:Neuromodulation device manufacturers are deploying smaller, longer-lasting implants that reduce surgical revision rates and expand candidacy to elderly patients previously excluded by operative risk.
- Home Care Migration:Patients are relocating therapeutic administration from institutional settings to residential environments, creating demand for self-administered pharmacological agents and remote monitoring infrastructure.
Market Restraints
- Anticholinergic Generic Saturation:Patent cliffs across oral oxybutynin and tolterodine formulations have collapsed price premiums, eroding branded revenue streams and deterring R&D investment in me-too molecules.
- Dry-Mouth Tolerability Ceiling:Persistent anticholinergic side effects limit adherence rates and drive discontinuation, constraining volume growth despite broad prescriber familiarity with the mechanism.
- Device Reimbursement Variability:CMS coverage determinations for sacral neuromodulation vary across Medicare Administrative Contractors, creating geographic access inequities and slowing provider adoption in non-parity regions.
Strategic Opportunities
- Underpenetrated Male Stress Incontinence:Post-prostatectomy populations remain underserved relative to female urge incontinence segments, offering white-space expansion for targeted surgical adjuncts and male-specific device configurations.
- Combination Pharmacotherapy:Converging beta-3 agonist and low-dose anticholinergic protocols demonstrate superior efficacy in refractory patients, opening combination product development pathways with differentiated labeling.
- Telehealth-Integrated Pelvic Floor Therapy:Digital health platforms are embedding behavioral interventions into remote care workflows, creating channel partnerships between device manufacturers and virtual care providers.
Industry Challenges
- Patient-Reported Outcome Validation:FDA draft guidance on incontinence-specific PRO instruments demands rigorous endpoint development, extending trial timelines and increasing clinical evidence generation costs for novel therapies.
- Interventional Urologist Training Bottleneck:Sacral neuromodulation implantation requires specialized surgical competency; fellowship pipeline constraints limit procedure volume expansion despite device availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Incontinence Therapeutics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Anticholinergics, Beta-3 Agonists, Neuromodulation Devices Therapy Area: Stress Incontinence, Urge Incontinence, Mixed Incontinence, Overflow Incontinence End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Topical, Oral, Injectable, Device-Based |
| Companies Covered | Pfizer Inc., AbbVie Inc., Astellas Pharma Inc., Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Sanofi S.A., GlaxoSmithKline plc, Boehringer Ingelheim Pharmaceuticals, Inc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Incontinence Therapeutics Market Strategic Shifts
Technology convergence between miniaturized implantable electronics and remote patient monitoring is dissolving traditional boundaries between pharmacological and device-based continence management. These developments are compressing treatment cycles and relocating care delivery toward patient-controlled environments.
Rechargeable neuromodulation systems with wireless power transfer are decentralizing sacral nerve stimulation from tertiary referral centers to community urology practices. Ambulatory surgical centers in the United States are adopting these platforms to capture CMS-reimbursed insertion procedures previously concentrated in hospital outpatient departments. This geographic diffusion is compressing specialist concentration and expanding addressable patient populations beyond academic medical center catchments.
EMA's Medical Device Regulation imposes strengthened clinical evidence requirements on neuromodulation systems entering European markets, mandating extended follow-up data and post-market surveillance protocols. Device manufacturers are restructuring EU submission strategies to accommodate MDR technical documentation demands, delaying commercial timelines but elevating competitive barriers for lower-resourced entrants. The regulatory friction disproportionately affects mid-tier neuromodulation developers lacking legacy clinical databases.
Patients are demanding discrete, portable continence solutions that minimize lifestyle disruption and workplace visibility. This preference shift is elevating beta-3 agonist oral therapies over transdermal patches and bulkier external collection devices in professional settings. Employer-sponsored health plans in the United States are reflecting this priority through formulary positioning that favors once-daily oral regimens with minimal anticholinergic burden.
Urinary Incontinence Therapeutics Market Segmentation
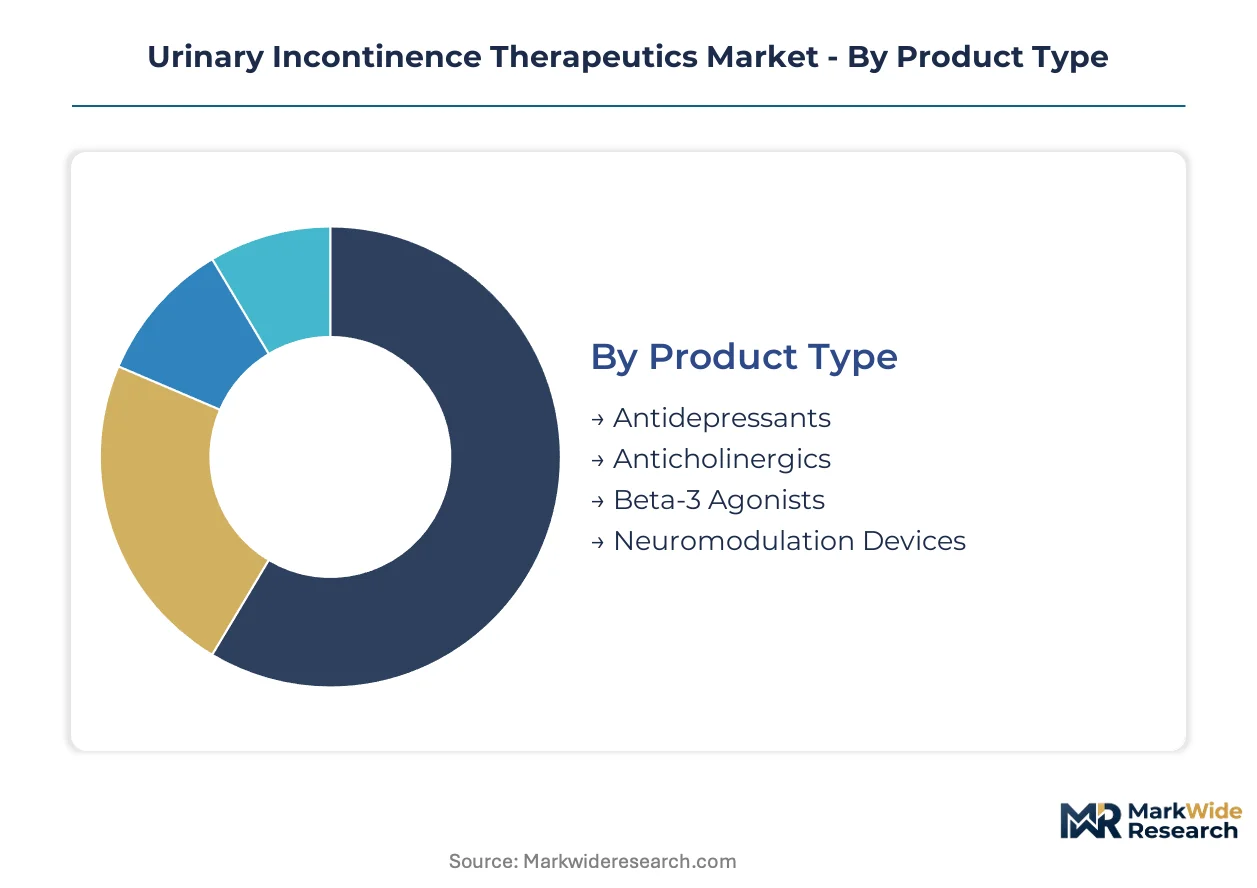
Segmentation in urinary incontinence therapeutics reveals divergent margin profiles across pharmacological and device-based modalities. Manufacturers calibrate portfolio investments against reimbursement parity, surgical candidacy thresholds, and patient preference for self-administered versus interventional solutions.
Product Type:
Cost tier separates chronic oral medication patients from surgical implant candidates, with reimbursement intensity scaling accordingly.
- Anticholinergics:Oral and transdermal formulations blocking muscarinic receptors to reduce detrusor overactivity. Volume concentrates in Medicare Part D formularies where generic oxybutynin and tolterodine dominate prescriptions, though dry-mouth discontinuation erodes adherence.
- Beta-3 Agonists:Selective adrenergic receptor activators like mirabegron increasing bladder capacity without anticholinergic burden. Commercially insured populations in the United States drive demand, with employer plans favoring once-daily oral regimens that minimize workplace disruption.
- Neuromodulation Devices:Sacral nerve stimulators and tibial nerve stimulation systems delivering electrical impulses to modulate voiding reflexes. CMS reimbursement for ambulatory insertion procedures accelerates adoption in community urology practices.
- Antidepressants:Off-label serotonin-norepinephrine reuptake inhibitors addressing co-morbid depression and stress incontinence symptoms. Psychiatric and urology co-prescribing patterns determine utilization.
Anticholinergics lead volumes today; neuromodulation devices are gaining share fastest.
Therapy Area:
Application specificity dictates whether patients qualify for device implantation or remain on pharmacological management pathways.
- Urge Incontinence:Detrusor overactivity-driven leakage responding to antimuscarinic and beta-3 agonist modulation. Academic medical centers in the United States concentrate sacral neuromodulation referrals for refractory cases.
- Stress Incontinence:Urethral sphincter incompetence from pelvic floor weakness or post-surgical trauma. Post-prostatectomy male populations remain underpenetrated relative to female segments, creating white-space expansion for male-specific surgical adjuncts.
- Mixed Incontinence:Concurrent urge and stress components requiring combination pharmacotherapy or staged intervention. Combination beta-3 agonist and low-dose anticholinergic protocols demonstrate superior efficacy, opening differentiated product development pathways.
- Overflow Incontinence:Detrusor underactivity or outlet obstruction necessitating catheterization or alpha-blocker therapy. Long-term care facilities manage the highest prevalence of this segment.
Urge incontinence leads volumes today; stress incontinence is expanding most quickly in male-specific configurations.
End User:
Customer type determines reimbursement mechanism and care delivery infrastructure requirements.
- Home Care:Self-administered oral therapies and remote monitoring platforms enabling residential continence management. Patients seek alternatives to institutional settings, pulling prescriptions away from hospitals and rehabilitation centers.
- Hospitals:Acute inpatient initiation of pharmacological therapy and complex surgical implantation requiring anesthesia support. Tertiary referral centers concentrate sacral neuromodulation training and high-volume procedural expertise.
- Clinics:Ambulatory urology practices performing device insertion and follow-up programming. Community adoption of rechargeable implant platforms captures CMS-reimbursed procedures previously concentrated in hospital outpatient departments.
- Rehabilitation Centers:Pelvic floor physical therapy and behavioral intervention delivery. Telehealth-integrated platforms are embedding these services into remote care workflows.
Home care leads volumes today; clinics are climbing the fastest on device-based service line expansion.
Delivery Mode:
Maturity gradient separates established oral administration from emerging device-based and targeted delivery technologies.
- Oral:Systemic absorption through gastrointestinal tract enabling convenient self-administration. Employer-sponsored health plans in the United States favor once-daily regimens with minimal anticholinergic burden in professional settings.
- Device-Based:Implantable neuromodulation systems and external stimulators requiring surgical or interventional placement. Rechargeable implant miniaturization reduces surgical revision rates and expands candidacy to elderly patients previously excluded by operative risk.
- Topical:Transdermal patches and gels delivering localized anticholinergic effects with reduced systemic exposure. Patient preference for discrete, portable solutions elevates oral alternatives in workplace visibility-sensitive populations.
- Injectable:Intradetrusor botulinum toxin and bulking agents for refractory or surgical-adjunct indications. Specialist administration requirements limit volume expansion despite efficacy in selected populations.
Oral delivery leads volumes today; device-based modalities show the steepest expansion trajectory on rechargeable system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston medical device cluster anchors urinary incontinence therapeutics development, with academic medical centers driving neuromodulation innovation and FDA interaction density. Regional prescribing patterns diverge sharply based on reimbursement parity, aging demographics, and specialist concentration.
United States
Medicare Administrative Contractor variability and employer-sponsored plan formulary positioning shape demand across urge and stress incontinence segments. The FDA's 505(b)(2) pathway accelerates generic anticholinergic approvals while CMS reimbursement determinations for sacral neuromodulation create geographic access inequities. The Minneapolis-St. Paul corridor concentrates interventional urology training programs and high-volume neuromodulation implantation centers.
Germany
EMA Medical Device Regulation compliance costs and statutory health insurance (GKV) reimbursement protocols determine market access for neuromodulation systems. The country's national pharmaceutical regulator enforces strengthened clinical evidence standards on implantable devices entering European markets. The Baden-Württemberg region hosts precision electronics manufacturers supplying miniaturized rechargeable implant components to device developers.
Japan
PMDA consultation pathways and aging demographic density drive beta-3 agonist prescribing growth among urologists managing refractory overactive bladder. METI industrial policy supports domestic neuromodulation device development through medical technology innovation grants. The Osaka-Kobe corridor concentrates pelvic floor specialty clinics adopting ambulatory insertion procedures for sacral nerve stimulation systems.
United Kingdom
NICE technology appraisal guidance and NHS Integrated Care Board procurement frameworks determine formulary placement for oral therapeutics versus surgical interventions. The Medicines and Healthcare products Regulatory Agency oversees post-market surveillance for neuromodulation devices under retained EU MDR provisions. The Oxford-Cambridge arc anchors digital health platform development embedding telehealth-integrated pelvic floor therapy into remote care workflows.
France
ANSM regulatory oversight and HAS (Haute Autorité de Santé) health technology assessment procedures shape reimbursement timelines for novel continence therapies. The country's national pharmaceutical regulator coordinates with EMA on centralized marketing authorization procedures for beta-3 agonist formulations. The Lyon-Grenoble corridor concentrates medical device engineering talent developing wireless power transfer systems for rechargeable neuromodulation implants.
Urinary Incontinence Therapeutics Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers rebalance between generic-saturated anticholinergic exposure and device-based service line expansion. The market exhibits tiered concentration with large-cap pharmaceutical incumbents, specialized neuromodulation developers, and regional generic manufacturers occupying distinct competitive positions. Three archetypes define strategic positioning: scale-driven oral therapy suppliers, interventional device specialists, and integrated delivery network partners. M&A activity and technology licensing agreements represent the dominant competitive moves reshaping manufacturer capabilities.
Within the pharmaceutical incumbent tier, Pfizer Inc. and Johnson & Johnson exemplify scale-driven oral therapy and surgical adjunct positioning respectively. Astellas Pharma Inc. occupies a specialist position in neuromodulation device development for urology clinic channels. These three companies represent contrasting portfolio strategies—anticholinergic manufacturing scale, stress incontinence surgical integration, and neuromodulation device specialization—reflecting the therapeutic substitution dynamics compressing traditional pharmacological revenue pools while expanding device-based alternatives.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Astellas Pharma Inc. |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| GlaxoSmithKline plc |
| Boehringer Ingelheim Pharmaceuticals, Inc. |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up generic manufacturers anchor anticholinergic supply, compressing distributor margins while concentrating pricing power among three domestic production clusters. This ownership pattern feeds directly into formulary negotiations, where volume commitments extract steeper rebates from retail pharmacies and mail-order channels.
Pricing Analysis
Distributor margin compression runs through the generic anticholinergic tier, where 90-day supply contracts dominate Medicare Part D formularies. Three-tier pricing structure across premium beta-3 agonists, standard branded anticholinergics, and economy generic oxybutynin separates patient populations by insurance archetype. Pricing pressure stems from patent cliff saturation in oral muscarinic antagonists, forcing manufacturers toward device-based service lines. Commercially insured employers show lowest price sensitivity, prioritizing dry-mouth tolerability over per-unit cost.
Supply Chain Analysis
Domestic-content mandates in the FDA's 505(b)(2) pathway reshape active pharmaceutical ingredient sourcing toward qualified U.S. and European facilities. Supply concentrates in India for anticholinergic APIs, Germany for precision electronics in neuromodulation implants, and Switzerland for beta-3 agonist finished dosage forms. Raw material dependencies span lithiated battery cells, platinum-iridium electrodes, and mirabegron intermediates. Single-source vulnerability in rechargeable implant microelectronics creates geographic concentration risk. Distribution runs through specialty pharmacy channels for oral therapies and direct-to-hospital consignment for surgical devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in urinary incontinence therapeutics rests on rechargeable implant miniaturization reducing surgical revision costs, while beta-3 agonist formulary positioning captures premium-tier employer sponsorship.
For Market Incumbents: Acquire ambulatory surgical center networks to lock in CMS-reimbursed neuromodulation insertion volume. Consolidate interventional urology training programs to defend against mid-tier device entrants lacking fellowship pipeline access. Vertical integration into rechargeable battery cell production hedges lithiated supply volatility from Asian concentrate markets. For New Entrants and Emerging Players: Launch via telehealth-integrated pelvic floor therapy platforms targeting post-prostatectomy male stress incontinence, the most penetrable white-space segment. Underpenetration in male-specific surgical adjuncts offers faster adoption curves than saturated female urge markets. Partner with virtual care providers to embed behavioral interventions into remote monitoring workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier neuromodulation developers lacking EU MDR technical documentation databases. Long-term viability favors device specialists with rechargeable platform roadmaps over generic-dependent pharmaceutical portfolios. Watch FDA draft guidance finalization on patient-reported outcome instruments as the signal for label expansion timing and competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS coverage parity for ambulatory sacral neuromodulation insertion expands addressable patient populations beyond academic centers. |
| Manufacturing Scale-Up | Rechargeable implant miniaturization reduces surgical revision rates and extends device lifecycle economics for elderly candidates. |
| Regulatory Approval Pathway | FDA 505(b)(2) submissions for generic anticholinergics accelerate market entry while compressing branded revenue pools. |
| Hospital System Partnership | Integrated delivery network contracts for stress incontinence surgical adjuncts lock in channel control with gynecology and urology service lines. |
| Software Companion Development | Digital health platforms embedding remote monitoring capture patient adherence data and support outcome-based contracting with payers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulary directors, interventional urologists, GPO contracts managers, and neuromodulation device engineers with secondary validation against FDA 510(k) filings, CMS Medicare data, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down manufacturer revenue triangulation anchored segment-level estimates.
Segment-weighting approaches applied therapy area, product type, delivery mode, and end-user channel dimensions across the projection horizon. CAGRs derived from patient population epidemiology, procedure volume trends, and reimbursement trajectory modeling. Forecast inputs incorporated patent expiration schedules, MDR transition timelines, and ambulatory surgical center adoption curves for rechargeable implant platforms.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance delays, CMS non-coverage determinations, or lithium supply disruptions. Forecasts reflect assumptions documented in stakeholder interview transcripts and regulatory filing analysis. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urinary Tract Infection Testing Market
Urology
Global Prostate Cancer Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Global Prostate Health Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Urology Surgery Supplies Market
Urology
Urology Disposables Market
Urology
Uraemia Treatment Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
Global Bladder Scanner Market
Urology
Urology Forceps Market
Urology
Global Hydronephrosis Market
Urology
Urology Devices Market
Urology
Suprapubic Catheters Market
Urology
Europe Bladder Disorders Market
Urology
Ureterorenoscopes Market