
 Video-Guided Pericardial Access Device Market | 2026-2036
Video-Guided Pericardial Access Device Market Size, Share, and Industry Trends Forecast 2026-2036
Video-Guided Pericardial Access Device Market Outlook
Software-defined visualization and procedural analytics subscription tiers is recalibrating how device vendors monetize pericardial access platforms. Medtronic plc leverages integrated imaging-to-navigation ecosystems to sustain premium positioning across cardiac catheterization labs. Boston Scientific Corporation anchors its portfolio through specialized sheath compatibility with multiple imaging modalities. Abbott Laboratories differentiates via end-to-end electrophysiology workflow control spanning access through ablation.
A video-guided pericardial access device combines optical or digital imaging sensors with needle, catheter, or sheath delivery systems to enable direct visualization during pericardial puncture, typically incorporating fiberoptic bundles or CMOS sensors with working channels of 4–8 French for instrument passage and fluid aspiration. Its primary purpose is reducing the incidence of cardiac laceration, coronary artery puncture, and pneumothorax during pericardiocentesis or epicardial mapping procedures. Catheter systems capture the dominant revenue share due to repeat utilization rates and higher per-procedure pricing, while ultrasound-guided technology leads volume deployment because of portability and cath lab integration speed. Access kits represent the fastest-expanding product category as hospitals standardize disposable bundles to streamline inventory and reduce cross-contamination risk.
FDA 510(k) clearance pathways govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence and post-market surveillance obligations for Class IIa and IIb percutaneous cardiac instruments. The Japanese Ministry of Health, Labour and Welfare through PMDA reviews foreign-manufactured devices through a designated marketing authorization holder system that extends approval timelines. Stakeholders must monitor evolving reimbursement codes for image-guided pericardiocentesis across Medicare, NHS England, and Japanese social insurance frameworks, as coding changes directly alter hospital capital allocation for advanced access platforms.
Market Dynamics
Software-defined visualization and procedural analytics subscription tiers is recalibrating how device vendors monetize pericardial access platforms, compressing upfront capital requirements while extending recurring revenue capture across cardiac catheterization labs.
Growth Catalysts
- MDR Certification Requirements:The EU Medical Device Regulation imposes stricter clinical evidence and post-market surveillance obligations for Class IIa and IIb percutaneous cardiac instruments, elevating barriers for marginal competitors and consolidating premium positioning for compliant manufacturers.
- Electrophysiology Program Expansion:Academic medical centers in the United States, Germany, and Japan are scaling structural heart and electrophysiology programs, driving institutional procurement of integrated imaging-to-navigation ecosystems for complex pericardial interventions.
- Fiberoptic CMOS Sensor Miniaturization:Advances in CMOS sensor fabrication are enabling smaller working channels of 4–8 French with enhanced resolution, expanding the addressable procedure set beyond diagnostic pericardiocentesis to therapeutic epicardial ablation.
Market Restraints
- Single-Source Optical Component Supply:Concentrated manufacturing of specialized fiberoptic bundles in select East Asian supplier clusters creates vulnerability to input disruption for catheter system producers.
- PMDA Approval Timeline Extension:Japan's designated marketing authorization holder system for foreign-manufactured devices extends regulatory review cycles, delaying market entry and compressing effective patent life.
- Ultrasound-Guided Substitution:Portable ultrasound systems with cath lab integration speed represent a lower-cost alternative for standard pericardiocentesis, constraining pricing power for video-guided platforms in volume-tier hospitals.
Strategic Opportunities
- Disposable Access Kit Standardization:Hospitals are streamlining inventory and reducing cross-contamination risk through standardized disposable bundles, creating white space for vendors with integrated kit design capabilities.
- Image-Guided Reimbursement Code Expansion:Evolving Medicare and NHS England coding for image-guided pericardiocentesis directly alters hospital capital allocation, rewarding early movers with validated health economic evidence.
- AI-Assisted Procedural Navigation:Machine learning algorithms for real-time needle trajectory prediction are converging with optical imaging platforms, enabling autonomous safety interlocks that differentiate next-generation systems.
Industry Challenges
- Interventional Cardiologist Training Bottlenecks:Epicardial mapping and ablation require specialized skill sets that outpace fellowship program output, constraining procedure volume growth and device utilization rates.
- Legacy EMR Integration Complexity:Procedural data capture from video-guided systems must interface with diverse hospital information architectures, extending deployment timelines and inflating implementation costs.
- FDA 510(k) Predicate Device Scarcity:Narrow equivalence pathways for novel optical sensor configurations prolong premarket notification preparation and trigger de novo classification requests.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video-Guided Pericardial Access Device Market |
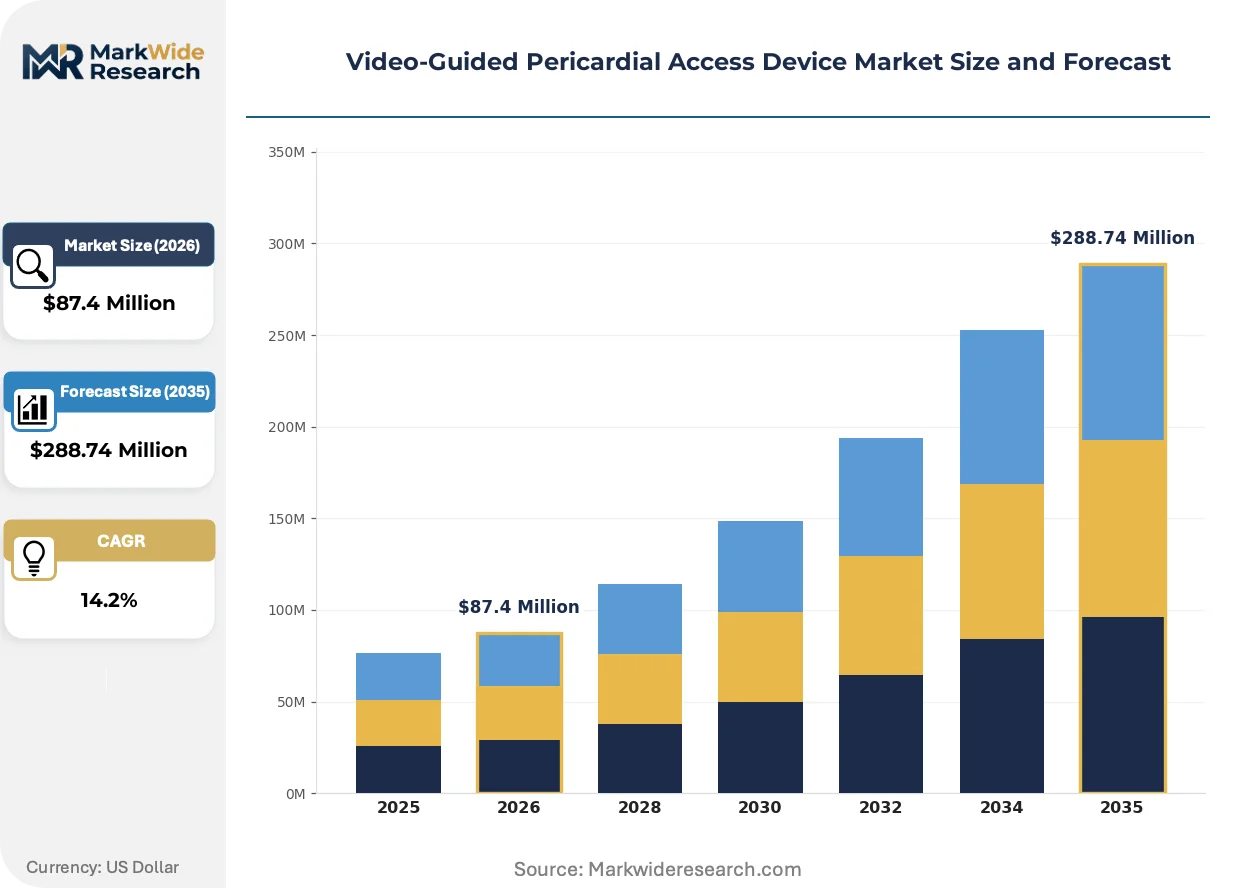
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $288.74 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Systems, Catheter Systems, Sheath Systems, Access Kits End User: Hospitals, Specialty Clinics, Academic Medical Centers, Cardiology Practices Technology: Ultrasound-Guided, X-Ray-Guided, Magnetic Resonance-Guided, Conventional Techniques Application: Cardiac Tamponade, Pericardiocentesis, Fluid Drainage, Diagnostic Procedures |
| Companies Covered | GE Healthcare, Siemens Healthcare, Philips Healthcare, Medtronic plc, Boston Scientific Corporation, AtriCure, Inc., Baylis Medical Company Inc., Cook Medical Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video-Guided Pericardial Access Device Market Strategic Shifts
Optical sensing architectures and regulatory data requirements are actively reshaping competitive positioning in pericardial access, compressing development cycles while elevating post-commercialization accountability.
CMOS-based digital imaging is converging with traditional fiberoptic visualization in next-generation pericardial access catheters. Academic medical centers with high-volume electrophysiology programs are adopting hybrid platforms at accelerated procurement cycles. This convergence is enabling real-time image processing and augmented trajectory overlay, compressing the learning curve for complex epicardial procedures while differentiating premium catheter systems from standard ultrasound-guided alternatives.
MDR post-market surveillance obligations are intensifying clinical evidence requirements for Class IIb percutaneous cardiac instruments. Manufacturers must now maintain active implant registries and periodic safety update reports beyond initial CE marking. Catheter systems with longer commercial histories in European electrophysiology labs face heightened compliance costs, while newer entrants with native MDR-compliant quality management systems capture share in replacement procurement cycles.
Hospital purchasing committees are unbundling after-sales service from capital equipment contracts in the United States. Independent service organizations and third-party preventive maintenance providers are displacing manufacturer-captive technical support teams in mid-tier community hospital cath labs. This behavioral shift is most visible in Medicare-dependent institutions seeking to reduce per-procedure overhead through multi-vendor service aggregation.
Video-Guided Pericardial Access Device Market Segmentation
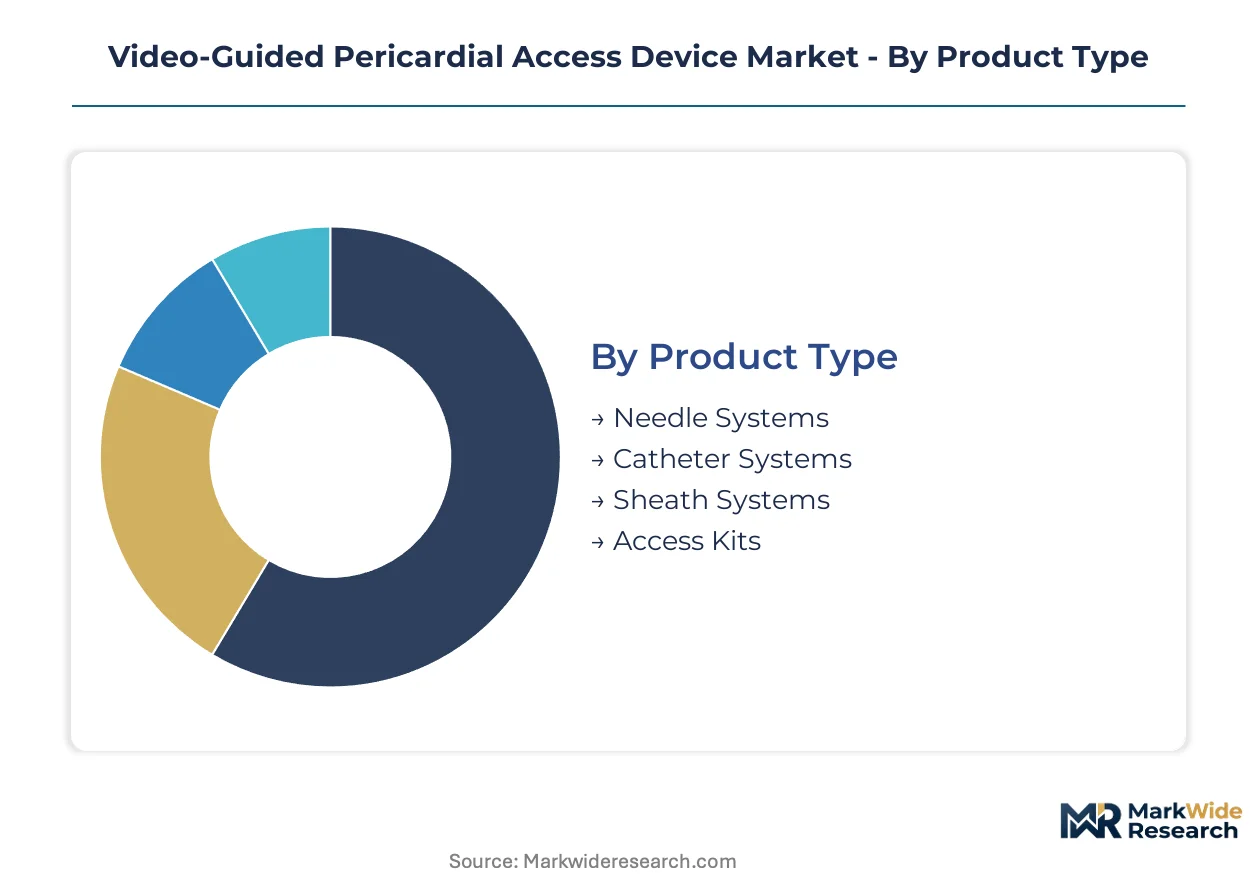
Video-guided pericardial access devices fragment across four distinct dimensions. Product architecture determines capital intensity and recurring revenue potential. End-user concentration shapes procurement authority and service bundling preferences.
Product Type:
Catheter systems command premium pricing through repeat utilization, while access kits gain volume traction via disposable standardization.
- Needle Systems:Fiberoptic or CMOS-integrated needles deliver direct visualization during initial pericardial puncture. Demand clusters in German and Japanese academic centers performing complex epicardial mapping where needle trajectory precision reduces cardiac laceration risk.
- Catheter Systems:Multi-lumen designs with 4–8 French working channels enable instrument passage and fluid aspiration under continuous imaging. United States electrophysiology programs anchor procurement volumes for these systems due to higher per-procedure reimbursement and integrated navigation ecosystem compatibility.
- Sheath Systems:Introducer sheaths with integrated optical sensors maintain access patency during prolonged procedures. Cardiology practices in Japan favor sheath compatibility across multiple imaging modalities.
- Access Kits:Standardized disposable bundles streamline inventory and reduce cross-contamination risk. Hospitals across Germany are standardizing kit configurations to compress procurement overhead.
Today's leader: Catheter Systems. Tomorrow's challenger: Access Kits.
End User:
Academic medical centers concentrate advanced procedure volume, while specialty clinics expand ambulatory pericardiocentesis capacity.
- Hospitals:General hospital cath labs represent the foundational deployment base for video-guided platforms. Medicare-dependent institutions in the United States prioritize capital efficiency through multi-vendor service aggregation.
- Academic Medical Centers:High-volume electrophysiology and structural heart programs drive adoption of hybrid imaging-to-navigation ecosystems. These centers in the United States, Germany, and Japan anchor demand for next-generation CMOS-based systems with augmented trajectory overlay.
- Specialty Clinics:Focused cardiac intervention facilities pursue portable ultrasound-guided alternatives for standard pericardiocentesis. German outpatient cardiology networks are expanding ambulatory fluid drainage capacity.
- Cardiology Practices:Private practice cardiologists require compact, reimbursement-optimized systems for diagnostic procedures. Japanese social insurance frameworks influence capital allocation timing in this segment.
Procurement authority sits with Academic Medical Centers. Volume expansion favors Specialty Clinics.
Technology:
Ultrasound-guided platforms dominate deployment speed, while magnetic resonance-guided systems target emerging research applications.
- Ultrasound-Guided:Portable systems with rapid cath lab integration enable point-of-care deployment. Volume-tier hospitals across the United States favor this modality for its lower capital threshold and established reimbursement pathways.
- X-Ray-Guided:Fluoroscopy-integrated access supports complex structural heart interventions requiring simultaneous device visualization. German hybrid operating suites anchor demand for these systems.
- Magnetic Resonance-Guided:MRI-compatible catheters enable real-time soft tissue visualization without ionizing radiation. Research programs at select Japanese academic centers pilot these systems for epicardial ablation guidance.
- Conventional Techniques:Non-imaging blind or ECG-guided pericardiocentesis persists in resource-constrained settings. NHS England coding evolution is compressing residual demand for these approaches.
Ultrasound-Guided holds volume leadership. Magnetic Resonance-Guided presents the steepest expansion trajectory.
Application:
Emergency cardiac tamponade management anchors life-critical demand, while diagnostic procedures expand elective utilization.
- Cardiac Tamponade:Emergency pericardiocentesis for hemodynamic compromise demands rapid, reliable access with minimal complications. United States trauma centers and cardiac surgery units prioritize video-guided systems for these high-stakes scenarios.
- Pericardiocentesis:Therapeutic fluid evacuation for recurrent or large pericardial effusions represents the core repeat procedure volume. German hospital networks standardize video-guided protocols to reduce coronary artery puncture incidence.
- Fluid Drainage:Chronic or malignant effusion management requires indwelling catheter capability. Japanese palliative care pathways influence device selection for oncology patients.
- Diagnostic Procedures:Pericardial biopsy and epicardial mapping support arrhythmia substrate characterization. Academic electrophysiology programs in the United States drive demand for integrated visualization-to-navigation workflows.
Pericardiocentesis generates procedure volume. Diagnostic Procedures unlock premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German academic centers standardize video-guided protocols faster than Japanese institutions navigate PMDA authorization timelines. Both markets concentrate electrophysiology program expansion, yet regulatory friction creates divergent procurement cadences across cath lab networks.
United States
Academic medical centers in Boston, Cleveland, and Houston anchor demand for integrated imaging-to-navigation ecosystems. FDA 510(k) clearance pathways govern commercialization, with predicate device scarcity prolonging premarket preparation for novel optical configurations. Medicare reimbursement coding evolution directly alters hospital capital allocation for advanced access platforms across the Northeast and Midwest corridors.
Germany
Hybrid operating suites in Munich and Berlin drive procurement of fluoroscopy-integrated access systems for complex structural heart interventions. EU MDR imposes stricter clinical evidence obligations for Class IIb percutaneous cardiac instruments, elevating compliance costs for legacy catheter systems. Bavarian hospital networks standardize disposable access kit configurations to compress procurement overhead and reduce cross-contamination risk.
Japan
Electrophysiology programs in Tokyo and Osaka scale CMOS-based systems with augmented trajectory overlay for epicardial ablation. PMDA's designated marketing authorization holder system extends regulatory review cycles for foreign-manufactured devices, compressing effective patent life. Social insurance frameworks influence capital allocation timing across private cardiology practices in the Kanto region.
United Kingdom
NHS England coding evolution for image-guided pericardiocentesis is compressing residual demand for conventional non-imaging techniques. London teaching hospitals prioritize portable ultrasound-guided alternatives for rapid cath lab integration. Procurement committees across the Southeast unbundle after-sales service from capital equipment contracts to reduce per-procedure overhead.
Switzerland
Swissmedic maintains rigorous post-market surveillance aligned with EU MDR standards for Class IIa and IIb cardiac instruments. Zurich and Geneva academic centers pilot MRI-compatible catheter systems for real-time soft tissue visualization without ionizing radiation. Research programs concentrate on autonomous safety interlocks converging machine learning with optical imaging platforms.
Video-Guided Pericardial Access Device Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated imaging-to-navigation ecosystems commanding premium positioning in academic medical centers while portable ultrasound alternatives capture volume-tier hospitals. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with electrophysiology workflow control, specialized cardiovascular device manufacturers with sheath compatibility expertise, and imaging system incumbents leveraging installed base relationships. Competitive moves center on M&A activity targeting optical sensor miniaturization capabilities and strategic partnerships with independent service organizations to displace captive technical support teams.
Within the diversified conglomerate tier, Medtronic plc and Abbott Laboratories exemplify end-to-end workflow control strategies spanning pericardial access through ablation. Boston Scientific Corporation occupies a specialized position emphasizing sheath compatibility across multiple imaging modalities. Among imaging system incumbents, GE Healthcare, Siemens Healthcare, and Philips Healthcare anchor demand through cath lab infrastructure relationships and integrated visualization hardware ecosystems.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthcare |
| Philips Healthcare |
| Medtronic plc |
| Boston Scientific Corporation |
| AtriCure, Inc. |
| Baylis Medical Company Inc. |
| Cook Medical Inc. |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Fiberoptic bundle fabrication costs in East Asian supplier clusters cascade through catheter system pricing tiers, with CMOS sensor miniaturization compressing component expenses for premium video-guided platforms while single-source optical dependencies sustain margin pressure on mid-tier disposable kits.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for CMOS sensor modules, enabling three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU MDR and FDA 510(k) pathways differentiates vendor positioning, with MDR-compliant systems commanding sustained premiums. Cost compression in standard-tier catheter systems is intensifying because ultrasound-guided alternatives constrain pricing power in volume-tier hospitals. Academic medical centers demonstrate least price sensitivity due to integrated navigation ecosystem requirements, while Medicare-dependent community hospitals exhibit highest sensitivity to per-procedure overhead.
Supply Chain Analysis
Freight cost volatility from East Asian manufacturing hubs to United States and European cath lab networks is elevating landed costs for specialized optical components. Supply concentrates in Japan, South Korea, and Taiwan for fiberoptic bundles and CMOS sensors, with German precision manufacturing anchoring sheath system production. Raw material dependencies span medical-grade polymers, rare-earth optical coatings, and semiconductor-grade silicon substrates. Single-source vulnerability for 4–8 French working channel components creates disruption exposure. Distribution runs through GPO contracts and direct hospital procurement committees, with independent service organizations displacing manufacturer-captive technical support in mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The video-guided pericardial access device market functions as a stable compounder, with electrophysiology program expansion across academic medical centers providing durable procedure volume growth that underpins recurring revenue capture for integrated platform vendors.
For Market Incumbents: Hedge against ultrasound-guided substitution by deepening software-defined visualization subscriptions that compress upfront capital requirements and extend customer lifetime value. Invest in MDR-native quality management systems to capture replacement procurement cycles as European hospitals retire legacy catheter systems. Prioritize optical sensor miniaturization R&D to maintain performance differentiation against portable imaging alternatives. For New Entrants and Emerging Players: The price-point gap between premium CMOS-integrated systems and economy-tier disposable kits offers entry space for hybrid platform specialists targeting German and Japanese academic centers with augmented trajectory overlay capabilities. Focus initial penetration on access kit standardization contracts where hospital purchasing committees seek inventory streamlining. Pursue strategic partnerships with independent service organizations to bypass captive technical support infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR compliance costs and predicate device scarcity elevate barriers for sub-scale manufacturers, creating acquisition opportunities for quality system assets with European commercial histories. Frame long-term viability around software-to-hardware recurring revenue ratios exceeding traditional device economics. Watch for FDA de novo classification requests as inflection indicators for novel optical sensor configurations that could reset competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | European notified body audits for Class IIb instruments elevate barriers for marginal competitors in Germany and France. |
| Software Companion Development | Procedural analytics subscriptions recalibrate monetization from capital sales toward recurring revenue in United States cath labs. |
| Hospital System Partnership | Integrated imaging-to-navigation contracts with academic medical centers in Boston and Houston anchor premium positioning. |
| Reimbursement Strategy | Medicare coding evolution for image-guided pericardiocentesis directly alters capital allocation timing across Northeast corridors. |
| CE Marking Pathway | Post-market surveillance obligations under EU MDR intensify clinical evidence requirements beyond initial device approval. |
Study Parameters
Multiple input streams — structured interviews with electrophysiology lab directors, procurement data from hospital GPO contracts, and regulatory filing analysis — were reconciled to construct market estimates. Primary fieldwork engaged cardiac catheterization lab managers, biomedical engineers, interventional cardiologists, and GPO contracts specialists across United States, German, and Japanese healthcare systems. Secondary validation drew from FDA 510(k) premarket notifications, EU MDR technical documentation, PMDA approval records, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up procedure volume modeling and top-down equipment replacement cycle analysis were cross-referenced to anchor value estimates.
Historical shipment data from catheter system manufacturers was cross-referenced against panel input from purchasing committees and independent service organizations to calibrate adoption trajectories. Segmentation modeling spanned product architecture, end-user concentration, technology modality, and application urgency across the projection horizon. CAGRs were derived from weighted average procedure growth assumptions and equipment replacement cadences. Forecast inputs incorporated electrophysiology fellowship program output, MDR transition timelines, and reimbursement code evolution patterns.
The model assumes a particular technology adoption path; alternative pathways for AI-assisted procedural navigation would alter the outlook if autonomous safety interlocks accelerate faster than projected. Forecasts reflect assumptions about regulatory clearance timelines, hospital capital budget availability, and substitution dynamics between video-guided and ultrasound-guided modalities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Stair Lift Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
US Contact Lenses Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Nasal Irrigation Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Italy Spinal Surgery Devices Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
North America Medical Devices Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Americas Wearable Medical Device Market