
 Urinary Incontinence Treatment Drugs Market | 2026-2036
Urinary Incontinence Treatment Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Incontinence Treatment Drugs Market Insights
A shift from single-source API procurement to multi-source active pharmaceutical ingredient agreements is realigning cost structures across the urinary incontinence treatment drugs supply chain. Pfizer Inc. leverages backward integration into specialized chemical manufacturing to secure feedstock reliability for anticholinergic production. AbbVie Inc. anchors its position through sustained investment in beta-3 adrenergic agonist research platforms. Astellas Pharma Inc. differentiates via concentrated expertise in urology-focused development pipelines across Asian and North American markets.
Urinary incontinence treatment drugs comprise pharmacological agents that modulate detrusor muscle contractility through muscarinic receptor antagonism, beta-3 adrenergic stimulation, or estrogen-mediated tissue restoration, with oral bioavailability thresholds typically exceeding 60% for first-line systemic therapies. These compounds serve to restore bladder storage function and reduce urgency-frequency episodes in patients with overactive bladder or stress incontinence. Anticholinergics occupy the largest revenue share within product type segmentation, though beta-3 agonists are gaining fastest due to superior dry-mouth tolerability profiles. Injectable delivery modes command premium positioning in long-term care facilities where caregiver administration compliance drives formulary preference.
The FDA enforces stringent bioequivalence standards for generic anticholinergic substitutions, while the EMA's MDR-aligned pharmacovigilance requirements shape post-market surveillance obligations across European distribution channels. Japan's PMDA maintains distinct efficacy benchmarks for Asia-specific trial data inclusion, creating layered approval complexity for multinational sponsors. Stakeholders must monitor evolving reimbursement thresholds for neuromodulation device alternatives that could displace chronic drug therapy selection criteria.
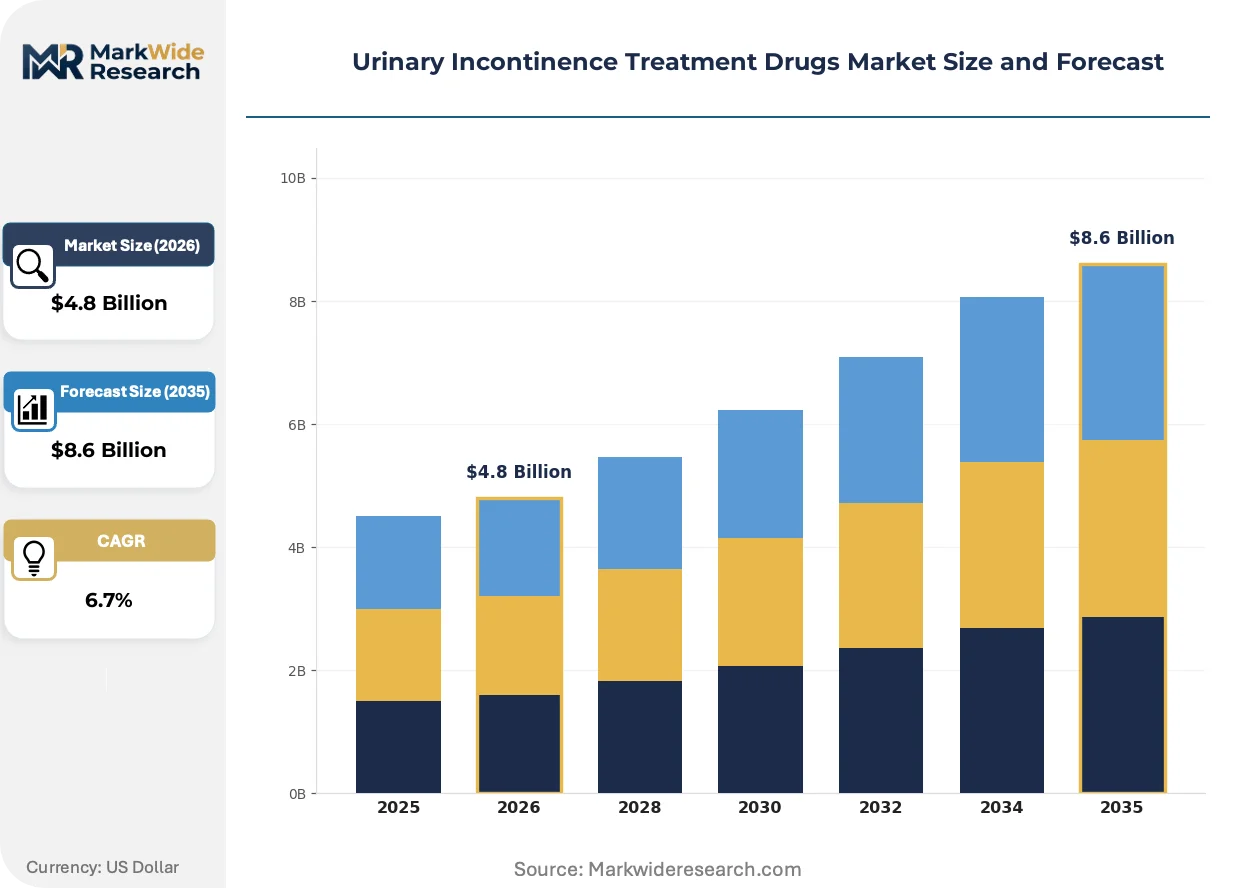
Market Dynamics
Long-term care facilities across the United States are consolidating formulary decisions around caregiver-administered injectable therapies, compressing demand for patient-managed oral regimens and reshaping competitive positioning among anticholinergic and beta-3 agonist suppliers.
Growth Catalysts
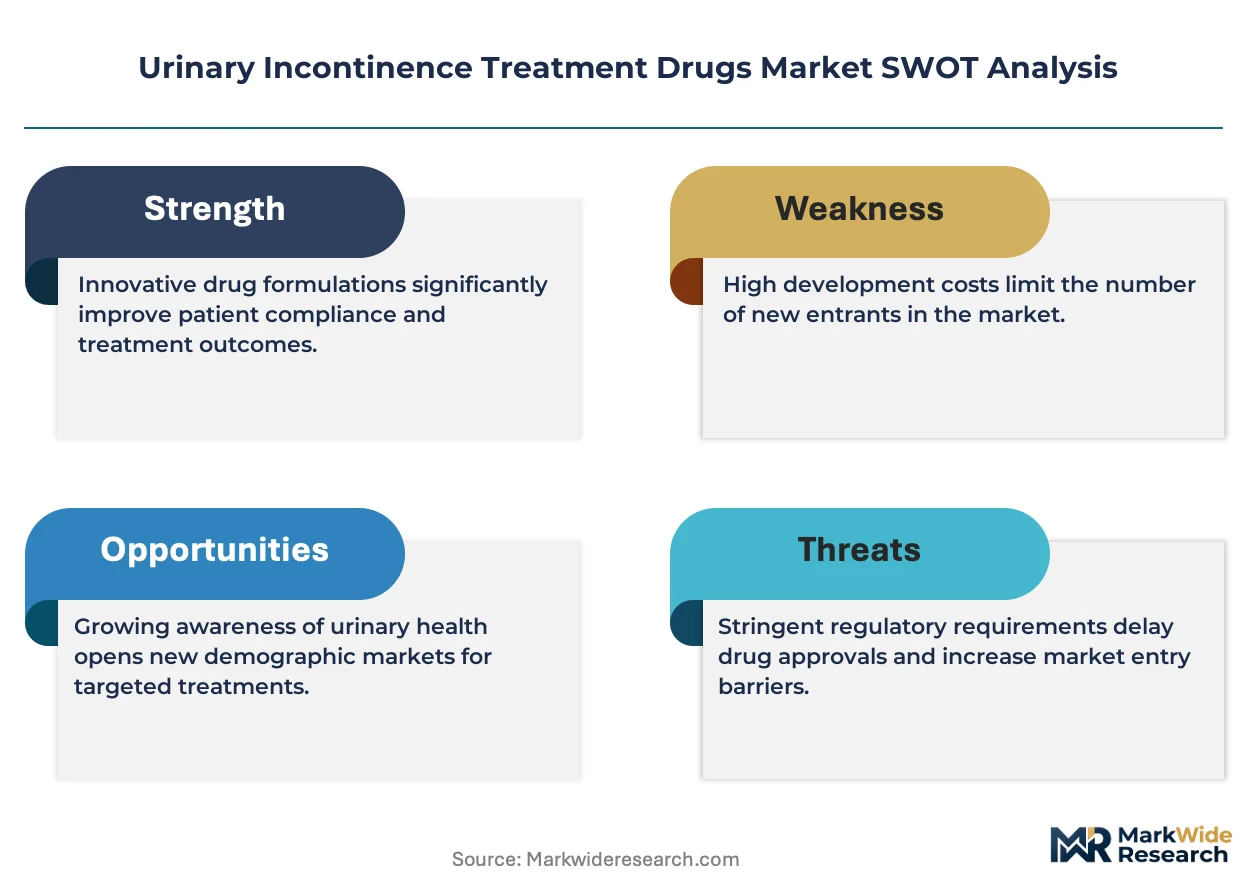
- Streamlined FDA Review Pathways:The FDA's accelerated approval mechanisms for urology therapeutics reduce development timelines for new molecular entities targeting overactive bladder, drawing expanded R&D investment from multinational sponsors.
- Injectable Administration Modes:Long-term care facilities prioritize caregiver-controlled delivery systems that ensure compliance among cognitively impaired residents, elevating demand for parenteral formulations over oral alternatives.
- Aging Demographics in the United States:The concentration of patients aged 65 and above within Medicare reimbursement frameworks sustains prescription volumes for chronic bladder management therapies.
Market Restraints
- Specialized Chemical Feedstock Concentration:Backward integration into anticholinergic precursor manufacturing concentrates among a limited supplier base in Germany and Switzerland, exposing API procurement to single-source disruption risk.
- Neuromodulation Device Substitution:Sacral nerve stimulation systems and percutaneous tibial nerve stimulation protocols displace chronic pharmacological therapy in refractory cases, capping addressable drug market expansion.
- EMA MDR-Aligned Pharmacovigilance:Post-market surveillance obligations across European distribution channels impose documentation burdens that extend generic substitution timelines and elevate compliance costs.
Strategic Opportunities
- Underpenetrated Japanese Elderly Care:Japan's PMDA maintains distinct efficacy benchmarks that, once satisfied, unlock access to the world's oldest national population with limited current beta-3 agonist penetration.
- Estrogen-Mediated Tissue Restoration:Topical estrogen formulations for postmenopausal stress incontinence represent an underserved mechanism with minimal current pipeline competition from beta-3 or anticholinergic platforms.
- Multi-Source API Agreements:Procurement officers at integrated delivery networks are renegotiating supply contracts to diversify active pharmaceutical ingredient sourcing across three or more qualified manufacturers.
Industry Challenges
- Bioequivalence Study Complexity:The FDA's stringent bioequivalence standards for generic anticholinergic substitutions require extensive pharmacokinetic trials that extend abbreviated new drug application timelines.
- Urology-Focused Talent Scarcity:Clinical development programs face recruitment competition for investigators with specialized expertise in bladder physiology and detrusor muscle contractility assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Incontinence Treatment Drugs Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticholinergics, Beta-3 Agonists, Hormonal Therapies, Neuromodulation Devices Delivery Mode: Oral, Injectable, Topical, Intravesical End User: Hospitals, Homecare Settings, Clinics, Long-term Care Facilities Treatment Phase: Acute Care, Chronic Management, Preventive Care, Palliative Care |
| Companies Covered | Pfizer Inc., AbbVie Inc., Astellas Pharma Inc., Johnson & Johnson, Viatris Inc., Teva Pharmaceutical Industries Ltd., Sanofi S.A., GlaxoSmithKline plc, Boehringer Ingelheim Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Incontinence Treatment Drugs Market Trends and Innovations
Beta-3 adrenergic agonist development platforms are compressing the historical dominance of muscarinic receptor antagonists through superior tolerability profiles, while regulatory convergence and procurement centralization simultaneously reshape competitive dynamics across developed markets.
Extended-release mirabegron formulations are overtaking immediate-release oxybutynin in Medicare Part D formularies through reduced dry-mouth discontinuation rates. Hospital systems in the United States are prioritizing these agents for polypharmacy-elderly populations. The shift is enabling premium pricing persistence for beta-3 innovators while compressing anticholinergic volume growth.
The EMA's MDR-aligned pharmacovigilance requirements are extending post-approval surveillance obligations for generic anticholinergic substitutions across European distribution channels. Manufacturers must now maintain active risk management systems that track real-world adverse event patterns. German and French national health technology assessment bodies are incorporating these surveillance costs into reimbursement ceiling calculations.
Integrated delivery networks in the United States are consolidating pharmaceutical procurement through centralized pharmacy and therapeutics committees that standardize formularies across multiple long-term care facilities. Regional buying coalitions are replacing individual facility purchasing decisions in California and Texas. This concentration is visible most acutely in the Southwest, where Catholic health systems have unified bladder management protocols across 40-plus skilled nursing properties.
Urinary Incontinence Treatment Drugs Market Segmentation
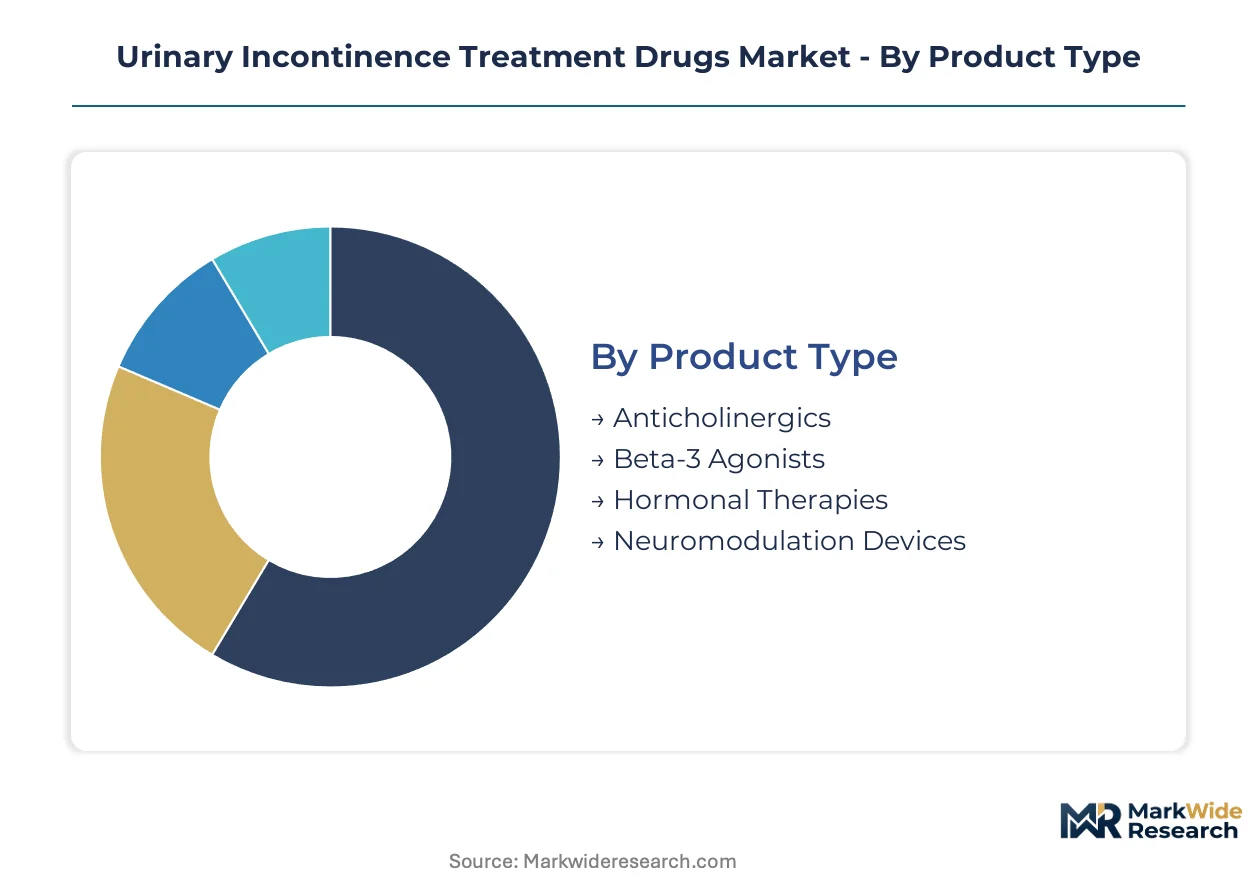
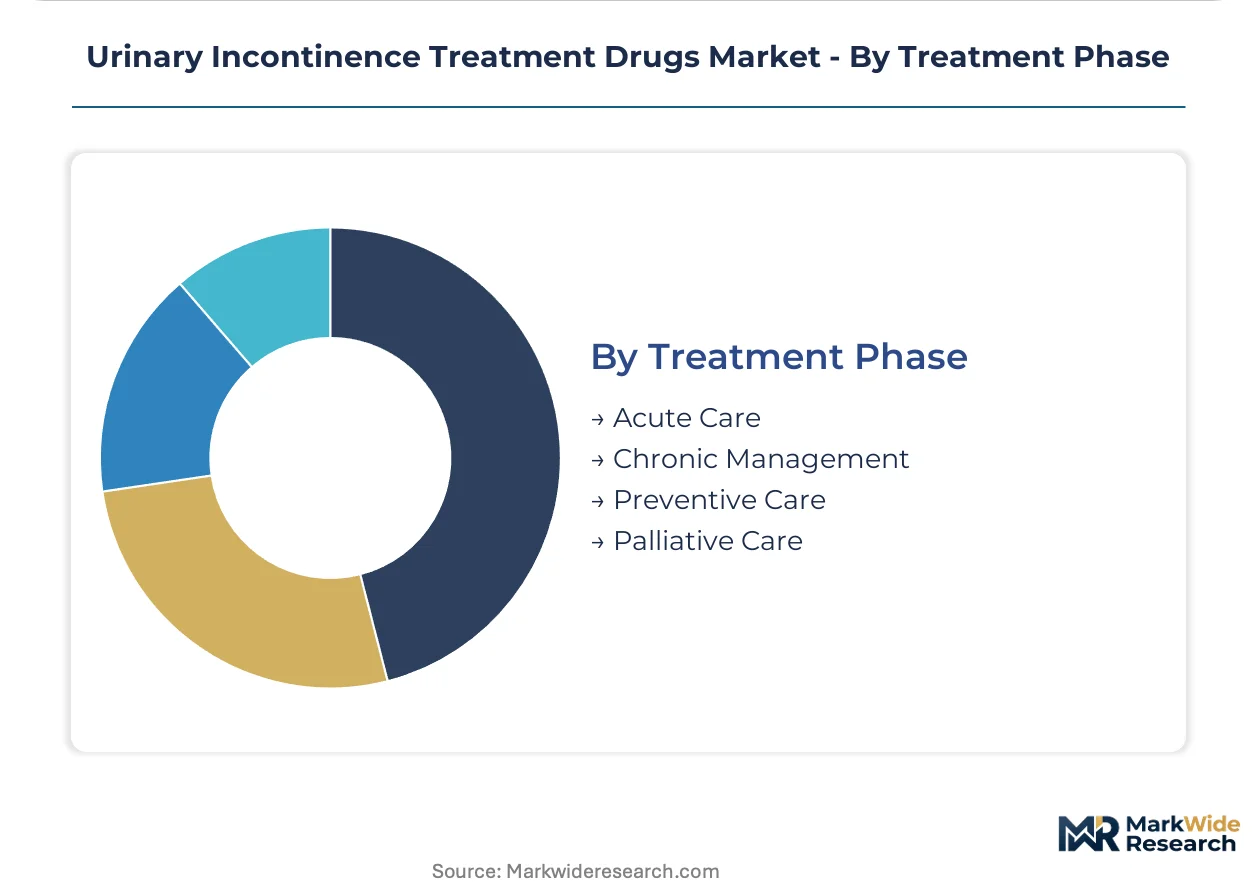
Segmentation in the urinary incontinence treatment drugs market reveals divergent growth trajectories between mature anticholinergic platforms and emerging beta-3 agonist alternatives. Procurement patterns across long-term care facilities and hospital systems favor delivery modes that reduce caregiver burden, while reimbursement frameworks concentrate volume in chronic management phases.
Product Type:
Volume leadership rests with anticholinergics, though premium pricing power is shifting toward beta-3 agonists with superior tolerability profiles.
- Anticholinergics:Muscarinic receptor antagonists including oxybutynin, tolterodine, and solifenacin modulate detrusor contractility through competitive inhibition of acetylcholine binding. Demand concentrates in Medicare Part D formularies across the United States, where cost-driven prescribing persists despite documented dry-mouth discontinuation rates exceeding 30% in elderly polypharmacy patients.
- Beta-3 Agonists:Mirabegron and vibegron stimulate beta-3 adrenergic receptors to induce detrusor relaxation without anticholinergic side effects. Prescription volume is climbing fastest in integrated delivery networks serving skilled nursing populations, where reduced cognitive impairment risk drives formulary preference over traditional antagonists.
- Hormonal Therapies:Topical estrogen formulations address urogenital atrophy in postmenopausal stress incontinence with minimal systemic absorption.
- Neuromodulation Devices:Sacral nerve stimulation and percutaneous tibial nerve stimulation systems displace pharmacological therapy in refractory overactive bladder cases.
Today's leader: Anticholinergics. Tomorrow's challenger: Beta-3 Agonists.
Delivery Mode:
Application context determines modality selection, with caregiver-controlled administration commanding premium positioning in institutional settings.
- Oral:Immediate-release and extended-release tablets dominate patient-managed chronic therapy, with bioavailability thresholds typically exceeding 60% for systemic absorption. Volume concentrates in retail pharmacy dispensing across the United States, though long-term care facilities are compressing oral share in favor of supervised alternatives.
- Injectable:Botulinum toxin intradetrusor injections and long-acting depot formulations ensure compliance in cognitively impaired populations. Demand is expanding most quickly in Catholic health system networks across the American Southwest, where unified protocols across 40-plus skilled nursing properties standardize parenteral bladder management.
- Topical:Transdermal oxybutynin patches and estrogen creams deliver localized effects with reduced systemic exposure.
- Intravesical:Direct bladder instillation of anticholinergics or capsaicin analogs serves refractory cases unresponsive to oral therapy.
Oral formulations retain volume dominance. Injectable modes are gaining share fastest in institutional channels.
End User:
Customer type stratification follows care intensity, with acute intervention sites diverging from maintenance-focused settings.
- Long-term Care Facilities:Skilled nursing properties and assisted living communities aggregate the highest per-capita consumption of urinary incontinence therapeutics due to resident age demographics and caregiver-administered protocols. Procurement centralization through pharmacy and therapeutics committees is reshaping competitive dynamics across California and Texas regional buying coalitions.
- Hospitals:Inpatient units and emergency departments manage acute urinary retention and post-surgical incontinence episodes. Volume concentrates in admission-driven prescribing for transient conditions rather than chronic disease management.
- Homecare Settings:Medicare-certified home health agencies support patient-managed therapy for community-dwelling elderly.
- Clinics:Urology and geriatric outpatient practices initiate first-line therapy and monitor treatment response.
Long-term care facilities anchor institutional demand. Homecare settings present the steepest expansion trajectory as aging-in-place preferences intensify.
Treatment Phase:
Maturity gradients separate acute intervention from chronic maintenance, with reimbursement durability favoring sustained therapy models.
- Chronic Management:Long-term pharmacological suppression of overactive bladder symptoms constitutes the largest addressable population, with Medicare reimbursement clarity supporting sustained prescription volumes. Demand concentrates in patients aged 65 and above within the United States, where polypharmacy considerations increasingly favor beta-3 agonist selection.
- Acute Care:Post-operative urinary retention and infection-related incontinence require short-term pharmacological or catheter-based intervention. Volume fluctuates with surgical admission patterns rather than demographic trends.
- Preventive Care:Pelvic floor rehabilitation combined with early pharmacological intervention aims to delay progression in mild cases.
- Palliative Care:Hospice and end-of-life settings prioritize comfort-focused bladder management over curative approaches.
Chronic management commands volume leadership. Preventive care represents the fastest-climbing opportunity as early intervention protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate active pharmaceutical ingredient synthesis toward jurisdictions with streamlined environmental compliance and lower cost-of-quality-assurance thresholds. Germany and Switzerland retain specialized chemical feedstock concentration for anticholinergic precursors, while India and China expand contract manufacturing capacity for intermediate-stage synthesis.
United States
Medicare Part D reimbursement clarity sustains prescription volumes for chronic bladder management therapies among patients aged 65 and above. The FDA's accelerated approval pathways for urology therapeutics compress development timelines for new molecular entities. Integrated delivery networks in California and Texas are consolidating formulary decisions through regional pharmacy and therapeutics committees that standardize protocols across 40-plus skilled nursing properties.
Germany
Specialized chemical manufacturing clusters in Ludwigshafen and Leverkusen anchor European supply for anticholinergic active pharmaceutical ingredients. The EMA's MDR-aligned pharmacovigilance requirements extend post-market surveillance obligations for generic substitutions, elevating compliance documentation burdens. Bavarian pharmaceutical hubs are absorbing surveillance costs into pricing structures that feed into German and French health technology assessment calculations.
Japan
The world's oldest national population presents underpenetrated demand for beta-3 adrenergic agonists with superior tolerability profiles in elderly polypharmacy patients. PMDA maintains distinct efficacy benchmarks requiring Asia-specific trial data inclusion, creating layered approval complexity for multinational sponsors. Tokyo-Osaka pharmaceutical corridors are expanding urology-focused development pipelines to satisfy these regulatory requirements.
India
Contract research organizations in Hyderabad and Bangalore are capturing anticholinergic bioequivalence study contracts as FDA scrutiny of abbreviated new drug applications intensifies. CDSCO streamlined approval pathways for urology generics are attracting multinational sponsors seeking parallel development tracks. Maharashtra-based API manufacturers are diversifying feedstock sourcing across three or more qualified suppliers to mitigate single-source disruption risk.
Switzerland
Basel-area chemical specialists concentrate backward integration into specialized precursor manufacturing for European anticholinergic production. Swissmedic maintains stringent quality benchmarks that preserve premium positioning for originator compounds against generic substitution pressure. Zürich pharmaceutical clusters are negotiating multi-source API agreements with procurement officers at integrated delivery networks seeking supply chain resilience.
Urinary Incontinence Treatment Drugs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue beta-3 adrenergic agonist platforms with superior dry-mouth tolerability profiles. Market structure consolidates around three archetypes: large-cap pharmaceutical conglomerates with urology divisions, mid-cap specialists with concentrated bladder therapeutic expertise, and generic manufacturers competing on bioequivalence documentation efficiency. Dominant competitive moves include strategic partnerships for API sourcing diversification and portfolio expansion into injectable delivery modes for long-term care penetration.
Among North American-based pharmaceutical conglomerates, Pfizer Inc. and AbbVie Inc. exemplify divergent strategic positioning within the anticholinergic and beta-3 agonist segments respectively. Astellas Pharma Inc. occupies a distinct position as a Japan-based specialist with concentrated urology pipeline investment across Asian and North American regulatory jurisdictions. These three entities anchor competitive dynamics as procurement centralization and formulary consolidation reshape channel access requirements.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Astellas Pharma Inc. |
| Johnson & Johnson |
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| GlaxoSmithKline plc |
| Boehringer Ingelheim Pharmaceuticals, Inc. |
| Others |
Pricing and Supply Chain Analysis
Extended-release mirabegron formulation technology is compressing anticholinergic pricing power while simultaneously concentrating API synthesis in specialized chemical clusters across Germany and Switzerland. This dual shift elevates cost structures for legacy muscarinic antagonists while rewarding beta-3 innovators with premium positioning in Medicare Part D formularies.
Pricing Analysis
Distributor margins on oral anticholinergics are compressing as integrated delivery networks consolidate procurement through regional pharmacy and therapeutics committees. Pricing stratifies across premium beta-3 agonists, standard extended-release anticholinergics, and economy-tier immediate-release generics differentiated by bioequivalence documentation quality. Cost compression in the generic tier is intensifying because FDA abbreviated new drug application scrutiny has extended pharmacokinetic trial timelines. Long-term care facilities demonstrate lowest price sensitivity due to caregiver-administered protocol requirements, while retail pharmacy channels exhibit highest sensitivity to Medicare Part D tier placement.
Supply Chain Analysis
Freight costs for temperature-controlled anticholinergic precursor shipments from Ludwigshafen and Leverkusen to North American formulation plants are elevating landed cost structures for European-sourced APIs. Active pharmaceutical ingredient concentration rests on Germany, Switzerland, and emerging Indian contract manufacturers in Hyderabad and Bangalore. Raw material dependencies include specialized chemical feedstocks for muscarinic antagonist synthesis, beta-3 adrenergic receptor ligand precursors, and estrogen base compounds for hormonal therapies. Single-source vulnerability in German and Swiss anticholinergic precursor manufacturing exposes procurement to disruption. Distribution runs through integrated delivery network central pharmacies replacing individual facility purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical sponsors can arbitrage cost differentials between FDA bioequivalence study requirements and CDSCO streamlined approval pathways for urology generics. German EMA MDR-aligned pharmacovigilance obligations impose documentation burdens that Indian contract research organizations avoid.
For Market Incumbents: Hedge anticholinergic margin erosion by accelerating backward integration into specialized chemical manufacturing for precursor reliability. Secure multi-source API agreements across three or more qualified manufacturers to mitigate single-source disruption risk from German and Swiss concentration. Prioritize R&D investment in beta-3 adrenergic agonist platforms where superior dry-mouth tolerability profiles sustain premium pricing against neuromodulation device substitution threats. For New Entrants and Emerging Players: Catholic health system networks across the American Southwest represent an underserved buyer archetype with unified protocols across 40-plus skilled nursing properties demanding caregiver-administered injectable formulations. Penetrate Japan's elderly care market where PMDA Asia-specific trial data requirements have limited current beta-3 agonist availability. Pursue topical estrogen development for postmenopausal stress incontinence with minimal pipeline competition from established antagonist platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among generic manufacturers with efficient bioequivalence documentation capabilities and established CDSCO approval track records. Long-term viability over the projection horizon rests on positioning for chronic management phase dominance as acute intervention volumes plateau. Watch for inflection upon Medicare reimbursement threshold adjustments favoring neuromodulation device alternatives over pharmacological therapy.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source API Agreement | Diversifies anticholinergic precursor sourcing across German, Swiss, and Indian qualified manufacturers. |
| Beta-3 Agonist Pipeline Expansion | Captures formulary preference in skilled nursing populations through superior dry-mouth tolerability profiles. |
| Injectable Formulation Development | Aligns product mix with Catholic health system unified protocols across 40-plus Southwest properties. |
| Asia-Specific Trial Investment | Satisfies PMDA distinct efficacy benchmarks for access to Japan's underpenetrated elderly population. |
| Topical Estrogen Platform | Addresses underserved postmenopausal stress incontinence mechanism with minimal current competition. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at integrated delivery networks, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare Part D formulary databases. Bottom-up prescription volume modeling and top-down market sizing triangulated across manufacturer revenue disclosures and distributor shipment data.
Segment-weighting approaches distributed value across anticholinergic, beta-3 agonist, and hormonal therapy product types; oral, injectable, topical, and intravesical delivery modes; and long-term care facility, hospital, homecare, and clinic end users throughout the forecast period. CAGRs derived from demographic trend extrapolation, reimbursement framework stability assessments, and therapeutic substitution elasticity modeling incorporated polypharmacy burden indices and neuromodulation device penetration curves as industry-specific inputs.
Inputs from FDA, EMA, and PMDA regulatory filings were available through the study window; gaps in real-world adherence data for cognitively impaired populations introduce uncertainty bands around chronic management phase volume projections. Forecasts reflect documented assumptions regarding Medicare reimbursement durability and beta-3 agonist formulary expansion velocity. A model refresh is warranted upon material change in FDA bioequivalence standards or neuromodulation device CMS coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Single Use Cystoscope Market
Urology
Urinary Bag Market
Urology
Europe Bladder Disorders Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Europe Urology Devices Market
Urology
Urology Lasers Market
Urology
Nordic Urinary Catheters Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Urology Robotic Surgery Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Voiding Cystourethrogram Market
Urology
North America Transrectal Ultrasound Market
Urology
Pyelonephritis Treatment Market
Urology
Ureter Cancer Treatment Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market