
 Europe Bladder Disorders Market | 2026-2036
Europe Bladder Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bladder Disorders Market Foresight
Germany is reconfiguring access patterns for advanced bladder disorder interventions through expanded ambulatory urology capacity. Medtronic leverages its established neuromodulation platform to sustain procedural pull-through across German hospital networks. Boston Scientific Corporation competes with differentiated sacral nerve stimulation systems optimized for outpatient deployment. Laborie anchors diagnostic workflow integration, positioning its urodynamics portfolio within streamlined referral pathways.
Bladder disorders encompass pathological conditions affecting urinary storage and voiding function, including overactive bladder, urinary incontinence, interstitial cystitis, and neurogenic bladder dysfunction, typically diagnosed through urodynamic testing, cystoscopy, and symptom scoring instruments. The primary purpose of intervention is restoration of continence, reduction of urgency-frequency episodes, and prevention of upper tract deterioration. Medications occupy the largest revenue pool despite patent erosion in antimuscarinic classes, while surgical devices represent the fastest-expanding margin segment driven by rechargeable implantable pulse generators. Urology clinics concentrate procedural volume for diagnostic equipment, though hospitals retain complex revision surgery and complication management.
The EU Medical Device Regulation and EMA pharmacovigilance frameworks are elevating clinical evidence requirements for implantable bladder disorder technologies, compressing timelines for market access. Germany's Federal Institute for Drugs and Medical Devices and France's ANSM coordinate national reimbursement assessments that determine regional adoption velocity for novel therapies. Stakeholders must monitor HTA convergence across France, Germany, and Italy to anticipate pricing and access trajectories for next-generation neuromodulation platforms.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing market access timelines for implantable neuromodulation systems, forcing manufacturers to front-load clinical evidence generation while Germany's ambulatory urology expansion redistributes procedural volume toward outpatient settings.
Growth Catalysts
- MDR clinical evidence mandates:The EU Medical Device Regulation elevates premarket data requirements for sacral nerve stimulators, creating competitive moats for firms with established trial infrastructure.
- Germany's ambulatory urology networks:Expanded clinic capacity for minimally invasive procedures is accelerating patient throughput for diagnostic and therapeutic interventions.
- France's reimbursement alignment:ANSM-coordinated national assessments for minimally invasive bladder disorder procedures are reducing patient out-of-pocket burdens and procedural delays.
Market Restraints
- Rechargeable battery supply concentration:Dependence on East Asian lithium-ion cell manufacturers exposes implantable pulse generator production to input volatility and logistics disruptions.
- Antimuscarinic patent erosion:Generic substitution in oral pharmacotherapy is compressing revenue pools for established pharmaceutical portfolios across European markets.
- MDR transition friction:Legacy device certifications under the Medical Devices Directive require costly technical file remediation to maintain market access.
Strategic Opportunities
- Italy's underpenetrated neuromodulation market:Regional reimbursement disparities create whitespace for targeted market development and physician education investments.
- Artificial intelligence and urodynamics convergence:Machine learning integration with diagnostic workflows promises automated pattern recognition and reduced specialist interpretation burden.
- Remote programming capabilities:Telemedicine-enabled device adjustment reduces patient travel requirements and expands addressable geography for implantable systems.
Industry Challenges
- Interventional neurourology skill scarcity:Sacral nerve lead placement requires specialized training that outpaces current fellowship pipeline output in several European markets.
- MDR notified body capacity constraints:Certification backlog for Class III implantable devices extends time-to-revenue for product iterations and line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bladder Disorders Market |
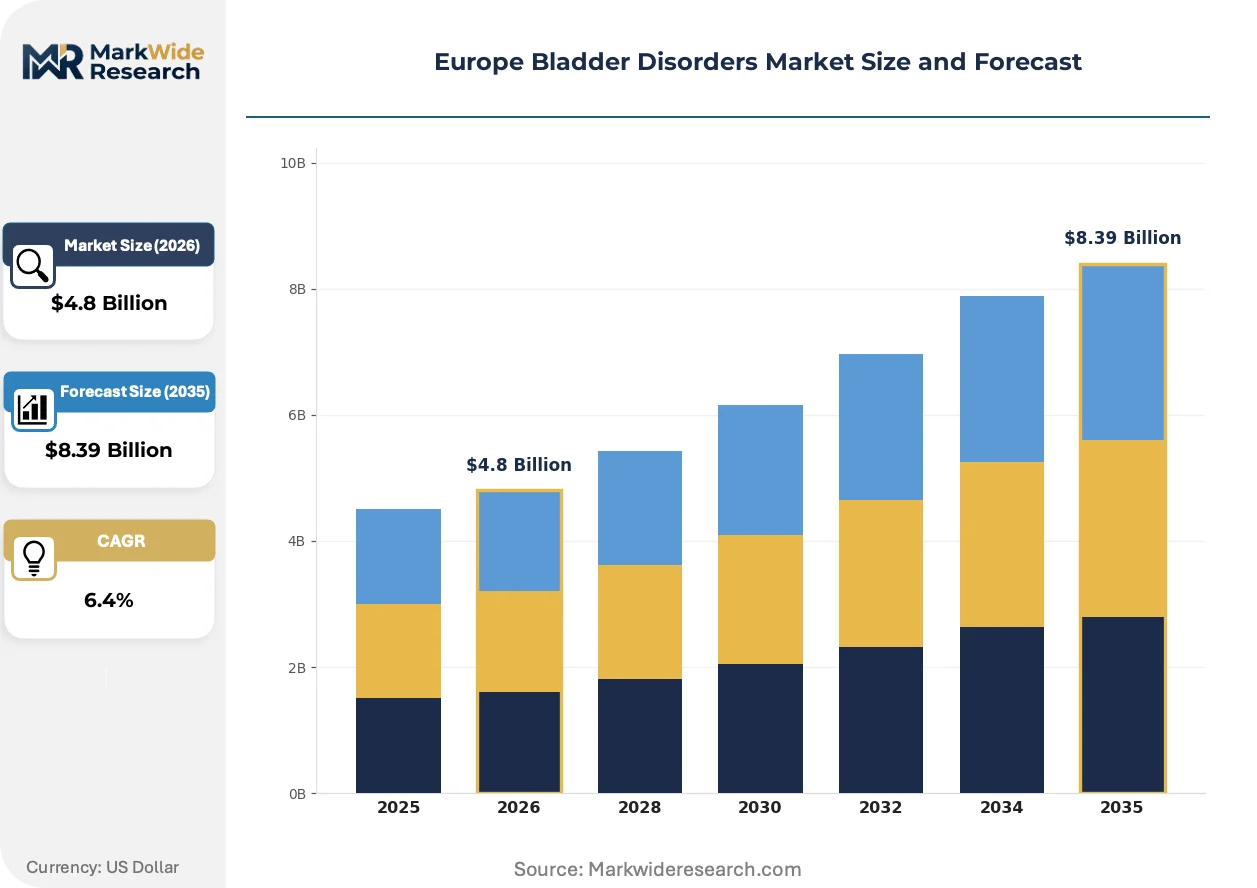
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Devices, Diagnostic Equipment, Catheters Application: Urology Clinics, Hospitals, Home Care, Rehabilitation Centers Delivery Mode: Oral, Intravenous, Topical, Inhalation End User: Healthcare Providers, Patients, Caregivers, Payers |
| Companies Covered | Medtronic, Laborie, Boston Scientific Corporation, Pfizer Inc., Astellas Pharma Inc., KYORIN Pharmaceutical Co., Ltd., Bristol-Myers Squibb Company, Johnson & Johnson Services, Inc., Axonics, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bladder Disorders Market Shifts & Advancements
Rechargeable implantable pulse generators are compressing the total cost of ownership for neuromodulation therapy while regulatory data requirements and care delivery models undergo parallel transformation across European markets.
Tibial nerve stimulation is collapsing the boundary between office-based and surgical intervention tiers. Urology clinics in Germany and France are adopting percutaneous posterior tibial nerve stimulation systems for patients who fail oral pharmacotherapy but resist implantable device commitment. This technology is collapsing the historical step-up pathway that funneled patients directly from medication to sacral nerve implantation.
The EU Medical Device Regulation's Post-Market Clinical Follow-up requirements are extending surveillance obligations for implantable bladder disorder technologies throughout device lifecycle. Manufacturers must now commit to systematic data collection beyond initial approval, elevating post-market infrastructure costs. High-risk implantable categories face the steepest compliance burden, with MDR technical documentation demands exceeding prior Directive thresholds substantially.
Hospital procurement consortia are consolidating purchasing authority for high-value urology devices across multi-site health systems. France's regional hospital groups and Germany's hospital federations are centralizing implantable neuromodulation contracting, displacing individual site negotiation autonomy. This concentration is most visible in France, where Groupements Hospitaliers de Territoire exercise expanded sourcing control over specialized urology interventions.
Europe Bladder Disorders Market Segmentation
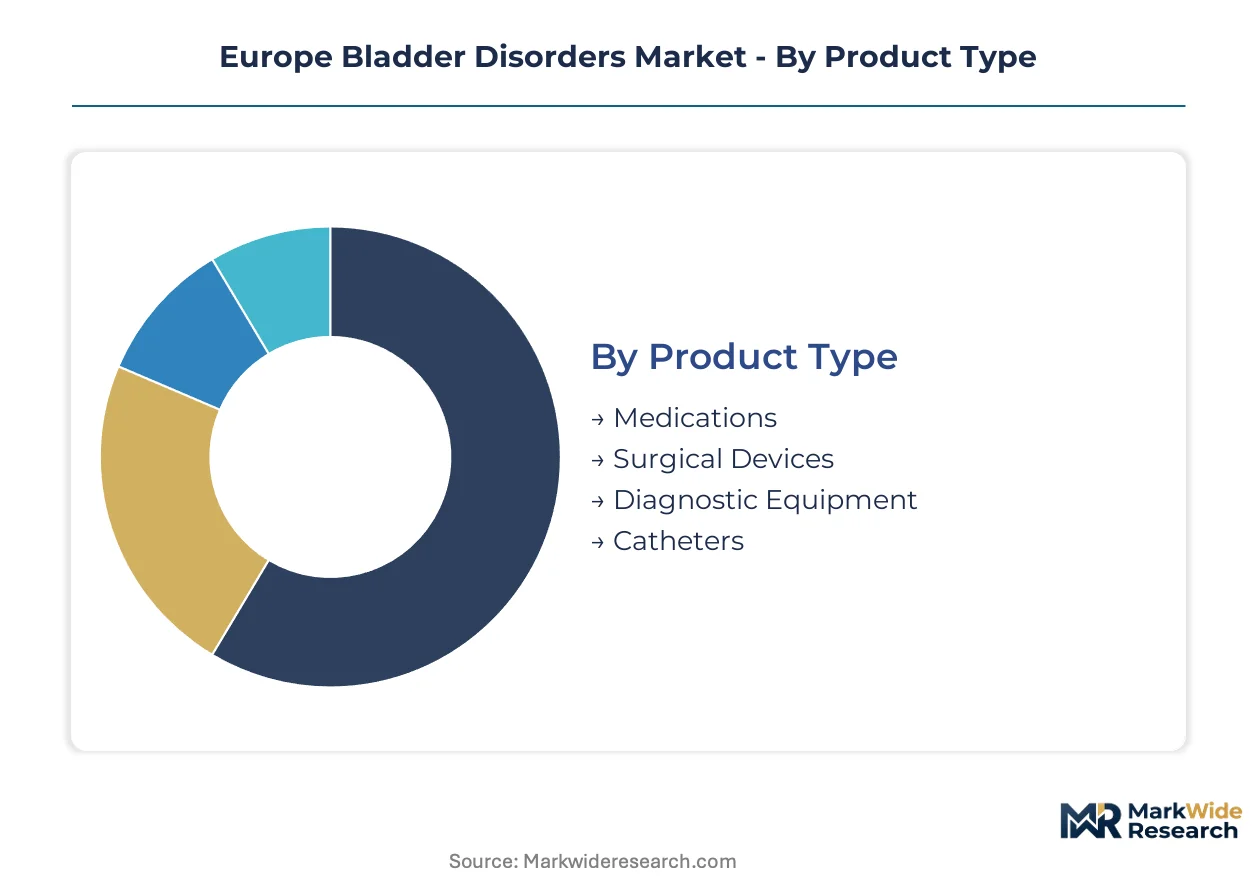
Segmentation in the Europe Bladder Disorders Market reveals divergent service intensity and procurement patterns across product and delivery categories. Manufacturers must align technical support infrastructure and reimbursement navigation capabilities to the specific demands of each segment cluster.
Product Type:
After-sales service intensity varies sharply across product categories, with implantable systems demanding multi-year technical support contracts and diagnostic equipment requiring calibration and software maintenance protocols.
- Medications:Oral antimuscarinics and beta-3 agonists constitute the volume base, with generic substitution eroding branded margins across German and French pharmacy reimbursement systems. France's ANSM pharmacovigilance requirements impose ongoing safety reporting obligations that sustain post-market infrastructure costs for manufacturers.
- Surgical Devices:Rechargeable implantable pulse generators and sacral nerve stimulation systems command premium pricing supported by specialized implantation training and remote programming capabilities. Germany's ambulatory urology expansion is redistributing implant volume toward outpatient surgical centers with compressed procedure timelines.
- Diagnostic Equipment:Urodynamics systems require intensive field service support for sensor calibration and software updates.
- Catheters:Intermittent and indwelling catheter lines operate on high-volume, low-margin economics with limited service attachment.
By volume, Medications leads. By growth pace, Surgical Devices is ahead.
Application:
Procurement authority concentrates differently across care settings, with hospital consortia exercising bulk purchasing power while urology clinics negotiate on speed-to-implant and technical training access.
- Urology Clinics:Specialized ambulatory facilities in Germany and France are capturing diagnostic workup and initial neuromodulation screening, creating demand for compact, office-deployable tibial nerve stimulation systems. Laborie's urodynamics portfolio anchors workflow integration within these referral pathways.
- Hospitals:Acute care institutions retain complex revision surgery, explant procedures, and complication management for implantable device patients. France's Groupements Hospitaliers de Territoire are centralizing high-value urology device contracting across multi-site systems.
- Home Care:Self-catheterization and remote device monitoring are expanding the addressable patient population beyond facility-based treatment.
- Rehabilitation Centers:Neurogenic bladder management in post-stroke and spinal cord injury populations requires coordinated urological and physical therapy protocols.
Urology Clinics capture the fastest volume expansion. Hospitals retain the highest per-procedure value concentration.
Delivery Mode:
Margin profiles diverge across administration routes, with oral formulations facing reimbursement compression while implantable and parenteral systems sustain pricing through procedural bundling.
- Oral:First-line pharmacotherapy dominates patient initiations but faces steep generic erosion in antimuscarinic classes across European markets.
- Intravenous:Botulinum toxin injections for refractory overactive bladder require specialist administration in hospital or clinic settings.
- Topical:Transdermal oxybutynin and local estrogen formulations address specific patient subpopulations with compliance or tolerability constraints.
- Inhalation:Emerging delivery technologies for bladder-targeted pharmacotherapy remain developmental with limited commercial presence.
Oral administration dominates patient volume. Intravenous delivery commands the highest reimbursement per treatment course.
End User:
Purchasing influence fragments across stakeholder groups, with healthcare providers driving product selection while payers increasingly condition reimbursement on demonstrated outcomes.
- Healthcare Providers:Urologists and specialized nurses exercise primary device selection authority, with Germany's expanding clinic networks amplifying physician preference influence.
- Patients:Direct purchasing concentrates in catheter self-supply and emerging remote monitoring subscriptions, with France's reimbursement alignment reducing out-of-pocket burdens for eligible interventions.
- Caregivers:Family members and home health aides influence catheter and containment product selection in long-term care contexts.
- Payers:Statutory health insurance funds in Germany and France are tightening prior authorization requirements for implantable neuromodulation systems.
Healthcare Providers control device selection. Payers are gaining leverage over access and pricing through outcomes-based reimbursement conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Implantable neuromodulation manufacturing concentrates in German and Swiss industrial clusters, while procedural demand distributes across aging populations in France, Germany, Italy, and the UK. The EU MDR is synchronizing certification requirements across member states, compressing national variation in market access timelines.
Germany
Ambulatory urology networks in Bavaria and North Rhine-Westphalia are absorbing diagnostic workup and initial neuromodulation screening from hospital settings. The Federal Institute for Drugs and Medical Devices coordinates reimbursement assessments that determine regional adoption velocity for novel therapies. Berlin-Brandenburg hosts specialized training centers addressing interventional neurourology skill scarcity.
France
ANSM-coordinated national assessments for minimally invasive procedures are reducing patient out-of-pocket burdens and accelerating procedural volumes. The Groupements Hospitaliers de Territoire exercise expanded sourcing control over specialized urology interventions across Île-de-France and Auvergne-Rhône-Alpes. Lyon and Marseille clusters concentrate revision surgery capacity for implantable device complications.
United Kingdom
NICE technology appraisals condition National Health Service funding for sacral nerve stimulation systems, creating staged access pathways. The Medicines and Healthcare products Regulatory Agency enforces MDR-aligned post-market surveillance for implantable pulse generators. London and Manchester academic medical centers anchor clinical trial recruitment for next-generation neuromodulation platforms.
Italy
Regional reimbursement disparities between Lombardy and southern regions create whitespace for targeted market development investments. The Italian Medicines Agency harmonizes pharmacovigilance reporting with EMA frameworks for antimuscarinic and beta-3 agonist therapies. Milan and Rome hospital networks concentrate complex neurogenic bladder management in post-stroke populations.
Netherlands
The Healthcare Institute's conditional reimbursement assessments prioritize demonstrated outcomes for implantable bladder disorder technologies. Randstad urology clinics are adopting percutaneous tibial nerve stimulation as an intermediate intervention tier. Eindhoven's medical technology corridor supports component sourcing for diagnostic equipment manufacturers.
Europe Bladder Disorders Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and battery supply. The vendor base stratifies across three tiers: multinational neuromodulation platforms with established European trial infrastructure, mid-cap diagnostic equipment specialists with intensive field service networks, and generic pharmaceutical manufacturers facing margin compression. Strategic moves concentrate on M&A for MDR-compliant technical files and partnerships for ambulatory care channel access.
Within the implantable systems tier, Medtronic and Boston Scientific Corporation occupy positions sustained by rechargeable pulse generator portfolios and remote programming capabilities. Laborie exemplifies the diagnostic equipment archetype with workflow-integrated urodynamics systems deployed across German and French clinic networks. Axonics, Inc. represents the emerging challenger structure, competing through differentiated device architectures optimized for outpatient deployment.
| Leading Market Players |
|---|
| Medtronic |
| Laborie |
| Boston Scientific Corporation |
| Pfizer Inc. |
| Astellas Pharma Inc. |
| KYORIN Pharmaceutical Co., Ltd. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson Services, Inc. |
| Axonics, Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on East Asian lithium-ion cell manufacturers exposes implantable pulse generator production to input volatility that compresses both premium-tier margins and mid-tier pricing flexibility while forcing European assemblers into dual-sourcing configurations.
Pricing Analysis
The EU Medical Device Regulation dictates the pricing tier structure across implantable neuromodulation systems, with MDR certification grade separating premium rechargeable pulse generators from standard non-rechargeable alternatives and economy-tier diagnostic catheters. Price differentiation rests on battery longevity specifications and remote programming capability bundling. Cost compression in the oral pharmacotherapy tier is intensifying because antimuscarinic patent erosion accelerates generic substitution. Healthcare payers exhibit the highest price sensitivity, while hospital procurement consortia leverage volume scale for implantable device discounts.
Supply Chain Analysis
Export-control restrictions on advanced battery management semiconductors limit component flows into European manufacturing facilities, constraining production scalability for next-generation implantable systems. Supply concentration centers on China, South Korea, and Japan for lithium-ion cells, rare-earth magnets, and specialized sensor substrates. Raw material dependencies span cobalt cathodes, nickel-manganese formulations, and medical-grade silicone encapsulants. Single-source vulnerability in solid-state battery prototyping creates qualification bottlenecks. Distribution runs through hospital procurement consortia and specialized urology clinic networks with direct manufacturer field service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Bladder Disorders Market represents an early-cycle expansion story where ambulatory urology network buildout in Germany and France creates procedural capacity that outpaces current neuromodulation penetration rates.
For Market Incumbents: Build regulatory evidence moats through systematic Post-Market Clinical Follow-up infrastructure that satisfies MDR surveillance obligations for implantable pulse generators. Deepen backward integration into rechargeable battery cell qualification to reduce East Asian supply exposure. Anchor hospital system partnerships through training center accreditation that addresses interventional neurourology skill scarcity. For New Entrants and Emerging Players: Pursue Italy's regional reimbursement disparities as the most penetrable geography, where Lombardy's coverage precedents contrast with southern region whitespace. Target percutaneous tibial nerve stimulation as an intermediate intervention tier that collapses the historical medication-to-implant step-up pathway. Deploy office-deployable system architectures that align with German ambulatory clinic workflow requirements. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors platform integrators with MDR-compliant technical files and established European trial infrastructure. Long-term viability over the next decade hinges on remote programming capability maturation and AI-integrated diagnostic workflow positioning. Monitor ANSM reimbursement alignment velocity in France as the signal for regional adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Remediation | Legacy device certifications under the Medical Devices Directive require costly updates to maintain EU market access. |
| Ambulatory Clinic Partnership | German urology network expansion redistributes procedural volume toward outpatient surgical centers. |
| Rechargeable IPG Development | Battery longevity improvements compress total cost of ownership and justify premium positioning. |
| Remote Programming Capability | Telemedicine-enabled device adjustment reduces patient travel requirements and expands addressable geography. |
| AI-Urodynamics Integration | Machine learning diagnostic workflows promise automated pattern recognition and reduced specialist burden. |
Research Methodology
A spread of perspectives from urology clinic directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions that shape this analysis. Primary fieldwork combined structured interviews with secondary validation through EMA submission databases, hospital procurement records, ANSM reimbursement assessments, and clinical trial registries. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segment-level CAGRs derived from procedure volume trajectories and pricing elasticity patterns. Segmentation dimensions spanned product type, application setting, delivery mode, and end-user purchasing influence. Forecast inputs incorporated EU MDR transition timelines, ambulatory capacity expansion rates, and regional reimbursement alignment velocity.
Macroeconomic conditions sit as an overlay; deviation in eurozone healthcare expenditure growth or East Asian battery supply disruptions would shift the trajectory. Forecasts reflect documented assumptions regarding MDR notified body capacity and national HTA convergence timelines. Material shifts in EU Medical Device Regulation enforcement stringency or France's ANSM reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Chronic Pyelonephritis Treatment Market
Urology
Urinary Bag Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Urology Devices Market
Urology
Self-Intermittent Catheters Market
Urology
Single Use Cystoscope Market
Urology
Global Lithotripsy Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Transrectal Ultrasound Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Urology Surgery Supplies Market
Urology
Continence Care Market
Urology
US Urology Devices Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Urinary Incontinence Treatment Drugs Market