
 Catheter-Associated Urinary Tract Infections Treatment Market | 2026-2036
Catheter-Associated Urinary Tract Infections Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Catheter-Associated Urinary Tract Infections Treatment Market Outlook
Project finance for hospital antimicrobial stewardship programs is tilting competitive advantage toward suppliers with asset-light service models. Coloplast A/S leverages its specialized urology portfolio to sustain premium positioning in catheter coating technologies. Teleflex Incorporated anchors its presence through intensive R&D in infection-resistant materials. Pfizer Inc. competes via broad antibiotic manufacturing scale that supports institutional procurement contracts.
Catheter-associated urinary tract infections treatment encompasses antimicrobial therapies, antiseptic irrigation protocols, and engineered catheter systems designed to prevent biofilm formation on polymer surfaces; its primary purpose is reducing morbidity, length of hospital stay, and antimicrobial resistance in catheterized patients. Antibiotics within the product type segment still occupy the largest revenue pool despite narrowing formularies, while catheter-based prevention devices represent the fastest-growing margin category as hospitals shift toward prophylactic expenditure. The end user dimension shows hospitals dominating absolute volume, though home care delivery is extending fastest as discharge protocols accelerate.
The FDA enforces stringent premarket notification requirements for antimicrobial-coated catheters, while the EPA regulates residual antiseptic concentrations in irrigation solutions; both frameworks elevate compliance costs but simultaneously lock out low-standard imports. CMS hospital-acquired condition reduction programs directly shape demand by penalizing facilities with elevated CAUTI rates. Stakeholders must monitor whether FDA guidance on novel biofilm-resistant coatings will create accelerated review pathways or extend evidentiary requirements for device-drug combinations.
Market Dynamics
Medicare reimbursement penalties for hospital-acquired conditions are compressing margins and forcing procurement departments toward prophylactic device expenditure rather than reactive antibiotic therapy.
Growth Catalysts
- CMS Hospital-Acquired Condition Reduction Program:Financial penalties for elevated CAUTI rates drive hospital investment in antimicrobial-coated catheters and irrigation protocols. Facilities prioritize prevention to avoid reimbursement cuts.
- Biofilm-resistant polymer engineering:Advances in surface modification chemistry reduce bacterial adhesion on indwelling catheter surfaces. Academic medical centers adopt these devices for high-risk surgical populations.
- Home care discharge acceleration:Post-acute care protocols shift catheter management from inpatient wards to outpatient settings. This expands demand for patient-administered antiseptic irrigation systems.
Market Restraints
- Silver and chlorhexidine input cost volatility:Antimicrobial coating materials face supply concentration from specialty chemical producers. Price swings compress device manufacturer margins.
- FDA premarket notification requirements:Antimicrobial-coated catheters face stringent evidentiary thresholds for safety and efficacy. Review timelines extend product development cycles.
- Antibiotic stewardship narrowing:Institutional formularies restrict fluoroquinolone and cephalosporin use for uncomplicated CAUTI. This limits revenue from traditional pharmaceutical therapy.
Strategic Opportunities
- Long-term acute care hospitals:LTACHs with extended catheterization durations represent underpenetrated demand for subscription-based device replacement programs.
- Combination device-drug pathways:FDA guidance on novel biofilm-resistant coatings may create accelerated review frameworks. Early entrants capture preferential formulary placement.
- Telehealth-integrated catheter monitoring:Remote patient monitoring platforms enable real-time infection risk scoring. Home health agencies adopt these bundled service models.
Industry Challenges
- Clinical microbiology talent scarcity:Hospital laboratories face shortages of specialists trained in biofilm detection and resistance profiling. Diagnostic delays compromise stewardship program effectiveness.
- Legacy electronic health record integration:CAUTI surveillance modules require costly customization within entrenched hospital information systems. Implementation timelines stretch 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catheter-Associated Urinary Tract Infections Treatment Market |
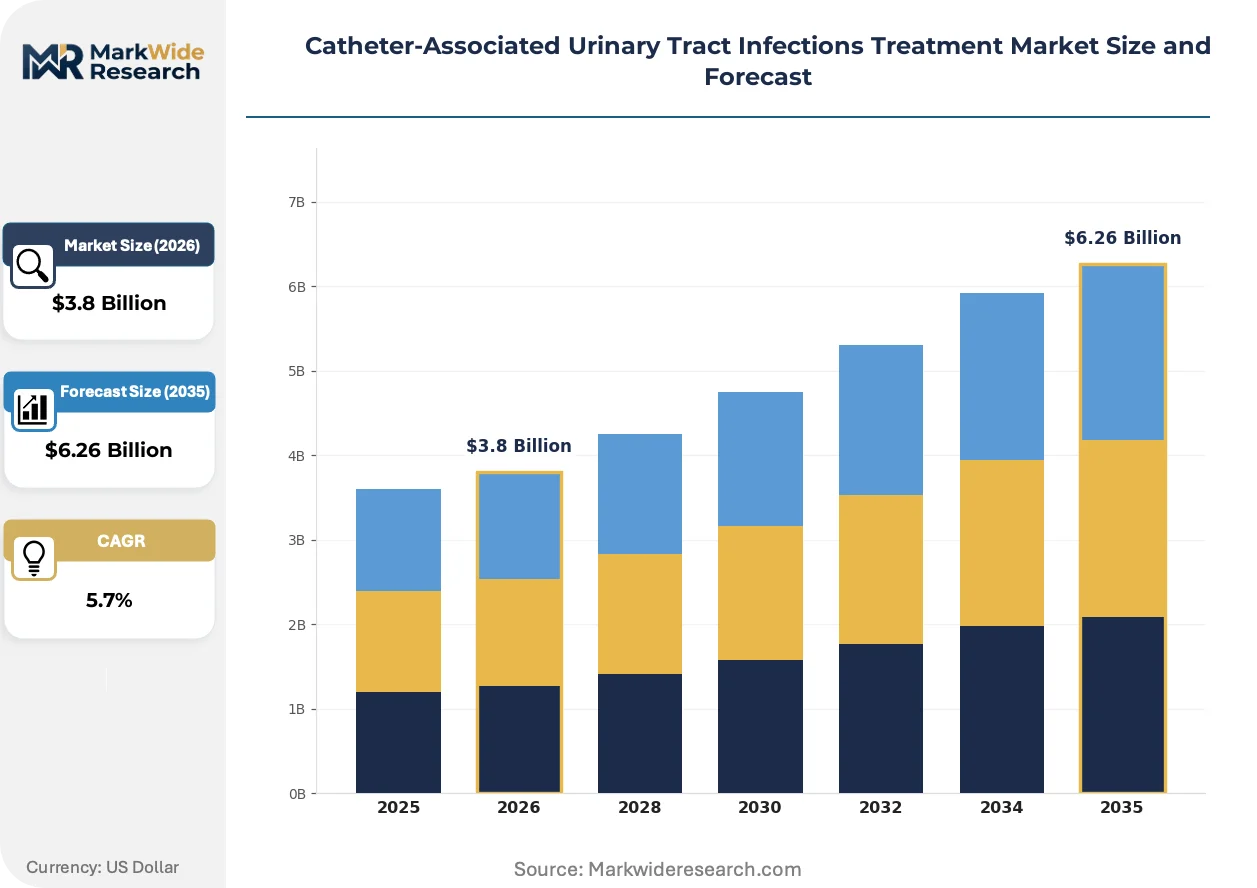
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiseptics, Catheters, Bolsters Application: Infection Control, Pain Management, Surgical Intervention, Patient Care End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Injectables, Oral Tablets, Topical Solutions, Intravenous |
| Companies Covered | Coloplast A/S, Teleflex Incorporated, Cook Medical, Medline Industries, Hollister Incorporated, Merck & Co., Inc., Pfizer Inc., Bayer AG, ConvaTec Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catheter-Associated Urinary Tract Infections Treatment Market Strategic Shifts
Active materials science and reimbursement engineering are converging to displace reactive treatment models with embedded prevention architectures across the catheter care continuum.
Antimicrobial-eluting polymer matrices is migrating from experimental coatings to standard-of-care specifications for indwelling urinary devices. Academic medical centers in the United States and Germany now mandate silver-alloy or nitrofurazone-impregnated catheters for anticipated durations exceeding 48 hours. This migration is compressing demand for conventional latex and silicone alternatives while elevating raw material specifications across supplier tiers.
The EPA's updated residual antiseptic concentration limits for irrigation solutions tighten environmental discharge standards for hospital wastewater systems. Manufacturers reformulate povidone-iodine and chlorhexidine blends to meet effluent thresholds without compromising antimicrobial efficacy. Dialysis centers and ambulatory surgery units face the steepest compliance costs as they retrofit drainage infrastructure.
Hospital procurement departments consolidate vendor relationships through integrated device-antibiotic contracting frameworks. Single-source agreements bundle catheter supply with formulary commitment to specific antimicrobial agents. This concentration is most visible in United States health systems responding to CMS bundled payment models for surgical episodes.
Catheter-Associated Urinary Tract Infections Treatment Market Segmentation
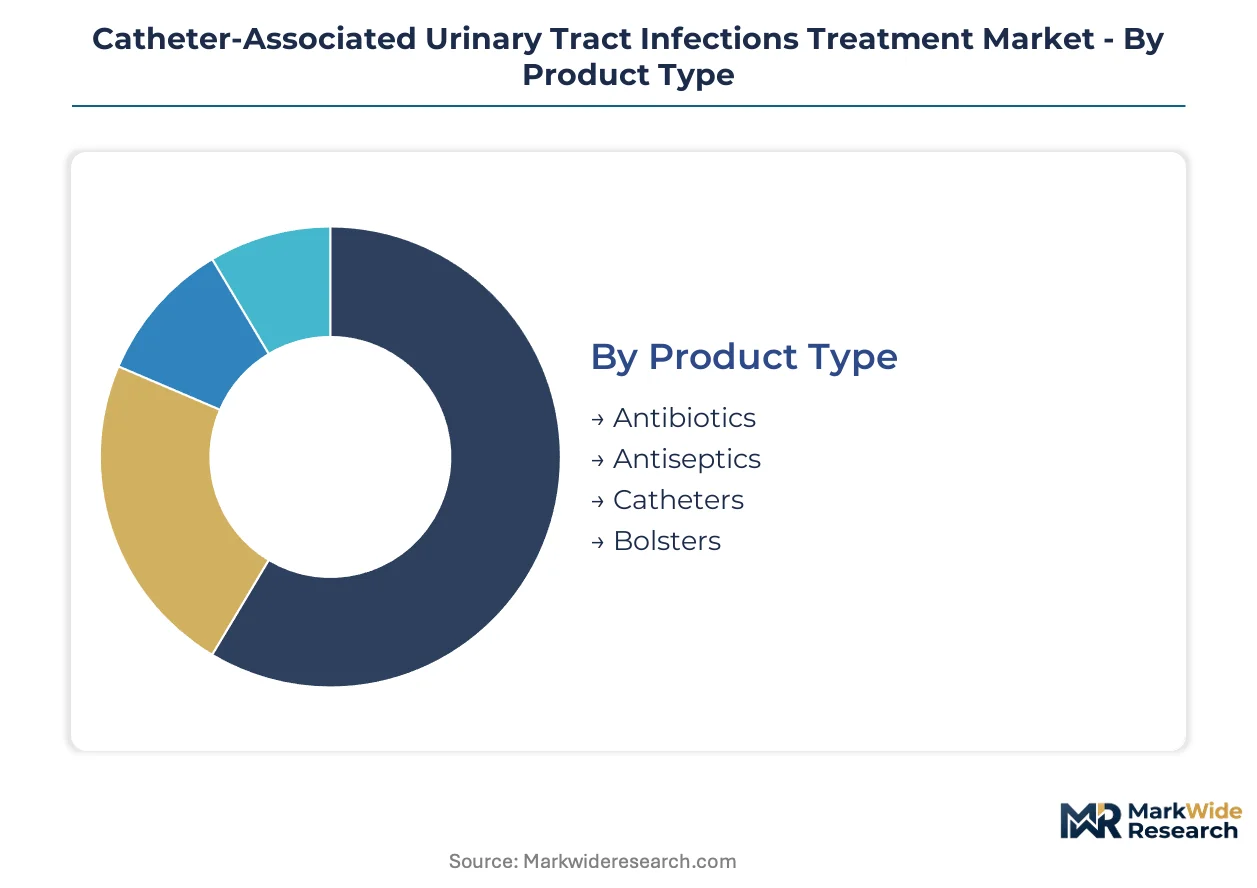
CAUTI treatment markets fragment across therapeutic modality, care setting, and administration route. Each segment demands distinct regulatory navigation and procurement economics. Understanding these fault lines reveals where margin pools concentrate and where commoditization pressures bite hardest.
Product Type:
After-sales service intensity varies sharply across this dimension—catheter systems require clinical training support and replacement logistics, while pharmaceutical therapies operate on formulary contracting alone.
- Antibiotics:Systemic agents including fluoroquinolones, cephalosporins, and aminoglycosides target established infections. Hospital formularies in the United States restrict their use for uncomplicated CAUTI under stewardship protocols, compressing volume but preserving acute-care premium pricing.
- Antiseptics:Irrigation solutions and catheter maintenance formulations containing chlorhexidine or povidone-iodine. Home care agencies in Germany and Japan adopt these for patient-administered protocols as discharge acceleration shifts infection prevention outside institutional walls.
- Catheters:Engineered devices with antimicrobial-eluting polymer matrices or silver-alloy coatings. FDA premarket notification requirements for novel biofilm-resistant surfaces extend development timelines but lock in premium positioning for compliant manufacturers.
- Bolsters:Stabilization accessories securing catheter placement and reducing mechanical irritation. These command lower unit economics but integrate into bundled procedural kits favored by United States health systems under CMS surgical episode payments.
By volume, antibiotics lead. By growth pace, catheters with engineered surfaces are expanding most quickly.
Application:
Cost tier stratification separates acute intervention from maintenance protocols, with surgical settings commanding premium device specifications and long-term care accepting standard alternatives.
- Infection Control:Prophylactic and therapeutic measures targeting biofilm prevention and bacterial clearance. Academic medical centers in the United States mandate antimicrobial-coated devices for anticipated catheterization exceeding 48 hours, elevating specification requirements.
- Pain Management:Adjunctive therapies addressing urethral irritation and procedural discomfort. These attach to catheterization kits as secondary revenue streams with limited standalone procurement.
- Surgical Intervention:Perioperative catheterization protocols in operating theaters and post-anesthesia units. Bundled payment models in United States Medicare concentrate purchasing authority within health system procurement departments.
- Patient Care:Routine maintenance and hygiene protocols across general medical wards. Standardization pressures here favor commodity suppliers with scale manufacturing.
By revenue concentration, infection control dominates. By margin expansion, surgical intervention offers the steepest trajectory.
End User:
Customer type determines contracting complexity—hospitals negotiate enterprise agreements while home care channels fragment across regional distributors.
- Hospitals:Inpatient facilities with intensive care units, surgical services, and emergency departments. CMS Hospital-Acquired Condition Reduction Program penalties directly shape their procurement priorities toward prevention expenditure.
- Clinics:Outpatient facilities including ambulatory surgery centers and urology practices. These sites favor disposable catheter systems with minimal processing infrastructure.
- Home Care:Post-acute settings where patients or caregivers manage catheterization. Discharge protocol acceleration in the United States and Western Europe expands demand for patient-administered irrigation systems.
- Rehabilitation Centers:Long-term acute care and skilled nursing facilities with extended catheterization durations. These represent underpenetrated demand for subscription-based device replacement programs.
By absolute volume, hospitals lead. By expansion velocity, home care is gaining share fastest.
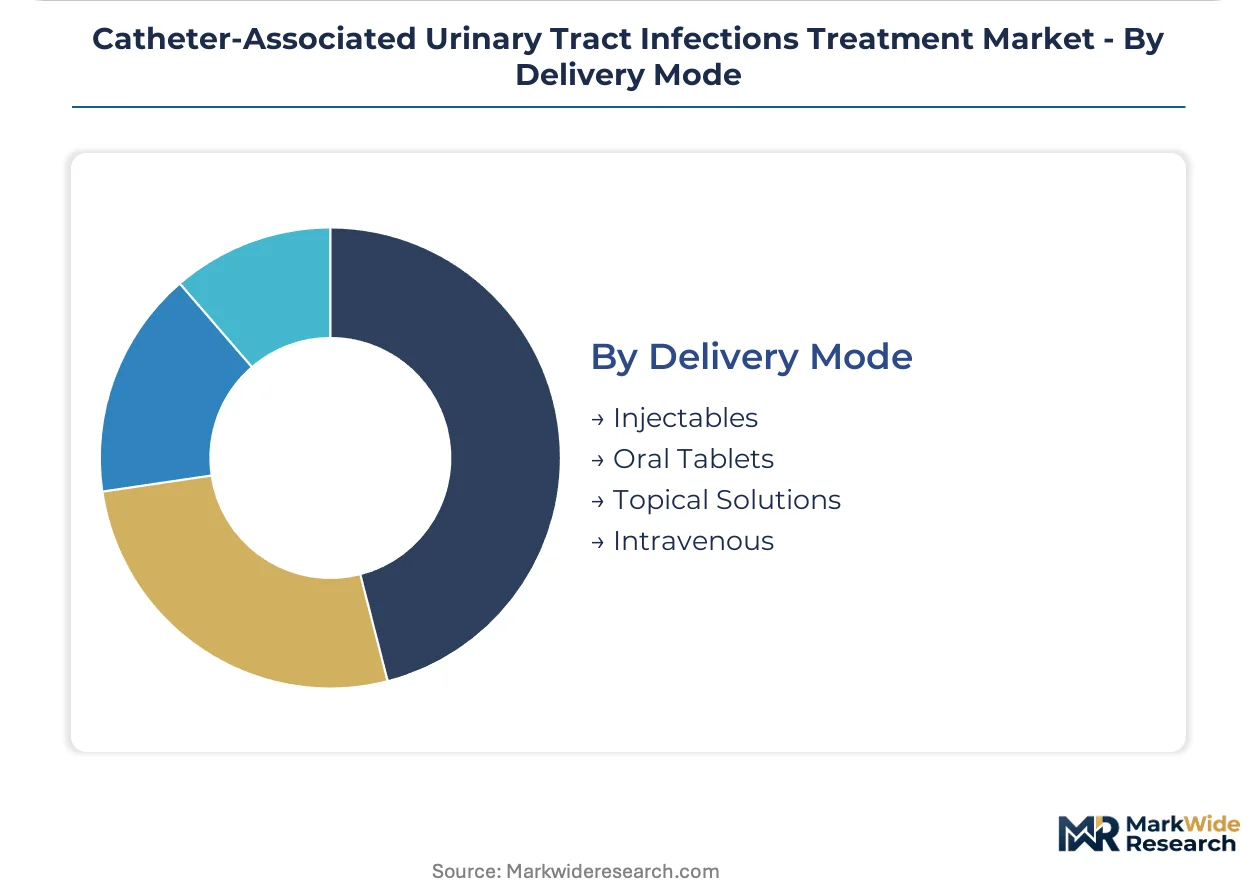
Delivery Mode:
Supply concentration aligns with administration route complexity—parenteral forms require sterile manufacturing infrastructure that oral and topical alternatives bypass.
- Injectables:Parenteral antibiotics administered intramuscularly for severe or refractory infections. Manufacturing concentration among specialized sterile facilities limits supplier base.
- Oral Tablets:Systemic agents for uncomplicated outpatient infections. Stewardship narrowing restricts formularies, shifting volume toward narrow-spectrum alternatives.
- Topical Solutions:Irrigation and instillation formulations for catheter maintenance. EPA residual antiseptic concentration limits for hospital wastewater discharge force reformulation to meet effluent thresholds.
- Intravenous:Hospital-administered therapy for septic or high-risk patients. This channel preserves premium pricing but faces length-of-stay reduction pressures.
By utilization frequency, oral tablets lead. By value per course, intravenous administration maintains the highest tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where Medicare penalties for hospital-acquired conditions drive premium device procurement, while cost-sensitive procurement in emerging markets compresses margins toward commodity tiers.
United States
Hospital procurement departments prioritize antimicrobial-coated catheters to avoid CMS Hospital-Acquired Condition Reduction Program penalties. The FDA enforces stringent premarket notification requirements for novel biofilm-resistant coatings. Academic medical centers in Boston and the Research Triangle mandate silver-alloy devices for catheterizations exceeding 48 hours.
Germany
Home care agencies adopt patient-administered antiseptic irrigation systems as discharge protocols accelerate. The EMA coordinates with national regulators on device-drug combination frameworks. Medical technology clusters in Baden-Württemberg and Bavaria drive surface modification chemistry advances for polymer engineering.
Japan
Aging demographics expand long-term catheterization demand in skilled nursing facilities. METI promotes domestic manufacturing of infection-resistant materials through industrial policy incentives. Tokyo and Osaka medical device corridors concentrate R&D investment in antimicrobial-eluting matrices.
United Kingdom
NHS procurement consolidation favors integrated device-antibiotic contracting frameworks. MHRA aligns with EMA guidance on biofilm-resistant coating evidentiary standards. London and Cambridge health systems pilot subscription-based catheter replacement programs for extended-care populations.
China
Hospital infrastructure expansion in tier-2 and tier-3 cities creates demand for standardized prevention protocols. NMPA tightens registration requirements for antimicrobial-coated devices. Manufacturing clusters in Jiangsu and Zhejiang provinces scale production of silver-alloy catheter components for domestic and export markets.
Catheter-Associated Urinary Tract Infections Treatment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in coating chemistry and polymer substrates. Market structure tilts toward consolidated procurement contracting as health systems bundle device supply with formulary commitments. Three archetypes dominate: diversified medical device conglomerates with urology portfolios, specialized catheter engineering firms, and pharmaceutical manufacturers with institutional antibiotic contracts. Competitive moves concentrate on vertical integration into coating material supply and strategic partnerships with antimicrobial stewardship program consultants.
Among diversified device manufacturers, Coloplast A/S and Teleflex Incorporated occupy positions spanning engineered catheter systems and clinical training infrastructure. Pfizer Inc. anchors the pharmaceutical tier through manufacturing scale that supports enterprise procurement agreements. These three exemplify how market participants align with distinct value capture mechanisms—device premiumization, service bundling, and formulary lock-in respectively.
| Leading Market Players |
|---|
| Coloplast A/S |
| Teleflex Incorporated |
| Cook Medical |
| Medline Industries |
| Hollister Incorporated |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Bayer AG |
| ConvaTec Group PLC |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese silver-alloy catheter component manufacturing is compressing supplier margins and forcing tier-2 producers toward aggressive spot pricing, while simultaneously enabling US and European device manufacturers to extract volume discounts that reshape procurement economics across the CAUTI treatment continuum.
Pricing Analysis
The customization-premium spread between configured-to-order antimicrobial-coated catheters and standard silicone alternatives spans three distinct tiers: silver-nitrofurazone matrix devices command the highest bracket, chlorhexidine-impregnated mid-range systems occupy the middle, and uncoated commodity catheters sit at the base. Price differentiation rests on FDA premarket notification tier and clinical validation depth, with academic medical centers showing lowest sensitivity to unit cost when bundled payment models absorb device expenditure. Cost compression in the commodity tier is intensifying because Jiangsu and Zhejiang manufacturers are absorbing silver input volatility to maintain market share.
Supply Chain Analysis
Export-control regime scrutiny on advanced polymer surface modification technologies limits flow of proprietary biofilm-resistant coating chemistries from German and Japanese specialty chemical producers to unlicensed third-country manufacturers. Geographic supply concentration centers on China for silver-alloy components, the United States for nitrofurazone-impregnated matrices, and Germany for surface modification reagents. Raw material dependencies include silver nanoparticles, chlorhexidine gluconate, and medical-grade silicone elastomers. Single-source vulnerability in silver supply from concentrated mining operations in Peru and Mexico elevates input cost risk. Distribution runs through health system procurement departments consolidating vendor relationships under enterprise agreements.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CAUTI treatment market sits in early-cycle expansion as Medicare reimbursement penalties for hospital-acquired conditions accelerate prophylactic device adoption ahead of traditional antibiotic therapy curves.
For Market Incumbents: Insulate premium positioning by securing captive supply of silver-alloy substrates through backward integration into Chinese component manufacturing, while simultaneously embedding clinical training infrastructure into hospital contracts to raise switching costs against emerging coating-technology competitors. FDA premarket notification timelines for novel biofilm-resistant surfaces represent the critical regulatory moat requiring sustained investment. For New Entrants and Emerging Players: Long-term acute care hospitals in the United States with extended catheterization durations represent the most penetrable entry point, offering subscription-based device replacement programs absent entrenched incumbent relationships. Home care agencies in Germany and Japan managing patient-administered irrigation protocols present secondary white-space opportunity. A telehealth-integrated catheter monitoring platform bundled with antiseptic delivery systems offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized catheter engineering firms with hospital system partnership density and replacement logistics infrastructure. Long-term viability across the projection horizon favors acquisition targets with FDA-cleared antimicrobial-eluting matrices and established formulary placement in CMS penalty-exposed health systems. The signal to watch is EPA guidance tightening on residual antiseptic discharge thresholds, which would force rapid reformulation investment and consolidate advantage among compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial-Coating R&D Partnership | Teleflex and academic medical centers in Boston co-develop next-generation biofilm-resistant polymer matrices. |
| Hospital System Enterprise Contracting | Coloplast secures multi-year sole-source agreements bundling catheter supply with stewardship program consulting. |
| Home Care Distribution Expansion | Medline Industries builds direct-to-agency logistics for patient-administered irrigation systems in Germany. |
| Regulatory Fast-Track Positioning | Cook Medical aligns FDA submission strategy with anticipated guidance on novel coating evidentiary standards. |
| Silver Supply Backward Integration | Hollister Incorporated acquires Jiangsu-based component manufacturer to stabilize input cost exposure. |
Study Parameters
A spread of perspectives from hospital procurement directors, biomedical engineering leads, infection control specialists, and antimicrobial stewardship program managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, CMS Hospital-Acquired Condition Reduction Program penalty data, EPA residual antiseptic concentration guidance, and hospital GPO contract databases. Bottom-up demand modeling across product type, application, end user, and delivery mode segments was triangulated against top-down macro healthcare expenditure trajectories.
Demand-supply-balance dynamics across the projection horizon anchored the analytical framework, with segmentation dimensions spanning therapeutic modality, care setting, administration route, and regional regulatory cluster. CAGRs were derived from installed base projections for indwelling catheter utilization, CMS penalty exposure calculations, and antimicrobial stewardship program adoption curves. Industry-specific forecast inputs included silver price volatility indices and FDA premarket notification approval velocity.
Stress conditions across silver input cost spikes, EPA effluent threshold tightening, and Medicare penalty program expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on hospital discharge protocol acceleration and home care channel development. Material shifts in FDA guidance on device-drug combination review pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Uraemia Treatment Market
Urology
Male Urinary Incontinence Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Europe Urology Devices Market
Urology
Genitourinary Cancers Treatment Market
Urology
Global Bladder Scanner Market
Urology
Urology Devices Market
Urology
Ureteral Obstruction Market
Urology
Obstructive Uropathy Treatment Market
Urology
Penile Cancer Market
Urology
Urinary Retention Therapeutics Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
Urology Laser Fibers Market
Urology
Urology Disposables Market
Urology
Global Castrate Resistant Prostate Cancer Market