
 Security Guard Market | 2026-2036
Security Guard Market Size, Share, and Industry Trends Forecast 2026-2036
Security Guard Market Intelligence
AI-powered video analytics is narrowing the functional gap between human guards and automated surveillance, yet physical presence remains irreplaceable for de-escalation and access control. Securitas AB leverages its global footprint to anchor enterprise contracts across multiple continents. Allied Universal dominates North American commercial real estate through vertical integration of technology and manpower. G4S competes in critical infrastructure and government segments with specialized training protocols.
Security guard services encompass trained personnel deployed for asset protection, access control, and incident response, typically operating under contractual arrangements with defined patrol routes, shift coverage, and escalation protocols. The primary commercial purpose centers on deterrence, real-time threat mitigation, and compliance with insurance and regulatory requirements for physical security presence. On-site guarding commands the largest revenue pool due to persistent demand from commercial and industrial clients, while remote monitoring represents the fastest-expanding segment as cloud-connected surveillance reduces marginal labor costs. Event security maintains premium pricing during peak seasons but faces cyclical volume constraints.
FAA regulations govern airport security staffing minimums, while OSHA standards shape workplace violence prevention protocols that drive industrial guard deployment. The EU AI Act imposes human oversight requirements on automated surveillance systems, reinforcing demand for hybrid guard-technology service models. Stakeholders must weigh capital allocation between biometric access control integration and workforce training programs as regulatory thresholds for technology accountability tighten across jurisdictions.
Market Dynamics
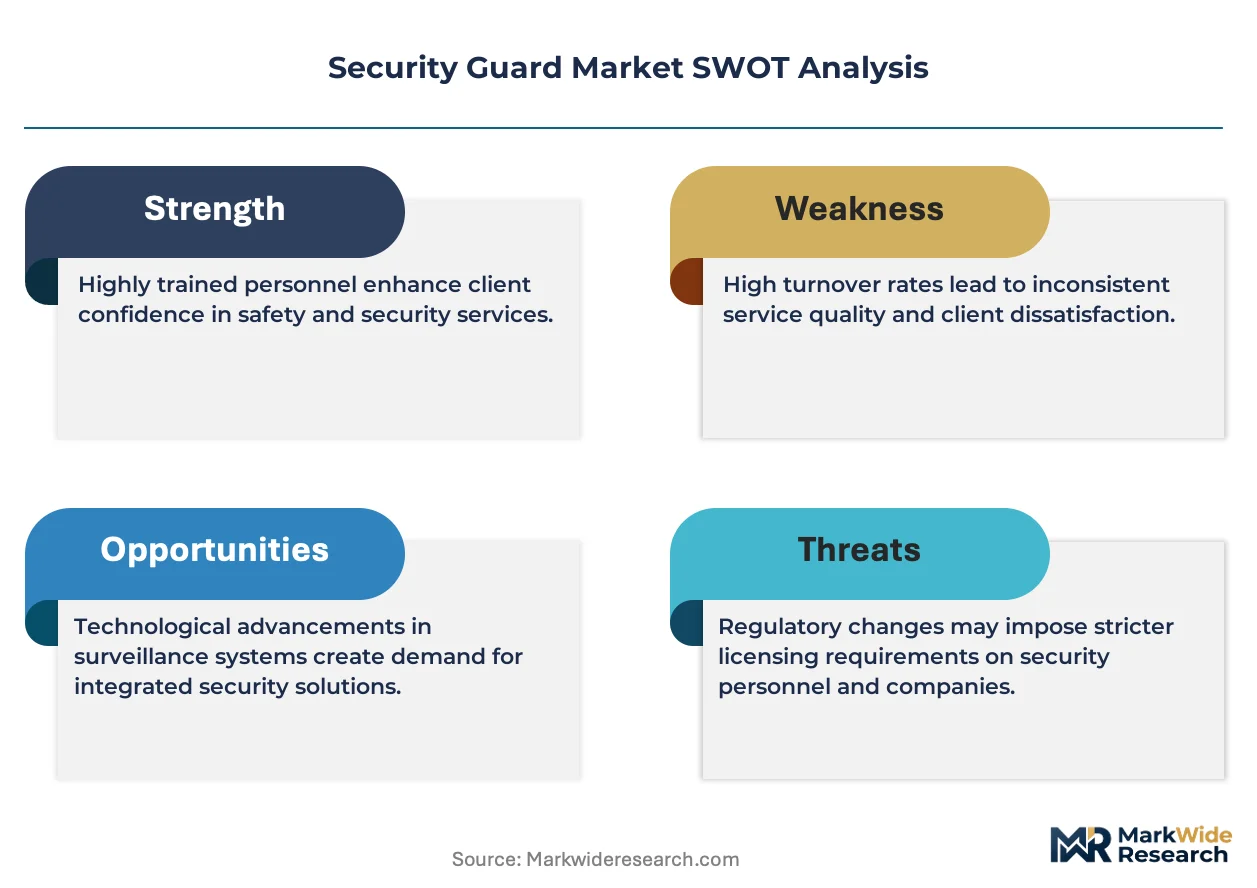
Hybrid human-technology service models are restructuring competitive economics across the security guard industry as the EU AI Act and similar frameworks mandate human oversight over automated surveillance, forcing providers to rebalance labor-technology cost structures.
Growth Catalysts
- Critical infrastructure expansion:Energy facilities and data centers across Texas, California, and Florida metro corridors are scaling manned guarding budgets to meet insurance and regulatory physical presence requirements.
- GDPR and EU AI Act compliance:European data protection rules are reinforcing demand for hybrid guard-technology deployments where trained personnel supervise algorithmic surveillance outputs.
- Workplace violence prevention mandates:OSHA protocols are driving industrial manufacturing and logistics clients to expand on-site security staffing for employee safety compliance.
Market Restraints
- Labor cost inflation:Wage pressure in major US metropolitan markets is compressing guard service margins without commensurate pricing power in commoditized segments.
- AI-powered video analytics substitution:Cloud-connected surveillance with remote monitoring capabilities is displacing low-complexity guarding posts in retail and commercial real estate.
- Regulatory fragmentation:Divergent licensing requirements across US states and EU member countries inflate compliance overhead for multi-jurisdictional providers.
Strategic Opportunities
- Event security premiumization:Sports venues and entertainment complexes in Florida and California are expanding specialized crowd management contracts during peak seasons.
- Biometric access control integration:Convergence of facial recognition systems with guard-managed entry protocols creates high-margin hybrid service bundles for corporate campuses.
- German critical infrastructure:The EU NIS2 Directive is accelerating demand for certified security personnel at energy, transport, and healthcare facilities across German federal states.
Industry Challenges
- Specialized de-escalation training gaps:Guard firms struggle to recruit and retain personnel with certified crisis intervention skills for healthcare and educational institutions.
- Legacy access control integration:Retrofitting biometric and mobile credential systems into existing building infrastructure requires capital-intensive site-by-site customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Guard Market |
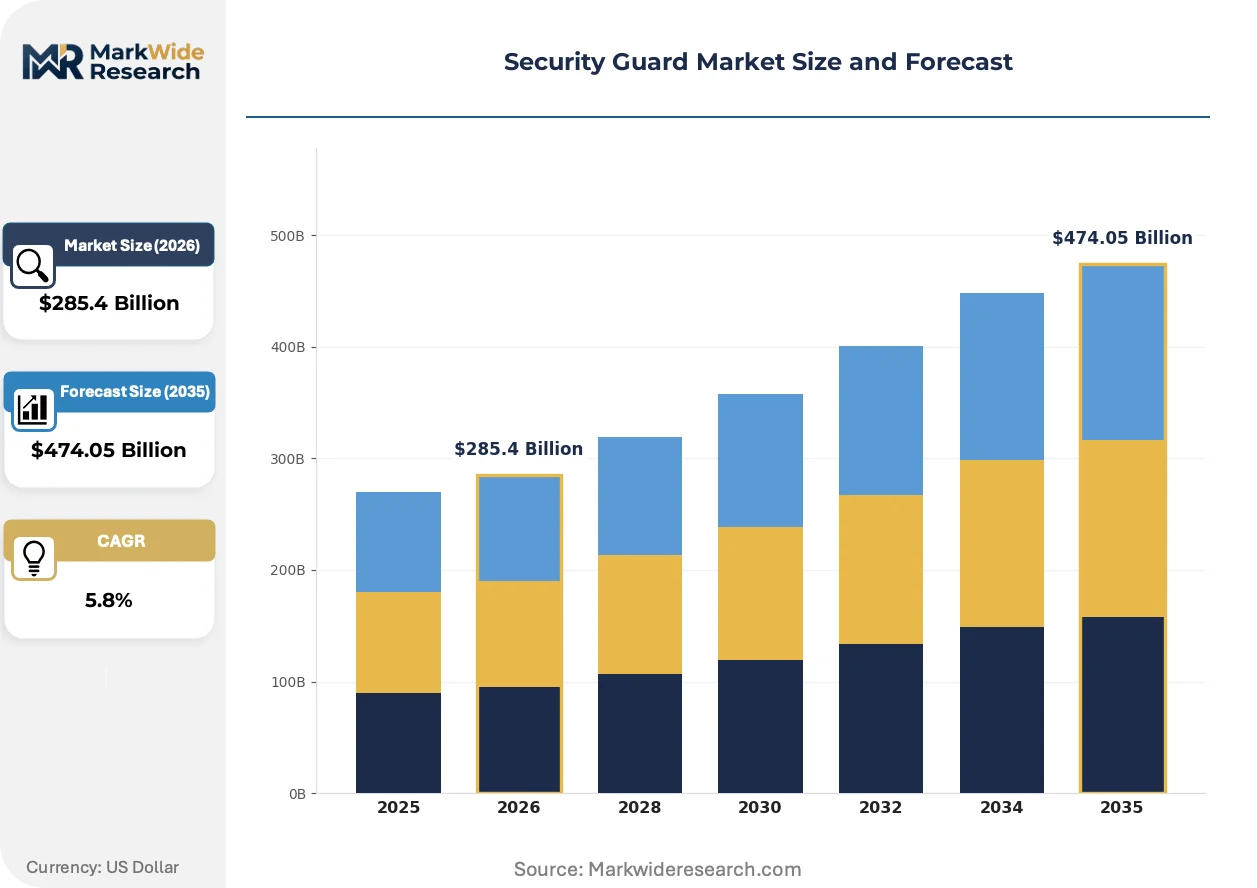
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $474.05 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Patrol, On-site Guarding, Event Security, Remote Monitoring Client Type: Residential, Commercial, Government, Industrial Technology: Access Control, Surveillance Systems, Alarm Systems, Incident Management Deployment: Full-time, Part-time, Contractual, Temporary |
| Companies Covered | Walden Security, Securitas AB, Inter-Con Security Systems, Sunstates Security, G4S, Protos Security, GardaWorld, Signal, Allied Universal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Guard Market Strategic Shifts & Innovations
Service delivery architectures are bifurcating between technology-augmented guarding and pure remote monitoring, with regulatory pressure determining which model prevails in specific end-use verticals and geographies.
AI-powered video analytics is collapsing the functional boundary between human patrols and automated surveillance by enabling real-time threat detection with minimal guard intervention. Large commercial real estate owners in Texas and California are deploying these systems across parking structures and perimeter zones, compressing headcount requirements while maintaining insurance-compliant physical presence ratios.
The EU AI Act's human oversight mandate is restructuring European security procurement by prohibiting fully autonomous surveillance in public spaces. Facility managers in Germany and France must now staff guard posts to review algorithmic alerts, creating regulatory-driven demand that offsets labor substitution elsewhere in the market.
Buyers are unbundling traditional guarding contracts into discrete service modules—patrol, access control, incident response, and technology management—enabling competitive benchmarking and vendor switching. This pattern is most pronounced among Fortune 500 corporate campuses in California and Illinois, where procurement teams negotiate separate agreements for manned guarding and integrated security technology.
Security Guard Market Segmentation
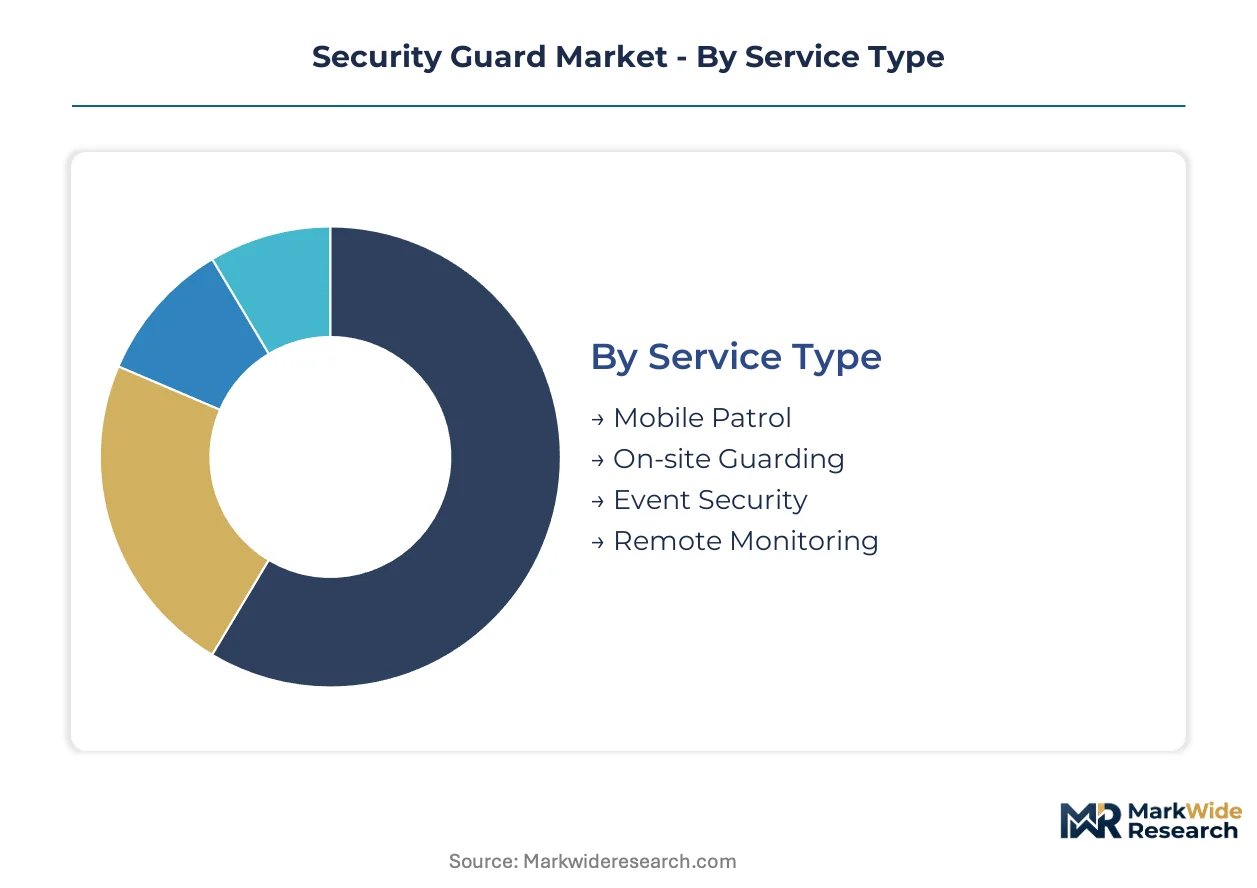
Segmentation in security guard services determines contract pricing, staffing ratios, and technology integration depth. Procurement teams unbundle service modules to benchmark vendors against specialized competitors rather than bundled incumbents.
Service Type:
After-sales service intensity varies dramatically across service types, with on-site guarding demanding continuous workforce management and remote monitoring requiring sustained technical support.
- On-site Guarding:Trained personnel maintain fixed posts with defined patrol routes, shift coverage, and escalation protocols for asset protection and access control. Demand concentrates across Texas, California, and Florida metro corridors where commercial real estate development and energy infrastructure expansion are accelerating physical presence requirements. Insurance and regulatory mandates for human oversight reinforce contract durability.
- Remote Monitoring:Cloud-connected surveillance centers deliver real-time threat detection with minimal on-ground intervention, reducing marginal labor costs. Corporate campuses in California and Illinois are unbundling this from traditional guarding contracts to enable competitive benchmarking and vendor switching.
- Mobile Patrol:Vehicle-based security personnel conduct randomized perimeter checks and alarm response across distributed facilities.
- Event Security:Specialized crowd management and access control for sports venues and entertainment complexes, with premium pricing during peak seasons but cyclical volume constraints.
On-site guarding holds the largest share; momentum sits with remote monitoring.
Client Type:
Contract value and margin profiles diverge sharply across client categories, with industrial and government segments commanding specialized training premiums.
- Commercial:Corporate campuses, retail properties, and office complexes require hybrid guard-technology deployments for insurance compliance and tenant safety. FAA regulations govern airport security staffing minimums in this segment.
- Industrial:Manufacturing facilities, logistics hubs, and energy infrastructure deploy guards for workplace violence prevention under OSHA protocols. Demand is scaling across Texas energy corridors and California data center clusters.
- Government:Federal, state, and municipal facilities require cleared personnel with specialized training protocols for critical infrastructure protection.
- Residential:Gated communities and multi-family properties purchase patrol and access control services, often competing on price in commoditized segments.
Commercial captures the highest contract volume; government delivers the steepest expansion trajectory.
Technology:
Technology integration depth determines service differentiation and recurring revenue streams beyond base guarding fees.
- Surveillance Systems:AI-powered video analytics enables real-time threat detection with minimal guard intervention, collapsing functional boundaries between human patrols and automated monitoring. Large commercial real estate owners in Texas and California deploy these across parking structures and perimeter zones.
- Access Control:Biometric and mobile credential systems converge with guard-managed entry protocols, creating high-margin hybrid service bundles for corporate campuses. Retrofitting into existing building infrastructure requires capital-intensive site-by-site customization.
- Alarm Systems:Intrusion detection and emergency response coordination with guard dispatch services.
- Incident Management:Digital reporting platforms and escalation workflows for regulatory documentation and insurance claims.
Surveillance systems anchor technology revenue; access control is gaining share fastest.
Deployment:
Labor model selection directly impacts margin stability and regulatory compliance exposure across jurisdictions.
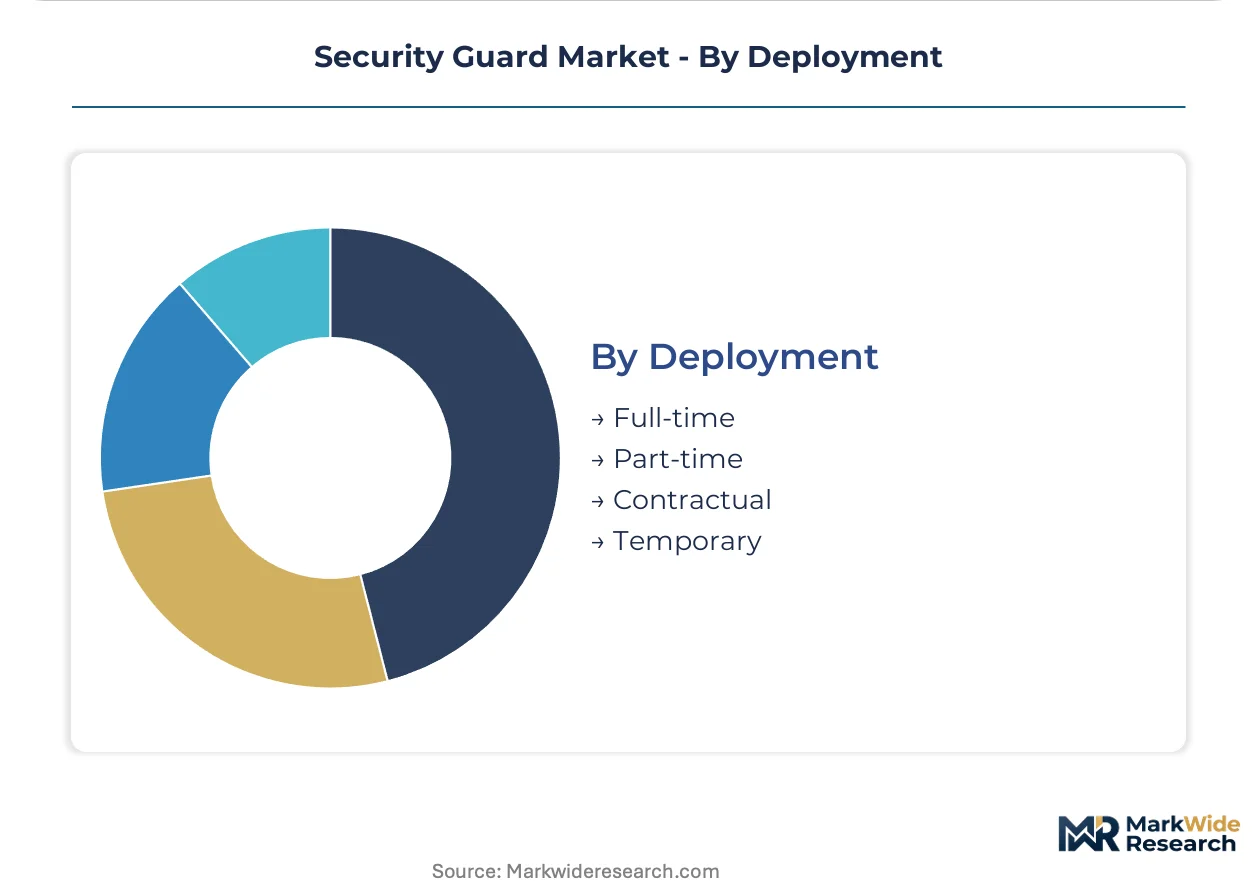
- Full-time:Permanent guard staffing with benefits obligations and training investment, preferred by critical infrastructure and government clients for continuity.
- Contractual:Defined-term service agreements with specified deliverables, enabling competitive rebidding and vendor switching among Fortune 500 procurement teams.
- Part-time:Supplemental coverage for low-traffic periods and secondary facilities.
- Temporary:Surge staffing for events, seasonal demand, and emergency response.
Full-time deployment dominates revenue; contractual arrangements are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States security providers export hybrid guard-technology service models to Canadian and Mexican commercial real estate portfolios, while German firms supply certified personnel frameworks to Austrian and Swiss critical infrastructure operators.
United States
Commercial real estate development and energy infrastructure expansion across Texas, California, and Florida metro corridors are accelerating physical presence requirements. FAA regulations govern airport security staffing minimums while OSHA protocols shape workplace violence prevention mandates. Corporate campuses in Dallas-Fort Worth and Houston are scaling manned guarding budgets to meet insurance compliance thresholds.
Germany
The EU NIS2 Directive is accelerating demand for certified security personnel at energy, transport, and healthcare facilities. GDPR and EU AI Act compliance requirements push providers to integrate human oversight with automated surveillance systems. Facility managers in Bavaria and North Rhine-Westphalia must now staff guard posts to review algorithmic alerts.
United Kingdom
Corporate campuses and critical infrastructure facilities are expanding manned guarding budgets across Greater London and the Southeast. The EU AI Act's human oversight mandate influences procurement patterns even post-Brexit. Data center clusters in Slough and Manchester are deploying hybrid guard-technology models for insurance-compliant physical presence.
Canada
Workplace violence prevention protocols and critical infrastructure protection requirements drive industrial guard deployment in Ontario and Alberta. Health Canada regulations intersect with provincial licensing frameworks for healthcare facility security. Oil sands operators in Fort McMurray are scaling specialized guarding contracts for remote site access control.
France
CNIL oversight of automated surveillance reinforces demand for hybrid guard-technology deployments where trained personnel supervise algorithmic outputs. The EU AI Act prohibits fully autonomous surveillance in public spaces. Facility managers in Île-de-France and Provence-Alpes-Côte d'Azur are restructuring procurement to staff guard posts for alert review.
Security Guard Market Key Industry Players
On the supply side, the industry is consolidating around multi-jurisdictional providers with technology integration capabilities. Tiered competitive positioning separates global footprint operators from regional specialists and technology-augmented niche players. Strategic archetypes include scale-driven manpower aggregators, hybrid technology-guard integrators, and certified critical infrastructure specialists. Dominant competitive moves encompass vertical integration of surveillance technology with guard services and geographic expansion through contract acquisition in high-growth metro corridors.
Within the global footprint tier, Securitas AB and G4S exemplify scale-driven operators with multi-continental contract anchoring. Allied Universal occupies a position as the North American commercial real estate dominant through backward integration of technology and manpower. Regional specialists such as Walden Security and Sunstates Security represent the certified training and localized service archetype. GardaWorld anchors the Canadian-origin expansion model with cross-border operational capabilities.
| Leading Market Players |
|---|
| Walden Security |
| Securitas AB |
| Inter-Con Security Systems |
| Sunstates Security |
| G4S |
| Protos Security |
| GardaWorld |
| Signal |
| Allied Universal |
| Others |
Cost & Logistics Intelligence
Overcapacity in commoditized retail guarding across Texas and Florida metros is compressing spot pricing while tightening margins for providers lacking technology differentiation, forcing a bifurcation between price-takers in saturated corridors and premium-positioned operators in regulated critical infrastructure segments.
Pricing Analysis
Legacy manned guarding commands standard rates against next-generation hybrid guard-technology bundles that capture 40-60% premiums through biometric integration and AI-augmented patrol protocols. Three-tier pricing structure across premium certified personnel, standard contractual guarding, and economy temporary staffing segments reflects divergent training depth and insurance backing. Cost compression in economy-tier retail and commercial real estate guarding is intensifying because cloud-connected remote monitoring displaces low-complexity posts. Industrial and government clients exhibit lowest price sensitivity due to OSHA compliance mandates and specialized clearance requirements.
Supply Chain Analysis
EU AI Act restrictions on autonomous surveillance technology exports to non-compliant jurisdictions are fragmenting equipment sourcing patterns across the security guard industry. Guard service provision concentrates in the United States, Germany, and the United Kingdom where regulatory frameworks support certified personnel deployment. Labor recruitment draws from vocational training pipelines, background screening infrastructure, and specialized de-escalation certification programs. Single-source vulnerability in biometric access control hardware creates procurement risk for mid-tier providers dependent on Chinese facial recognition componentry. Distribution runs through direct enterprise sales teams for Fortune 500 accounts and regional subcontractor networks for localized commercial coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The security guard market is undergoing high-growth disruption as the EU AI Act's human oversight mandate restructures procurement economics across European critical infrastructure and ripples into North American compliance frameworks.
For Market Incumbents: Insulate core enterprise contracts through backward integration of AI-powered video analytics and biometric access control systems, reducing vendor switching incentives among Fortune 500 procurement teams in California and Illinois. Accelerate certified personnel training pipelines to address specialized de-escalation gaps in healthcare and educational institutions where substitute technologies face regulatory prohibition. For New Entrants and Emerging Players: Mid-market commercial buildings in German federal states outside Bavaria and North Rhine-Westphalia represent the most penetrable entry point given NIS2 Directive compliance requirements that favor certified local operators over unqualified technology vendors. Target event security premiumization in Florida and California sports venues through specialized crowd management certifications that command peak-season pricing multiples unavailable to commoditized guarding providers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid technology-guard integrators with multi-year enterprise contracts spanning surveillance system maintenance and personnel deployment. Long-term viability hinges on regulatory moats deepening around human oversight mandates rather than pure technology substitution plays. Monitor EU AI Act enforcement patterns and OSHA workplace violence rulemaking as early signals of contract durability shifts across industrial and government verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Access Control Integration | Creates high-margin hybrid service bundles for corporate campuses requiring GDPR-compliant entry protocols. |
| Certified Personnel Training Programs | Addresses specialized de-escalation gaps in healthcare and educational institutions under OSHA protocols. |
| Remote Monitoring Platform Deployment | Reduces marginal labor costs for commercial real estate clients unbundling traditional guarding contracts. |
| Geographic Expansion in Energy Corridors | Captures scaling demand across Texas and California data center clusters with insurance-mandated physical presence. |
| Regulatory Compliance Specialization | Positions providers for EU NIS2 Directive contracts across German critical infrastructure facilities. |
Research Approach
The analysis maps on-site guarding, remote monitoring, mobile patrol, and event security segments, each validated through facility security directors, corporate procurement officers, guard firm operations managers, and regulatory compliance consultants. Primary interviews with industry stakeholders combined with secondary validation from FAA staffing filings, OSHA workplace violence enforcement data, EU AI Act implementation guidance, and commercial real estate development permits. Bottom-up contract value analysis and top-down market sizing triangulate segment-level revenue estimates across service type, client vertical, and deployment model dimensions.
Assumptions held fixed include regulatory enforcement timelines for EU AI Act human oversight mandates and OSHA protocol adoption rates, while technology substitution elasticities and labor cost inflation trajectories were varied across sensitivity scenarios. Segmentation dimensions modeled encompass service type, client industry, technology integration depth, and deployment labor model throughout the forecast period. CAGRs derive from trend extrapolation of contract renewal rates, technology penetration curves, and geographic expansion patterns in named metro corridors, with specific inputs including energy infrastructure capital expenditure pipelines and data center construction permitting velocity.
Practitioners should monitor EU AI Act enforcement stringency and OSHA rulemaking pace for early signals of hybrid service model adoption acceleration. Forecasts reflect assumptions about regulatory stability and technology cost curves that could shift with generative AI surveillance capabilities or federal preemption of state licensing frameworks. Material shifts in biometric hardware supply chain access or critical infrastructure protection mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Tactical Lights Market
Physical Security
Canada Data Center Physical Security Market
Physical Security
Physical Security Market
Physical Security
Physical Security Services Market
Physical Security
Body Armor Market
Physical Security
Active Geofencing Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Bulletproof Glass Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Smart Police Helmet Market
Physical Security
Tactical Vests Market
Physical Security
France Data Center Physical Security Market
Physical Security
Global Wearable Security Device Market
Physical Security
Europe Physical Security Market