
 Europe Physical Security Market | 2026-2036
Europe Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Physical Security Market Analytics
The capital-intensity divergence between integrated platform providers and hardware-centric vendors is redrawing competitive boundaries across Europe. Axis Communications AB leverages its deep R&D investment in edge-computing cameras to sustain technology leadership in Nordic markets. Bosch Security Systems GmbH anchors its position through in-house manufacturing of image sensors and analytics chipsets. Siemens AG competes by extending its building-automation footprint into converged physical-cyber security architectures for industrial clients.
Physical security encompasses the integrated systems, devices, and services designed to protect personnel, assets, and infrastructure from unauthorized access, intrusion, or harm, typically incorporating video analytics with minimum 1080p resolution, IP-based transmission protocols, and real-time threat detection algorithms. Video surveillance and access control command the largest revenue pools as municipalities and enterprises replace analog infrastructure with AI-enabled platforms. Cloud-based deployment represents the fastest-expanding segment as hybrid work models push organizations toward centralized, remotely manageable security operations. The intrusion detection category remains mature in Western European commercial real estate but sees renewed specification in Eastern European data center construction.
The EU AI Act, GDPR, and the F-Gas Regulation collectively reshape product design mandates across the continent, with biometric authentication systems now requiring algorithmic transparency documentation and refrigerant-based thermal cameras facing phase-out timelines. EMA and national data protection authorities in France, Germany, and Italy enforce divergent consent frameworks for facial recognition in public spaces, complicating cross-border rollout strategies. Stakeholders must monitor evolving CE marking requirements for AI-integrated security devices and assess whether cloud sovereignty provisions in individual member states warrant dedicated in-country data residency investments.
Market Dynamics
The EU AI Act and GDPR compliance deadlines are compressing procurement cycles for biometric and video analytics systems across European critical infrastructure operators. Vendors must now certify algorithmic transparency and data residency before contract award, reshaping competitive positioning toward privacy-certified platform providers.
Growth Catalysts
- EU AI Act Mandates:The regulation's risk-based classification system requires high-risk biometric deployments to maintain audit trails and human oversight, creating specification pull for certified edge-computing cameras in French transportation hubs and German government facilities.
- Critical Infrastructure Modernization:Energy operators in the Netherlands and Belgium are replacing analog perimeter systems with IP-based intrusion detection following NIS2 directive implementation, accelerating platform consolidation.
- Edge AI Chipsets:On-device inference capabilities reduce bandwidth costs and latency for real-time threat detection, enabling municipalities to scale video analytics without proportional cloud infrastructure expansion.
Market Restraints
- GDPR Consent Fragmentation:France's CNIL, Germany's federal data protection authorities, and Italy's Garante enforce divergent facial recognition frameworks for public spaces, complicating cross-border product rollouts and requiring jurisdiction-specific algorithm configurations.
- Image Sensor Supply Concentration:Advanced CMOS sensor fabrication concentrates among East Asian foundries, exposing European camera manufacturers to lead time volatility and currency fluctuation risks.
- F-Gas Phase-Out Timelines:The EU F-Gas Regulation mandates refrigerant reduction schedules for thermal imaging equipment, forcing redesign cycles for perimeter security deployments in Nordic climates.
Strategic Opportunities
- Eastern European Data Center Construction:Poland and Romania see accelerated specification of integrated physical-cyber security architectures as hyperscale operators expand cloud regions, creating demand for converged access control and IT security platforms.
- Cloud Sovereignty Provisions:Individual member state data residency requirements create openings for vendors offering in-country cloud security operations centers, particularly in Germany and France where public sector procurement mandates local processing.
- Building Automation Convergence:Integration of access control with HVAC and lighting systems under single management platforms enables vendors to capture facility-wide operational budgets rather than isolated security line items.
Industry Challenges
- Algorithmic Audit Expertise Gap:The EU AI Act requires documented bias testing and performance monitoring for biometric systems, but qualified AI ethics auditors remain scarce across continental Europe, extending certification timelines.
- Legacy Analog Infrastructure:Municipalities in Southern and Eastern Europe retain substantial coaxial cable and DVR-based deployments, complicating migration paths to IP platforms and AI-enabled analytics without full infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Physical Security Market |
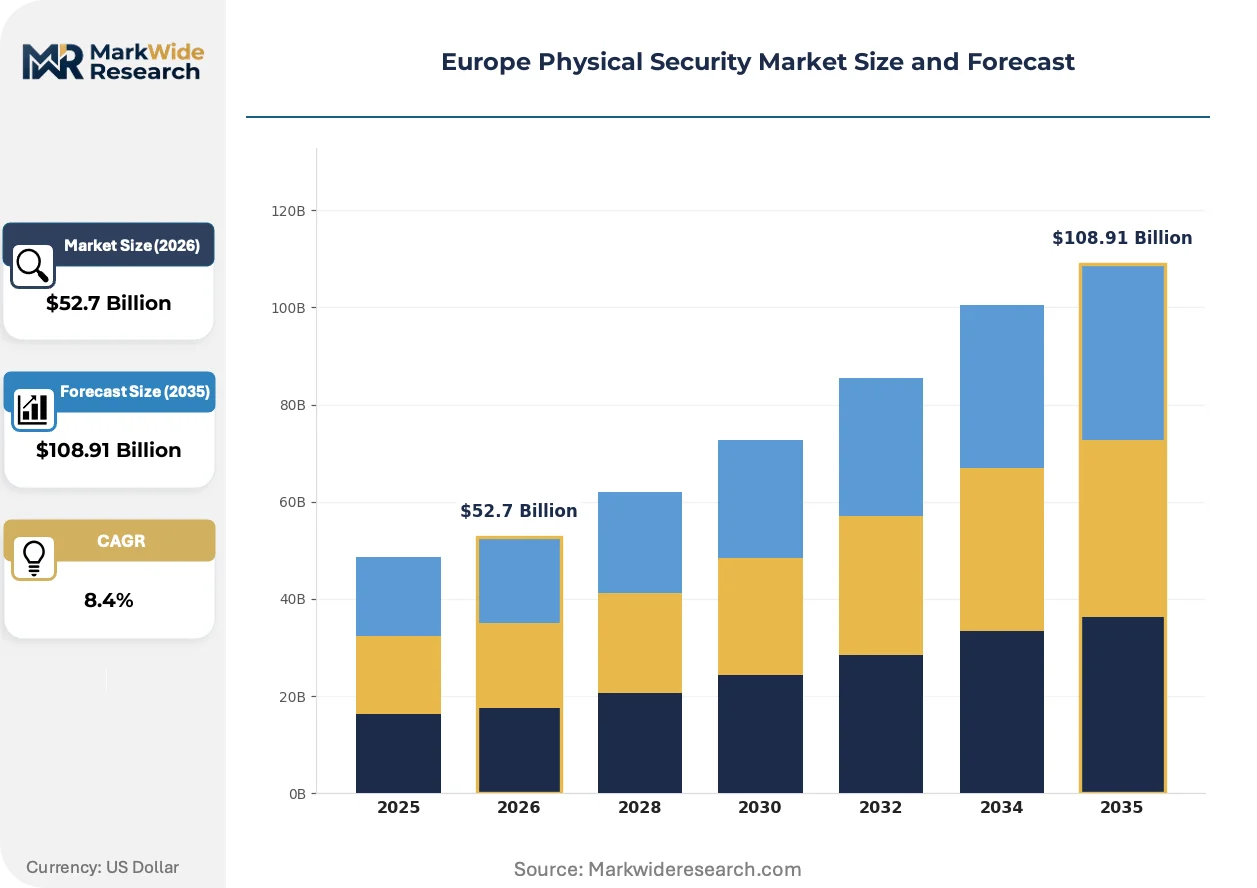
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Video Surveillance, Access Control, Intrusion Detection, Alarms Product Type: Locks, Security Cameras, Fencing, Barriers End User: Government, Retail, Transportation, Healthcare Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Axis Communications AB, Honeywell International Inc, Securitas AB, Schneider Electric SE, Siemens AG, Bosch Security Systems GmbH, Johnson Controls, Genetec Inc, G4S Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Physical Security Market Evolving Landscape
Edge computing architectures and privacy-preserving analytics are restructuring how European organizations deploy, manage, and procure physical security capabilities. These shifts compress the traditional hardware-software boundary while elevating compliance and data sovereignty as specification criteria.
Video analytics processing is bifurcating between cloud-centralized and edge-distributed architectures based on application latency requirements. German automotive manufacturers and French nuclear facilities specify on-camera inference for sub-100-millisecond threat response, while retail and commercial real estate operators in the United Kingdom consolidate analytics in cloud security operations centers to reduce capital expenditure. This technical split is bifurcating vendor strategies between high-performance edge chipsets and scalable SaaS platforms.
The EU AI Act's high-risk system classification is mandating algorithmic documentation and human oversight protocols for biometric authentication deployments. Security integrators must now maintain model cards, training data provenance records, and bias audit trails to achieve CE marking for AI-integrated devices. French critical infrastructure operators and German federal agencies are specifying these compliance capabilities as mandatory evaluation criteria, compressing procurement toward vendors with established AI governance frameworks.
Subscription-based security-as-a-service models are displacing perpetual license structures in mid-market commercial deployments. British facility management firms and Dutch property portfolios now specify operational expenditure contracts bundling hardware, software, maintenance, and remote monitoring under fixed monthly fees. This financing shift favors platform vendors with captive cloud infrastructure and managed service capabilities, pressuring hardware-centric suppliers to develop recurring revenue streams or risk channel displacement.
Europe Physical Security Market Segmentation
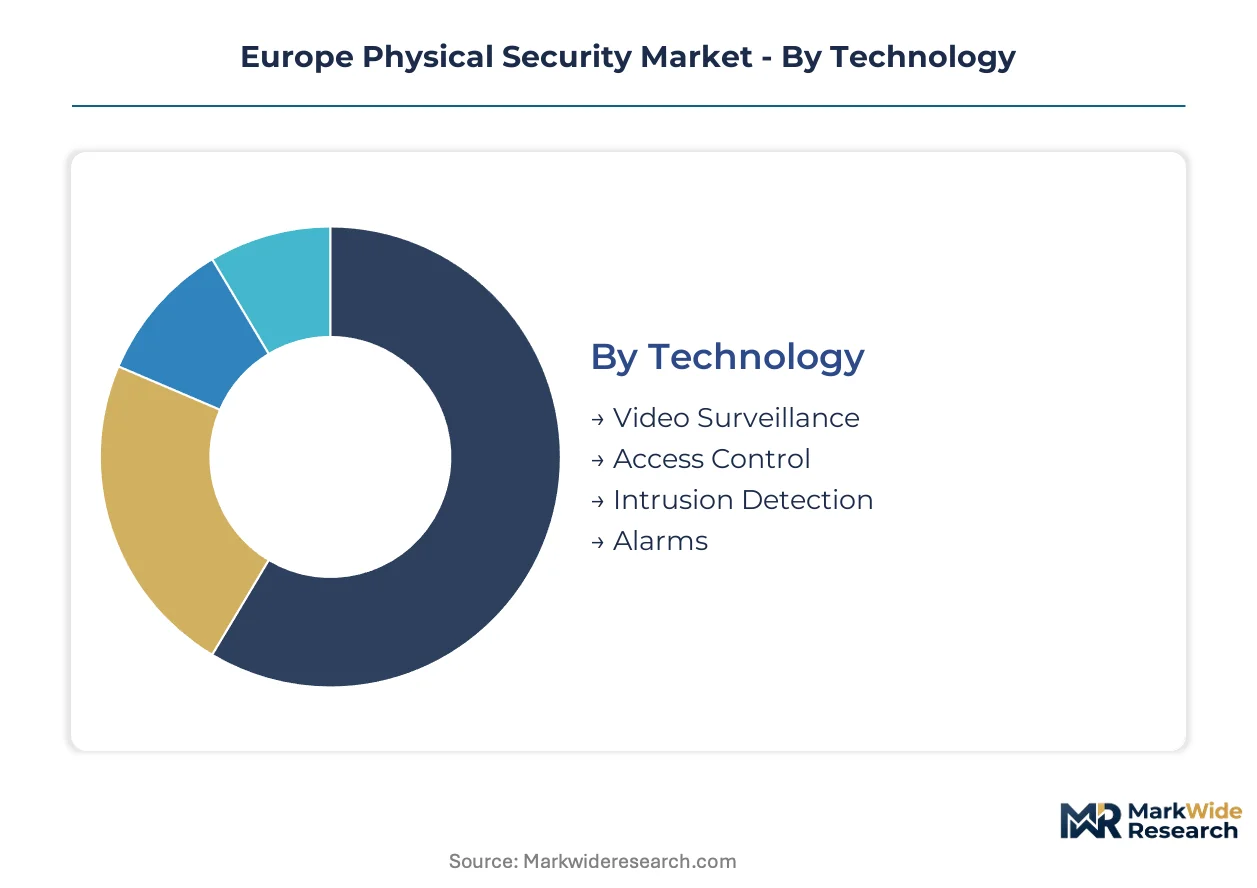
Technology choices in European physical security increasingly pivot on data sovereignty requirements and AI Act compliance timelines. Deployment models and end-user specifications diverge sharply between critical infrastructure operators subject to NIS2 directives and commercial enterprises prioritizing operational flexibility.
Technology:
Video analytics and biometric authentication face acute substitution pressure from privacy-preserving alternatives as GDPR enforcement tightens across France, Germany, and Italy.
- Video Surveillance:IP-based camera networks with edge-computing inference capabilities process threat detection locally to minimize bandwidth and cloud residency risks. German transportation hubs and French nuclear facilities specify these systems to meet sub-100-millisecond response requirements under EU AI Act high-risk system classifications.
- Access Control:Biometric and credential-based entry management systems integrate with building automation platforms for unified facility oversight. Demand concentrates in United Kingdom healthcare estates and Netherlands government complexes where NIS2 mandates drive replacement of legacy card-reader infrastructure.
- Intrusion Detection:Perimeter sensors and motion detection arrays secure data center and energy facility boundaries. Polish and Romanian hyperscale construction projects specify these for integrated physical-cyber architectures.
- Alarms:Audible and silent alert systems with centralized monitoring connectivity serve retail and commercial real estate operators.
Video surveillance anchors the volume base while access control gains share at the steepest rate.
Product Type:
Hardware procurement patterns split between premium-specified critical infrastructure and cost-optimized commercial deployments.
- Security Cameras:Fixed and PTZ devices with minimum 1080p resolution and IP transmission protocols replace analog coaxial infrastructure. United Kingdom municipalities and Dutch energy operators drive demand as F-Gas Regulation timelines force thermal camera redesigns.
- Locks:Electromechanical and smart locking systems with audit trail capabilities secure government and healthcare facilities. German federal procurement mandates biometric integration for high-security zones.
- Fencing:Perimeter barriers with sensor integration protect data centers and transportation corridors.
- Barriers:Vehicle and pedestrian control systems manage access at critical infrastructure entry points.
Security cameras dominate capital expenditure while smart locks expand most quickly through building automation convergence.
End User:
Customer-type concentration reflects divergent compliance burdens and procurement autonomy across European public and private sectors.
- Government:Federal, regional, and municipal facilities require AI Act-certified biometric systems with documented algorithmic transparency. French and German agencies specify privacy-certified platforms with in-country data residency.
- Transportation:Airports, rail hubs, and logistics terminals deploy integrated video analytics and access control for passenger and cargo security. United Kingdom aviation operators modernize analog infrastructure under CPNI guidelines.
- Healthcare:Hospital estates and pharmaceutical manufacturing facilities balance patient privacy with asset protection requirements.
- Retail:Store portfolios and distribution centers prioritize loss prevention through cloud-managed surveillance platforms.
Government procurement anchors the volume base while transportation infrastructure shows the steepest specification climb.
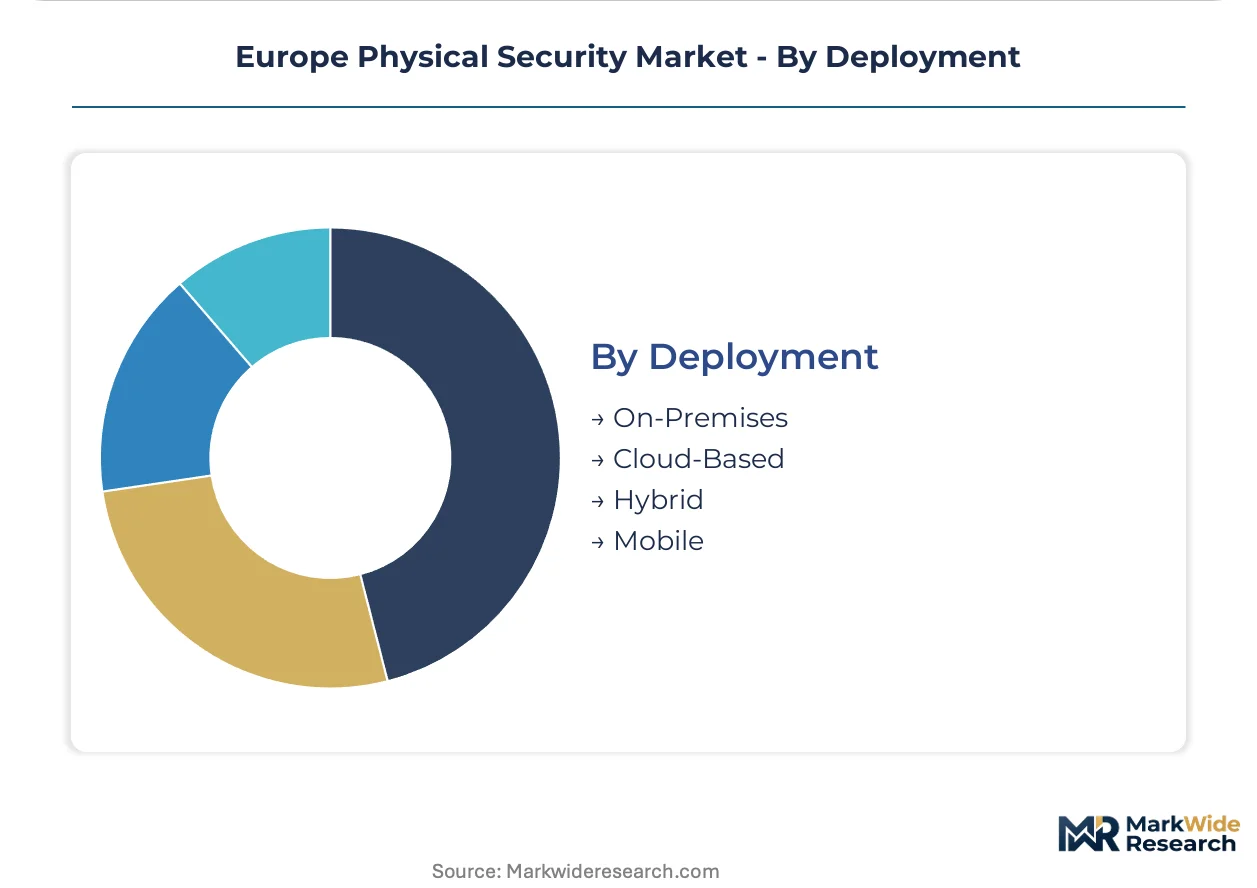
Deployment:
Infrastructure location decisions increasingly hinge on member-state cloud sovereignty provisions and cross-border data transfer restrictions.
- Cloud-Based:Centralized security operations centers with subscription-based pricing enable remote management of distributed facilities. British facility management firms and Dutch property portfolios specify these for operational expenditure conversion.
- Hybrid:Architectures combining edge processing with cloud analytics balance latency requirements against scalability. German automotive manufacturers deploy these for manufacturing site security with local inference and centralized monitoring.
- On-Premises:Fully localized systems with dedicated server infrastructure satisfy data residency mandates in France and Germany.
- Mobile:Portable surveillance and access control units serve temporary event security and construction site monitoring.
On-premises deployment retains the volume base while hybrid architectures climb the fastest as edge AI chipsets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's physical security trade flows reveal a technology-import pattern, with Nordic and German engineering houses supplying edge-computing hardware southward while French and British system integrators export managed security services eastward. This exchange reflects divergent national specializations in hardware versus services.
Germany
Federal procurement mandates for AI Act-certified biometric systems drive demand at transportation hubs and government complexes. The BSI enforces strict algorithmic transparency requirements for high-risk security deployments. Bavaria's industrial corridor anchors manufacturing site security upgrades where automotive producers specify hybrid edge-cloud architectures.
France
CNIL consent frameworks for public facial recognition compress procurement timelines for privacy-certified platforms. The EU AI Act's risk-based classification shapes specification criteria at nuclear facilities and aviation infrastructure. The Paris-Saclay cluster concentrates video analytics R&D as critical infrastructure operators modernize perimeter systems.
United Kingdom
CPNI guidelines accelerate analog-to-IP migration at aviation and rail terminals. Post-Brexit data transfer arrangements complicate cloud security operations center deployments for multinational facility managers. London's financial district drives demand for converged physical-cyber access control in banking headquarters.
Netherlands
NIS2 directive implementation forces energy operators to replace legacy perimeter intrusion systems. Rotterdam's port complex specifies integrated vessel-traffic and facility security platforms. National data residency preferences create openings for in-country cloud security operations.
Poland
Hyperscale data center construction by cloud operators generates demand for integrated physical-cyber security architectures. EU funding for critical infrastructure resilience supports municipal video surveillance upgrades. Warsaw's emerging tech corridor attracts security technology deployment as regional cloud capacity expands.
Europe Physical Security Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that leverage building-automation footprints into converged security offerings. The vendor base spans three tiers: integrated platform providers with captive cloud infrastructure, hardware-centric camera manufacturers with edge-computing specialization, and security services firms with managed operations capabilities. Strategic moves center on portfolio diversification into AI-enabled analytics and geographic expansion through channel partnerships in Eastern European growth markets.
Within the integrated platform tier, Siemens AG and Schneider Electric SE exemplify industrial conglomerates extending building-automation dominance into security architectures. Axis Communications AB anchors the hardware-specialist segment with Swedish engineering heritage in network video. Bosch Security Systems GmbH represents German manufacturing depth with in-house component production capabilities.
| Leading Market Players |
|---|
| Axis Communications AB |
| Honeywell International Inc |
| Securitas AB |
| Schneider Electric SE |
| Siemens AG |
| Bosch Security Systems GmbH |
| Johnson Controls |
| Genetec Inc |
| G4S Limited |
| Others |
Value Network & Pricing Analysis
Camera sensor foundry utilization rates above 85 percent in East Asian fabrication facilities concentrate bargaining power among a handful of wafer suppliers, establishing price floors that propagate through European OEM procurement contracts and compress margin structures for mid-tier system integrators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates AI Act-certified biometric platforms with algorithmic transparency documentation from uncertified edge devices and legacy analog replacements. Cost compression in the standard tier is intensifying because German federal procurement mandates now require in-country data residency premiums. Municipal transportation authorities exhibit the highest price sensitivity due to budget fragmentation across regional governments, while French nuclear facility operators show the least sensitivity given NIS2 directive compliance deadlines.
Supply Chain Analysis
Japan and South Korea anchor advanced CMOS image sensor fabrication, while Taiwan concentrates edge AI chipset foundry capacity. European camera assembly draws from Japanese optical components, Taiwanese semiconductors, and Chinese rare earth magnet supplies for PTZ motor assemblies. Single-source vulnerability concentrates in 12-inch wafer fabrication for high-resolution sensors, exposing lead time volatility. Distribution runs through German and Dutch system integrators that bundle hardware with compliance consulting services for GDPR and EU AI Act certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Physical Security Market is entering a cyclical recovery phase as NIS2 directive implementation deadlines force replacement of legacy analog infrastructure across critical infrastructure operators.
For Market Incumbents:Compound platform consolidation advantages by acquiring AI ethics audit capabilities to compress EU AI Act certification timelines for customers. Deepen backward integration into edge AI chipsets to reduce exposure to Taiwanese foundry concentration. Channel control through exclusive distribution partnerships with French and German system integrators defends against emerging SaaS-native entrants.
For New Entrants and Emerging Players:GDPR consent framework fast-tracks in Poland and Romania offer lower regulatory barriers than Western European markets. White-space targets include Eastern European data center security architectures and mid-market British facility management SaaS conversions. A go-to-market angle emphasizing subscription-based security-as-a-service with bundled compliance documentation bypasses incumbent hardware lock-in.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors edge AI hardware specialists with captive algorithm development capabilities. Long-term viability over the next decade hinges on cloud sovereignty adaptation as member state data residency requirements proliferate. Acquisition targets should demonstrate established AI governance frameworks with documented bias audit trails. The signal to watch is CE marking backlog duration for AI-integrated devices as a proxy for regulatory friction.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Accelerates procurement eligibility for French nuclear and German federal facilities. |
| Edge AI Chipset Development | Reduces latency below 100 milliseconds for German automotive manufacturing site security. |
| In-Country Cloud Infrastructure Deployment | Satisfies German BSI and French CNIL data residency mandates for public sector contracts. |
| Building Automation Platform Integration | Captures facility-wide operational budgets beyond isolated security line items. |
| Eastern European Channel Partnership | Positions for Polish and Romanian hyperscale data center construction cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with security system integrators, critical infrastructure procurement officers, building automation engineers, and data center facility managers. Secondary validation drew from EU NIS2 implementation guidance, EDPB facial recognition enforcement actions, customs trade data for camera and sensor imports, and SEC filings of listed security technology vendors. Bottom-up unit economics for edge camera deployments were triangulated against top-down market sizing from government modernization program budgets.
Across the analysis window, the forecast framework modeled technology adoption curves by deployment architecture, end-user compliance burden, and regional regulatory enforcement intensity. Segmentation dimensions included cloud-hybrid-on-premises deployment mix, critical infrastructure versus commercial enterprise end-use, and AI Act risk classification tier. CAGRs were derived from installed base replacement cycles and net new specification rates in Eastern European construction. Industry-specific inputs incorporated F-Gas Regulation phase-out timelines for thermal imaging and NIS2 directive implementation schedules.
Underlying assumptions cover stable EU AI Act enforcement continuity and uninterrupted East Asian semiconductor supply, with deviation risk concentrated in GDPR consent framework fragmentation and geopolitical disruption to sensor foundry output. Recalibration cycles align with material shifts in NIS2 transposition deadlines and CE marking requirement updates for AI-integrated security devices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Border Security Technologies Market
Physical Security
Physical Security Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Canada Data Center Physical Security Market
Physical Security
South America Data Center Physical Security Market
Physical Security
Security Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Body Armor Market
Physical Security
Body Armor Plates Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Airport Full Body Scanner Market
Physical Security
Smart Police Helmet Market
Physical Security
North America Physical Security Market
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Tactical Vests Market