
 Asia-Pacific (APAC) Physical Security Market | 2026-2036
Asia-Pacific (APAC) Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific (APAC) Physical Security Market Analysis
Shortage of certified cybersecurity-physical security convergence engineers is collapsing project timelines across major APAC deployments. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its vertically integrated sensor manufacturing to control cost structures in mass-market video surveillance. Dahua Technology Co., Ltd. dominates AI-enabled camera R&D through dedicated chip design subsidiaries. Johnson Controls anchors premium building security integration through its Metasys platform dominance across commercial real estate in Singapore and Tokyo.
Asia-Pacific physical security encompasses electronic systems designed to protect personnel, assets, and infrastructure through detection, deterrence, and response mechanisms, typically integrating video capture at 4K resolution with edge-based analytics processing below 150ms latency for real-time threat classification. The primary commercial purpose centers on reducing operational risk for high-footfall environments while generating audit trails for insurance and liability compliance. Video surveillance leads product type revenue due to camera hardware refresh cycles accelerating across aging analog estates in Indonesia and Vietnam. Biometrics within technology segments sustains premium pricing through multimodal fusion deployments at Indian banking halls and Philippine government service centers. Cloud security is displacing on-premise NVR architectures fastest among mid-market retail chains seeking centralized multi-site management without dedicated IT staffing.
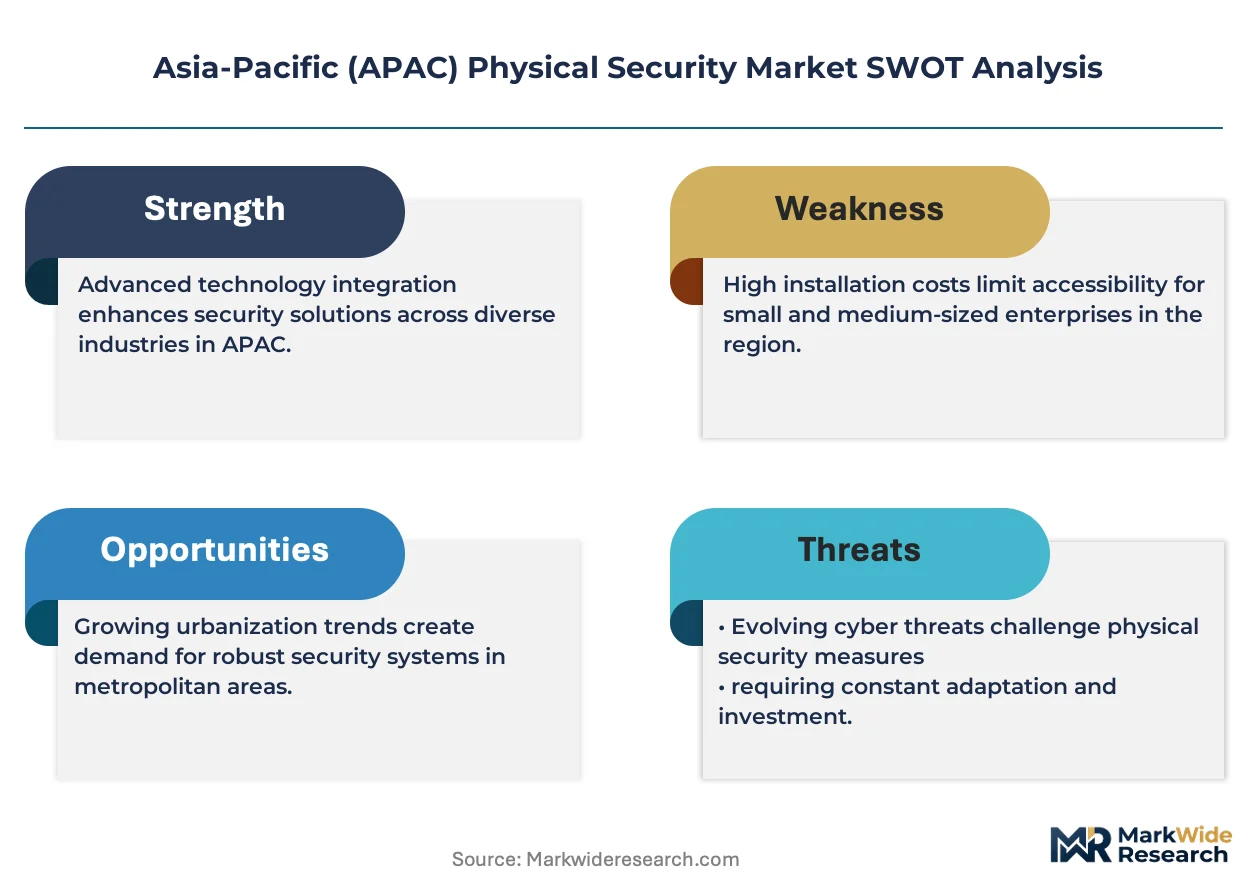
China's GB national standards and India's BIS certification requirements for electronic safety equipment create divergent compliance pathways that fragment vendor go-to-market economics. Japan's METI energy efficiency mandates for IoT devices indirectly shape power consumption specifications for battery-backed security sensors deployed in remote infrastructure. Australia's Critical Infrastructure Protection Act enforcement through the Department of Home Affairs mandates incident reporting timelines that drive demand for automated security orchestration platforms. Stakeholders must monitor how cross-border data localization rulings across ASEAN member states redefine cloud-architected video storage architectures and partner qualification criteria.
Market Dynamics
China's GB/T 28181 national video interconnection standard and India's Bureau of Civil Aviation Security facial recognition mandates are fragmenting vendor compliance pathways, forcing suppliers to engineer region-specific firmware and certification stacks rather than unified product platforms.
Growth Catalysts
- Smart city infrastructure mandates:Southeast Asian metros in Vietnam, Indonesia, and Thailand are bundling video surveillance and access control into municipal procurement packages, creating integrated platform demand.
- Biometric fusion at financial institutions:India's banking halls and Philippine government service centers are deploying multimodal authentication combining facial, fingerprint, and iris recognition for high-security zones.
- Cloud-native architectures:Mid-market retail chains across Australia and Singapore are abandoning on-premise NVR systems for centralized multi-site management without dedicated IT staffing.
Market Restraints
- Certified engineer scarcity:Cybersecurity-physical security convergence expertise remains critically undersupplied, collapsing deployment timelines for integrated projects.
- Sensor supply concentration:Image sensor fabrication clusters in China's eastern seaboard create geographic single-point vulnerability for camera hardware refresh cycles.
- Cross-border data localization:Divergent ASEAN member state rulings on video storage residency complicate cloud-architected platform economics.
Strategic Opportunities
- Indonesian and Vietnamese analog estate replacement:Aging CCTV infrastructure across manufacturing and logistics corridors presents hardware refresh volume.
- Australia's Critical Infrastructure Protection Act enforcement:Automated security orchestration platforms gain traction as Department of Home Affairs mandates tighten incident reporting timelines.
- Edge-AI and thermal imaging convergence:Mining and energy infrastructure operators in Western Australia and Queensland are piloting unified threat detection for remote perimeter monitoring.
Industry Challenges
- Convergence engineering talent gap:Project stalling persists where system integrators lack staff credentialed in both network security and physical access control.
- Legacy analog integration friction:Hybrid deployments combining IP cameras with existing coaxial infrastructure create latency and compatibility failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific (APAC) Physical Security Market |
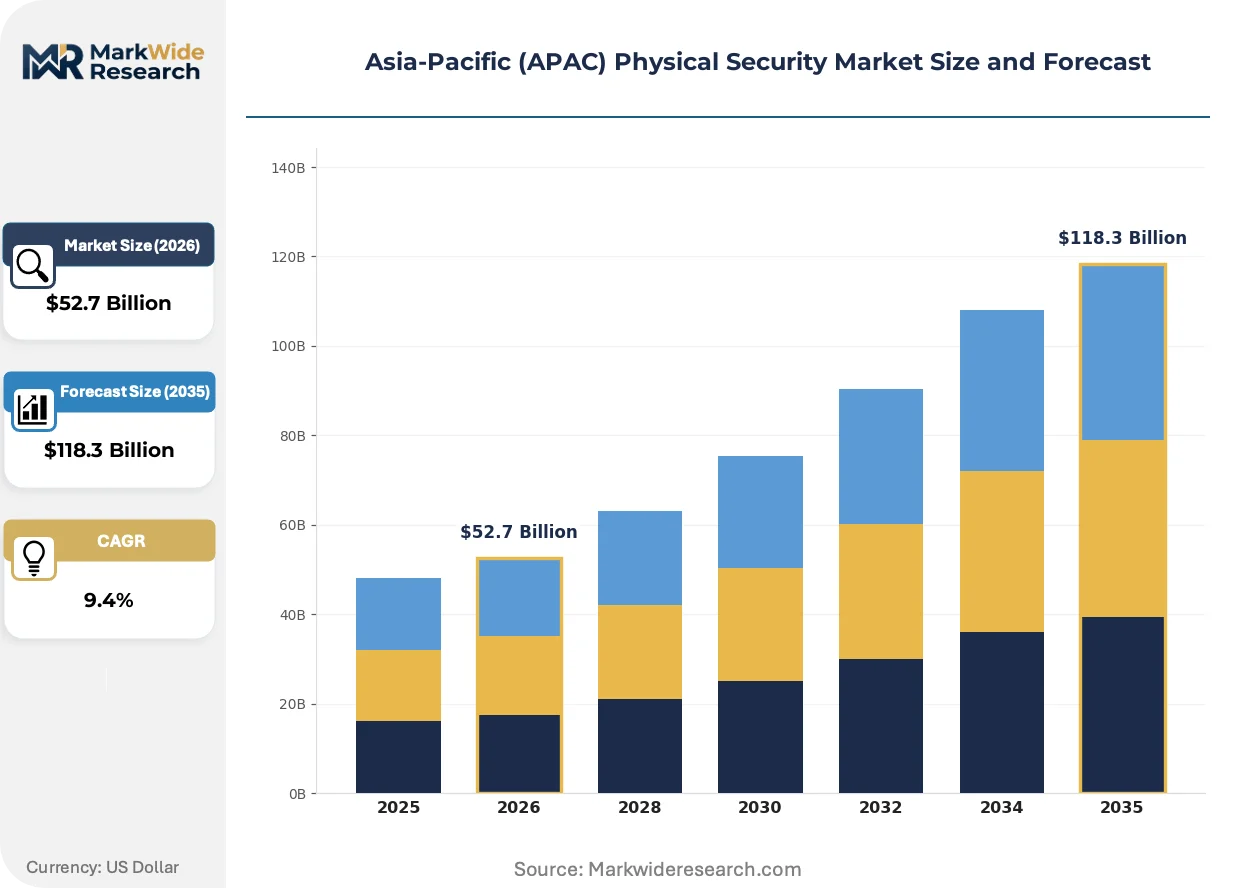
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $118.3 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, Access Control Systems, Intrusion Detection Systems, Alarms End User: Retail, Government, Transportation, Banking Technology: Video Surveillance, Biometrics, Cloud Security, IoT Solutions Application: Perimeter Security, Building Security, Event Security, Workforce Safety |
| Companies Covered | Dahua Technology Co., Ltd., Johnson Controls, Honeywell International Inc., NEC Corporation, Axis Communications AB, Bosch Security Systems GmbH, Genetec Inc., Cisco Systems Inc., Hangzhou Hikvision Digital Technology Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific (APAC) Physical Security Market Emerging Trajectories
Edge-based analytics processing is compressing threat classification latency below 150 milliseconds, while regulatory divergence between China's GB standards and India's BIS certification is forcing architectural fragmentation across the vendor base.
Edge computing architectures for video analytics are decomposing traditional centralized processing models. Manufacturing clusters in China's eastern seaboard and logistics corridors in India's National Capital Region are deploying camera-embedded GPUs for real-time facial recognition and behavioral analysis. This distributed processing is decomposing the legacy server-room infrastructure that previously dominated enterprise security budgets.
Japan's METI energy efficiency mandates for IoT devices are indirectly reshaping power consumption specifications for battery-backed security sensors. Remote infrastructure deployments in Australia's mining zones and Southeast Asian plantation perimeters now face stricter standby power requirements. Vendors are responding with low-power chip designs and solar-integrated enclosures.
Managed security service contracts are displacing capital-heavy ownership models among mid-market buyers. Retail chains and commercial property operators in Singapore and Tokyo are subscribing to video-surveillance-as-a-service rather than procuring hardware directly. This preference shift is most visible in Australia's mid-tier commercial real estate sector, where landlords prioritize operational expenditure predictability over asset ownership.
Asia-Pacific (APAC) Physical Security Market Segmentation
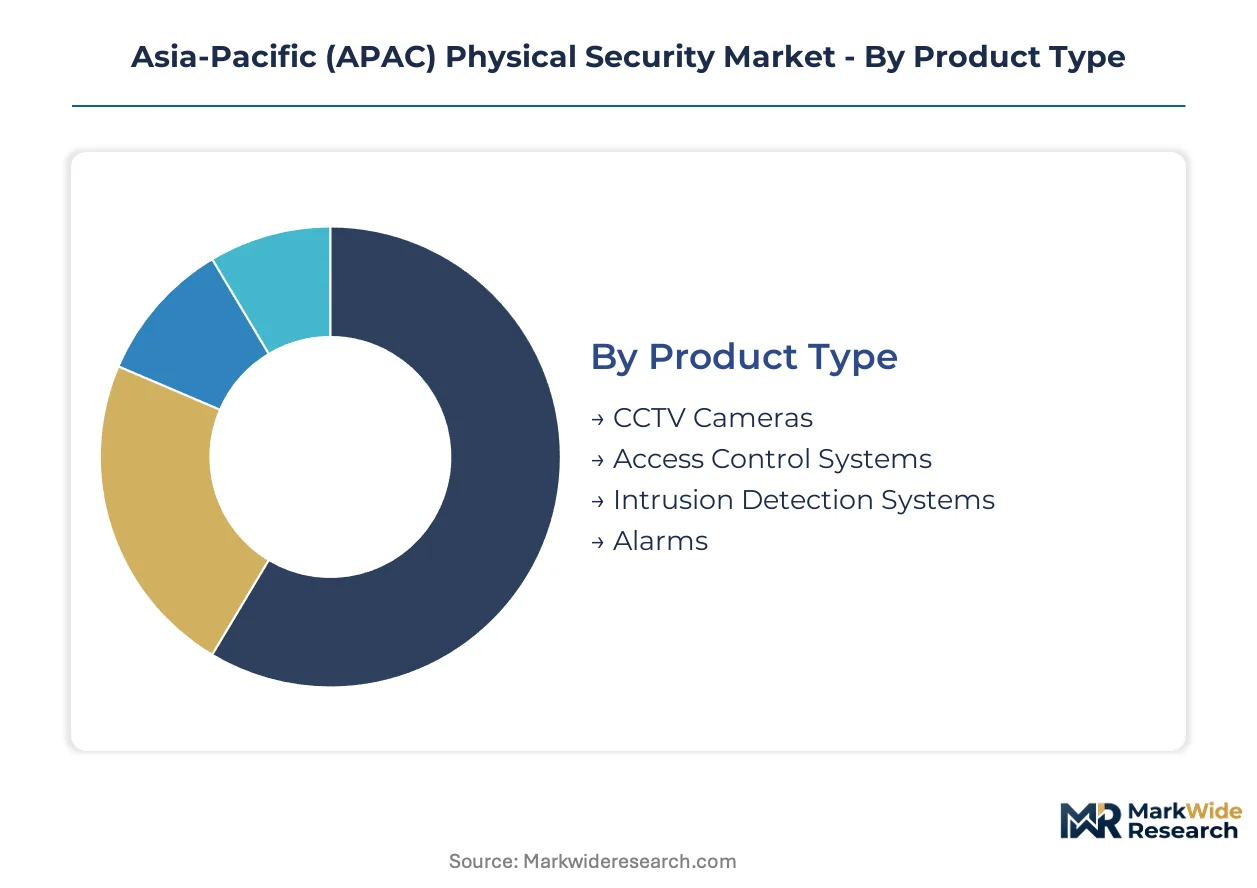
Segmentation in APAC physical security reveals how procurement priorities diverge across compliance regimes, infrastructure maturity, and threat models. Understanding these splits exposes where vendors must engineer region-specific firmware versus scalable platforms.
Product Type:
Margin pools concentrate in camera hardware refresh cycles and integrated access platforms where certification stacks command pricing power.
- CCTV Cameras:Hardware spans fixed dome, PTZ, and thermal variants with 4K resolution and edge-based analytics processing below 150ms latency. Demand clusters in China's eastern seaboard manufacturing zones and Indonesia's analog estate replacement programs, driven by GB/T 28181 compliance mandates and aging infrastructure obsolescence.
- Access Control Systems:Biometric readers, card-based entry, and mobile credential platforms integrate with building management systems. India's National Capital Region logistics corridors and Singapore commercial real estate drive procurement, pressured by Bureau of Civil Aviation Security directives and smart city infrastructure bundling.
- Intrusion Detection Systems:Perimeter sensors and motion detectors with battery-backed power specifications for remote deployment.
- Alarms:Audible and silent alert systems with automated security orchestration for Australia's Critical Infrastructure Protection Act reporting timelines.
CCTV Cameras holds installed capacity. Access Control Systems is rotating up the share rankings.
End User:
Application intensity varies sharply by sector risk exposure and regulatory enforcement depth across the region.
- Retail:Mid-market chains in Australia and Singapore are abandoning on-premise NVR architectures for cloud-native centralized management. Procurement prioritizes operational expenditure predictability over capital ownership, with multi-site video-surveillance-as-a-service subscriptions displacing direct hardware buys.
- Government:Philippine government service centers and Indian state facilities deploy multimodal biometric fusion for high-security zone authentication. Compliance with facial recognition mandates and national video interconnection standards shapes vendor qualification.
- Transportation:Airports and logistics hubs under India's Bureau of Civil Aviation Security directives.
- Banking:Financial institutions in Indian metro banking halls with iris and fingerprint recognition requirements.
Retail is climbing the fastest. Government holds the deepest compliance-driven pricing premium.
Technology:
Architecture choices fragment between edge-based processing and cloud-centralized models based on data localization rulings.
- Video Surveillance:Camera-embedded GPUs enable real-time facial recognition and behavioral analysis without server-room infrastructure. Manufacturing clusters in China's eastern seaboard and India's National Capital Region deploy these distributed processing architectures, decomposing legacy centralized security budgets.
- Biometrics:Multimodal fusion combining facial, fingerprint, and iris recognition sustains premium pricing at Indian banking halls and Philippine government centers. Vendors engineer region-specific firmware to satisfy divergent BIS certification and GB standards pathways.
- Cloud Security:Mid-market retail chains in Australia and Singapore adopt centralized multi-site management without dedicated IT staffing.
- IoT Solutions:Battery-backed sensors with Japan METI-influenced power efficiency specifications for remote Australian mining infrastructure.
Video Surveillance maintains the dominant revenue base. Biometrics is expanding most quickly on authentication depth requirements.
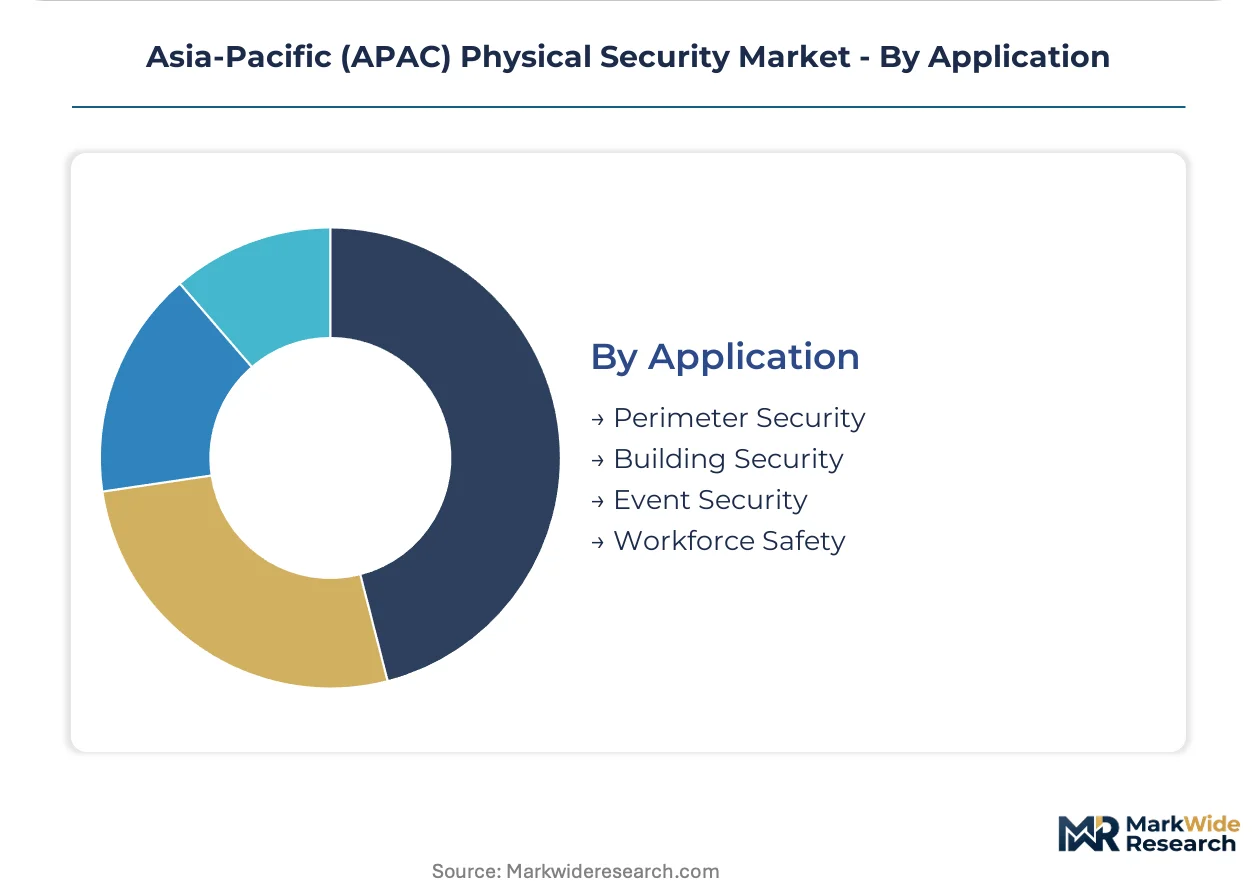
Application:
Use case specificity determines sensor specification, integration complexity, and service contract structure.
- Perimeter Security:Thermal imaging and edge-AI convergence for remote monitoring of Western Australian and Queensland mining zones. Solar-integrated enclosures address Japan METI-influenced standby power mandates for battery-backed sensors in plantation and extraction perimeters.
- Building Security:Integrated video surveillance and access control platforms dominate commercial real estate in Singapore and Tokyo. Johnson Controls anchors premium integration through Metasys platform dominance, with managed security service contracts displacing capital-heavy ownership.
- Event Security:Temporary deployment models for high-footfall environments requiring rapid threat classification.
- Workforce Safety:Audit trail generation for insurance and liability compliance in high-risk industrial settings.
Building Security commands the largest addressable spend. Perimeter Security is gaining share fastest on critical infrastructure protection enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards and India's BIS certification requirements anchor compliance complexity across the Asia-Pacific physical security landscape. Divergent national mandates fragment vendor economics and reshape deployment architectures.
China
Eastern seaboard manufacturing clusters drive camera hardware procurement at scale. GB/T 28181 national video interconnection standards force firmware customization for domestic interoperability. Hangzhou and Shenzhen anchor sensor fabrication and system integration capacity.
India
National Capital Region logistics corridors generate integrated access control demand. Bureau of Civil Aviation Security facial recognition mandates reshape airport and transportation hub procurement. Mumbai and Bangalore banking halls deploy multimodal biometric authentication systems.
Japan
Commercial real estate in Tokyo and Osaka sustains premium building security integration. METI energy efficiency mandates for IoT devices reshape power specifications for battery-backed sensors. Nagoya manufacturing zones pilot edge-AI convergence for workforce safety monitoring.
Australia
Western Australian and Queensland mining infrastructure drives perimeter security and thermal imaging procurement. Critical Infrastructure Protection Act enforcement through the Department of Home Affairs mandates automated incident reporting. Sydney and Melbourne commercial property operators adopt managed security service contracts.
Singapore
Smart city infrastructure bundling accelerates integrated video surveillance and access control platform deployment. Retail chains and commercial landlords prioritize cloud-native centralized management over capital ownership. Marina Bay and Jurong logistics hubs anchor regional procurement volume.
Asia-Pacific (APAC) Physical Security Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around platform-scale vendors and component-scale fabricators. The upper tier commands premium pricing through certification depth and vertical integration into sensor manufacturing. Specialist players occupy niche positions in biometric fusion, thermal imaging, and cloud-native orchestration. Competitive dynamics center on M&A activity targeting AI-enabled camera R&D and strategic partnerships bridging cybersecurity-physical security convergence expertise.
Within the integrated platform tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. represent Chinese-origin manufacturers with captive sensor supply chains. Johnson Controls occupies a position among building management system integrators with premium commercial real estate penetration. These three exemplify divergent strategic archetypes: vertically integrated hardware dominance, AI-focused component innovation, and platform-centric enterprise integration.
| Leading Market Players |
|---|
| Dahua Technology Co., Ltd. |
| Johnson Controls |
| Honeywell International Inc. |
| NEC Corporation |
| Axis Communications AB |
| Bosch Security Systems GmbH |
| Genetec Inc. |
| Cisco Systems Inc. |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with China's eastern seaboard sensor fabricators lock in both component access and cost visibility for video surveillance OEMs navigating GB/T 28181 compliance mandates. These arrangements insulate Hangzhou and Shenzhen manufacturers from spot-market volatility while compressing margins for second-tier vendors without captive supply.
Pricing Analysis
Price spreads between China's manufacturing clusters and Australian mining corridor deployments exceed three-to-one for equivalent 4K camera specifications. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels dominates procurement, with India's BIS certification and China's GB standards anchoring tier boundaries. Pricing pressure stems from Indonesian and Vietnamese analog replacement programs prioritizing volume over feature depth. Mid-market retail chains in Singapore exhibit highest price sensitivity, while Australian critical infrastructure operators absorb premiums for automated orchestration platforms.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose camera hardware shipments to Southeast Asian smart city projects. Image sensor fabrication concentrates in China's eastern seaboard, South Korea's memory foundries, and Japan's precision optics clusters. Raw material dependencies span silicon wafers, rare-earth magnet components, and lithium-ion cell chemistries for battery-backed perimeter sensors. Single-source vulnerability concentrates in CMOS sensor die supply. Distribution runs through regional system integrators with certification engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific physical security market sits at a high-growth inflection as edge-AI processing below 150ms latency collapses traditional server-room infrastructure economics. China's GB standards and India's BIS certification divergence is fragmenting vendor platforms and creating consolidation pressure.
For Market Incumbents: Compound platform stickiness through backward integration into AI chip design subsidiaries and captive sensor manufacturing. Deepen Metasys-class building management integration in Singapore and Tokyo commercial real estate to defend against cloud-native challengers. Prioritize cybersecurity-physical security convergence certification programs to address engineer scarcity choking project timelines. For New Entrants and Emerging Players: Lead with thermal-edge fusion pilots in Western Australian mining zones where incumbent coverage remains thin. Target Philippine government service centers deploying multimodal biometric authentication under fragmented compliance regimes. Anchor go-to-market through managed security service contracts rather than capital-heavy hardware sales to bypass incumbent distribution lock-in. For Investors and Strategic Acquirers: Cloud-native orchestration specialists with ASEAN data localization compliance capabilities represent the highest-conviction acquisition archetype. Position for five-to-ten year platform consolidation as divergence between China's GB standards and India's BIS requirements forces architectural specialization. Watch for cross-border data residency rulings across ASEAN member states as the signal for cloud-architected video storage inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI Chip Design Subsidiary Acquisition | Dahua Technology's captive R&D model demonstrates how in-house GPU architectures accelerate facial recognition latency below 150ms. |
| Managed Security Service Launch | Australia's mid-tier commercial real estate sector is abandoning capital ownership for operational expenditure predictability through video-surveillance-as-a-service. |
| Biometric Fusion Platform Integration | Indian banking halls and Philippine government centers are consolidating multimodal authentication vendors under BIS and divergent national standards. |
| Critical Infrastructure Certification Investment | Australia's Department of Home Affairs mandates automated incident reporting timelines that disqualify non-compliant orchestration platforms. |
| Solar-Integrated Enclosure Manufacturing Scale-Up | Japan's METI energy efficiency mandates for IoT devices are reshaping standby power specifications for remote Australian mining sensors. |
Methodological Framework
Operator-level perspectives from physical security system integrators, airport procurement officers under India's Bureau of Civil Aviation Security directives, mining infrastructure security directors, and smart city municipal technology leads anchored the qualitative base. Primary fieldwork combined with secondary validation against GB standards documentation, BIS certification registries, Australia's Critical Infrastructure Protection Act enforcement guidelines, and METI IoT efficiency mandates. Customs records for camera hardware imports, hyperscaler cloud security capex disclosures, and ASEAN data localization rulings provided quantitative triangulation through bottom-up deployment tracking and top-down market sizing.
Sensitivity analysis across edge-AI adoption velocity, biometric fusion penetration rates, and cloud-native architecture displacement speed shaped the forecast framework. Segmentation dimensions modeled include product type, end-user sector, technology architecture, and application intensity across the projection horizon. CAGRs derived from installation base refresh cycles, compliance mandate enforcement calendars, and managed service contract conversion rates. Industry-specific inputs incorporated GB/T 28181 firmware customization costs and solar-integrated enclosure manufacturing scale economics.
The analysis sits within stated boundaries; outcomes outside sustained smart city infrastructure funding, stable ASEAN cross-border data flow regimes, or continued dual-carbon policy enforcement in China would require recalibration. Forecasts reflect documented assumptions regarding edge processing cost curves and certification pathway divergence. Practitioners should keep alternative scenarios live as engineer scarcity severity and sensor supply geographic concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Global Wearable Security Device Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
France Data Center Physical Security Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Tactical Lights Market
Physical Security
Bulletproof Glass Market
Physical Security
North America Physical Security Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Security Guard Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Active Geofencing Market
Physical Security
Body Armor Market