
 Poland Data Center Physical Security Market | 2026-2036
Poland Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Data Center Physical Security Market Insights
Cloud provider buyer concentration is expanding across Poland's primary data center corridors. Axis Communications AB leverages its video surveillance specialization to anchor deployments in Warsaw's growing hyperscale cluster. Bosch Sicherheitssysteme GmbH sustains competitive positioning through integrated intrusion detection platforms. Schneider Electric dominates critical infrastructure power and access integration for Tier III and Tier IV facilities.
Poland Data Center Physical Security encompasses layered protection systems—surveillance cameras with thermal analytics, biometric access control, perimeter intrusion detection, and reinforced physical barriers—designed to safeguard computing infrastructure against unauthorized entry, environmental threats, and deliberate sabotage. Surveillance Systems lead technology adoption as operators mandate continuous visual coverage across multi-hectare campuses. Access Control represents the fastest-growing technology segment, driven by biometric integration and multi-factor authentication requirements for compliance-sensitive financial and government workloads. Monitoring services capture expanding margin pools as operators outsource round-the-clock security operations to specialized providers rather than building in-house command centers.
Polish facility operators navigate oversight from the national cybersecurity regulator alongside EU-wide frameworks including the NIS2 Directive and GDPR-mandated physical safeguards for personal data processing infrastructure. BIS-aligned facility certification requirements for critical infrastructure are tightening product standards for perimeter barriers and alarm response systems. Stakeholders must weigh capital allocation between standalone security upgrades and integrated building management platforms that consolidate physical and cyber monitoring under unified command architectures.
Market Dynamics
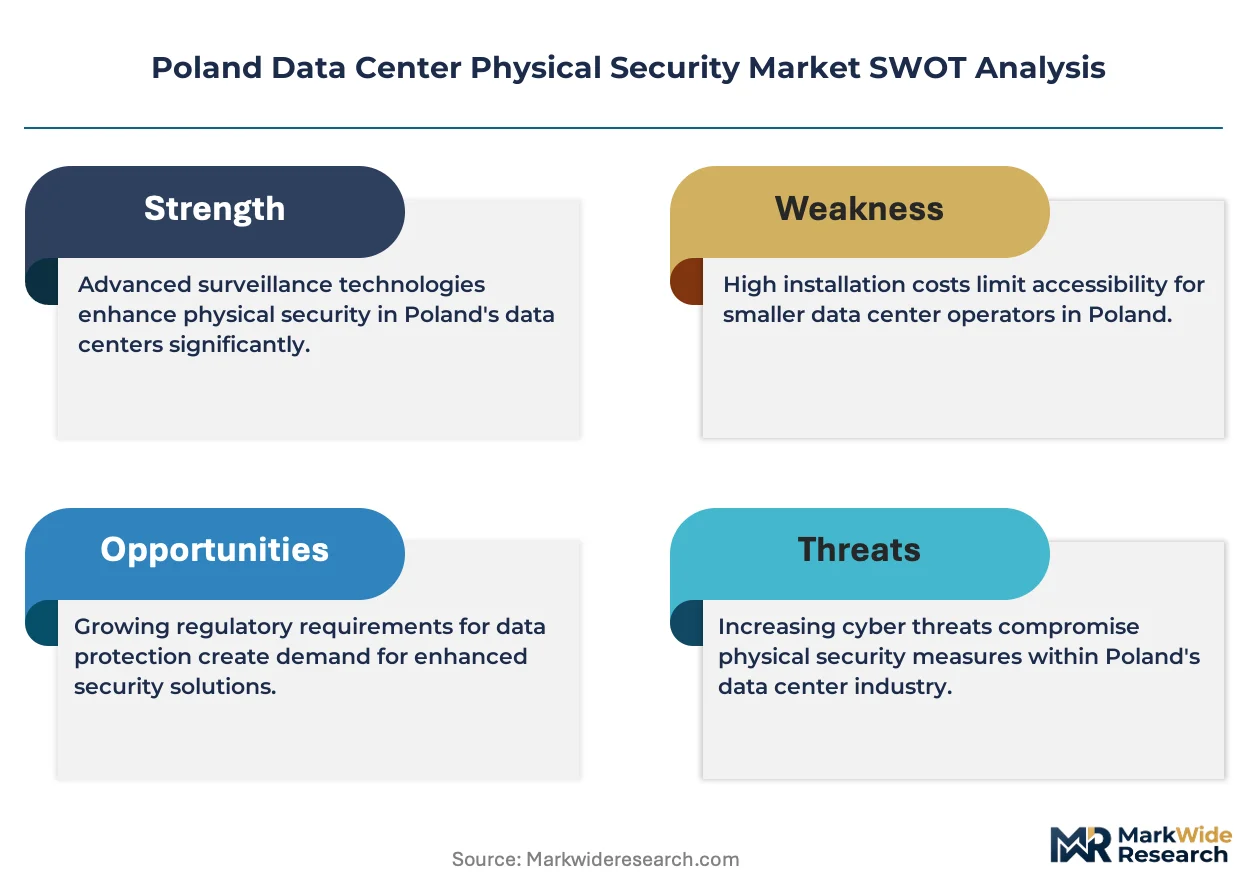
The EU AI Act and NIS2 Directive are forcing Polish data center operators to harden physical security architectures ahead of compliance deadlines, accelerating capital deployment into biometric access systems and integrated command platforms.
Growth Catalysts
- Hyperscale construction in Warsaw:Cloud providers are expanding multi-hectare campuses that mandate enterprise-grade perimeter protection and 24/7 surveillance coverage, pulling demand for thermal analytics and video management systems.
- GDPR-mandated physical safeguards:Personal data processing infrastructure must demonstrate documented access controls and audit trails, driving biometric multi-factor authentication adoption across financial services colocation facilities.
- National cybersecurity directives:Poland's critical infrastructure classification for data centers tightens facility certification standards for alarm response systems and reinforced barriers.
Market Restraints
- Specialized engineering talent scarcity:Integration of physical and cyber security systems requires cross-trained technicians familiar with both IEC 62443 and BIS-aligned barrier standards, constraining deployment velocity.
- Imported component dependency:Thermal camera sensors and enterprise access control hardware concentrate in Asian manufacturing hubs, exposing Polish integrators to extended lead times and currency volatility.
- Legacy facility retrofit complexity:Older Warsaw and Krakow data centers built before 2015 lack structural capacity for modern perimeter detection arrays, forcing costly civil works or partial security compromises.
Strategic Opportunities
- Tricity corridor underpenetration:Gdańsk-Gdynia-Sopot hosts emerging submarine cable landing points with limited Tier III facility security infrastructure, creating first-mover positioning for integrated platform vendors.
- AI-powered video analytics convergence:Machine learning-enabled threat detection fused with thermal imaging is compressing false alarm rates and enabling reduced guard staffing at hyperscale campuses.
- Outsourced security operations:Specialized monitoring providers are capturing margin pools as operators abandon in-house command center construction in favor of subscription-based round-the-clock surveillance services.
Industry Challenges
- Multi-vendor integration complexity:Stitching together surveillance, access control, and intrusion detection from disparate suppliers into unified building management platforms demands scarce systems architecture expertise.
- BIS certification timeline compression:Critical infrastructure facility approvals for perimeter barriers and alarm response systems are extending project schedules, forcing operators to sequence security deployment around construction milestones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Data Center Physical Security Market |
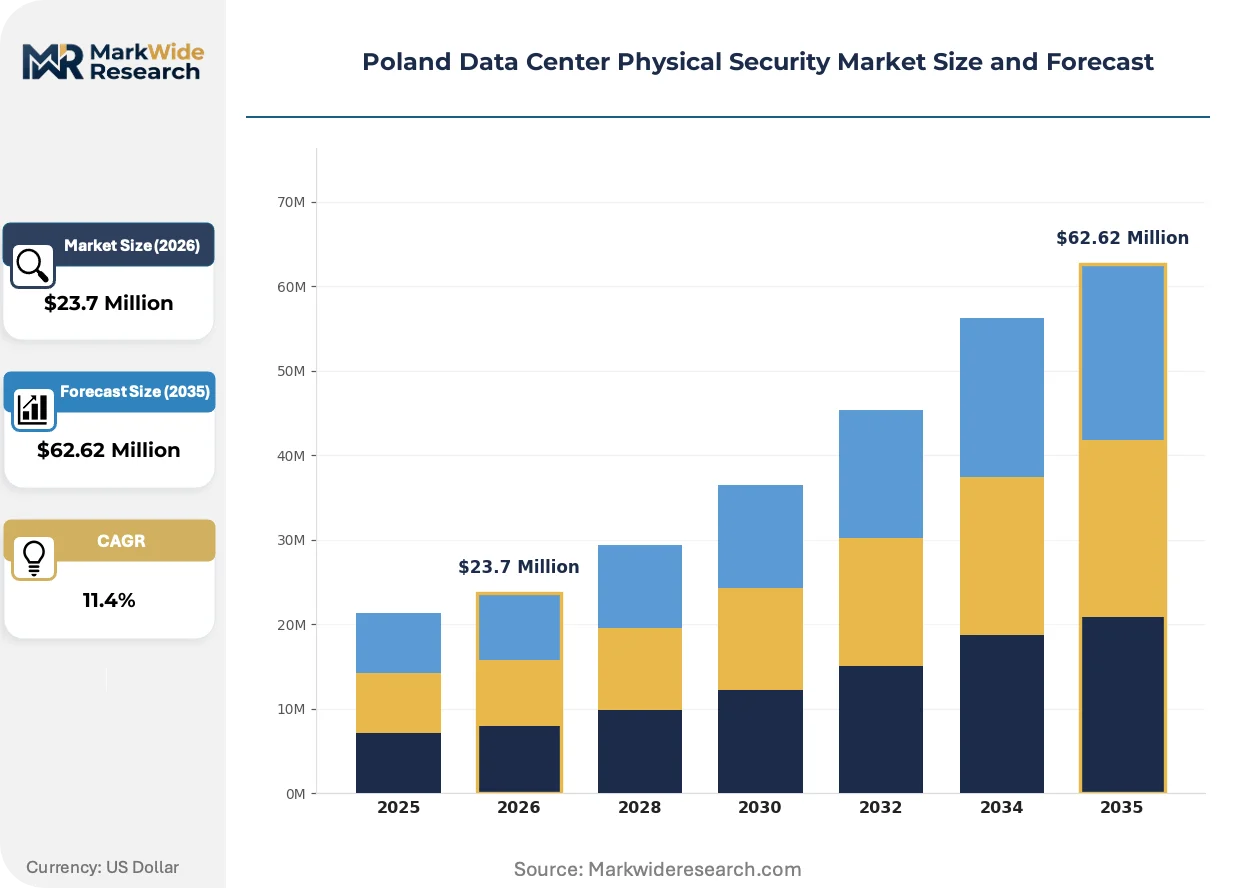
| Market Size in 2026 | $23.7 Million |
| Market Size in 2035 | $62.62 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Systems, Access Control, Intrusion Detection, Physical Barriers Service Type: Consulting, Installation, Maintenance, Monitoring End User: Financial Institutions, Telecom Providers, Government Agencies, Cloud Providers Product Type: Cameras, Alarms, Locks, Fencing |
| Companies Covered | Axis Communications AB, ABB Ltd, Securitas Technology, Bosch Sicherheitssysteme GmbH, Johnson Controls, Honeywell International Inc, Siemens AG, Schneider Electric, Cisco Systems Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Data Center Physical Security Market Trends and Innovations
Physical security architectures in Polish data centers are converging with building management systems and IT infrastructure monitoring, collapsing operational silos that previously separated facilities teams from cybersecurity operations.
Unified physical-cyber command platforms are unifying video surveillance, access logs, and environmental sensors into single-pane dashboards. Tier III and Tier IV facility operators in Warsaw are adopting these integrated architectures fastest. This convergence is compressing vendor count per site and elevating Schneider Electric and similar infrastructure specialists over standalone security hardware suppliers.
EU AI Act risk classification requirements for high-impact AI systems are mandating documented physical access controls for model training infrastructure. Polish operators hosting GPU clusters for generative AI development must now demonstrate biometric-protected server cages and audit-trail completeness. Financial services and government cloud segments are responding with accelerated procurement of facial recognition and palm-vein authentication systems.
Facility operators are consolidating vendor relationships around integrated platform providers capable of delivering surveillance, access control, and power monitoring through single contracts. Traditional standalone security integrators are losing share to building automation specialists with cybersecurity credentials. This pattern is most visible in Krakow's emerging hyperscale cluster, where cloud providers prioritize operational simplicity over best-of-breed component selection.
Poland Data Center Physical Security Market Segmentation
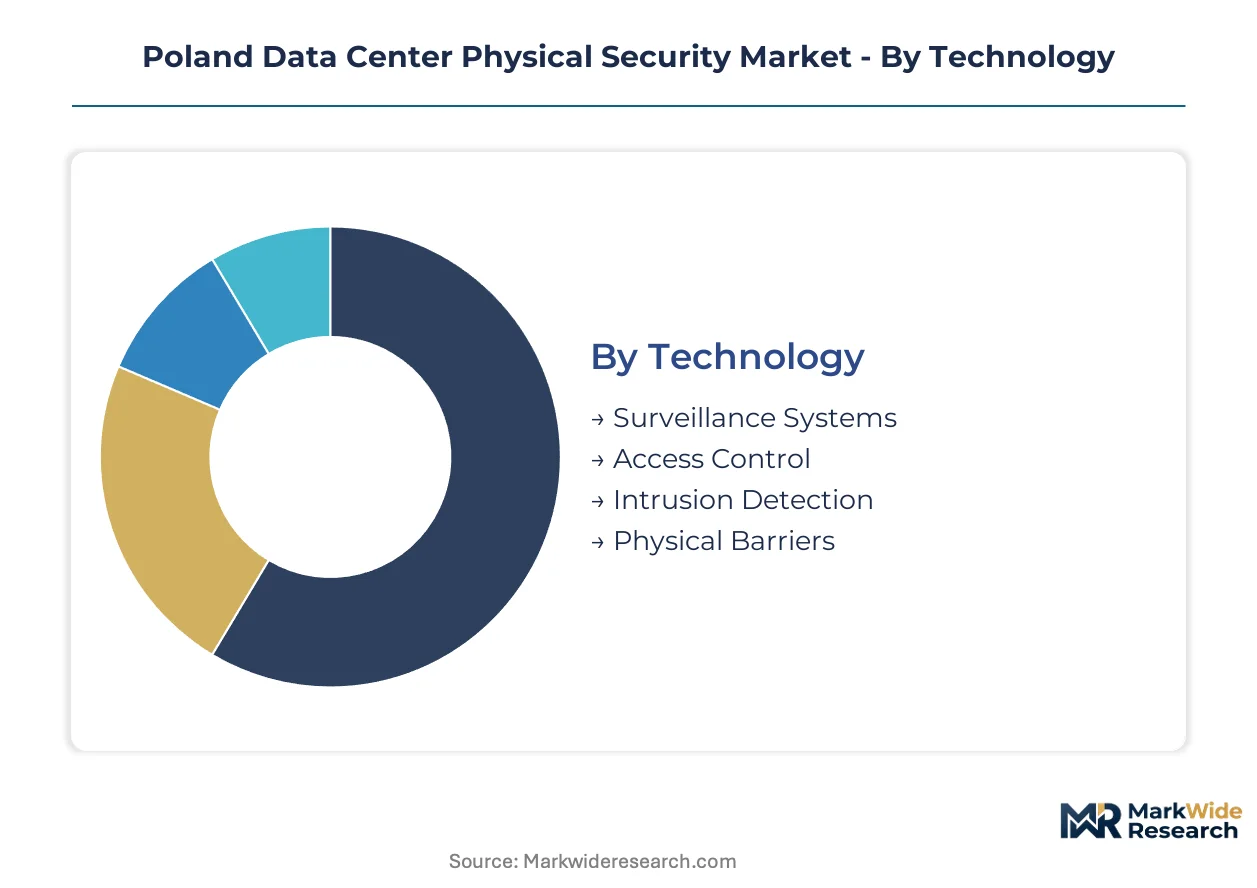
Polish data center operators make procurement decisions across four intersecting dimensions. Technology choices determine capital intensity and compliance posture. Service models shift risk between in-house teams and outsourced providers. End-user requirements vary sharply between financial regulatory mandates and cloud provider scale economics.
Technology:
Facility operators prioritize integration depth over standalone performance when selecting security layers.
- Surveillance Systems:Video management platforms with thermal analytics and edge-based processing dominate Warsaw hyperscale deployments. Cloud providers mandate continuous visual coverage across multi-hectare campuses, pulling demand for AI-enabled threat classification and reduced false alarm rates.
- Access Control:Biometric multi-factor authentication systems—facial recognition, palm-vein scanning, and mobile credentialing—are expanding fastest. GDPR-mandated audit trails for personal data processing infrastructure drive adoption across Krakow financial services colocation facilities.
- Intrusion Detection:Perimeter sensor arrays combining radar, fiber-optic cable, and seismic detection protect Tier III and Tier IV sites. BIS-aligned certification requirements for critical infrastructure tighten product standards for alarm response latency.
- Physical Barriers:Reinforced fencing, anti-ram bollards, and ballistic-rated enclosures form the outer defense layer. Legacy facility retrofits in older Warsaw districts face structural capacity constraints for modern barrier systems.
Volume sits with Surveillance Systems; growth tilts toward Access Control.
Service Type:
Risk transfer preferences vary by operator maturity and capital availability.
- Consulting:Security architecture design and compliance gap assessments precede major hyperscale construction. Polish operators engage specialized advisors to navigate EU AI Act physical safeguard requirements for AI training infrastructure.
- Installation:System deployment and commissioning services concentrate around Warsaw and Krakow construction corridors. Multi-vendor integration complexity demands scarce cross-trained technicians familiar with both IEC 62443 and national barrier standards.
- Maintenance:Preventive service contracts and hardware refresh programs sustain operational readiness. Extended lead times for Asian-sourced thermal camera sensors complicate spare parts inventory planning.
- Monitoring:Subscription-based round-the-clock surveillance operations capture expanding margin pools. Cloud providers increasingly outsource command center functions rather than building in-house security operations centers.
Revenue concentrates in Installation; margin expansion favors Monitoring.
End User:
Compliance sensitivity and scale economics create divergent procurement patterns.
- Financial Institutions:Banks and insurance operators mandate biometric-protected server cages with complete audit trail documentation. National cybersecurity directives for critical infrastructure classification accelerate capital deployment into hardened access architectures.
- Cloud Providers:Hyperscale operators prioritize operational simplicity and unified vendor relationships over best-of-breed component selection. Krakow's emerging cluster shows strongest concentration of integrated platform procurement.
- Government Agencies:State-owned facilities and defense-adjacent data centers require BIS-certified perimeter barriers and alarm response systems. Project timelines extend around certification milestones.
- Telecom Providers:Carrier-neutral facilities and 5G edge data centers balance cost discipline with baseline compliance. Tricity corridor submarine cable landing points create emerging demand for Tier III security infrastructure.
Cloud Providers anchor volume; Financial Institutions drive premium pricing.
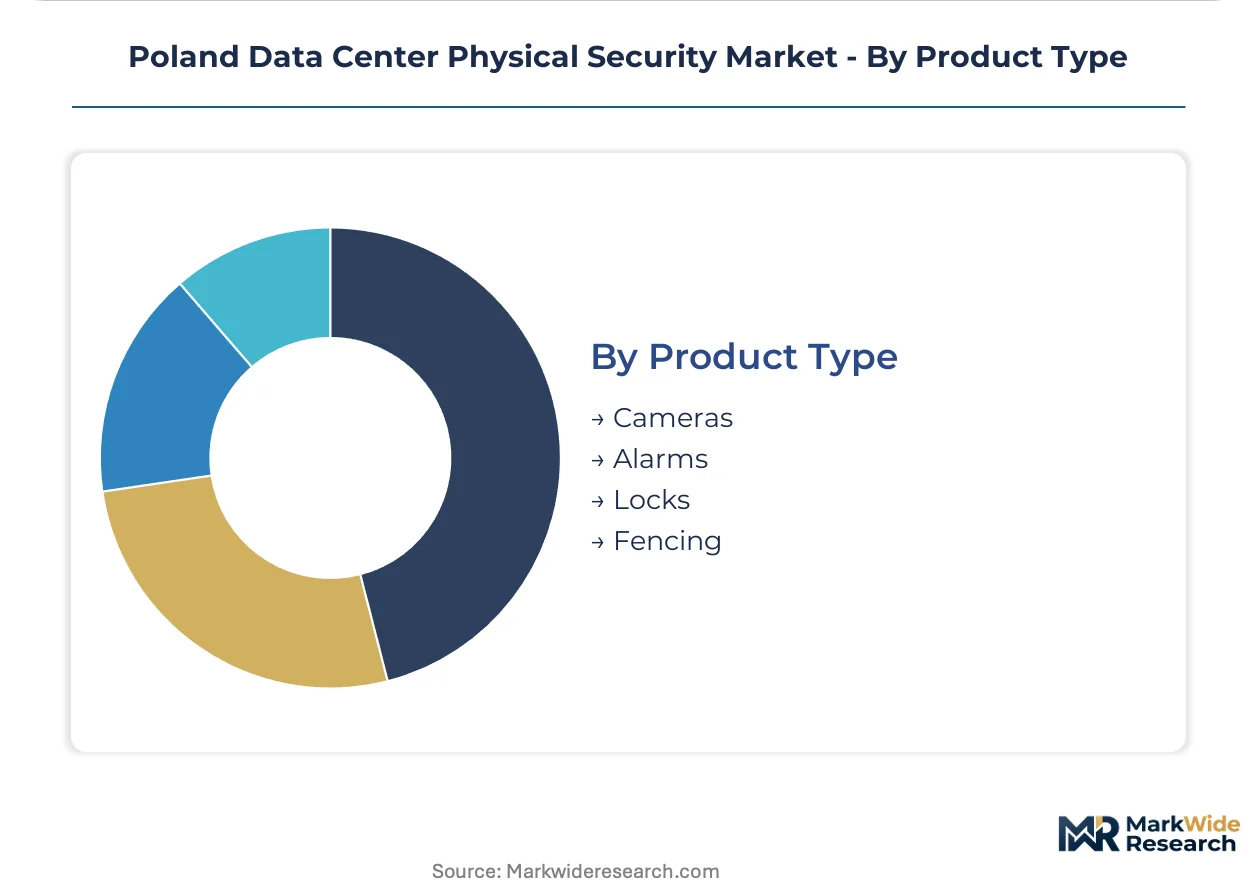
Product Type:
Hardware selection follows technology architecture decisions with limited substitution flexibility.
- Cameras:Thermal imaging and visible-light sensors with edge analytics form the surveillance backbone. AI-powered video analytics convergence compresses false alarm rates and enables reduced guard staffing.
- Alarms:Intrusion detection panels and perimeter alarm controllers integrate with building management systems. Unified physical-cyber command platforms elevate infrastructure specialists over standalone security hardware suppliers.
- Locks:Electronic strikes, magnetic locks, and biometric readers secure controlled access points. Multi-factor authentication requirements displace legacy card-based systems.
- Fencing:Anti-climb mesh, palisade barriers, and crash-rated perimeter walls define site boundaries. Reinforced barrier standards for critical infrastructure tighten material specifications.
Cameras generate the largest hardware revenue; Alarms show steepest integration-driven growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's data center security market clusters around metropolitan fiber hubs and power interconnection points. Warsaw and Krakow anchor hyperscale deployment corridors. The Tricity corridor emerges as a submarine cable landing zone with underdeveloped Tier III infrastructure.
Warsaw
Hyperscale cloud campuses drive perimeter protection procurement across multi-hectare sites. The EU AI Act mandates biometric access controls for AI training infrastructure. Mokotów and Praga districts concentrate new Tier IV construction with integrated command platforms.
Krakow
Financial services colocation demands GDPR-compliant audit trails and hardened server cages. National cybersecurity directives classify data centers as critical infrastructure. The Podgórze technology corridor attracts cloud providers prioritizing unified vendor relationships.
Tricity Corridor
Submarine cable landings at Gdańsk and Gdynia create latency-sensitive edge computing demand. Limited existing Tier III security infrastructure leaves first-mover positioning for integrated platform vendors. The Baltic Sea fiber route to Scandinavia and Germany accelerates facility planning.
Wrocław
Lower Silesia's industrial power surplus attracts energy-intensive computing workloads. BIS-aligned barrier certification requirements extend project timelines for perimeter hardening. The Wrocław Technology Park hosts emerging carrier-neutral facilities with baseline compliance needs.
Łódź
Central Poland's geographic position supports disaster recovery and backup site selection. Telecom providers balance cost discipline against national cybersecurity directive thresholds. The city's fiber ring expansion lags Warsaw and Krakow in security infrastructure maturity.
Poland Data Center Physical Security Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-powered analytics convergence and outsourced monitoring services. The vendor base stratifies across infrastructure integration specialists, standalone security hardware suppliers, and subscription-based monitoring providers. Three archetypes dominate: building automation platforms with cybersecurity credentials, video surveillance specialists with thermal analytics, and integrated intrusion detection platforms. Capacity expansion and strategic partnerships represent the dominant competitive vectors as operators consolidate vendor relationships.
Within the infrastructure integration tier, Schneider Electric and ABB Ltd exemplify platform consolidation strategies that collapse physical and cyber monitoring into unified command architectures. Axis Communications AB represents video surveillance specialization anchoring hyperscale deployments. Bosch Sicherheitssysteme GmbH occupies a position in integrated intrusion detection for Tier III and Tier IV certification requirements.
| Leading Market Players |
|---|
| Axis Communications AB |
| ABB Ltd |
| Securitas Technology |
| Bosch Sicherheitssysteme GmbH |
| Johnson Controls |
| Honeywell International Inc |
| Siemens AG |
| Schneider Electric |
| Cisco Systems Inc |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between BIS-aligned critical infrastructure tiers and baseline commercial deployments manifests in divergent pricing power and sourcing complexity across Polish data center security procurement. Premium-tier biometric access systems and reinforced perimeter barriers command substantial cost premiums while drawing from concentrated European supplier networks, whereas standard surveillance hardware faces cost compression from Asian manufacturing scale.
Pricing Analysis
Warranty bundling and multi-year service contracts separate integrated platform vendors from standalone hardware suppliers in Polish procurement decisions. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity, with BIS-aligned barrier systems and biometric server cages anchoring the premium band. Cost compression in thermal camera and enterprise access control hardware intensifies as cloud providers consolidate vendor relationships around single-contract building automation platforms. Cloud providers exhibit lowest price sensitivity, prioritizing operational simplicity and unified command architectures over component-level cost optimization.
Supply Chain Analysis
Poland's national cybersecurity directives and EU content rules are reshaping sourcing patterns for critical infrastructure components, though thermal camera sensors and enterprise access control hardware still concentrate in Chinese, South Korean, and Taiwanese manufacturing hubs. Fiber-optic perimeter sensors and edge analytics processors draw from German and Dutch specialist suppliers, creating dual-source dependencies. Single-source vulnerability in Asian-sourced biometric readers and thermal imaging modules exposes Polish integrators to extended lead times and currency volatility. Distribution runs through Warsaw-based systems integrators and Krakow construction corridor specialists serving hyperscale deployment clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as infrastructure specialists capture share from standalone security vendors by consolidating surveillance, access control, and power monitoring under unified command platforms. Players are pursuing backward integration into AI-powered video analytics and subscription-based monitoring services to defend margin pools.
For Market Incumbents: Lock in hyperscale cloud provider relationships through integrated platform contracts that collapse vendor count per site, while investing in BIS certification capabilities to capture critical infrastructure facility approvals ahead of compliance deadlines. Threat from AI-powered analytics specialists demands accelerated R&D in machine learning-enabled threat detection to prevent displacement in Warsaw's Tier IV construction corridor. For New Entrants and Emerging Players: Regional systems integrators in the Tricity corridor represent the most penetrable channel partner type for first-mover positioning, given limited existing Tier III security infrastructure around Gdańsk-Gdynia-Sopot submarine cable landing points. Target financial services colocation facilities in Krakow with GDPR-compliant biometric audit trail solutions, leveraging outsourced monitoring services as the primary go-to-market angle to bypass capital-intensive in-house command center competition. For Investors and Strategic Acquirers: Re-rating potential sits with AI-powered video analytics specialists given EU AI Act risk classification requirements for high-impact AI systems driving biometric-protected server cage mandates. Long-term viability favors platforms with cybersecurity credentials capable of converging physical and IT infrastructure monitoring. Watch hyperscale procurement consolidation patterns as the inflection signal indicating which integrated vendors are capturing cloud provider volume.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified command architectures collapse vendor count and elevate infrastructure specialists over standalone suppliers in Warsaw hyperscale deployments. |
| AI-Powered Video Analytics Convergence | Machine learning-enabled threat detection compresses false alarm rates and enables reduced guard staffing at multi-hectare cloud campuses. |
| Monitoring Services Expansion | Subscription-based round-the-clock surveillance captures margin pools as operators abandon in-house security operations center construction. |
| BIS Certification Investment | Critical infrastructure facility approvals for perimeter barriers extend project timelines, creating competitive moats for certified suppliers. |
| Tricity Corridor Market Entry | Gdańsk-Gdynia-Sopot submarine cable landings create latency-sensitive edge computing demand with underdeveloped Tier III security infrastructure. |
Research Methodology
Multi-period observation of hyperscale construction permits, BIS certification timelines, and cloud provider capex disclosures anchored the trend analysis, supplemented by interviews with data center facility managers, security systems integrators, and building automation procurement officers. Primary fieldwork combined with secondary validation against EU regulatory filings, national cybersecurity directive drafts, and construction industry databases. Bottom-up project pipeline tracking across Warsaw, Krakow, and Tricity corridors triangulated with top-down market sizing from infrastructure vendor revenue disclosures.
Input-output matrices modeled technology adoption rates, service model penetration, and end-user segment growth across the projection horizon. Segmentation dimensions included technology layer, service type, end-user vertical, and facility tier classification. CAGRs derived from facility construction forecasts, compliance deadline schedules, and vendor capacity expansion announcements. AI training infrastructure deployment and biometric authentication procurement patterns served as industry-specific demand indicators.
Caveats apply where NIS2 Directive implementation delays or BIS certification timeline extensions could materially shift the outlook, alongside potential supply chain disruptions in Asian-sourced thermal imaging components. Forecasts reflect assumptions around regulatory enforcement consistency and hyperscale construction continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
North America Physical Security Market
Physical Security
Airport Full Body Scanner Market
Physical Security
Body Armor Plates Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
South America Data Center Physical Security Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Active Geofencing Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Policing Technologies Market
Physical Security
Physical Security Services Market
Physical Security
Security Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Body Armor Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Europe Physical Security Market