
 Active Geofencing Market | 2026-2036
Active Geofencing Market Size, Share, and Industry Trends Forecast 2026-2036
Active Geofencing Market Analysis
The capital-intensity divergence between cloud-native platforms and legacy on-premises vendors is unwinding competitive hierarchies in active geofencing. Google LLC leverages its mapping infrastructure and Android device penetration to dominate consumer-facing location services. IBM Corporation anchors enterprise contracts through hybrid cloud deployments that integrate geofencing with broader analytics stacks. Bluedot Innovation Pty Ltd specializes in high-precision Bluetooth beacon technology for retail and transit applications.
Active geofencing denotes a location-based service that establishes virtual perimeters around physical geographic areas, triggering automated actions when GPS, Bluetooth, RFID, or Wi-Fi enabled devices cross predefined boundaries with accuracy thresholds typically ranging from one meter to several hundred meters depending on the underlying technology. Fleet management applications command substantial deployment volumes as logistics operators enforce route compliance, dwell-time limits, and unauthorized-use alerts across distributed vehicle assets. Retail marketing deployments generate concentrated margin pools through personalized push notifications and foot-traffic attribution, though privacy constraints tighten data-collection scope. Government agencies represent an expanding end-user category for perimeter security and emergency-response zone management.
The Federal Communications Commission shapes carrier-grade location accuracy mandates in the United States, while the European Union's GDPR and AI Act impose consent-layer requirements and algorithmic transparency obligations on automated geofencing decisions. China's MIIT and GB standards govern domestic data-localization rules that restrict cross-border transmission of location traces from connected devices. Stakeholders must monitor diverging national data-sovereignty frameworks when architecting multi-territory geofencing infrastructure.
Market Dynamics
The collision between precision-location hardware commoditization and escalating data-sovereignty mandates is forcing geofencing vendors to rearchitect data pipelines around jurisdictional boundaries rather than technical performance alone.
Growth Catalysts
- Fleet telematics mandates:Logistics operators in Germany deploy GPS-based perimeter enforcement to optimize electric vehicle charge-point access and route compliance across distributed assets.
- GDPR Article 6 lawful-basis frameworks:Consent-management platforms that embed geofencing into granular opt-in workflows unlock retail marketing deployments previously blocked by compliance uncertainty.
- Bluetooth beacon density:Transit authorities in Japan install high-precision beacon arrays for passenger flow analytics and platform safety zoning.
Market Restraints
- Silicon supply concentration:GPS and Bluetooth chipset fabrication concentrates in Taiwan and South Korea, exposing hardware vendors to single-source disruption risk.
- GDPR algorithmic-transparency obligations:Automated geofencing decisions triggering device lockouts or access denials require explainable logic layers that inflate development overhead.
- Wi-Fi fingerprinting substitution:Indoor positioning systems leveraging existing wireless infrastructure bypass dedicated beacon hardware in cost-sensitive retail deployments.
Strategic Opportunities
- India smart-city infrastructure:Municipal corporations in Bengaluru and Hyderabad tender perimeter-security contracts integrating geofencing with traffic management and emergency response coordination.
- EU AI Act conformity assessments:Third-party certification for high-risk location-based automated decision systems creates recurring revenue streams for compliance service providers.
- Ultra-wideband convergence:UWB radio technology combined with Bluetooth Low Energy enables centimeter-accuracy indoor positioning for warehouse robotics and asset tracking.
Industry Challenges
- Embedded systems firmware expertise:Vendors struggle to hire engineers capable of optimizing power-consumption algorithms for battery-operated beacon deployments at scale.
- Legacy SCADA integration:Industrial facilities require middleware development to bridge modern API-driven geofencing platforms with decades-old control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Geofencing Market |
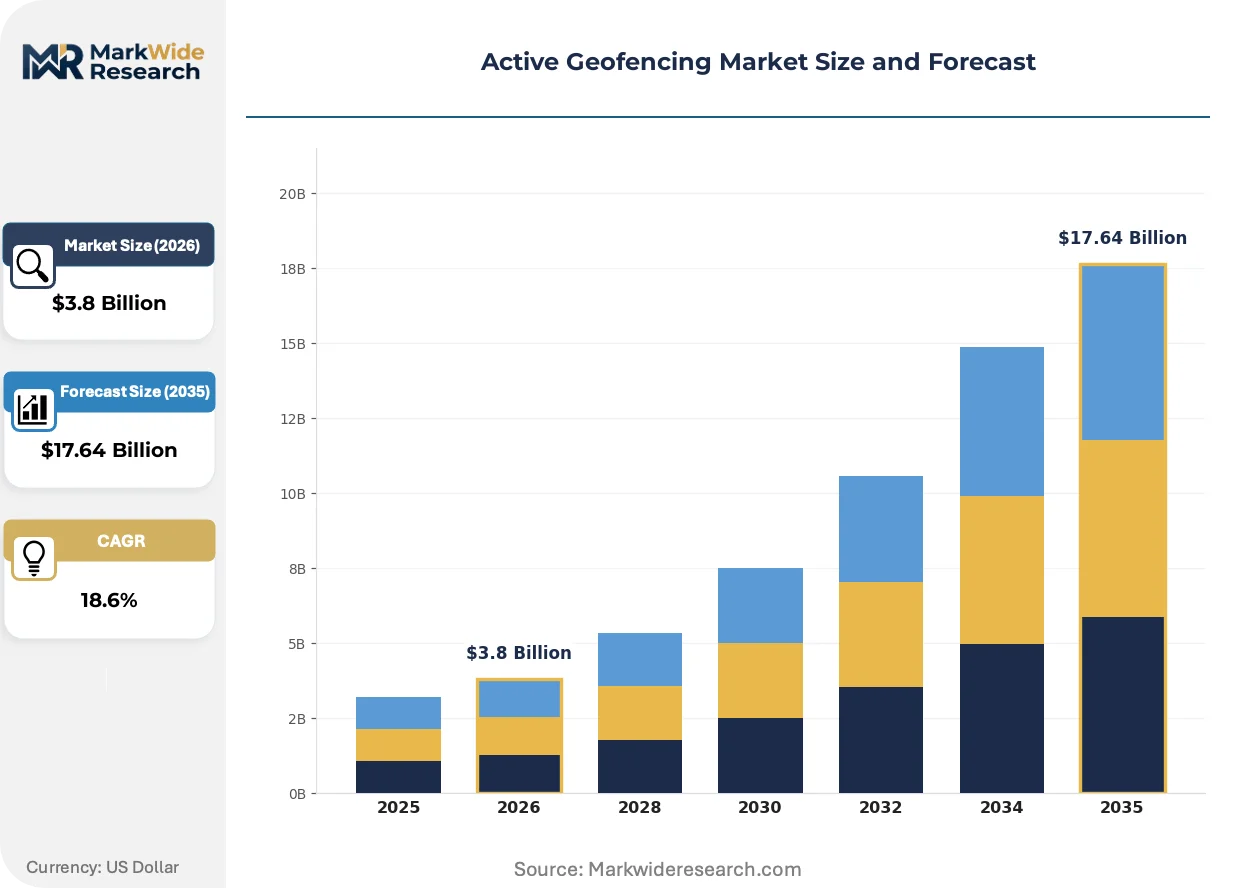
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth, GPS, RFID, Wi-Fi Application: Retail Marketing, Fleet Management, Public Safety, Location Tracking End User: Enterprises, Government Agencies, Event Organizers, Consumers Deployment: Cloud-based, On-premises, Hybrid, Mobile Platforms |
| Companies Covered | Bluedot Innovation Pty Ltd, Google LLC, Radar Labs Inc., LocationSmart, Infillion, IBM Corporation, Microsoft Corporation, ESRI India Technologies Private Limited, Apple Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Geofencing Market Emerging Trajectories
Active geofencing is pivoting from perimeter detection toward predictive intent inference, with hardware form factors and data governance frameworks evolving in parallel to enable anticipatory rather than reactive location services.
Ultra-wideband chipsets are miniaturizing into sub-millimeter packages while maintaining sub-10-centimeter accuracy, enabling smartphone OEMs to embed spatial-awareness hardware without sacrificing device thickness or battery capacity. Automotive suppliers in South Korea integrate these modules into digital key systems for passive entry authentication. The component cost curve is compressing premium positioning capabilities into mid-tier consumer electronics.
The EU AI Act's risk-classification framework for biometric and location-based automated decision systems imposes conformity-assessment obligations on geofencing deployments affecting critical infrastructure or public spaces. German automotive OEMs now document algorithmic logic for charge-point access denial triggers. This regulatory layer is segmenting vendor capabilities between certified enterprise-grade platforms and uncertified consumer applications.
Subscription-based location-intelligence contracts are displacing perpetual-license sales in enterprise fleet management, with logistics operators in the United States preferring usage-aligned pricing tied to active vehicle counts. Channel partners restructure compensation around recurring revenue share rather than upfront margin. This shift concentrates account control with platform vendors possessing native cloud infrastructure.
Active Geofencing Market Segmentation
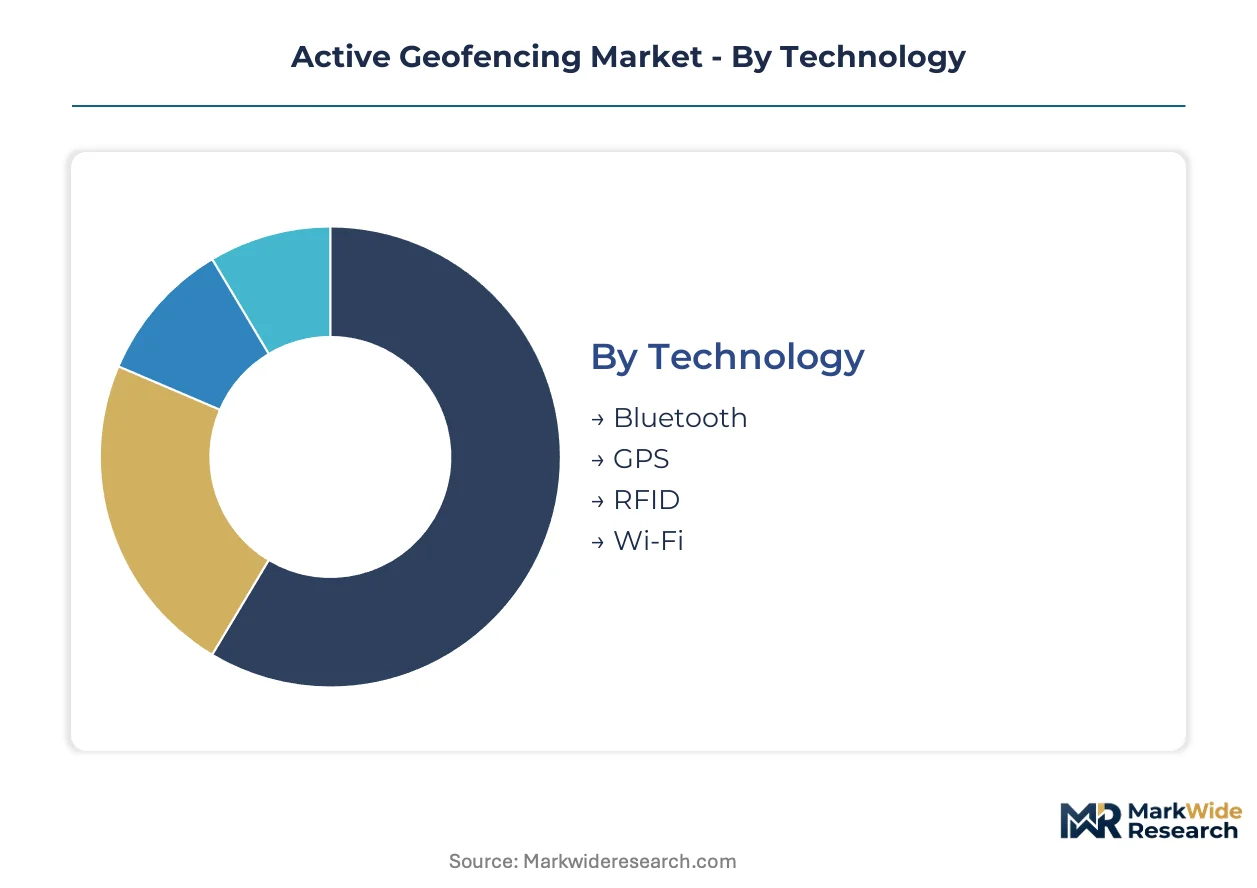
Technology choice determines accuracy thresholds and power consumption trade-offs in active geofencing deployments. Application focus shapes data governance requirements and integration complexity. End-user category dictates procurement patterns and compliance obligations.
Technology:
GPS-based systems capture premium pricing for outdoor perimeter enforcement, while Bluetooth beacon arrays dominate indoor proximity marketing budgets.
- Bluetooth:Low-energy beacon protocols enable sub-meter indoor positioning with minimal power draw. Retail chains in the United States deploy dense beacon grids for foot-traffic attribution and personalized push notification triggers, though GDPR consent-layer requirements inflate deployment overhead.
- GPS:Satellite-based positioning delivers hundred-meter to meter-scale accuracy for outdoor asset tracking. Fleet operators in Germany mandate GPS perimeter enforcement for electric vehicle charge-point access control and route compliance across distributed logistics networks.
- RFID:Passive and active radio-frequency tags support short-range identification without battery dependency in controlled environments.
- Wi-Fi:Fingerprinting techniques leverage existing infrastructure for indoor positioning, bypassing dedicated hardware costs in budget-constrained retail deployments.
The dominant share belongs to GPS, while Bluetooth is closing the gap fastest.
Application:
Retail marketing generates concentrated margin pools through attribution analytics, whereas fleet management commands deployment volume through operational compliance mandates.
- Retail Marketing:Proximity-triggered campaigns combine foot-traffic measurement with personalized offer delivery. United States retailers integrate beacon-triggered notifications into loyalty applications, constrained by tightening state-level privacy regulations on location data collection scope.
- Fleet Management:Route compliance, dwell-time monitoring, and unauthorized-use alerts protect distributed vehicle assets. German logistics operators embed geofencing into telematics platforms for electric vehicle charge-point access control.
- Public Safety:Perimeter security and emergency-response zone management support government agency deployments for crowd control and disaster coordination.
- Location Tracking:Asset and personnel monitoring applications span construction sites, healthcare facilities, and industrial warehouses.
Fleet management holds volume leadership, with retail marketing expanding most quickly as consent-management platforms resolve compliance uncertainty.
End User:
Enterprise procurement concentrates spending in multi-year platform contracts, while government agencies drive demand for certified high-security deployments.
- Enterprises:Retail chains, logistics operators, and industrial facilities purchase integrated location-intelligence platforms. United States enterprises prefer subscription pricing tied to active device counts over perpetual licenses.
- Government Agencies:Municipal corporations and national security bodies require perimeter enforcement for critical infrastructure protection. German automotive regulators mandate algorithmic documentation for charge-point access denial triggers under EU AI Act conformity frameworks.
- Event Organizers:Temporary deployments for crowd flow management and safety zoning at sporting venues and festivals.
- Consumers:Smartphone-integrated services for location-based reminders, family safety, and retail loyalty applications.
Enterprises command the largest revenue share, though government agencies are gaining share fastest through critical infrastructure mandates.
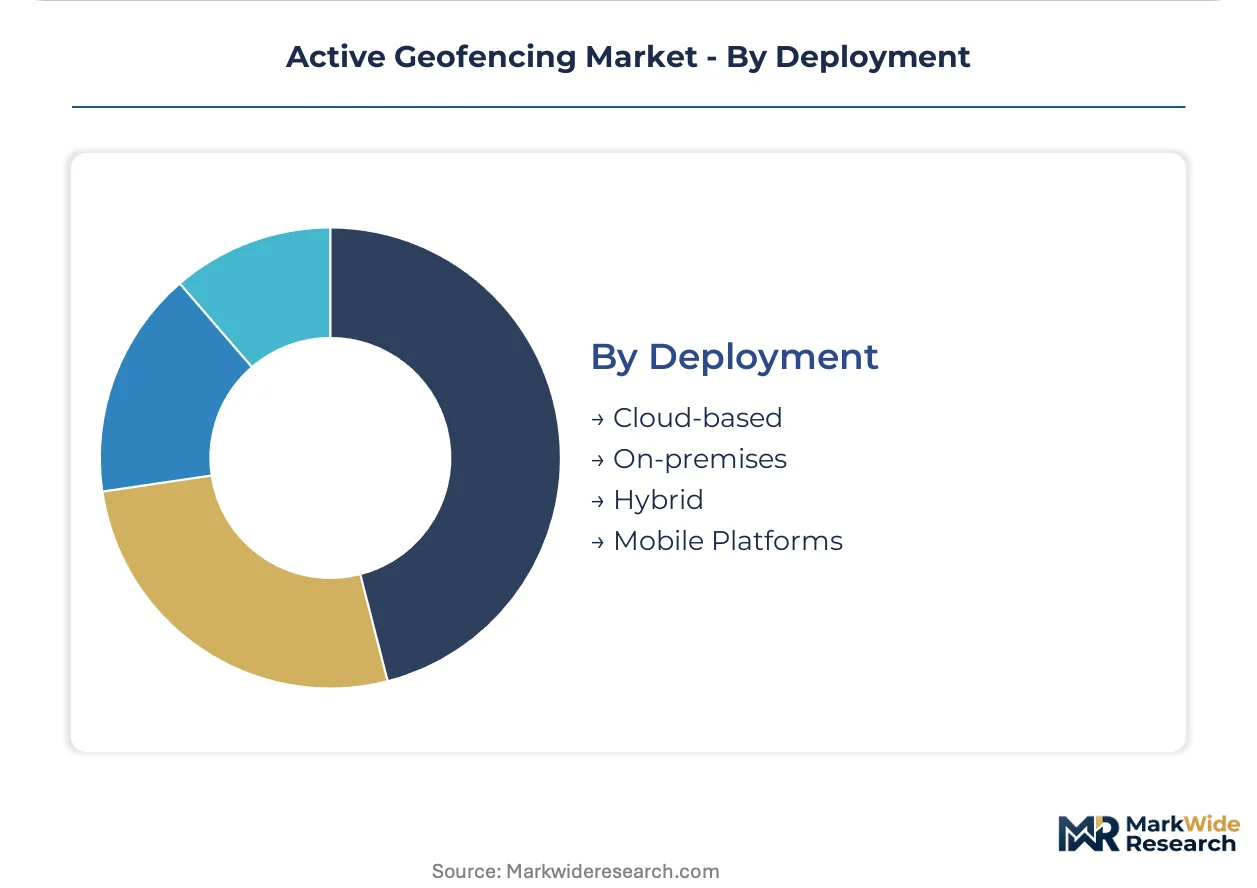
Deployment:
Cloud-native architectures displace on-premises installations as data-sovereignty tools enable jurisdictional boundary enforcement without sacrificing scalability.
- Cloud-based:Scalable infrastructure supports dynamic perimeter configuration and real-time analytics. United States logistics operators align pricing with active vehicle counts through usage-based subscription models.
- On-premises:Air-gapped installations serve defense and critical infrastructure operators with strict data-localization requirements. China's MIIT regulations restrict cross-border transmission of location traces from connected devices.
- Hybrid:Edge processing with cloud aggregation balances latency sensitivity and computational depth for industrial IoT deployments.
- Mobile Platforms:Smartphone-native SDKs enable rapid consumer application deployment without dedicated hardware investment.
Cloud-based deployment leads adoption, while hybrid architectures are climbing the fastest as sovereignty-aware data pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German automotive OEMs absorb premium pricing for EU AI Act-compliant fleet telematics, while Indian municipal buyers prioritize lowest-cost cloud deployments for smart-city perimeter security.
United States
Retail chains deploy Bluetooth beacon grids for proximity marketing campaigns, though state-level privacy laws in California and New York constrain data collection scope. The FCC mandates carrier-grade location accuracy thresholds for emergency services integration. Fleet operators in Dallas-Fort Worth and Chicago metropolitan corridors purchase subscription-based geofencing tied to active vehicle counts.
Germany
Automotive OEMs integrate GPS-based perimeter enforcement into electric vehicle charge-point access control and route compliance systems. The EU AI Act and GDPR impose algorithmic transparency obligations on automated geofencing decisions affecting critical infrastructure. Logistics clusters in Stuttgart and Wolfsburg mandate telematics platforms with documented logic layers for denial triggers.
China
Domestic technology vendors serve municipal smart-city tenders for traffic management and emergency response coordination. MIIT regulations and GB standards enforce strict data-localization rules that restrict cross-border transmission of location traces. Shenzhen and Hangzhou deploy dense beacon arrays for public transit passenger flow analytics.
India
Municipal corporations in Bengaluru and Hyderabad tender perimeter-security contracts integrating geofencing with traffic signal coordination and disaster response systems. The Digital India initiative accelerates cloud-native infrastructure adoption for government agency deployments. Cost-sensitive procurement favors Wi-Fi fingerprinting over dedicated beacon hardware in retail implementations.
Japan
Transit authorities install high-precision Bluetooth beacon arrays for platform safety zoning and passenger flow optimization in dense urban corridors. METI guidelines shape industrial IoT standards for warehouse robotics integration. The Tokyo-Osaka corridor concentrates demand for ultra-wideband-enabled asset tracking in automotive supply chain facilities.
Active Geofencing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in active geofencing. Cloud-native platforms with mapping infrastructure dominate consumer-facing deployments, while hybrid-cloud vendors anchor enterprise contracts requiring data-sovereignty compliance. Three archetypes define competitive positioning: mapping-integrated technology conglomerates, precision-location hardware specialists, and enterprise analytics platform providers. Consolidation pressure intensifies through strategic partnerships bridging beacon hardware with cloud software stacks, alongside vertical integration into chipset fabrication.
Among technology conglomerates with mapping infrastructure, Google LLC and Microsoft Corporation exemplify scale-driven platform approaches. IBM Corporation occupies a position within the enterprise hybrid-cloud tier, anchoring multi-year contracts through integration with broader analytics stacks. Bluedot Innovation Pty Ltd represents the precision-hardware specialist archetype, with Australian-registered corporate structure signaling geographic concentration in Asia-Pacific retail and transit deployments.
| Leading Market Players |
|---|
| Bluedot Innovation Pty Ltd |
| Google LLC |
| Radar Labs Inc. |
| LocationSmart |
| Infillion |
| IBM Corporation |
| Microsoft Corporation |
| ESRI India Technologies Private Limited |
| Apple Inc |
| Others |
Supply Flow & Price Mechanics
Subscription-based capacity reservations lock in multi-year platform access for United States logistics operators while anchoring price predictability against volatile cloud infrastructure costs. German automotive OEMs negotiate algorithmic-audit clauses into telematics contracts, embedding EU AI Act compliance premiums into lifetime value calculations.
Pricing Analysis
After-sales service tiers and extended algorithmic-audit contracts drive lifetime value differentiation in enterprise geofencing deployments. Three-tier pricing structure across premium certified platforms, standard cloud-native subscriptions, and economy beacon-hardware bundles segments buyer archetypes. Pricing pressure stems from Wi-Fi fingerprinting substitution in cost-sensitive Indian retail implementations. Municipal buyers in smart-city tenders exhibit highest price sensitivity, while German automotive OEMs absorb compliance premiums for documented denial-logic systems.
Supply Chain Analysis
Inbound logistics costs through Taiwan Strait shipping lanes and South Korean port congestion expose hardware vendors to container-availability volatility. GPS and Bluetooth chipset fabrication concentrates in Taiwan, South Korea, and China, drawing from silicon wafers, rare-earth substrates, and precision radio-frequency components. Single-source vulnerability in Taiwan semiconductor foundries threatens beacon-array deployment timelines. Distribution runs through hyperscaler cloud marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The active geofencing market rewards scarce embedded-systems firmware expertise and jurisdictional data-architecture capabilities that bridge cloud scalability with sovereignty compliance. Engineering talent capable of optimizing power-consumption algorithms for battery-operated beacon deployments at scale remains the critical constraint on platform expansion.
For Market Incumbents: Consolidate algorithmic-audit capabilities and EU AI Act certification infrastructure to defend enterprise contract renewals against cloud-native entrants. Acquire precision-hardware specialists in Asia-Pacific markets to anchor beacon-density deployments for transit authority tenders. Channel control through hyperscaler marketplace listings protects against direct API commoditization. For New Entrants and Emerging Players: Lead with ultra-wideband convergence for warehouse robotics integration in Japan's automotive supply chain corridor. Target India's cost-sensitive municipal smart-city segment with Wi-Fi fingerprinting alternatives to dedicated beacon hardware. Go-to-market through systems integrators already embedded in traffic management and emergency response coordination tenders. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid-cloud vendors possessing both mapping infrastructure and jurisdictional data-pipeline architecture. Long-term viability hinges on recurring revenue share models displacing perpetual-license sales in enterprise fleet management. Watch for EU AI Act conformity-assessment bottlenecks as inflection indicator for certified-platform pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Google LLC leverages Android device penetration to embed geofencing SDKs into consumer loyalty applications. |
| Acquisition of Specialist Firm | IBM Corporation absorbs middleware developers bridging modern API platforms with legacy SCADA control systems. |
| Strategic Partnership | Bluedot Innovation Pty Ltd allies with transit authorities in Japan for high-precision beacon array deployments. |
| Geographic Expansion | Cloud-native vendors establish data-residency zones in Germany to satisfy GDPR Article 44 localization mandates. |
| Product Launch | Ultra-wideband chipsets miniaturize into sub-millimeter packages for smartphone OEM spatial-awareness hardware. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet telematics directors, retail loyalty platform engineers, municipal smart-city procurement officers, and embedded-systems firmware architects. Secondary validation drew from FCC carrier-grade location accuracy mandates, EU AI Act conformity assessment frameworks, MIIT data-localization regulations, and hyperscaler cloud infrastructure capex disclosures. Bottom-up deployment volume estimates triangulated against top-down platform revenue aggregation.
Across the analysis window, forecasts modeled technology segmentation by accuracy threshold and power consumption, application segmentation by compliance intensity and integration complexity, and deployment segmentation by data-sovereignty architecture. CAGRs derived from logistic diffusion curves for beacon density saturation and linear extrapolation of fleet telematics mandate adoption. Key inputs included electric vehicle charge-point access control deployment timelines and GDPR consent-management platform penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor foundry capacity expansion or abrupt regulatory fragmentation in cross-border data flows would require recalibration. Forecasts reflect assumptions on Bluetooth beacon cost curves and cloud infrastructure pricing elasticity. Recalibration cycles align with material shifts in EU AI Act enforcement intensity and MIIT data-localization rule amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Canada Data Center Physical Security Market
Physical Security
North America Physical Security Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Physical Security Equipment Market
Physical Security
Global Wearable Security Device Market
Physical Security
Airport Full Body Scanner Market
Physical Security
Policing Technologies Market
Physical Security
Body Armor Market
Physical Security
Tactical Lights Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Body Armor Plates Market
Physical Security
Tactical Vests Market
Physical Security
Physical Security Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Europe Physical Security Market
Physical Security
Hong Kong Data Center Physical Security Market