
 Bulletproof Glass Market | 2026-2036
Bulletproof Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Bulletproof Glass Market Analysis
EU Green Deal building retrofit mandates is consolidating demand toward energy-efficient security glazing across European commercial real estate. Saint-Gobain S.A. leverages its integrated flat glass and coatings portfolio to supply certified ballistic solutions with thermal performance. SCHOTT AG anchors its position through advanced borosilicate and laminated glass-ceramic expertise for extreme-threat applications. PPG Industries, Inc. competes on optical clarity coatings that reduce weight without sacrificing NIJ protection levels.
Bulletproof glass consists of multiple layers of glass, polycarbonate, or acrylic bonded with polyvinyl butyral (PVB) or polyurethane interlayers, engineered to absorb kinetic energy from ballistic impacts while maintaining optical transmission above 80%. Its primary purpose is to protect occupants and assets in high-threat environments including embassies, financial institutions, military vehicles, and critical infrastructure. Laminated products dominate volume due to established supply chains and multi-threat certification acceptance, while polycarbonate segments capture margin pools in automotive and mobile security where weight reduction directly impacts fuel efficiency. Security glazing specifications across government and transportation end users are tightening, pushing demand toward 20mm and 30mm thickness categories that satisfy combined ballistic and blast requirements.
The EU Construction Products Regulation and CE marking requirements enforce consistent performance testing for ballistic-resistant glazing installed in public buildings across member states. In the United States, NHTSA and Department of State security standards shape automotive and diplomatic facility specifications respectively. The National Institute of Justice (NIJ) ballistics threat level classifications provide the baseline testing protocol that most international buyers reference for procurement. Stakeholders must monitor how evolving energy-efficiency codes in Europe and North America will force reformulation of traditional glass-polymer stacks to meet combined thermal and ballistic performance thresholds.
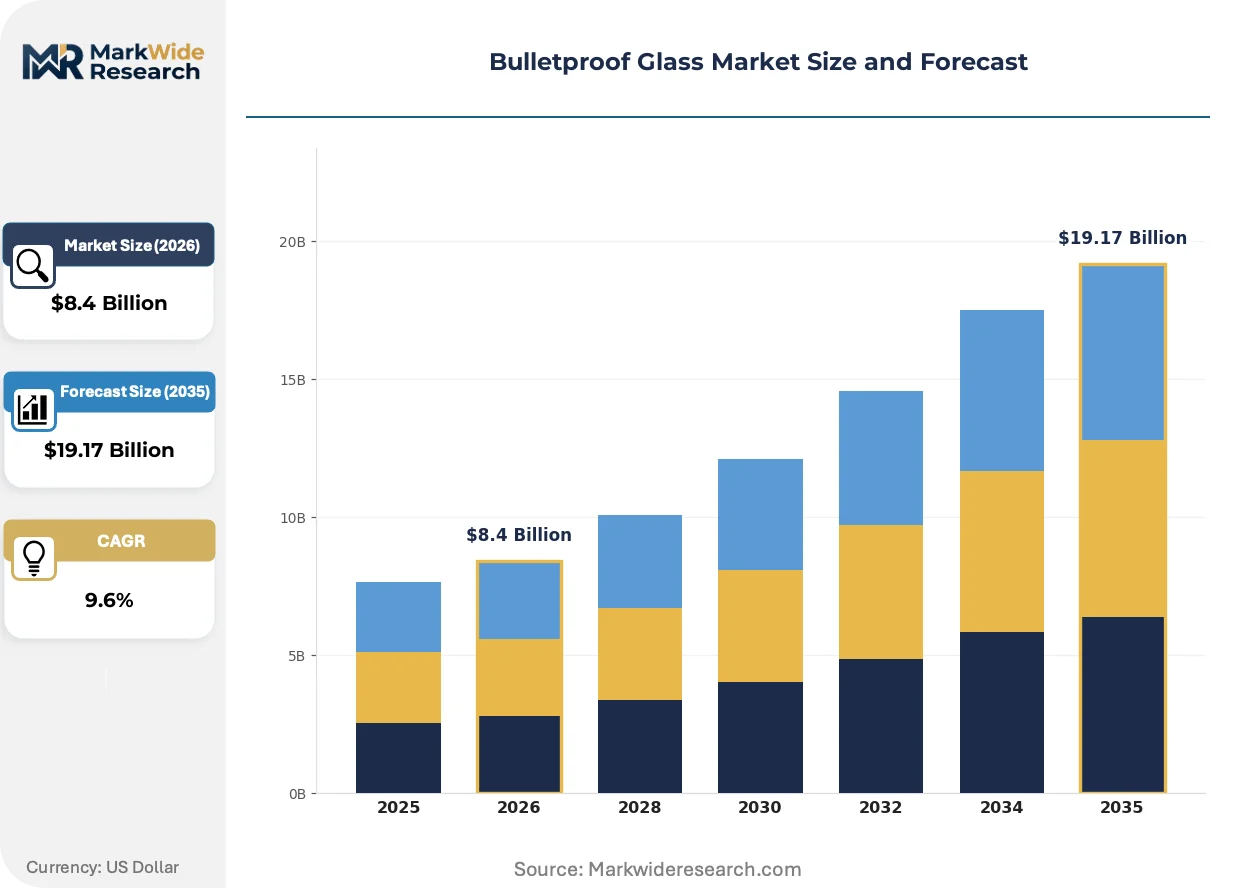
Market Dynamics
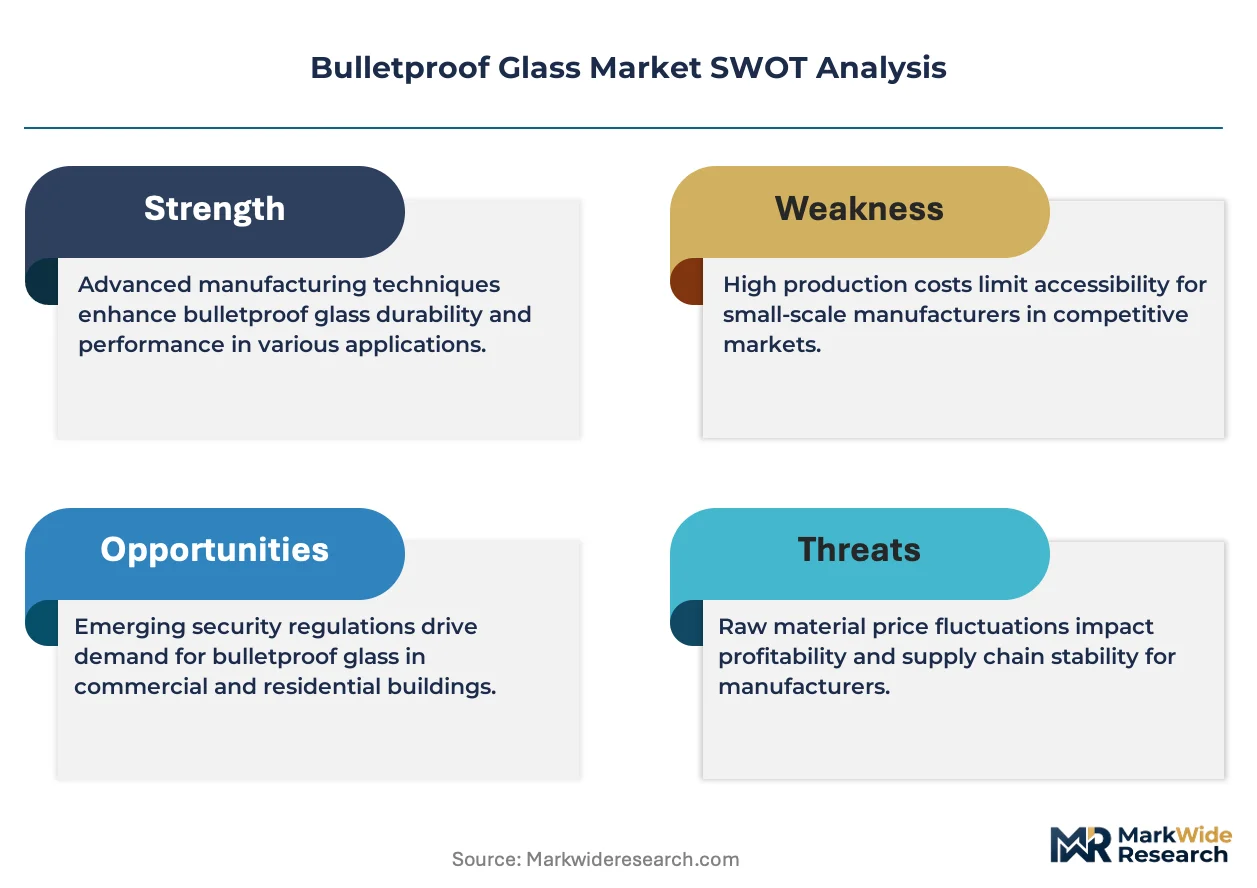
The bulletproof glass market faces structural pressure from EU Green Deal retrofit mandates that compel manufacturers to reformulate traditional glass-polymer laminates for combined ballistic and thermal performance. This dual-certification requirement is compressing margins for legacy producers while rewarding integrated suppliers with coatings and glazing expertise.
Growth Catalysts
- Public Infrastructure Retrofit Mandates:Germany's security upgrade requirements for government buildings and transit systems are accelerating specification upgrades toward 20mm and 30mm thickness categories that satisfy combined ballistic and blast ratings.
- NIJ Standardization:The National Institute of Justice ballistics threat level classifications provide procurement baselines that international buyers reference, streamlining cross-border tender processes and reducing certification duplication costs.
- Automotive Lightweighting:Polycarbonate interlayer formulations are capturing specification share in armored vehicle segments where weight reduction directly impacts fuel efficiency and payload capacity.
Market Restraints
- Raw Material Concentration:Polyvinyl butyral (PVB) interlayer supply concentrates among a limited cohort of chemical producers, creating input cost volatility and qualification bottlenecks for secondary glass laminators.
- Energy-Code Friction:Traditional glass-polymer stacks face reformulation costs to meet tightening thermal transmittance requirements under EU Construction Products Regulation and member state building codes.
- Transparent Armor Substitution:Advanced ceramics and transparent aluminum oxynitride composites threaten premium segments in military aerospace applications where weight thresholds are most severe.
Strategic Opportunities
- Underpenetrated Critical Infrastructure:Data centers and energy substations in the United States lack standardized ballistic glazing protocols, creating first-mover advantage for suppliers offering integrated cyber-physical security solutions.
- CE Marking Expansion:The EU Construction Products Regulation enforcement across Eastern European member states is opening specification opportunities in public building retrofits previously served by uncertified regional suppliers.
- Smart Glazing Convergence:Integration of electrochromic and ballistic-resistant layers addresses demand from embassy and diplomatic facilities requiring both threat protection and dynamic optical control.
Industry Challenges
- Multi-Threat Certification Timelines:Combined ballistic, blast, and forced-entry testing protocols extend product validation cycles, delaying revenue recognition for new laminate formulations.
- Specialized Lamination Talent Scarcity:Autoclave operation and optical-grade bonding expertise concentrates among aging workforces in Germany and the United States, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulletproof Glass Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Laminated, Acrylic, Security Glazing Application: Automotive, Military, Commercial Buildings, Residential Buildings Thickness: 6mm, 12mm, 20mm, 30mm End User: Government, Private Security, Transportation, Retail |
| Companies Covered | AGC Inc., Saint-Gobain S.A., Nippon Sheet Glass Co., Ltd., SCHOTT AG, PPG Industries, Inc., Guardian Industries Corp., Consolidated Glass Holdings, Inc., Total Security Solutions, Apogee Enterprises, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulletproof Glass Market Emerging Trajectories
Reformulation of glass-polymer stacks for energy-code compliance is compressing product development cycles and forcing collaboration between coatings specialists and ballistic certifiers. This convergence is reshaping competitive capabilities across the supply base.
Glass-ceramic laminates with borosilicate cores are consolidating specification share in extreme-threat applications where optical clarity must persist after multiple impacts. Embassies and diplomatic facilities in high-risk postings are adopting these formulations despite 40-60% cost premiums over conventional laminated glass. The technology is consolidating demand around suppliers with captive fusion-casting capabilities and in-house ballistic testing ranges.
EU Green Deal building retrofit mandates are tightening thermal transmittance requirements for security glazing installed in public buildings across member states. The regulation is forcing reformulation of traditional PVB interlayers toward thermally efficient polyurethane alternatives that maintain NIJ protection levels. German and French specification authorities are leading enforcement, with compliance deadlines compressing procurement timelines for municipal infrastructure projects.
Buyer concentration among government procurement agencies is consolidating contract awards toward suppliers offering lifecycle service agreements rather than standalone product sales. Facility managers in banking and critical infrastructure segments are unbundling installation, maintenance, and replacement scheduling into multi-year performance contracts. This shift is most visible in the United States, where Department of State and General Services Administration tender formats increasingly mandate service-level commitments.
Bulletproof Glass Market Segmentation
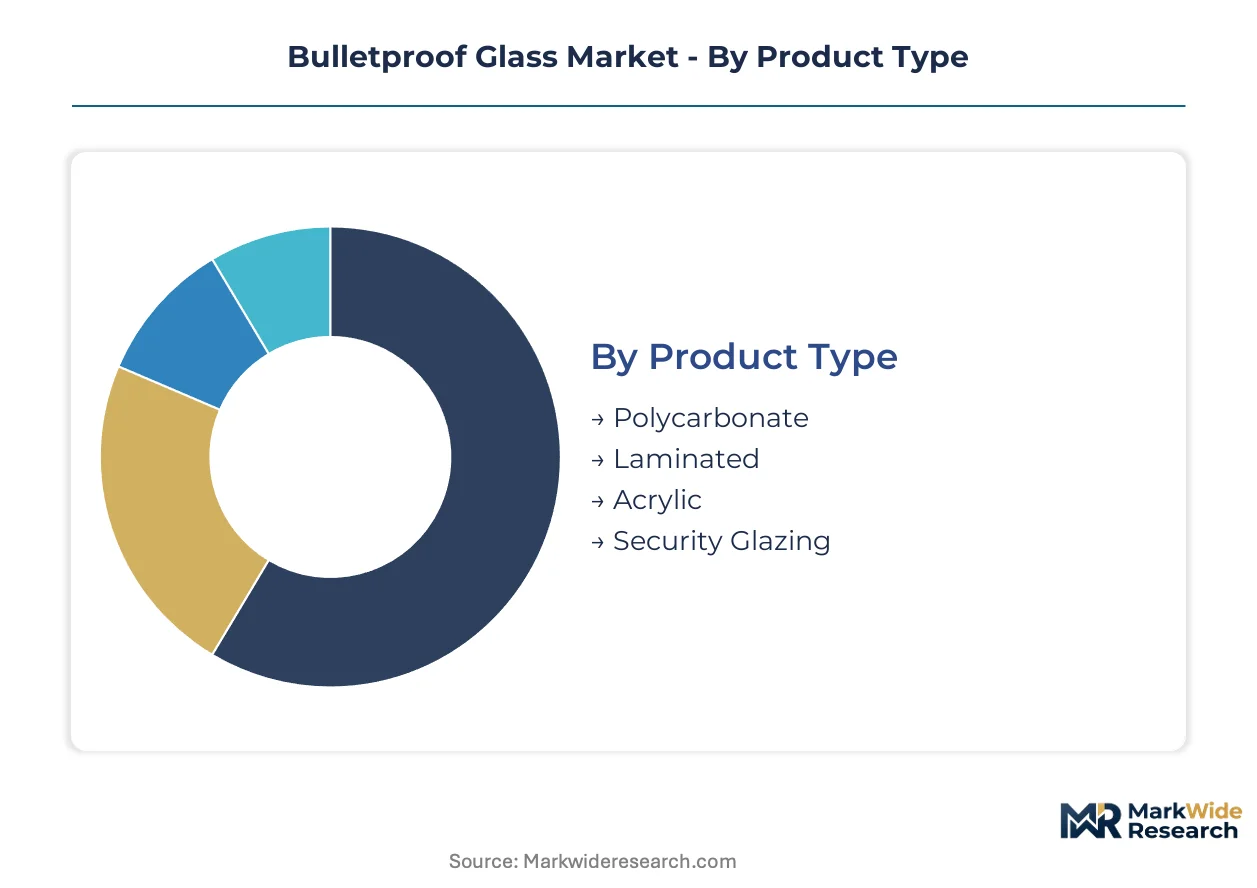
Segmentation in bulletproof glass reveals how specification requirements diverge across threat environments, installation constraints, and procurement authority structures. Buyers optimize across ballistic rating, weight tolerance, optical clarity, and thermal performance rather than selecting on cost alone.
Product Type:
Material selection hinges on the kinetic energy absorption mechanism and multi-hit durability requirements of the intended threat environment.
- Laminated:Multiple glass layers bonded with PVB or polyurethane interlayers absorb impact energy through controlled delamination while maintaining optical transmission above 80%. Banking and embassy specifications in Germany and France favor these formulations for combined ballistic and blast certification under EU Construction Products Regulation mandates.
- Polycarbonate:Solid thermoplastic sheets deliver equivalent NIJ protection at 60-70% of glass weight, capturing specification share in armored vehicle programs where fuel efficiency penalties drive material selection. NHTSA automotive safety standards shape thickness and optical clarity requirements for VIP transport fleets.
- Acrylic:Lighter than glass but susceptible to crazing and solvent damage, limiting deployment to interior partitions and retail fixtures where projectile threats are lower-velocity. Private security contractors in commercial real estate specify these for cost-sensitive perimeter hardening.
- Security Glazing:Composite stacks integrating glass, polycarbonate, and ceramic layers address extreme-threat postings for diplomatic facilities and military command centers. Department of State security standards mandate these formulations for high-risk embassy locations.
Mature deployment sits with Laminated. Newer deployment is concentrated in Polycarbonate.
Application:
End-use environments dictate the acceptable trade-off between protection level, weight, installation complexity, and lifecycle maintenance.
- Automotive:Curved windshield and side window specifications require optical-grade laminates that maintain clarity across temperature cycling and vibration loads. Armored vehicle OEMs in Germany and the United States specify 20mm-30mm polycarbonate-glass hybrids to satisfy NIJ Level IIIA while minimizing payload impact.
- Military:Transparent armor for tactical vehicles and forward operating bases demands multi-hit survivability against rifle threats. Glass-ceramic laminates with borosilicate cores consolidate specification share despite cost premiums, driven by Department of Defense procurement protocols.
- Commercial Buildings:Banking halls, data centers, and government facilities drive volume for 12mm-20mm laminated products. EU Green Deal retrofit mandates in Germany are accelerating replacement of legacy glazing with thermally efficient security alternatives.
- Residential Buildings:High-net-worth individual demand concentrates in urban centers with elevated violent crime rates. Private security consultants specify 6mm-12mm solutions balancing discrete aesthetics with handgun-level protection.
Volume concentrates in Commercial Buildings. Margin expansion is steepest in Military.
Thickness:
Thickness selection maps directly to NIJ threat level certification and the kinetic energy of anticipated projectile impacts.
- 30mm:Rifle-rated protection for military vehicles and critical infrastructure command centers. These specifications require extended autoclave cycles and specialized optical bonding expertise concentrated among German and United States laminators.
- 20mm:Combined ballistic and blast ratings for embassy perimeters and government buildings. German public infrastructure retrofit mandates are accelerating specification of this category for municipal facilities.
- 12mm:Handgun protection for banking, retail, and private security applications. Standardization around this thickness reduces procurement complexity for facility managers across European commercial real estate.
- 6mm:Minimal protection against low-velocity threats for interior partitions and residential applications. Cost-sensitive segments favor these specifications where regulatory mandates do not prescribe higher ratings.
Certification density is highest at 20mm. Specification growth is climbing the fastest at 30mm.
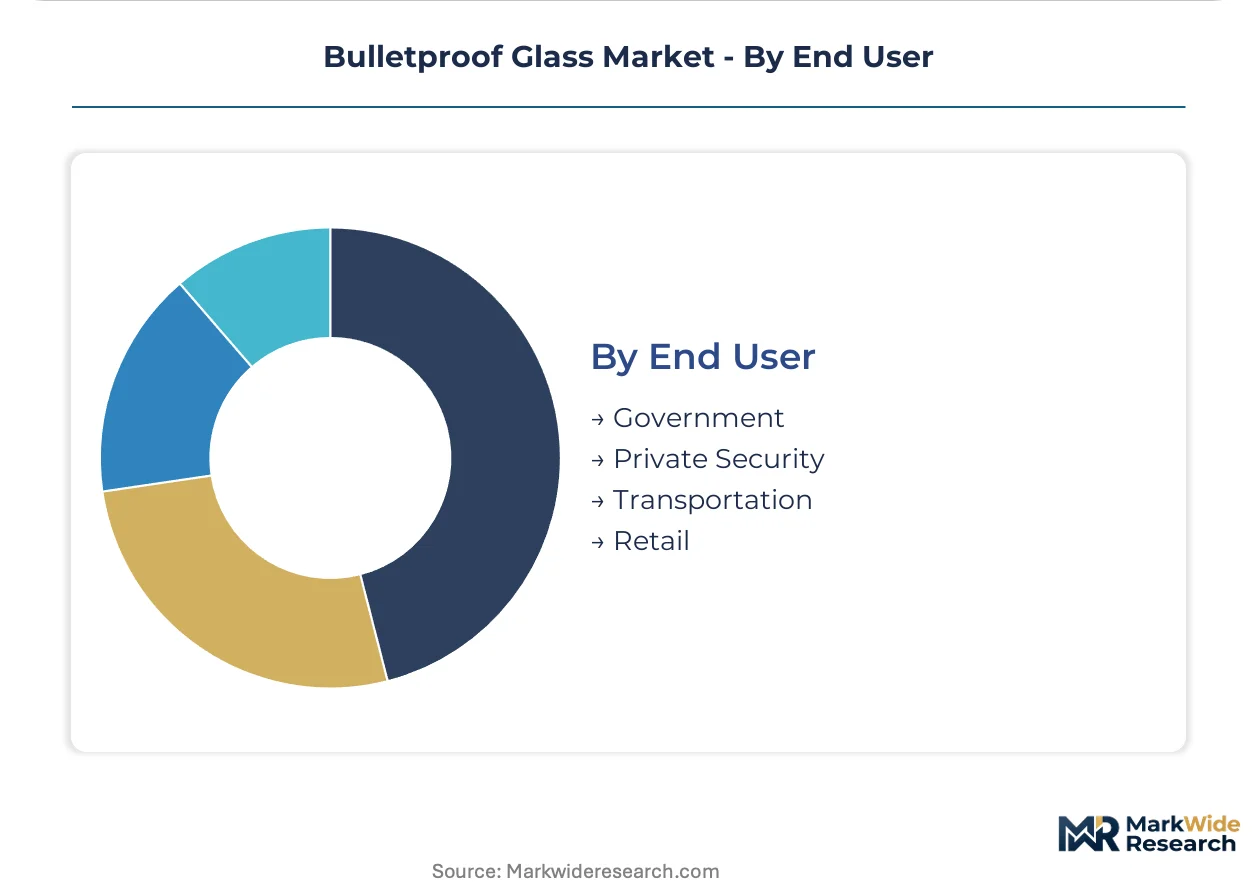
End User:
Procurement authority structures determine contract format, lifecycle service expectations, and compliance documentation requirements.
- Government:Embassy, military, and public building specifications mandate NIJ-certified products with CE marking or equivalent compliance documentation. General Services Administration and Department of State tender formats increasingly require multi-year service agreements encompassing installation, inspection, and replacement scheduling.
- Transportation:Rail, airport, and mass transit authorities specify 12mm-20mm solutions for control rooms and passenger screening areas. German transit system security upgrade mandates are driving specification upgrades in this segment.
- Private Security:Corporate headquarters and executive protection programs favor discreet 6mm-12mm installations with rapid deployment timelines. These buyers prioritize supplier responsiveness over lowest-unit-cost procurement.
- Retail:Jewelry stores, currency exchanges, and high-value merchandise outlets specify 12mm laminated products for counter and display case protection. Insurance underwriters increasingly mandate certified glazing as a condition of coverage.
Contract value concentrates with Government. Procurement velocity is expanding most quickly in Transportation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European bulletproof glass specification activity through its dense concentration of automotive OEMs and specialized laminators serving both vehicle armor and architectural security segments.
United States
Department of State embassy security upgrades and General Services Administration facility retrofits drive specification volume. NHTSA automotive safety standards shape armored vehicle glazing requirements for VIP transport fleets. Michigan and Ohio host the primary laminator clusters serving Detroit's armored vehicle modification industry.
Germany
Public infrastructure retrofit mandates for government buildings and transit systems accelerate demand for combined ballistic and blast-rated glazing. EU Green Deal thermal performance requirements force reformulation of traditional PVB interlayers toward polyurethane alternatives. Bavaria's glass-ceramic specialists concentrate around Mainz and Jena for extreme-threat diplomatic applications.
France
Banking hall security upgrades and luxury retail perimeter hardening sustain demand for 12mm-20mm laminated solutions. CE marking enforcement under EU Construction Products Regulation streamlines cross-border procurement for multinational facility operators. The Île-de-France corridor hosts specification consultants influencing embassy and corporate headquarters projects across Africa and the Middle East.
China
Domestic financial institution branch expansion and high-speed rail security investments drive volume procurement of 20mm thickness categories. GB standards for architectural safety glass create certification pathways for local laminators seeking export qualification. The Yangtze River Delta concentration of flat glass producers enables integrated supply chains for polycarbonate-glass hybrid formulations.
United Arab Emirates
Diplomatic facility construction and sovereign wealth fund real estate developments specify premium security glazing for landmark commercial towers. MOHAP building safety codes incorporate ballistic resistance requirements for critical infrastructure. Dubai's free zone clustering attracts European and Asian laminators establishing regional distribution hubs.
Bulletproof Glass Market Vendor Landscape
The competitive structure tilts toward integrated glass-coating conglomerates with captive raw material supply and in-house ballistic certification capabilities. Three archetypes dominate: flat glass majors with security divisions, specialized laminators focused on architectural and automotive armor, and regional fabricators serving government procurement channels. Consolidation pressure intensifies as energy-code compliance costs squeeze standalone laminators lacking thermal coating expertise. Strategic moves concentrate on backward integration into interlayer chemistry and geographic expansion through specification consulting relationships.
Among integrated material-science conglomerates, Saint-Gobain S.A. and SCHOTT AG exemplify the premium-tier archetype through their fusion-casting and glass-ceramic capabilities. PPG Industries, Inc. occupies a distinct position on optical clarity and coating technology. Regional specialists including Total Security Solutions and Consolidated Glass Holdings, Inc. represent the project-execution tier, competing on installation velocity and lifecycle service agreements rather than captive material production.
| Leading Market Players |
|---|
| AGC Inc. |
| Saint-Gobain S.A. |
| Nippon Sheet Glass Co., Ltd. |
| SCHOTT AG |
| PPG Industries, Inc. |
| Guardian Industries Corp. |
| Consolidated Glass Holdings, Inc. |
| Total Security Solutions |
| Apogee Enterprises, Inc. |
| Others |
Supply Flow & Price Mechanics
Autoclave operators and optical-grade bonding specialists concentrated in Germany and the United States command wage premiums that propagate across three distinct pricing tiers. Labor-cost differentials between these specialized laminator clusters and emerging Eastern European facilities widen spreads between premium certified products and economy-grade alternatives.
Pricing Analysis
NIJ certification level anchors value-based pricing, with combined ballistic-blast ratings commanding substantial premiums over single-threat certifications. Three-tier pricing structure across premium, standard, and economy levels separates glass-ceramic embassy specifications from commercial laminated products and acrylic interior partitions. Cost compression in standard-tier laminated glass is intensifying because EU Green Deal thermal reformulation mandates force interlayer substitution. Retail banking and private security contractors exhibit highest price sensitivity, while Department of State procurement shows lowest elasticity due to mission-critical requirements.
Supply Chain Analysis
Refurbishment flows for decommissioned embassy and military glazing create secondary material streams that compete with virgin polycarbonate and glass inputs. Raw material supply concentrates in Germany, the United States, and China, with borosilicate glass-ceramic fusion-casting capabilities limited to German and United States specialists. Polyvinyl butyral interlayer production rests on chemical producers in Belgium, Japan, and the United States, creating single-source vulnerability for secondary laminators. Distribution runs through specification consultants and certified installers rather than commodity distributors, with project-based procurement dominating government and critical infrastructure segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bulletproof glass market is becoming a vertical-integration race as energy-code compliance costs squeeze standalone laminators. Players are pursuing backward integration into polyurethane interlayer chemistry to capture margin pools and secure supply continuity.
For Market Incumbents: Deploy captive fusion-casting capabilities to defend specification share in extreme-threat embassy and military segments against transparent aluminum oxynitride substitution. Expand lifecycle service agreements beyond product sales to lock in multi-year Department of State and General Services Administration contracts. Acquire specialized autoclave operators in Germany and the United States to constrain competitor capacity expansion.
For New Entrants and Emerging Players: The 40-60% price gap between glass-ceramic premium formulations and standard laminated products creates entry space for polycarbonate-glass hybrid specialists. Target data center and energy substation segments in the United States where standardized ballistic glazing protocols remain undeveloped. Pursue rapid-installation service models that prioritize responsiveness over lowest-unit-cost procurement to differentiate from incumbent project timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated coating-glazing conglomerates given EU Green Deal enforcement accelerating thermal-ballistic dual certification requirements. Long-term viability favors suppliers with in-house ballistic testing ranges and CE marking authority. Monitor CE marking expansion progress across Eastern European member states as inflection indicator for specification upgrade velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Interlayer Chemistry | Captures margin pools from chemical producers while securing supply continuity for EU thermal compliance mandates. |
| CE Marking Expansion into Eastern Europe | Opens specification opportunities in public building retrofits previously served by uncertified regional suppliers. |
| Lifecycle Service Agreement Standardization | Aligns contract formats with Department of State and General Services Administration tender requirements. |
| Glass-Ceramic Fusion-Casting Capacity Addition | Consolidates demand in extreme-threat embassy segments where optical clarity must persist after multiple impacts. |
| Smart Glazing Convergence Development | Addresses embassy demand for electrochromic-ballistic integration requiring dynamic optical control. |
Methodological Framework
Independent corroboration across laminator operations executives, government procurement officers, and specification consultants underwrites the qualitative findings. Primary interviews with autoclave operators, ballistic testing laboratory directors, and facility managers at banking and critical infrastructure sites combined with secondary validation from NIJ certification databases, EU Construction Products Regulation filings, and SEC disclosures from integrated glass-coating conglomerates. Bottom-up demand modeling across thickness categories and top-down supply verification through customs and trade data completed the triangulation.
Comparable-period anchoring to historical NIJ adoption curves and EU regulatory enforcement timelines shaped the projection horizon. Segmentation dimensions modeled include product type, application environment, thickness certification tier, and end-user procurement authority structure. CAGRs were derived from installation volume trajectories and specification upgrade cycles. Industry-specific inputs encompassed German public infrastructure retrofit mandate compliance rates and Department of State embassy security upgrade program pacing.
Inputs from laminator operations data and government procurement disclosures were available through the study window; gaps in real-time polycarbonate spot pricing and Eastern European CE marking enforcement timing introduce uncertainty bands. Forecasts reflect documented assumptions regarding EU Green Deal thermal transmittance deadline adherence and NIJ standardization adoption velocity. Practitioners should monitor transparent ceramic substitution rates in military aerospace and CE marking audit pass rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Border Security Technologies Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Canada Data Center Physical Security Market
Physical Security
Active Geofencing Market
Physical Security
Physical Security Equipment Market
Physical Security
Physical Security Services Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
North America Physical Security Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Smart Police Helmet Market
Physical Security
Tactical Lights Market
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Body Armor Market
Physical Security
Airport Full Body Scanner Market