
 AI in Video Surveillance Market | 2026-2036
AI in Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Video Surveillance Market Insights
Aftermarket service revenue is reconfiguring margin pools away from hardware sales toward software subscriptions and managed analytics. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its manufacturing scale to dominate camera production while bundling AI analytics licenses. Axis Communications AB anchors its position through open-platform architecture that integrates third-party deep learning modules. Dahua Technology Co., Ltd. extends its reach via edge-computing devices that process video locally, reducing bandwidth costs for enterprise buyers.
AI in video surveillance encompasses camera networks, video management software, and neural network algorithms that perform real-time object detection, behavioral analysis, and identity verification at frame rates exceeding 30 fps for 4K resolution streams. The primary commercial purpose centers on automated threat detection, forensic search acceleration, and operational intelligence extraction from continuous video feeds. Deep learning deployments in transport applications command premium pricing due to the computational intensity of license plate recognition and traffic flow optimization. Edge computing architectures are displacing pure cloud pipelines in retail and industrial settings where sub-100-millisecond latency proves essential for theft prevention and safety compliance.
The EU AI Act imposes conformity assessments on biometric identification systems, while the FDA oversees AI diagnostic integrations in healthcare surveillance workflows and China's SAMR enforces algorithmic transparency rules for public security procurement. These frameworks fragment product roadmaps, forcing vendors to maintain jurisdiction-specific firmware branches and audit documentation. Stakeholders must monitor whether emerging national AI sovereignty laws will mandate domestic data residency for video analytics processing.
Market Dynamics
Edge computing architectures are fragmenting procurement patterns as buyers prioritize sub-100-millisecond latency over cloud-native video analytics, forcing vendors to reconfigure hardware-software bundling strategies and service delivery models.
Growth Catalysts
- EU AI Act conformity requirements:Biometric identification systems face mandatory risk classification assessments, creating certified product demand from government and critical infrastructure buyers seeking compliance-ready solutions.
- Smart city infrastructure deployment:Southeast Asian urban development programs are procuring facial recognition-enabled camera networks for traffic management and public safety applications.
- Neural network algorithm advancement:Real-time object detection capabilities at 4K resolution and 30+ fps are expanding addressable use cases beyond security into operational intelligence and process optimization.
Market Restraints
- GPU and AI accelerator supply concentration:Taiwan Semiconductor Manufacturing Company and NVIDIA dominate specialized chip fabrication, exposing video analytics hardware vendors to allocation bottlenecks and 26-40 week lead times.
- Jurisdiction-specific firmware fragmentation:The EU AI Act, China's SAMR algorithmic transparency rules, and FDA healthcare surveillance oversight force parallel product development tracks that inflate R&D overhead.
- Bandwidth cost sensitivity in enterprise deployments:Continuous 4K video streaming to cloud analytics platforms generates prohibitive data transmission expenses for multi-site retail and industrial operators.
Strategic Opportunities
- India urban police modernization:State-level public safety departments are deploying AI-powered crowd analytics for festival management and emergency response, creating localized procurement windows.
- Healthcare surveillance-diagnostic convergence:FDA-regulated AI diagnostic integrations in hospital workflows enable patient monitoring and fall detection applications with reimbursement pathway potential.
- Edge-to-cloud hybrid orchestration:Containerized analytics modules running on NVIDIA Jetson and Qualcomm Vision platforms allow workload portability across deployment architectures.
Industry Challenges
- Computer vision engineering talent scarcity:Deep learning model optimization for resource-constrained edge devices requires specialized firmware and quantization expertise that commands premium compensation.
- Multi-jurisdiction audit documentation burden:EU AI Act conformity assessments, SAMR algorithmic filings, and FDA quality system requirements demand dedicated regulatory affairs capacity.
- Legacy analog infrastructure integration:Hybrid environments combining IP and coaxial camera networks complicate unified analytics deployment and degrade inference accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Video Surveillance Market |
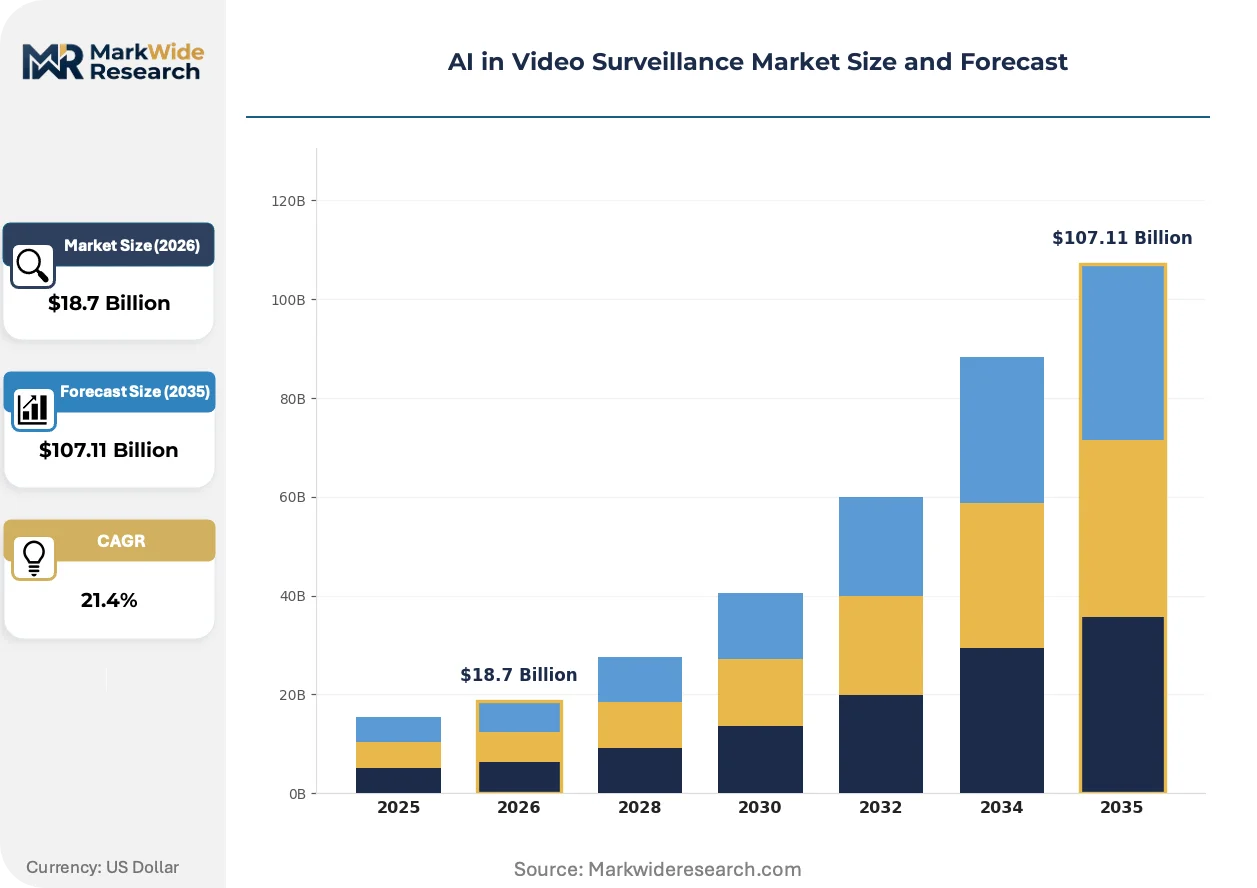
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Retail, Transport, Government, Healthcare Technology: Deep Learning, Machine Learning, Computer Vision, Analytics End User: Commercial, Residential, Industrial, Public Sector Deployment: Cloud, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Avigilon Corporation, Milestone Systems A/S, Motorola Solutions, Inc., SenseTime, Axis Communications AB, Genetec Inc., NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Video Surveillance Market Trends and Innovations
Video analytics delivery models are bifurcating between centralized cloud inference and distributed edge processing, with latency requirements and data sovereignty concerns driving architectural decisions across end-use verticals.
Software-defined video analytics is virtualizing the traditional hardware-software boundary in surveillance infrastructure. Enterprise buyers in retail loss prevention and industrial safety compliance are deploying containerized inference engines on commodity edge servers rather than proprietary NVR appliances. This shift is virtualizing vendor lock-in mechanisms and compressing switching costs between analytics providers.
The EU AI Act's risk-based classification framework for biometric identification systems imposes conformity assessment obligations on deployers of real-time remote identification technology. High-risk system providers must maintain technical documentation, human oversight protocols, and accuracy testing records subject to market surveillance authority audit. Public sector procurement across Germany, France, and Italy now requires CE marking with notified body involvement, extending sales cycles by 4-8 months.
Subscription-based managed analytics services are displacing perpetual license models in mid-market commercial deployments. System integrators and MSSPs are capturing recurring revenue streams by offering per-camera monthly pricing that bundles hardware, software, and remote monitoring. This transition is most advanced in US multi-site retail and UK logistics warehousing, where CFO preference for operational expenditure classification accelerates vendor financing program adoption.
AI in Video Surveillance Market Segmentation
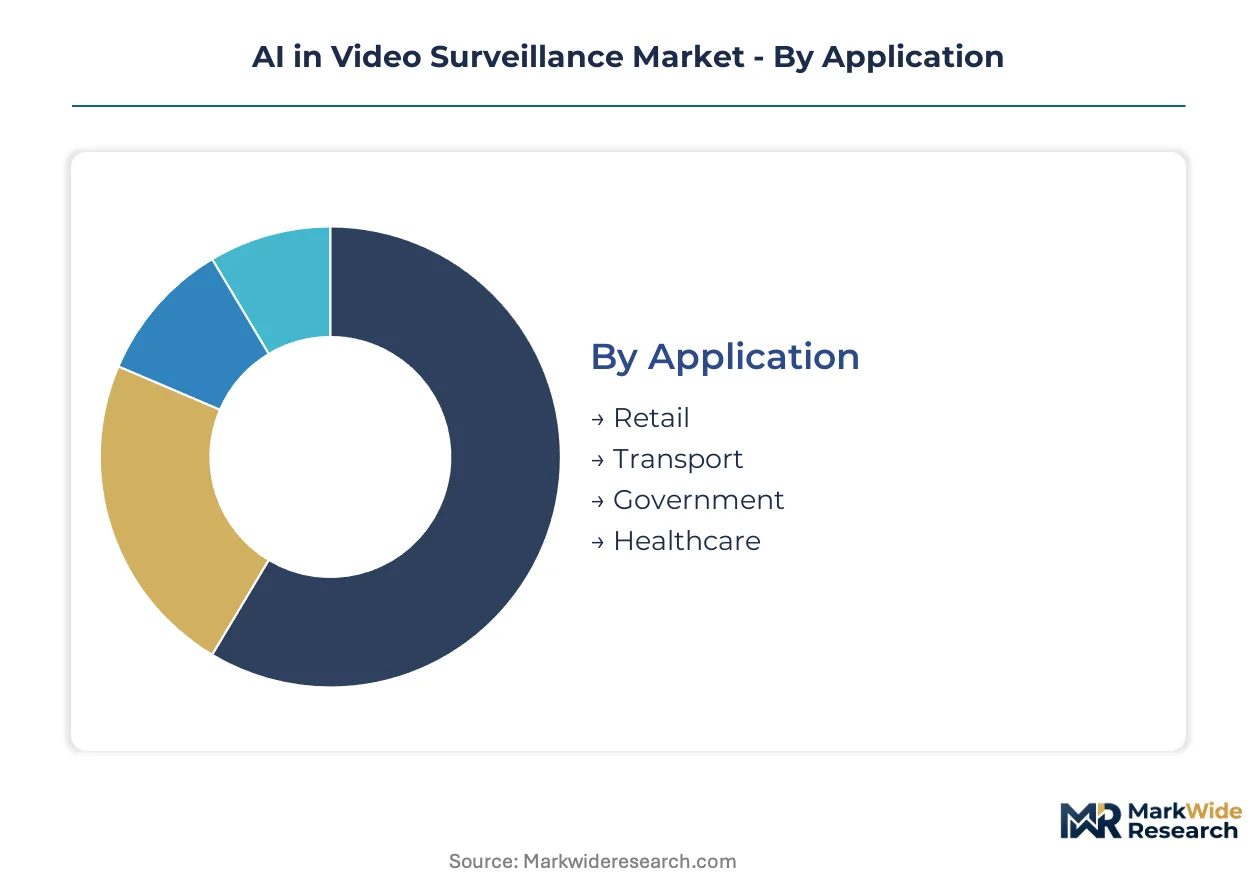
Segmentation in AI video surveillance reveals how deployment constraints, regulatory exposure, and computational requirements reshape vendor go-to-market strategies across divergent buyer profiles. Each dimension captures distinct procurement patterns that determine pricing architecture and partnership requirements.
Application:
Mature security applications now compete with emerging operational intelligence use cases for R&D investment allocation.
- Retail:Loss prevention algorithms process 4K streams at 30+ fps to detect shelf sweep patterns and organized retail crime coordination. Demand concentrates in US multi-site grocery and apparel chains where shrinkage reduction justifies per-camera subscription pricing.
- Transport:License plate recognition and traffic flow optimization command premium hardware specifications due to computational intensity of vehicle trajectory analysis. European smart city procurement under EU AI Act conformity requirements favors certified biometric systems for intersection monitoring.
- Government:Facial recognition networks for public safety deployment face heightened algorithmic transparency mandates under China's SAMR and India's state-level police modernization programs.
- Healthcare:Patient fall detection and diagnostic workflow integration fall under FDA oversight, creating reimbursement pathway potential for hospital surveillance-diagnostic convergence.
Transport retains volume leadership; Healthcare holds the steepest expansion curve.
Technology:
Cost tier stratification separates resource-intensive neural network training from lightweight inference deployment at the edge.
- Deep Learning:Convolutional neural networks enable real-time object detection with accuracy thresholds exceeding 95% for threat classification in critical infrastructure. Demand concentrates in Southeast Asian smart city projects where facial recognition-enabled camera networks anchor urban development procurement.
- Machine Learning:Traditional statistical models persist in legacy analog-to-IP transition environments where computational constraints limit neural network deployment. Indian urban police departments leverage these systems for festival crowd analytics with lower infrastructure investment requirements.
- Computer Vision:Edge-optimized inference engines from NVIDIA Jetson and Qualcomm Vision platforms enable sub-100-millisecond latency for theft prevention applications.
- Analytics:Containerized software modules virtualize hardware-software boundaries, compressing switching costs between vendors in retail and industrial safety compliance.
Deep Learning dominates revenue concentration; Analytics demonstrates the most rapid adoption velocity among mid-market commercial buyers.
End User:
Customer type determines procurement sophistication, with public sector buyers imposing certification requirements that private operators bypass.
- Commercial:Multi-site retail and logistics warehousing in the US and UK drive subscription-based managed analytics adoption, with CFO preference for operational expenditure classification accelerating vendor financing programs.
- Public Sector:Government and critical infrastructure buyers under EU AI Act jurisdiction require CE marking with notified body involvement, extending sales cycles by 4-8 months for biometric identification systems.
- Industrial:Safety compliance applications in manufacturing command sub-100-millisecond latency specifications that favor edge computing over cloud-native architectures.
- Residential:Consumer-grade deployments prioritize cost compression and DIY installation, limiting addressable margin for advanced analytics features.
Commercial end users generate the highest recurring revenue attachment; Public Sector procurement carries the longest sales cycle duration.
Deployment:
Volume distribution across architecture types reflects bandwidth cost sensitivity and data sovereignty pressures fragmenting vendor product roadmaps.
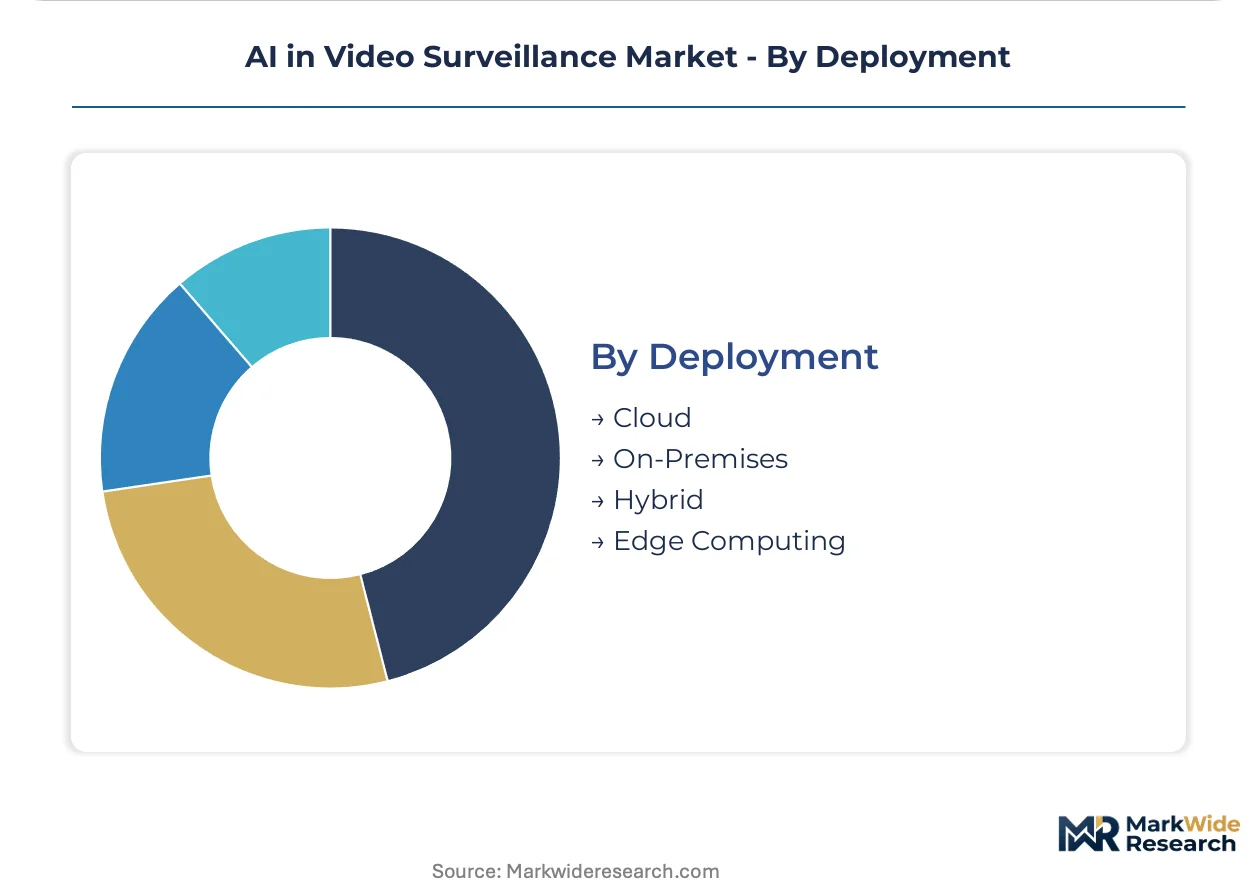
- Edge Computing:Local video processing on dedicated AI accelerators eliminates continuous 4K streaming expenses while achieving sub-100-millisecond inference latency for theft prevention. Enterprise retail and industrial operators prioritize this architecture to circumvent prohibitive data transmission costs.
- Hybrid:Containerized workloads orchestrate between edge inference and cloud training pipelines, enabling workload portability across NVIDIA Jetson and Qualcomm Vision platforms.
- Cloud:Centralized analytics platforms face headwinds from national AI sovereignty laws potentially mandating domestic data residency for video processing.
- On-Premises:Legacy NVR appliances persist in hybrid analog-IP environments where unified analytics deployment degrades inference accuracy.
Edge Computing captures the dominant procurement preference; Hybrid architectures gain share fastest as buyers seek workload flexibility without full cloud dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in India and Southeast Asia exhibit the highest price elasticity, squeezing hardware margins, while EU government procurement absorbs 40-60% premiums for EU AI Act-certified biometric systems without volume degradation.
United States
Multi-site retail chains and logistics warehousing operators drive subscription-based managed analytics adoption. FDA oversight of AI-diagnostic integrations in healthcare surveillance creates compliance-ready procurement pathways for hospital networks. The Greater Boston and Pacific Northwest corridors concentrate venture-backed computer vision startups developing edge-optimized inference engines.
China
SAMR algorithmic transparency rules for public security procurement mandate domestic firmware branches with audit documentation. State-level smart city programs in the Yangtze River Delta and Pearl River Delta deploy facial recognition-enabled camera networks at scale. Hangzhou and Shenzhen anchor manufacturing clusters for AI accelerator hardware and edge computing devices.
Germany
Critical infrastructure operators under EU AI Act jurisdiction require CE marking with notified body involvement, extending sales cycles. Industrial safety compliance applications in manufacturing command sub-100-millisecond latency specifications favoring edge architectures. The Ruhr industrial belt and Bavaria's automotive corridor concentrate demand for theft prevention and process optimization analytics.
India
State-level urban police departments deploy AI-powered crowd analytics for festival management with lower infrastructure investment requirements. BIS certification and state procurement guidelines shape product specifications for public safety deployments. Maharashtra and Karnataka lead municipal smart city tenders integrating video analytics into traffic management systems.
Singapore
Government-led smart nation initiatives procure facial recognition networks for urban development and public safety with premium pricing tolerance. National AI governance frameworks emphasize algorithmic accountability without imposing conformity assessment delays seen in EU jurisdictions. The city-state's logistics and financial services clusters drive demand for operational intelligence extraction from surveillance feeds.
AI in Video Surveillance Market Competitive Landscape
Capability concentration sits with specialized computer vision firms possessing deep learning optimization expertise; scale advantage sits with diversified electronics conglomerates leveraging manufacturing throughput. The vendor base stratifies across three tiers: integrated hardware-software platforms, pure-play analytics software vendors, and component suppliers for edge AI accelerators. Dominant competitive moves include geographic expansion through jurisdiction-specific firmware certification and strategic partnerships with system integrators capturing recurring managed services revenue.
Within the integrated platform tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. represent manufacturing-scale archetypes bundling camera production with analytics licensing, while Axis Communications AB occupies a position exemplifying open-platform architecture that accommodates third-party deep learning modules.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Avigilon Corporation |
| Milestone Systems A/S |
| Motorola Solutions, Inc. |
| SenseTime |
| Axis Communications AB |
| Genetec Inc. |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
Hangzhou and Shenzhen anchor global camera manufacturing capacity, with production scale concentration in these Yangtze and Pearl River Delta clusters translating directly into downstream pricing leverage for integrated hardware-software bundles. Their dominance in edge AI accelerator fabrication and lens assembly creates asymmetric cost structures that compress margins for second-tier assemblers while sustaining premium capture for firmware-differentiated offerings.
Pricing Analysis
Aftermarket service revenue from extended analytics subscriptions and managed detection contracts drives lifetime value capture beyond initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified biometric systems from uncertified commercial deployments and basic motion-detection commodity cameras. Cost compression in the economy tier intensifies because Indian and Southeast Asian municipal buyers squeeze hardware margins through competitive tendering. Commercial multi-site retail operators in the US and UK show lowest price sensitivity, absorbing per-camera monthly subscriptions that bundle remote monitoring and forensic search acceleration.
Supply Chain Analysis
Export-control restrictions on advanced GPU and AI accelerator technologies limit flows of NVIDIA H100 and A100 chips to Chinese surveillance hardware vendors, forcing reliance on domestic SMIC fabrication and legacy process nodes. Component sourcing draws from Taiwan for specialized image sensors, South Korea for memory modules, and Japan for precision optics. Single-source vulnerability concentrates in TSMC's monopoly on advanced node production for neural network inference chips. Distribution runs through authorized system integrators and MSSPs who capture recurring service revenue by embedding analytics licensing into long-term facility management contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory certification entrenchment creates durable switching costs. Vendors who secure notified body involvement for EU AI Act conformity assessments lock out uncertified competitors from public sector procurement channels.
For Market Incumbents: Build certification moats by accelerating EU AI Act CE marking with notified body partnerships and SAMR algorithmic transparency filings in China. Capacity addition in India for BIS-certified local production addresses state-level police modernization tenders. Threat from pure-play analytics software vendors containerizing inference engines demands firmware-level integration investments that degrade switching feasibility. For New Entrants and Emerging Players: Pursue healthcare surveillance-diagnostic convergence as the most penetrable vertical, where FDA oversight creates compliance-ready procurement pathways absent incumbent saturation. Target mid-market US logistics warehousing with subscription-based managed analytics offerings that CFOs classify as operational expenditure. Go-to-market angle: per-camera monthly pricing bundled with remote monitoring and forensic search acceleration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized computer vision firms with deep learning optimization expertise for edge-constrained devices. Long-term viability rests on algorithmic differentiation rather than manufacturing scale. Acquisition target archetype: containerized analytics software vendors with healthcare FDA submission pathways. Signal to watch: EU AI Act conformity assessment backlogs extending sales cycles beyond eight months, indicating certification scarcity premium.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | CE marking with notified body involvement unlocks German, French, and Italian public sector procurement. |
| Edge-to-Cloud Hybrid Orchestration | Containerized workloads on NVIDIA Jetson platforms enable workload portability across retail and industrial deployments. |
| Healthcare-Diagnostic Integration | FDA-regulated AI patient monitoring creates reimbursement pathway potential for hospital network contracts. |
| India Localized Production | BIS certification and state procurement guidelines position vendors for Maharashtra and Karnataka smart city tenders. |
| Subscription Revenue Transition | Per-camera monthly pricing with remote monitoring captures recurring revenue from US multi-site retail CFOs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with video analytics software architects, system integrators deploying facial recognition networks, municipal procurement officers in India and Southeast Asia, and regulatory affairs specialists navigating EU AI Act conformity. Secondary validation drew from FDA 510(k) filings for diagnostic-integrated surveillance, SAMR algorithmic transparency disclosures, EU notified body certification registers, and hyperscaler edge AI capex disclosures. Bottom-up camera shipment modeling and top-down software licensing revenue estimates were triangulated against customs data for AI accelerator imports.
Calibration against historical adoption curves in smart city deployments and retail loss prevention anchored projection parameters across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user procurement sophistication, application computational intensity, and regional regulatory framework. CAGRs were derived from logistic diffusion curves fitted to edge computing adoption patterns and cloud-native analytics displacement rates. Forecast inputs incorporated GPU supply allocation constraints and jurisdiction-specific firmware development overhead.
Macroeconomic conditions sit as an overlay; deviation in municipal infrastructure budgets, semiconductor capital expenditure cycles, or cross-border data sovereignty legislation would shift the trajectory. Forecasts embed assumptions regarding EU AI Act enforcement consistency and SAMR audit documentation requirements. Material shifts in export-control restrictions on AI accelerators or national AI sovereignty mandates mandating domestic data residency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
China Video Surveillance Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Under-Vehicle Surveillance Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Storage Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
Farm Video Surveillance System Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Security Camera Software Market