
 Persistent Threat Detection System (PTDS) Market | 2026-2036
Persistent Threat Detection System (PTDS) Market Size, Share, and Industry Trends Forecast 2026-2036
Persistent Threat Detection System (PTDS) Market Analysis
Cybersecurity-trained military engineering cadres is rotating toward aerostat-integrated persistent surveillance programs, tightening labor availability for ground-based radar maintenance. Northrop Grumman leverages its layered defense heritage to anchor aerostat payload development for integrated air and missile defense networks. Lockheed Martin sustains long-duration stratospheric platform operations through advanced tether and power management systems. Thales competes across European NATO markets with multi-spectral sensor fusion architectures designed for contested electromagnetic environments.
A Persistent Threat Detection System comprises aerostat-borne or fixed-platform sensor arrays delivering continuous wide-area surveillance, typically integrating electro-optical, infrared, and radar payloads with ground-based command nodes for real-time threat classification. These systems achieve dwell times measured in days rather than hours, enabling persistent coverage of border regions, critical infrastructure perimeters, and maritime chokepoints that rotary-wing or satellite assets cannot economically sustain. Endpoint Protection commands the largest product type allocation as legacy military networks harden individual nodes against cyber-physical intrusion. Cloud Security represents the fastest-expanding deployment architecture as defense ministries adopt federated data processing for multi-domain operations. Hybrid deployments capture concentrated margin pools where classified and unclassified data streams require physically segregated processing layers with unified analytic interfaces.
The US Department of Defense Zero Trust mandate, administered through NIST and DISA frameworks, compels PTDS vendors to embed continuous authentication and encrypted telemetry pathways across all sensor-to-shooter data chains. EUs NIS2 Directive and CE marking requirements under the Cyber Resilience Act establish conformity benchmarks for cross-border critical infrastructure protection systems sold within member states. Stakeholders must evaluate how emerging electromagnetic spectrum allocation disputes between civilian 5G expansion and military radar operations constrain available frequency bands for next-generation airborne surveillance payloads.
Market Dynamics
The US Department of Defense Zero Trust architecture mandate is compressing vendor qualification timelines while simultaneously fragmenting procurement across cybersecurity-integrated and legacy hardware-only platforms. Defense ministries now disqualify suppliers unable to demonstrate continuous authentication protocols across sensor-to-shooter data chains.
Growth Catalysts
- NATO border surveillance mandates:Member states are accelerating aerostat procurement for eastern flank monitoring, with Poland and Romania expanding persistent coverage corridors.
- UAE critical infrastructure hardening:Port and energy facility operators in Abu Dhabi and Dubai are deploying aerostat-based perimeter systems to protect maritime chokepoints.
- DISA Zero Trust framework:The mandate forces legacy system upgrades, creating replacement demand for cybersecurity-integrated detection platforms across Pentagon procurement channels.
Market Restraints
- Helium supply concentration:Aerostat buoyancy depends on helium imports concentrated in Qatar and the United States, exposing operators to price volatility and export restriction risk.
- Electromagnetic spectrum congestion:Civilian 5G expansion in the C-band is squeezing military radar allocations, constraining payload frequency options for next-generation airborne surveillance.
- Tether material cost escalation:Advanced fiber-optic tethers incorporating copper power conductors face raw material price pressure from copper concentrate supply bottlenecks.
Strategic Opportunities
- Stratospheric platform convergence:Hybrid architectures combining aerostat persistence with high-altitude platform station keeping are opening multi-domain operations contracts.
- EU NIS2 Directive compliance:Cross-border critical infrastructure operators must upgrade perimeter detection, creating certified-system demand across member state energy and transport networks.
- Maritime domain awareness gaps:Strait of Hormuz and South China Sea chokepoint monitoring programs are expanding aerostat deployment for illegal fishing and smuggling interdiction.
Industry Challenges
- Cyber-physical engineering talent scarcity:Military engineering cadres trained in both aerostat operations and Zero Trust cybersecurity are rotating toward integrated programs, depleting ground-based radar maintenance pools.
- Multi-level security certification delays:DISA and NIST framework compliance timelines stretch 18-24 months, freezing vendor revenue recognition until authority-to-operate approvals finalize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Persistent Threat Detection System (PTDS) Market |
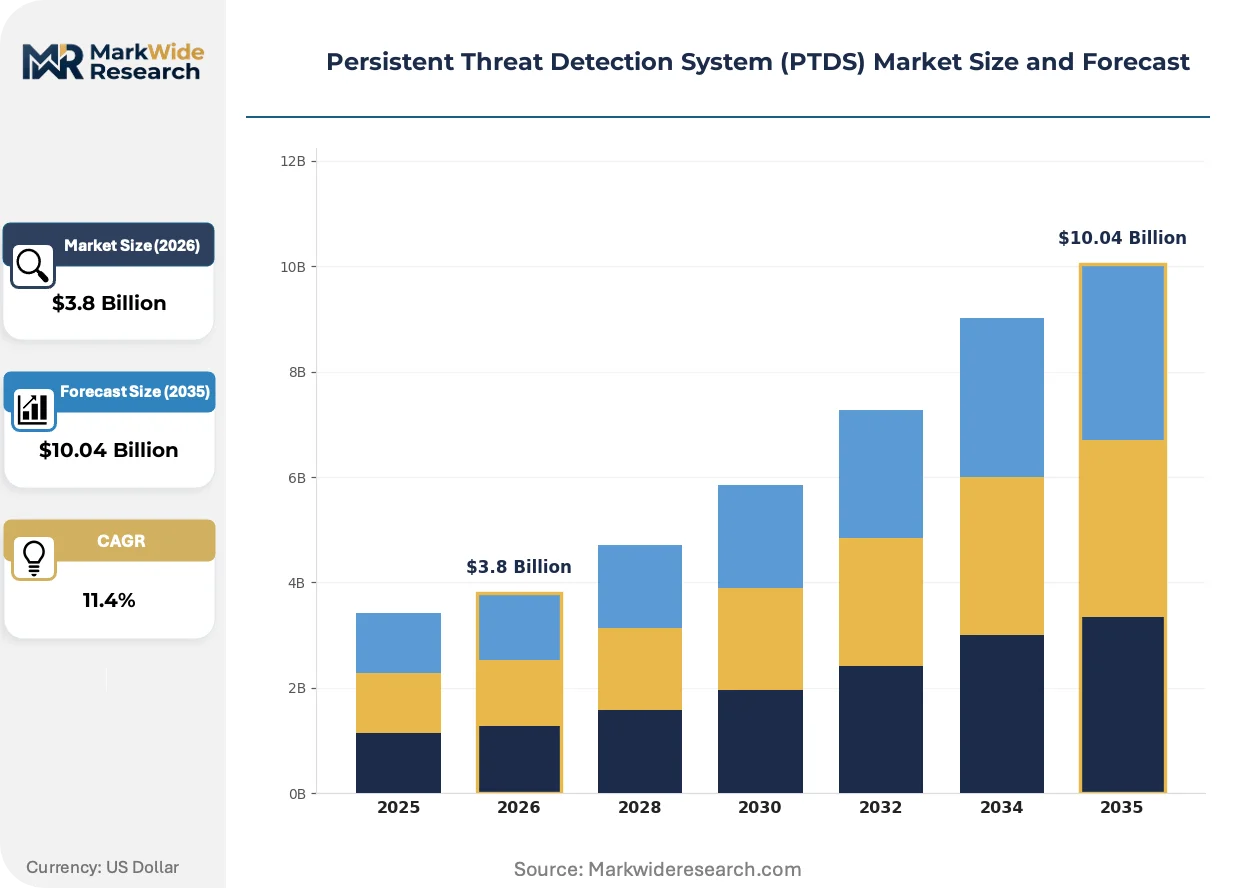
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endpoint Protection, Network Security, Cloud Security, Application Security Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Tenant End User: Government, BFSI, Healthcare, Telecom Technology: Machine Learning, User Behavior Analytics, Threat Intelligence, Automation |
| Companies Covered | AXIS Communications, Telephonics, Northrop Grumman, Thales, Flir Systems, Smiths Group, Lockheed Martin, Cisco Systems, Fortinet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Persistent Threat Detection System (PTDS) Market Emerging Trajectories
Active electronically scanned array technology is migrating from fixed ground radars onto aerostat payloads, compressing sensor size-weight-power constraints while expanding detection range. This migration is redrawing competitive boundaries between traditional radar houses and aerostat system integrators.
Synthetic aperture radar-on-chip technology is miniaturizing. DARPA and European defense research agencies are funding gallium nitride semiconductor integration for aerostat-borne SAR payloads. Maritime surveillance operators in the Mediterranean and Arabian Gulf are piloting these reduced-form-factor sensors for through-cloud ship detection. The technology is miniaturizing legacy radar footprints by 60 percent, enabling dual-payload configurations previously impossible under aerostat lift constraints.
The EU Cyber Resilience Act and CE marking requirements under NIS2 are mandating conformity benchmarks for cross-border critical infrastructure protection systems. Industrial consequence: vendors must re-engineer telemetry encryption and supply chain traceability for European market access. Energy facility operators in Germany, France, and the Netherlands are prioritizing pre-certified platforms to accelerate deployment timelines.
Buyer organizations are unbundling sensor procurement from platform integration contracts. Defense ministries now source electro-optical and radar payloads separately from aerostat hull and tether systems, then competitively bid integration services. This disintermediation is compressing incumbent system integrator margins while opening specialist payload vendors to direct government contracting. The United Kingdom Ministry of Defence and Australian Defence Force have adopted this model for their next-generation persistent surveillance programs.
Persistent Threat Detection System (PTDS) Market Segmentation
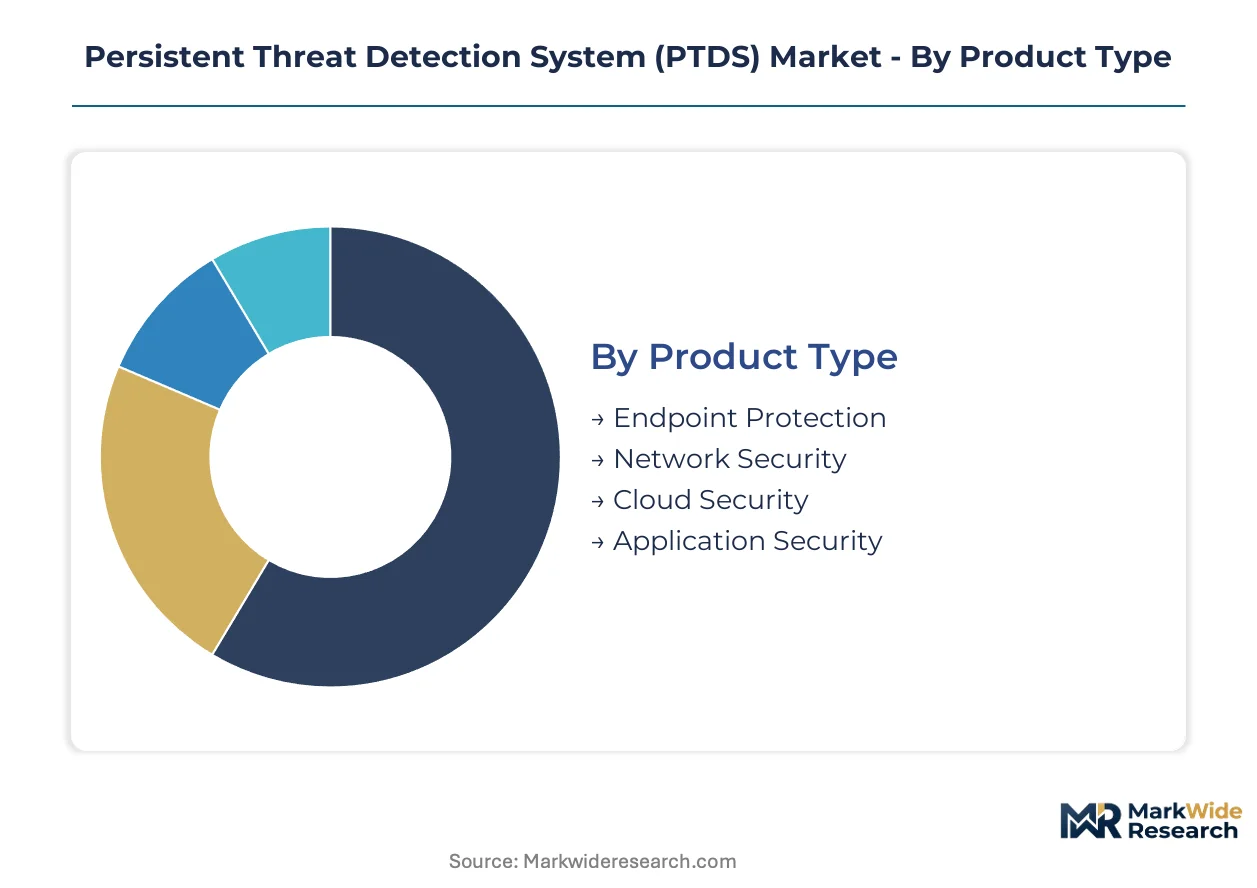
Segmentation in PTDS markets reveals how procurement channels bifurcate between defense integrators and commercial cybersecurity vendors. Buyers route endpoint protection through established military contractors while cloud security contracts flow directly to specialized platform providers.
Product Type:
Defense procurement channels favor integrated platforms combining physical and cyber protection, while commercial buyers unbundle components for competitive sourcing.
- Endpoint Protection:Hardware-software stacks harden individual sensor nodes and command terminals against intrusion. Pentagon procurement channels concentrate demand here as legacy military networks require node-level hardening under DISA Zero Trust mandates.
- Cloud Security:Federated data processing architectures enable multi-domain operations across distributed sensor networks. UAE critical infrastructure operators and European NATO members are expanding this category fastest for cross-border threat correlation.
- Network Security:Perimeter defense systems segment classified from unclassified data flows at aerostat ground stations.
- Application Security:Mission-specific software hardening protects threat classification algorithms from supply chain compromise.
By volume, Endpoint Protection leads. By growth pace, Cloud Security is expanding most quickly.
Deployment Model:
Cost tiering separates classified programs requiring physical isolation from commercial infrastructure operators prioritizing operational flexibility.
- On-Premises:Physically segregated processing environments handle classified aerostat telemetry at military installations. Intelligence community procurement maintains this preference despite higher capital intensity.
- Hybrid:Dual-layer architectures unify unclassified cloud analytics with classified on-premises processing through controlled interfaces. Energy facility operators in Germany and France favor this model for NIS2 compliance without full cloud migration.
- Cloud-Based:Pure cloud deployments suit commercial port operators and telecom providers with lower classification requirements.
- Multi-Tenant:Shared infrastructure models serve coalition operations where NATO members pool sensor data across national boundaries.
Hybrid deployments command premium pricing. Cloud-Based solutions are gaining share fastest among non-defense adopters.
End User:
Application requirements diverge sharply between sovereign defense programs and regulated commercial infrastructure.
- Government:Defense ministries and border agencies operate integrated aerostat-sensor networks for persistent territorial surveillance. Poland and Romania are expanding eastern flank coverage corridors under NATO collective defense commitments.
- BFSI:Financial institutions deploy perimeter detection for data center protection against physical-cyber combined threats.
- Healthcare:Hospital networks and medical device manufacturers adopt threat detection for operational technology security.
- Telecom:5G infrastructure operators monitor base stations and fiber landing points for sabotage and espionage.
Government accounts dominate contract value. BFSI represents the steepest expansion trajectory among commercial verticals.
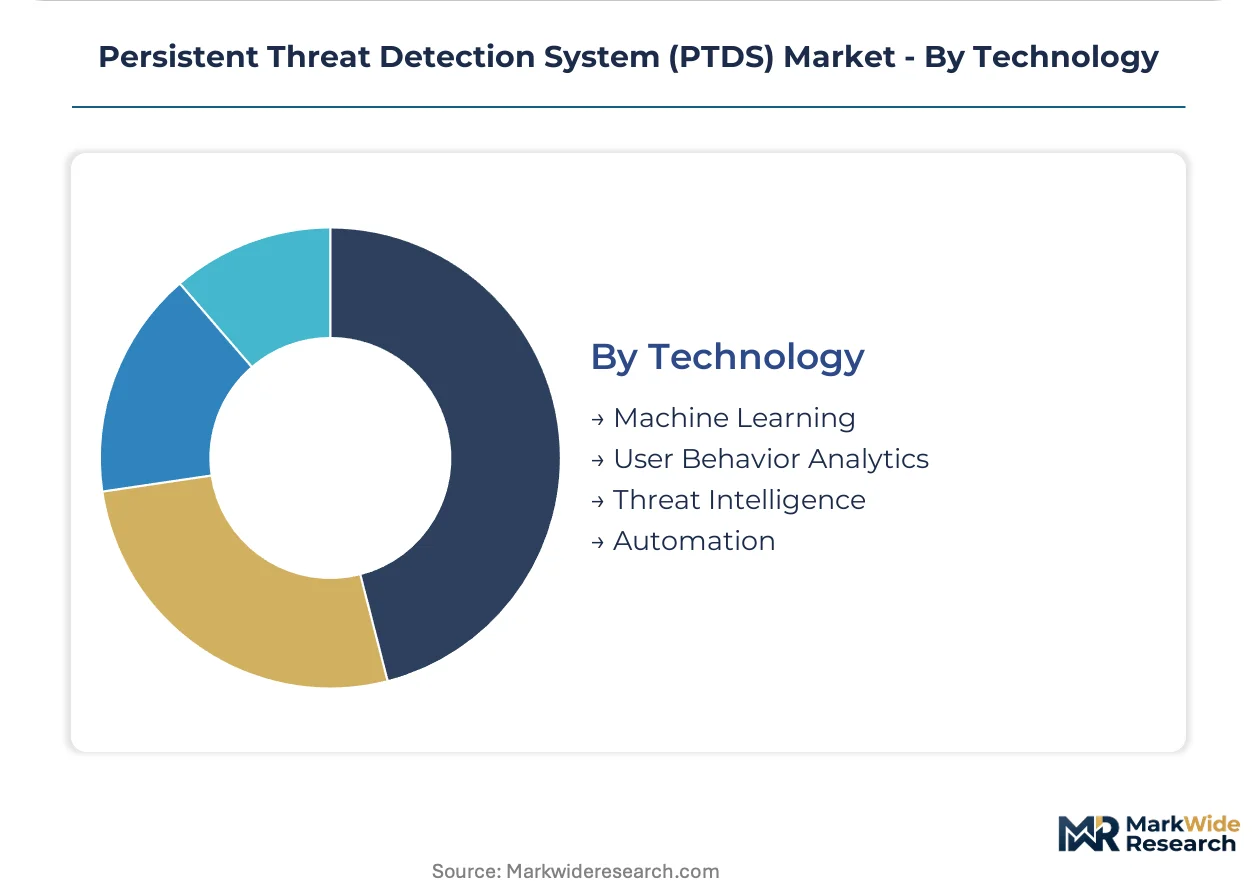
Technology:
Technology maturity curves separate proven detection methods from emerging capabilities still seeking operational validation.
- Machine Learning:Pattern recognition algorithms classify radar and electro-optical signatures in real time at aerostat ground stations. DARPA-funded research is compressing model size for edge deployment on tethered platforms.
- Threat Intelligence:Federated data sharing across NATO and Five Eyes partners enables correlated threat identification. This capability is climbing the fastest as alliance members integrate national sensor networks.
- User Behavior Analytics:Insider threat detection monitors ground station operator access patterns for compromise indicators.
- Automation:Autonomous response protocols reduce operator burden during high-tempo surveillance operations.
Machine Learning anchors current procurement. Threat Intelligence is pulling ahead on growth pace as alliance integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries in NATO member states deploy aerostat-borne surveillance for territorial border monitoring, while critical infrastructure operators in the Arabian Gulf prioritize maritime chokepoint protection using similar platforms. This consumption-mix differential reflects divergent threat environments: European states face land-border pressure, whereas UAE and Saudi operators concentrate on port and energy facility perimeters.
United States
The Pentagon's Zero Trust architecture mandate, administered through DISA and NIST frameworks, compels cybersecurity-integrated platform procurement for aerostat sensor networks. Defense agencies prioritize continuous authentication protocols across sensor-to-shooter data chains. The Southwest border corridor sees expanded aerostat deployment for persistent surveillance coverage.
Poland
Eastern flank NATO commitments drive accelerated aerostat procurement for border monitoring with Belarus and Kaliningrad. The country's national defense ministry aligns platform specifications with collective defense requirements. Industrial clusters near Warsaw concentrate integration services for multi-spectral payload systems.
United Arab Emirates
Critical infrastructure protection programs at Abu Dhabi and Dubai port facilities expand aerostat-based perimeter coverage for maritime chokepoint security. MOHAP and federal energy regulators mandate hardened detection systems for energy export terminals. Industrial zones along the Arabian Gulf coastline anchor deployment operations.
Germany
The EU NIS2 Directive and Cyber Resilience Act establish conformity benchmarks for cross-border critical infrastructure protection systems. Energy facility operators in North Rhine-Westphalia prioritize pre-certified platforms to accelerate deployment timelines. The Eindhoven-Randstadt corridor influences component sourcing patterns.
Romania
NATO collective defense commitments drive persistent surveillance corridor expansion along the Black Sea border. The national defense ministry coordinates platform specifications with allied interoperability standards. Constanța port complex operations integrate maritime domain awareness capabilities.
Persistent Threat Detection System (PTDS) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the PTDS market structure. Tier-one participants combine aerostat platform manufacturing with sensor payload integration and ground station command software. Two strategic archetypes dominate: legacy defense primes with layered defense heritage, and cybersecurity specialists pivoting toward physical-perimeter applications. Competitive moves concentrate on strategic partnerships for multi-domain operations and portfolio diversification into stratospheric platform convergence.
Within the integrated defense prime tier, Northrop Grumman and Lockheed Martin exemplify archetypes combining aerostat persistence with advanced tether management and power systems. Thales occupies a position representing European multi-spectral sensor fusion for contested electromagnetic environments. Among cybersecurity-integrated platform specialists, Cisco Systems and Fortinet anchor the network security architecture segment, while Flir Systems and AXIS Communications sit within the electro-optical payload specialist tier. Smiths Group and Telephonics represent mid-tier integration specialists competing on component modularity. These named entities collectively illustrate how vendor qualification timelines compress as defense ministries disqualify suppliers unable to demonstrate continuous authentication protocols.
| Leading Market Players |
|---|
| AXIS Communications |
| Telephonics |
| Northrop Grumman |
| Thales |
| Flir Systems |
| Smiths Group |
| Lockheed Martin |
| Cisco Systems |
| Fortinet |
| Others |
Supply Flow & Price Mechanics
Aerostat hull manufacturing scale in the United States and France anchors production economics, compressing unit costs for tethered platforms while elevating price floors for cybersecurity-integrated variants that demand DISA certification. This concentration rewards incumbents with captive helium sourcing arrangements and fiber-optic tether production capabilities, forcing smaller integrators toward modular payload assembly with thinner margins.
Pricing Analysis
Long-term offtake contracts dominate defense procurement, with Pentagon programs locking five-year aerostat leasing arrangements that bundle platform, sensor, and ground station maintenance. Price differentiation separates DISA-certified platforms from legacy hardware-only systems, with certification tier and tether material grade as primary drivers. Cost compression in commercial port security deployments is intensifying as UAE operators unbundle sensor procurement from platform integration. Government buyers exhibit lowest price sensitivity given mission-critical requirements, while commercial infrastructure operators in European energy sectors prioritize pre-certified platforms to accelerate NIS2 compliance timelines.
Supply Chain Analysis
Strait of Hormuz transit underwrites helium supply security for Arabian Gulf aerostat operators, though Qatari export concentration remains a structural vulnerability. Manufacturing draws from United States aerostat hull production, French tether and winch systems, and Israeli electro-optical payload integration. Raw material dependencies center on helium gas, copper concentrate for power conductors, and gallium nitride semiconductors for radar miniaturization. Single-source vulnerability concentrates in Qatar's helium export infrastructure and Chinese rare earth processing for magnet components. Distribution runs through defense prime integrators for military contracts and direct platform leasing for commercial critical infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero Trust architecture mandates and stratospheric platform convergence are compressing vendor qualification timelines while opening white-space opportunities for cybersecurity-native entrants. This regulatory-technological inflection favors suppliers with pre-certified encryption stacks and multi-domain operations software.
For Market Incumbents: Secure DISA authority-to-operate approvals for integrated sensor-to-shooter platforms before competitor certification cycles complete. Anchor tether and power management capabilities through backward integration into fiber-optic conductor production, defending against margin erosion from unbundled procurement trends. Prioritize stratospheric platform partnerships to capture hybrid architecture contracts as NATO members expand eastern flank surveillance corridors.
For New Entrants and Emerging Players: Lead with cloud-native threat correlation platforms targeting European energy operators under NIS2 Directive compliance pressure. The most penetrable segment sits in commercial port security across Mediterranean and Arabian Gulf chokepoints, where incumbent defense primes lack agile software deployment capabilities. Pursue direct payload contracts with disintermediated procurement models adopted by United Kingdom and Australian defence programs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cybersecurity-integrated platform specialists with existing DISA certification pathways over legacy hardware-only incumbents facing replacement demand. Long-term viability rests on multi-domain operations software and federated data architectures rather than aerostat hull manufacturing scale. Watch electromagnetic spectrum allocation rulings in C-band as the critical inflection signal for next-generation payload frequency options and competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero Trust Certification Investment | DISA authority-to-operate approvals unlock Pentagon procurement channels and coalition interoperability contracts. |
| Stratospheric Platform Partnership | Hybrid aerostat-HAPS architectures capture multi-domain operations demand from NATO eastern flank programs. |
| Helium Supply Captive Arrangement | Long-term offtake agreements with Qatari exporters insulate production economics from price volatility exposure. |
| Payload Unbundling Strategy | Direct electro-optical and radar contracts with defense ministries bypass incumbent system integrator margins. |
| EU NIS2 Pre-Certification | CE marking under Cyber Resilience Act accelerates deployment timelines for German and Dutch energy facility operators. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with aerostat program managers, cybersecurity integration leads at defense primes, DISA certification officers, and critical infrastructure security directors; alongside secondary validation through Pentagon budget justifications, NATO procurement disclosures, EU NIS2 implementation guidance, and customs records for helium and copper concentrate trade flows. Bottom-up platform deployment tallies across identified operator sites were triangulated against top-down defense ministry expenditure projections.
Across the analysis window, the analytical framework modeled volume and value trajectories through segmentation across deployment architecture, end-user vertical, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle timing for legacy platforms. Forecast inputs incorporated DISA certification pipeline velocity, helium supply contract renewal patterns, and electromagnetic spectrum allocation dispute resolution timelines.
Underlying assumptions cover sustained NATO eastern flank commitment levels and UAE critical infrastructure protection program continuity, with deviation risk concentrated in helium export restriction scenarios and C-band spectrum reallocation rulings. Practitioners should keep alternative scenarios live as Zero Trust implementation timelines and stratospheric platform technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Tactical Vests Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Smart Police Helmet Market
Physical Security
Active Geofencing Market
Physical Security
North America Physical Security Market
Physical Security
Global Wearable Security Device Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Bulletproof Glass Market
Physical Security
Canada Data Center Physical Security Market
Physical Security
Policing Technologies Market
Physical Security
Tactical Lights Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Physical Security Market