
 Smart Police Helmet Market | 2026-2036
Smart Police Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Police Helmet Market Insights
Fragmentation across municipal police departments and specialized tactical units is repositioning procurement patterns toward modular, upgradeable helmet systems. CrossHelmet leverages its augmented reality overlay architecture to dominate high-complexity environments. ZYON anchors European demand through its compliance with CE marking and EASA-derived safety protocols. Sena competes aggressively on wireless connectivity integration, sustaining channel control across North American highway patrol networks.
Smart police helmets integrate heads-up displays, biometric sensors, and real-time communication modules into ballistic or impact-resistant shell designs, primarily serving law enforcement officers requiring hands-free data access during active operations. Camera-integrated helmets lead current procurement volumes due to evidentiary recording requirements, while artificial intelligence-enabled systems represent the fastest-expanding technology segment as agencies deploy predictive threat analytics. GPS-enabled configurations occupy mature positions in highway patrol fleets, whereas augmented reality overlays concentrate margin pools within special task force contracts demanding fused sensor feeds.
The US Department of Justice and European Commission jointly shape product standards through ballistic certification requirements and data governance frameworks affecting evidence-chain integrity. The EU AI Act imposes algorithmic transparency obligations on facial recognition and behavioral prediction modules, constraining deployment scope for AI-integrated units. Stakeholders must monitor evolving procurement thresholds where federal grant programs intersect with emerging cybersecurity mandates for connected officer equipment.
Market Dynamics
Fragmentation across municipal police departments and specialized tactical units is repositioning procurement patterns toward modular, upgradeable helmet systems that accommodate evolving AI capabilities and shifting evidentiary standards.
Growth Catalysts
- US Department of Justice Safety Mandates:Federal grant programs for officer protection equipment are accelerating camera-integrated helmet deployments across metropolitan police forces.
- EU Internal Security Fund:Dedicated financing for smart policing infrastructure is channeling capital toward AI-enabled helmet systems in Germany, France, and the Netherlands.
- Smart City Convergence:Urban digitization initiatives in India are fusing law enforcement modernization budgets with municipal sensor networks.
Market Restraints
- Ballistic Certification Bottlenecks:Extended testing timelines under NIJ standards delay product commercialization by 18-24 months.
- Lithium-Ion Supply Concentration:Battery cell production dependence on East Asian suppliers creates input vulnerability for power-intensive AR-enabled units.
- EU AI Act Algorithmic Constraints:Transparency requirements for facial recognition modules restrict deployment scope for predictive threat analytics.
Strategic Opportunities
- Indian State-Level Procurement:Maharashtra and Karnataka police modernization programs represent underpenetrated demand for GPS-enabled highway patrol configurations.
- Edge-AI and Thermal Fusion:Convergence of on-device processing with infrared sensing is opening special task force contracts requiring low-latency threat detection.
- Outcome-Based Maintenance Contracts:Service models tying vendor payments to equipment uptime are displacing traditional capital expenditure procurement in German federal police.
Industry Challenges
- Embedded Systems Engineering Talent:Scarcity of specialists integrating ballistic shell design with real-time video compression is constraining R&D velocity.
- Evidence-Chain Cybersecurity Certification:FBI Criminal Justice Information Services compliance for data transmission modules extends development cycles.
- Legacy Radio Interoperability:Integration with existing encrypted communication networks requires costly protocol adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Police Helmet Market |
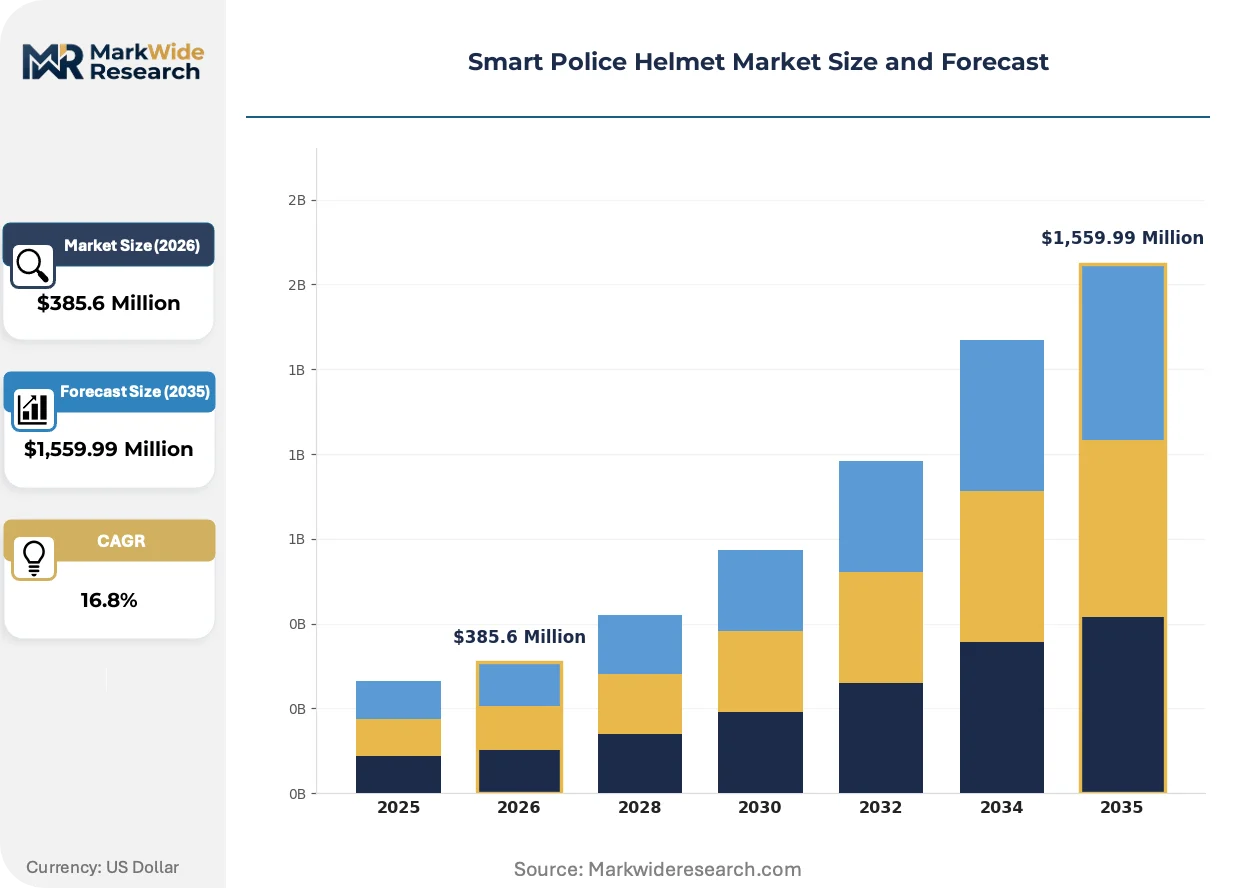
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,559.99 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Enabled Helmets, Camera Integrated Helmets, GPS Enabled Helmets, Night Vision Helmets, Impact Resistant Helmets Technology: Augmented Reality, Artificial Intelligence, Voice Recognition, Wireless Connectivity, Sensor Fusion Application: Traffic Management, Crime Prevention, Crowd Control, Surveillance, Search & Rescue End User: Municipal Police Departments, Highway Patrol Units, Special Task Forces, Investigation Agencies, Public Safety Organizations |
| Companies Covered | CrossHelmet, ZYON, Sena, MotoEye, Intelligent Cranium, HJC Helmets, Forcite, LS2 Helmets, Livall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Police Helmet Market Trends and Innovations
Active reshaping of the smart police helmet market stems from three intersecting forces: hardware miniaturization enabling new sensor payloads, algorithmic governance frameworks constraining AI deployment, and procurement model evolution favoring operational expenditure over capital ownership.
Augmented reality overlay architectures are expanding into high-complexity tactical environments. Special response teams in Los Angeles and Berlin are adopting fused sensor feeds combining thermal imaging, biometric monitoring, and building schematics. This capability compression is collapsing the historical separation between situational awareness tools and protective equipment.
The EU AI Act imposes algorithmic transparency obligations on facial recognition and behavioral prediction modules. Manufacturers must now document training data provenance and decision logic for law enforcement deployments. European agencies are responding by bifurcating procurement between restricted AI-enabled units for border control and camera-only configurations for municipal patrol.
Police departments are consolidating vendor relationships through multi-year fleet management agreements. California Highway Patrol and Bavarian State Police now contract for total cost of ownership rather than per-unit acquisition. This preference shift is most visible in North American and German markets where municipal budget pressures favor predictable operational expenditures over lumpy capital outlays.
Smart Police Helmet Market Segmentation
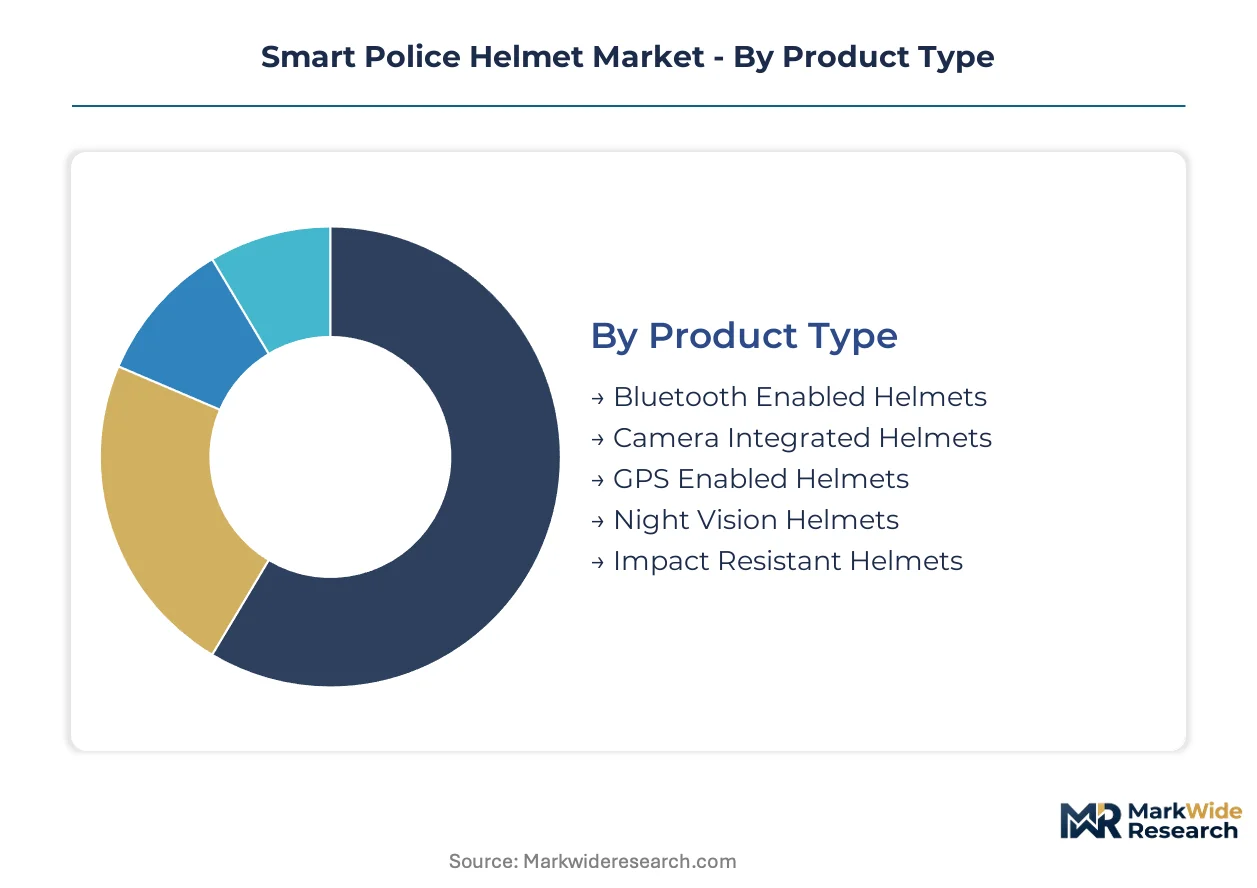
Segmentation in smart police helmets reveals how procurement priorities diverge across operational contexts. Technology integration depth and end-user mission profiles determine pricing tiers and vendor selection criteria.
Product Type:
Capital requirements vary sharply across shell configurations, with sensor-integrated systems demanding substantially higher upfront investment than baseline protective units.
- Camera Integrated Helmets:These units embed high-resolution recording modules with encrypted local storage and real-time streaming capability. Procurement concentrates in municipal police departments across the United States and Germany, driven by evidentiary recording mandates from the US Department of Justice and EU data governance frameworks.
- GPS Enabled Helmets:Location-tracking shells integrate satellite positioning with mesh networking for officer coordination in dispersed operations. Highway patrol units in India and the United States represent the primary demand concentration, supported by smart city infrastructure investments and fleet management digitization programs.
- Bluetooth Enabled Helmets:Short-range wireless connectivity enables hands-free communication with paired devices.
- Night Vision Helmets:Image-intensification or thermal sensor modules extend operational capability into low-light environments.
- Impact Resistant Helmets:Ballistic-rated shells prioritize protective performance over electronic integration.
Most installed capacity flows through Camera Integrated Helmets. Expansion is steepest in GPS Enabled Helmets.
Technology:
Application complexity separates mature connectivity layers from emerging cognitive systems requiring specialized engineering talent.
- Artificial Intelligence:On-device inference engines enable predictive threat analytics and automated scene interpretation. Special task forces in Germany and the Netherlands are deploying these capabilities under EU Internal Security Fund financing, though EU AI Act transparency obligations constrain facial recognition deployment scope.
- Augmented Reality:Heads-up display architectures overlay tactical data, building schematics, and biometric feeds onto the officer's field of view. Los Angeles and Berlin special response teams are adopting fused sensor configurations, collapsing the historical separation between situational awareness tools and protective equipment.
- Voice Recognition:Hands-free command interfaces reduce cognitive load during active operations.
- Wireless Connectivity:Radio and cellular integration enables real-time data transmission to command centers.
- Sensor Fusion:Multi-modal data integration combines thermal, biometric, and environmental inputs.
Wireless Connectivity commands the largest installed base. Sensor Fusion is gaining share fastest among special task force procurement.
Application:
Mission-criticality determines technology specification intensity, with high-stakes scenarios justifying premium integrated systems over modular add-ons.
- Crime Prevention:Proactive patrol operations require continuous recording and real-time analytics to intercept incidents before escalation. Municipal departments in urban India and the United States are prioritizing these deployments where smart city sensor networks intersect with law enforcement modernization budgets.
- Traffic Management:Highway patrol applications leverage GPS tracking and wireless communication for coordinated enforcement across extended road networks. California Highway Patrol and Bavarian State Police are consolidating vendor relationships through multi-year fleet management agreements favoring operational expenditure models.
- Crowd Control:Mass gathering security demands wide-area situational awareness and coordinated officer positioning.
- Surveillance:Covert and overt monitoring operations require discrete or overt recording capabilities.
- Search & Rescue:Extended field operations prioritize battery endurance and environmental resilience.
Traffic Management absorbs the majority of current procurement volume. Crime Prevention shows the steepest expansion trajectory as predictive analytics capabilities mature.
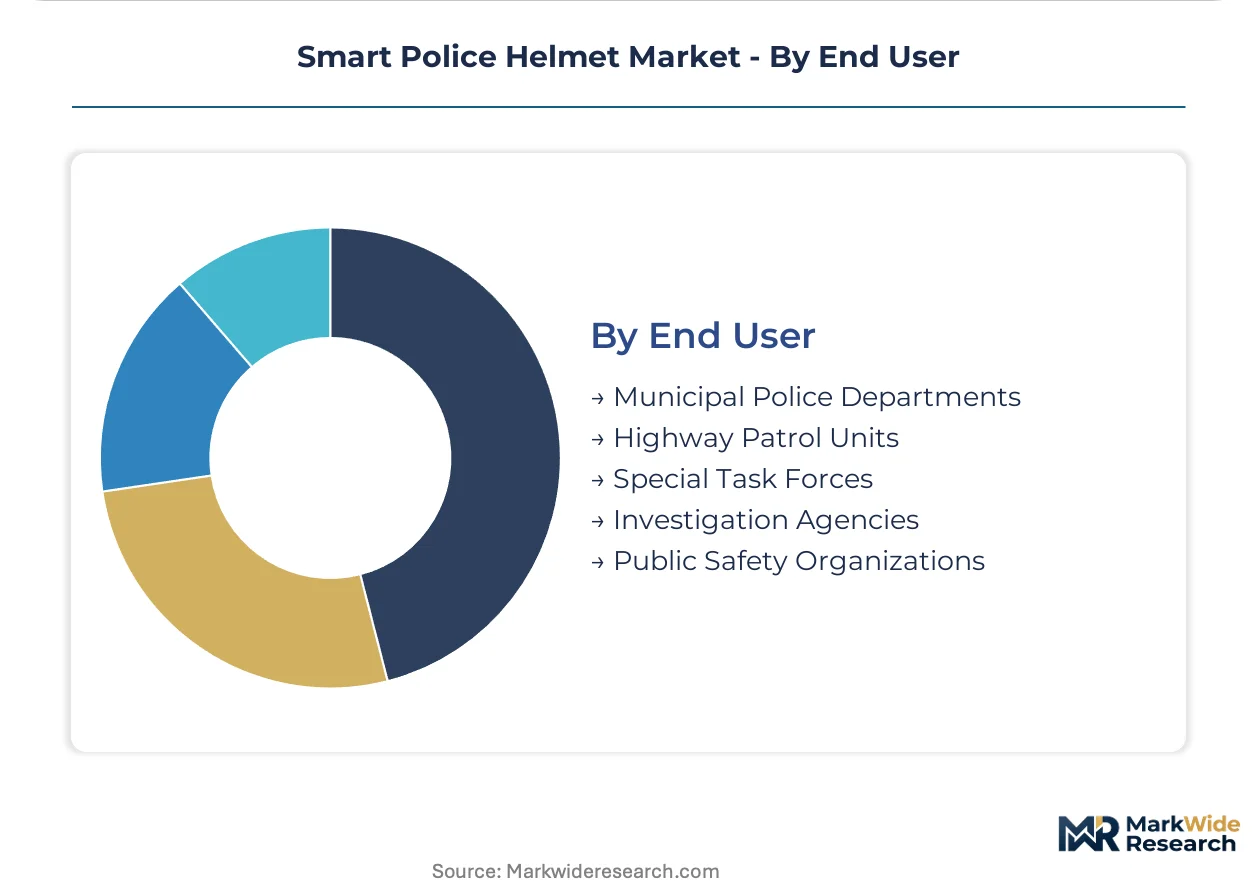
End User:
Budget scale and procurement autonomy create distinct customer tiers, from centralized federal programs to fragmented municipal purchasing.
- Municipal Police Departments:Urban law enforcement agencies balance officer safety mandates with evidentiary compliance requirements. These departments across North America and Europe are expanding camera-integrated helmet procurement through federal grant programs and smart city convergence initiatives.
- Special Task Forces:Tactical units demand the highest integration density, combining augmented reality, thermal fusion, and edge-AI processing for low-latency threat detection. German federal police and Los Angeles special response teams are contracting for total cost of ownership rather than per-unit acquisition.
- Highway Patrol Units:State and federal road enforcement agencies prioritize GPS tracking and wireless interoperability.
- Investigation Agencies:Detective and forensic units require discrete recording and evidence-chain integrity.
- Public Safety Organizations:Emergency management and disaster response agencies value modular upgrade paths.
Municipal Police Departments represent the dominant installed base. Special Task Forces are climbing the fastest as capability compression accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in procurement velocity, with German federal police favoring multi-year fleet agreements while US municipal departments chase federal grant windows. India accelerates on smart city convergence. France and the Netherlands calibrate AI deployment against regulatory guardrails.
United States
Municipal police departments in Los Angeles and New York Metro drive camera-integrated helmet procurement through US Department of Justice safety grants. FBI Criminal Justice Information Services compliance requirements shape evidence-chain cybersecurity standards for data transmission modules. California Highway Patrol contracts for total cost of ownership rather than per-unit acquisition.
Germany
Bavarian State Police and Berlin special response teams anchor European demand for augmented reality-enabled systems with fused sensor feeds. EU Internal Security Fund financing channels capital toward AI-enabled configurations, though EU AI Act transparency obligations constrain facial recognition deployment. German federal police pioneer outcome-based maintenance contracts tying vendor payments to equipment uptime.
India
Maharashtra and Karnataka police modernization programs generate concentrated demand for GPS-enabled highway patrol configurations. Smart city initiatives in Mumbai and Bangalore fuse law enforcement budgets with municipal sensor networks. BIS certification requirements for electronic safety equipment filter supplier eligibility.
France
Border control agencies in Paris and Marseille pilot AI-enabled units under EU Internal Security Fund programs, while municipal patrol forces procure camera-only configurations to sidestep algorithmic transparency constraints. ANSM and CNIL guidance on biometric data handling influences procurement specifications.
Netherlands
Special task forces in Amsterdam and Rotterdam deploy edge-AI configurations for low-latency threat detection in dense urban environments. EU AI Act algorithmic governance frameworks restrict predictive analytics deployment scope. Dutch national police integrate smart helmets with existing encrypted radio networks through costly protocol adaptation.
Smart Police Helmet Market Competitive Landscape
North American producers anchor the connectivity-integrated tier; European specialists hold the regulatory-compliance and AR-overlay segments. The vendor base separates into three strategic archetypes: augmented reality architects, wireless communication integrators, and modular ballistic shell fabricators. Consolidation pressures concentrate among municipal procurement channels, while special task force contracts sustain premium pricing for fused-sensor configurations. Competitive moves center on multi-year fleet management agreements and backward integration into battery cell supply.
Within the augmented reality tier, CrossHelmet exemplifies high-complexity environment positioning. ZYON occupies the European regulatory-compliance vector through CE marking alignment. Sena anchors North American highway patrol network penetration. These three entities represent distinct geographic-specialization archetypes rather than direct product competitors.
| Leading Market Players |
|---|
| CrossHelmet |
| ZYON |
| Sena |
| MotoEye |
| Intelligent Cranium |
| HJC Helmets |
| Forcite |
| LS2 Helmets |
| Livall |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion battery cells from East Asian suppliers flow through three pricing tiers before reaching municipal procurement officers, with raw material volatility compressing margins most acutely in AR-enabled configurations.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for power-intensive helmet systems. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated special task force units from camera-only municipal patrol configurations. Cost compression in the standard tier is intensifying because German federal police now contract for total cost of ownership rather than per-unit acquisition. Municipal departments in India exhibit the highest price sensitivity, while special task forces in Los Angeles and Berlin demonstrate minimal elasticity for fused-sensor configurations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean suppliers of high-density lithium-ion cells and thermal imaging sensors. Ballistic-grade composites draw from German and American specialty materials producers, while microprocessor fabrication rests on Taiwanese foundry capacity. Tariff exposure on Chinese electronics components threatens cost structures for GPS-enabled highway patrol units. Distribution runs through authorized defense equipment distributors with FBI Criminal Justice Information Services compliance certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
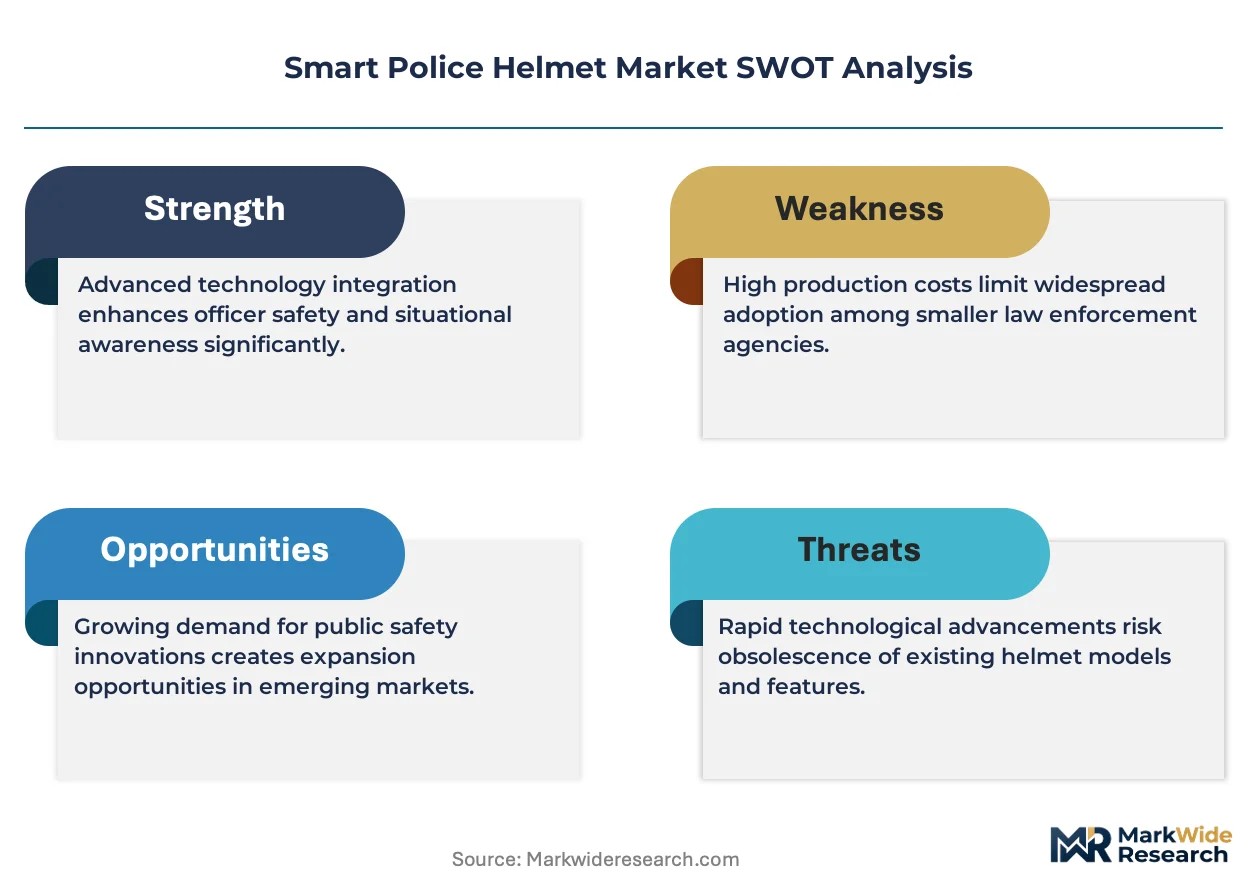
This market reads as a late-cycle quality story where procurement officers now prioritize evidence-chain integrity and algorithmic transparency over baseline protective specifications.
For Market Incumbents: Lock in multi-year fleet management agreements with California Highway Patrol and Bavarian State Police before outcome-based maintenance contracts become universal. Backward integration into battery cell supply hedges against East Asian supplier concentration. Invest in embedded systems engineering talent to defend against modular entrant architectures. For New Entrants and Emerging Players: Begin with GPS-enabled highway patrol configurations in Maharashtra and Karnataka, where Indian smart city convergence has outpaced established vendor relationships. Target municipal police departments in mid-sized American cities that missed initial federal grant windows. Lead with wireless connectivity integration as the wedge capability. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded firmware expertise intersects with ballistic certification capabilities. Five-to-ten-year viability favors vendors with captive supply of lithium-ion cells and in-house algorithmic transparency documentation for EU AI Act compliance. Watch for German federal police expanding outcome-based maintenance contracts as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Algorithmic transparency documentation unlocks German and Dutch special task force procurement. |
| Backward Integration into Battery Supply | Captive lithium-ion cell production insulates margins from East Asian supplier volatility. |
| Multi-Year Fleet Management Agreements | California Highway Patrol contracts demonstrate operational expenditure preference shift. |
| Edge-AI and Thermal Fusion Development | On-device processing meets Los Angeles special response team low-latency requirements. |
| FBI CJIS Cybersecurity Certification | Evidence-chain integrity standards filter supplier eligibility for US municipal departments. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Law enforcement procurement officers, ballistic certification engineers, embedded systems developers, and smart city infrastructure planners provided structured interviews. Secondary sources included FBI Criminal Justice Information Services compliance documentation, EU Internal Security Fund disbursement records, BIS certification filings, and municipal budget appropriation data. Bottom-up unit shipment estimates triangulated against top-down federal grant allocation analysis.
Granularity-level modeling operated at technology-integration tier, end-user mission profile, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from segmented growth rate reconciliation with macroeconomic law enforcement spending trajectories. Forecast inputs incorporated smart city infrastructure investment pipelines and evolving NIJ ballistic certification timelines.
Caveats apply where EU AI Act enforcement intensity or lithium-ion supply disruption could materially shift the outlook. Forecasts reflect assumptions about federal grant program continuity and municipal budget elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Border Security Technologies Market
Physical Security
Physical Security Services Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Security Guard Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Tactical Vests Market
Physical Security
Active Geofencing Market
Physical Security
North America Physical Security Market
Physical Security
Global Wearable Security Device Market
Physical Security
Bulletproof Glass Market
Physical Security
Physical Security Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Policing Technologies Market
Physical Security
France Data Center Physical Security Market
Physical Security
Body Armor Plates Market