
 Physical Security Services Market | 2026-2036
Physical Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Security Services Market Outlook
AI-powered video analytics is reshaping how physical security services are delivered, replacing reactive patrol models with predictive threat detection. Allied Universal leverages its scale to integrate manned guarding with remote monitoring centers across North America. Securitas AB anchors its competitive position through technology-led service bundles combining on-site personnel with digital platforms. GardaWorld Corporation specializes in high-risk site protection for energy and mining clients, differentiating through specialized training protocols.
Physical security services encompass the deployment of trained personnel, electronic surveillance systems, and access control mechanisms to protect assets, infrastructure, and individuals from unauthorized intrusion, theft, or violence. These services typically integrate manned guarding with CCTV monitoring, perimeter detection sensors, and emergency response coordination to create layered protection architectures. On-site security and monitoring services represent the mature revenue core, while mobile patrol and integrated technology offerings capture expanding margin pools as clients seek flexible, data-driven protection. End users in commercial buildings and government facilities drive structural demand, with retail stores accelerating adoption of loss prevention services amid organized crime pressures.
FDA workplace safety guidelines, OSHA protective service standards, and EU GDPR data handling requirements shape how security providers deploy biometric access control and video retention systems across jurisdictions. Compliance with these frameworks determines market access for technology-integrated service offerings and elevates operational costs for providers managing cross-border data flows. Stakeholders must weigh capital allocation between human capital training and sensor infrastructure as labor availability tightens and client expectations shift toward real-time situational awareness.
Market Dynamics
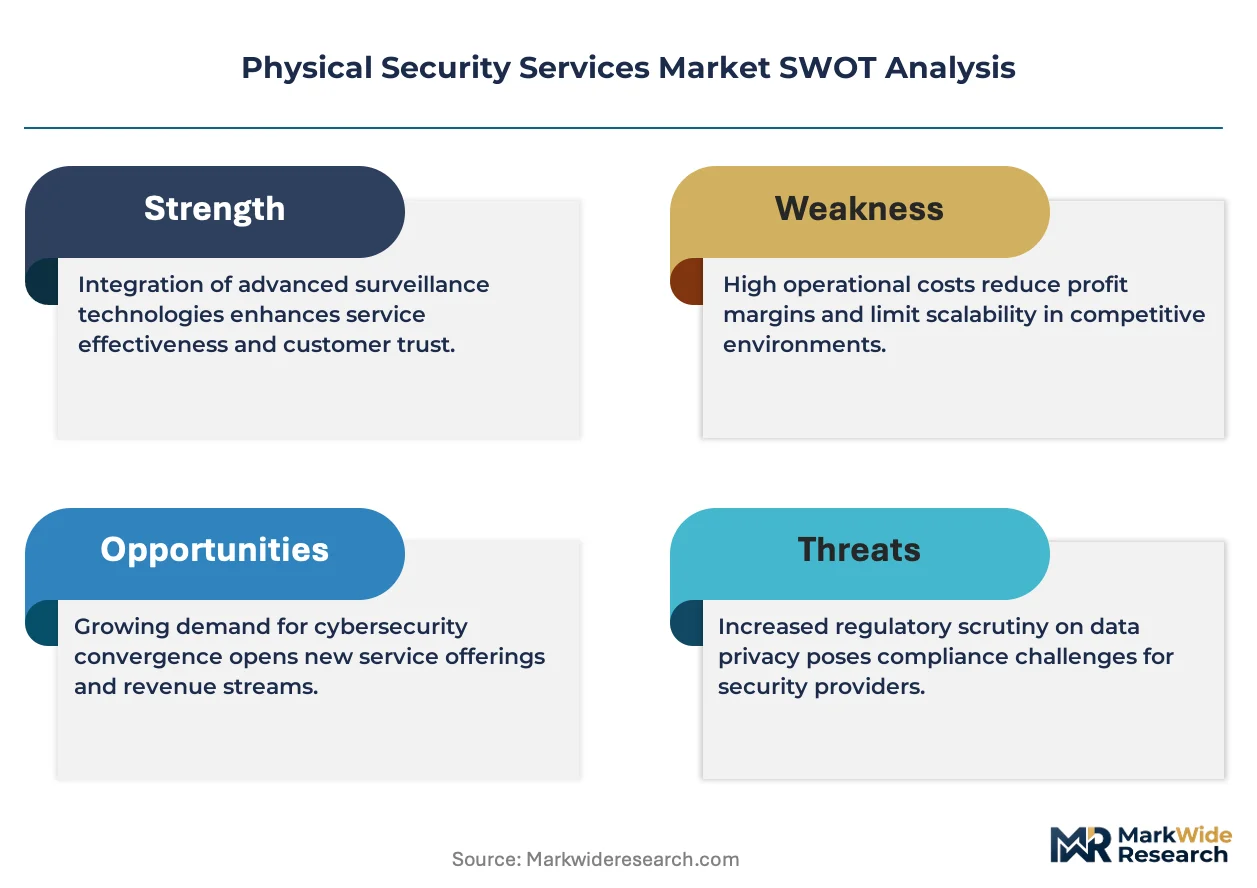
The physical security services sector is undergoing fundamental restructuring as labor scarcity forces providers to rebalance human capital against sensor infrastructure investments. This tension between guarding payrolls and technology deployment is compressing margins while elevating compliance complexity under divergent regional data frameworks.
Growth Catalysts
- Critical Infrastructure Protection Mandates:Energy facilities and transportation hubs across the United States, China, and Germany are expanding perimeter security contracts under national resilience directives.
- EU GDPR Video Retention Requirements:European data handling rules are accelerating replacement of legacy analog CCTV with compliant cloud-archived systems integrated with manned response protocols.
- AI-Powered Behavioral Analytics:Predictive threat detection algorithms deployed in retail loss prevention are reducing shrinkage rates below reactive patrol benchmarks.
Market Restraints
- Licensed Guard Labor Shortages:Background check delays and wage competition from logistics sectors are constraining workforce availability in major metropolitan markets.
- Semiconductor Supply Concentration:Video processing chip dependencies on Taiwan and South Korean fabrication are creating lead time volatility for access control hardware upgrades.
- Biometric Data Regulatory Friction:Illinois BIPA and similar state-level biometric privacy statutes are imposing litigation risk and consent complexity on fingerprint and facial recognition deployments.
Strategic Opportunities
- India Smart City Security Integration:Urban surveillance infrastructure buildouts under the national mission are creating bundled service opportunities combining electronic monitoring with emergency response.
- Drone-Based Perimeter Surveillance:Aerial patrol systems converging with ground sensor networks are opening new service tiers for expansive industrial sites and agricultural operations.
- OSHA Workplace Violence Prevention Standards:Updated federal guidelines are mandating threat assessment protocols that security providers can package as subscription consulting services.
Industry Challenges
- Cyber-Physical Integration Expertise Gap:Security technicians lack cross-training in IT network hardening required for IoT sensor deployment, forcing reliance on subcontracted specialists.
- Multi-Jurisdictional Certification Timelines:State-by-state licensing reciprocity failures are delaying guard mobilization across contract portfolios spanning multiple US territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Security Services Market |
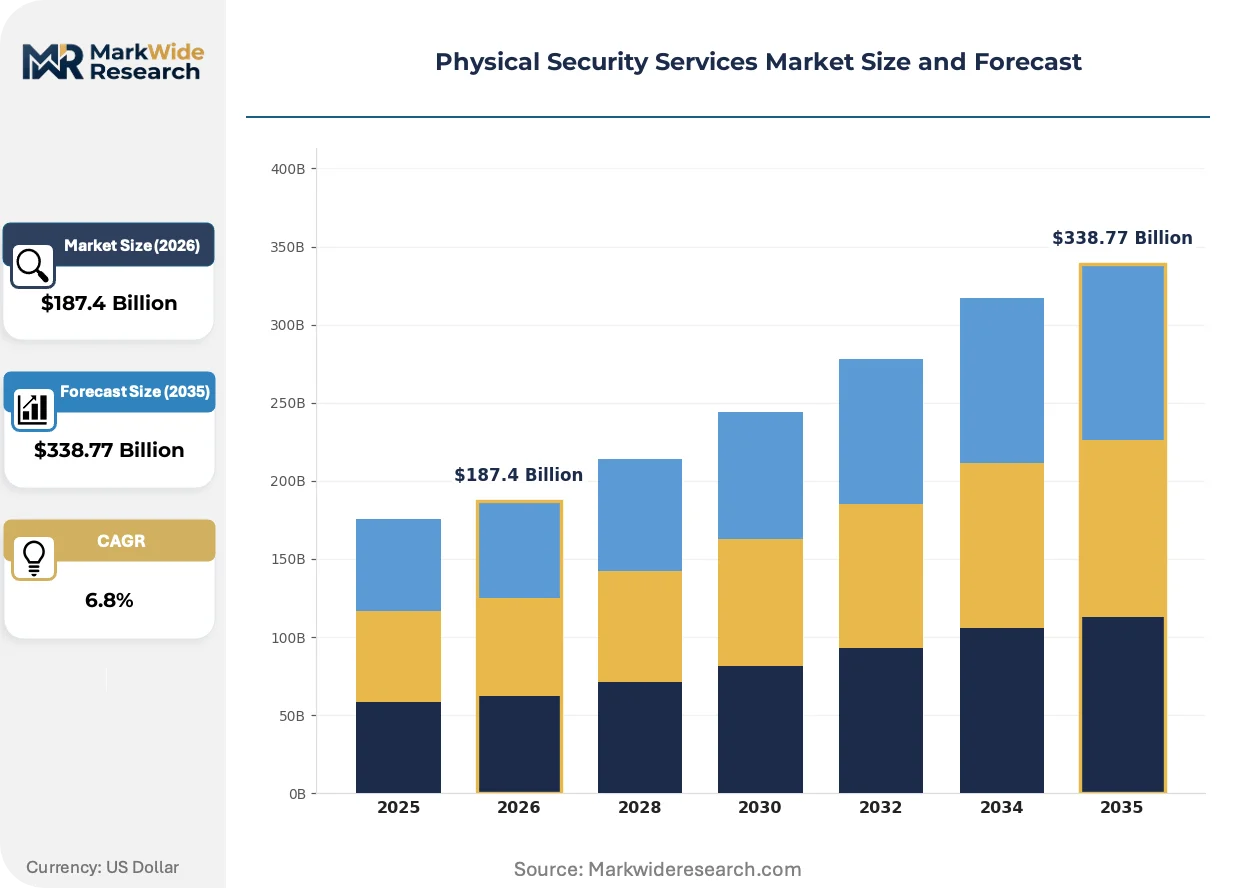
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Site Security, Monitoring Services, Mobile Patrol, Event Security End User: Commercial Buildings, Retail Stores, Government Facilities, Residential Areas Technology: CCTV Systems, Access Control, Intrusion Detection, Alarm Systems Application: Risk Assessment, Emergency Response, Loss Prevention, Security Audits |
| Companies Covered | Allied Universal, Securitas AB, Prosegur Compania de Seguridad, Secom Co., Ltd., Brink's Company, GardaWorld Corporation, ADT Inc., Johnson Controls International plc, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Security Services Market Strategic Shifts
Edge computing architectures are redistributing processing load from central command centers to field devices, enabling millisecond-latency threat response without bandwidth dependency. This shift is collapsing traditional hierarchies between remote monitoring and on-site intervention.
Computer vision platforms with embedded GPU acceleration are collapsing the distinction between recorded evidence review and real-time intervention. Large warehouse operators and distribution centers are deploying these systems at loading dock perimeters to intercept unauthorized access before breach completion. The technology is collapsing incident response timelines from minutes to seconds while reducing required guard density.
EU AI Act risk classification rules are redefining biometric deployment permissibility across member states. High-risk applications including real-time facial recognition in public spaces now require conformity assessments and human oversight mandates. German critical infrastructure operators are restructuring procurement specifications to exclude non-compliant vendors, while French CNIL enforcement is accelerating data protection impact assessment adoption.
Consolidated facility management contracts are unbundling security from bundled service agreements as procurement teams seek direct vendor relationships. Commercial real estate investment trusts are negotiating separate technology and guarding contracts to retain data ownership and switch providers without operational disruption. This pattern is most pronounced in United States Class A office portfolios where tenant experience platforms demand API-integrated security data feeds.
Physical Security Services Market Segmentation
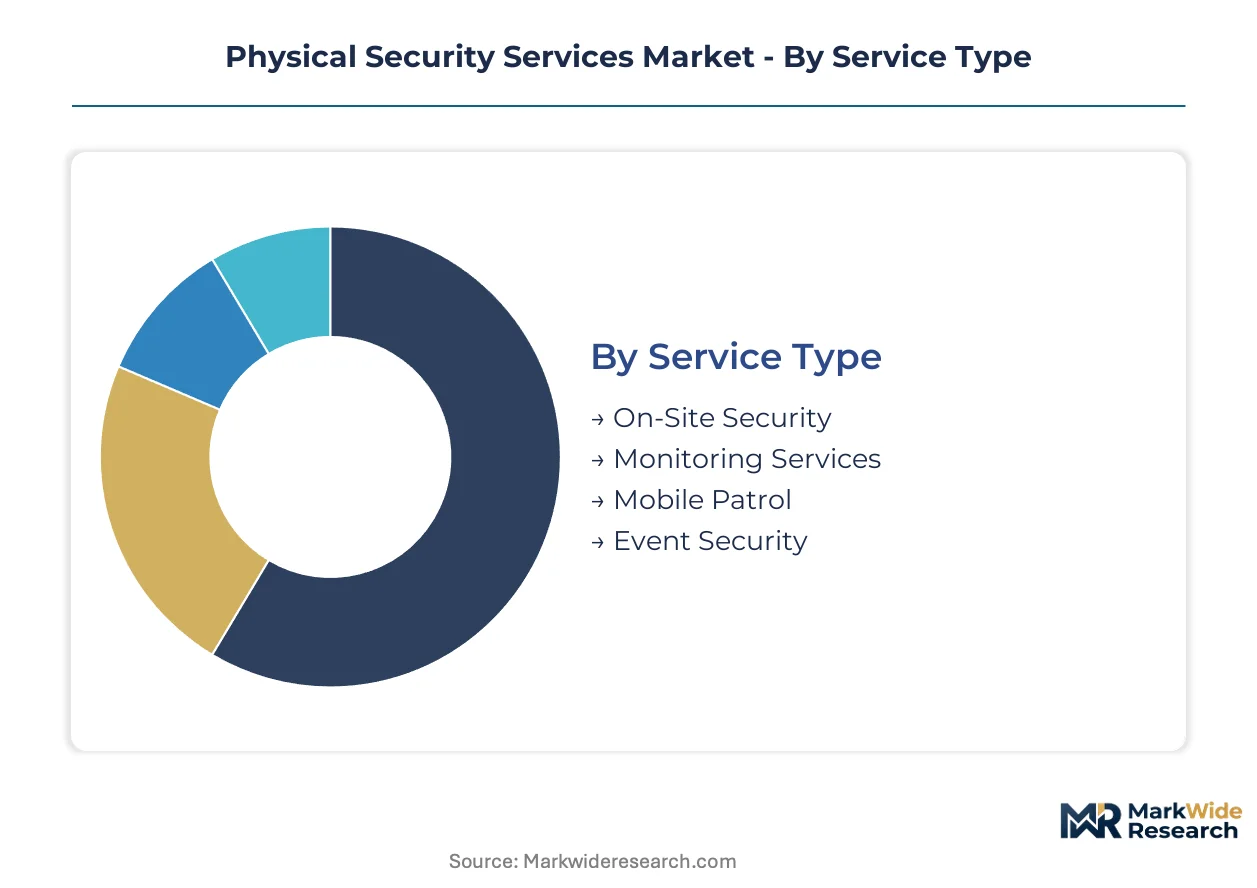
Segmentation in physical security services reveals how procurement patterns diverge between asset-heavy infrastructure operators and service-oriented commercial tenants. Understanding these splits enables providers to align staffing models, technology bundles, and compliance protocols with distinct buyer economics and risk profiles.
Service Type:
After-sales service intensity varies sharply across service types, with monitoring centers demanding 24/7 technical support while mobile patrol operates on break-fix schedules.
- On-Site Security:Deployment of uniformed personnel at fixed posts requiring continuous supervision, access verification, and incident documentation. Demand concentrates in United States government facilities and German critical infrastructure sites under national resilience directives mandating human-verified perimeter control.
- Monitoring Services:Centralized surveillance of sensor feeds and alarm conditions from remote operations centers. Commercial real estate investment trusts in United States Class A office portfolios are unbundling these contracts to retain data ownership and enable provider switching without operational disruption.
- Mobile Patrol:Scheduled or randomized vehicle-based inspection rounds covering multiple client sites. Agricultural operations and expansive industrial parks favor this model for cost coverage of dispersed assets.
- Event Security:Temporary personnel deployment for crowd management, access control, and emergency response at gatherings. Stadium operators and convention centers drive seasonal demand spikes with specialized training requirements.
On-Site Security holds the largest share; momentum sits with Monitoring Services as cloud-archived video analytics displace reactive patrol models.
End User:
Cost tier differentiation separates premium-integrated security buyers from budget-constrained segments with diverging technology appetite.
- Commercial Buildings:Office towers, mixed-use developments, and industrial parks requiring layered access control and visitor management. United States REITs are negotiating separate technology and guarding contracts to maintain API-integrated tenant experience platforms.
- Retail Stores:Loss prevention services combining visible deterrence with covert surveillance. Organized crime pressures are accelerating adoption of AI-powered behavioral analytics to reduce shrinkage below reactive patrol benchmarks.
- Government Facilities:Federal, state, and municipal buildings with classified or sensitive operations. Compliance with OSHA protective service standards and FDA workplace safety guidelines shapes procurement specifications.
- Residential Areas:Gated communities, apartment complexes, and private estates requiring concierge-security hybrid models. Homeowners associations favor subscription-based monitoring over full-time posted guards.
Commercial Buildings anchor revenue concentration; Retail Stores are climbing the fastest as organized crime pressures intensify technology investment.
Technology:
Application context determines whether buyers prioritize standalone reliability or integrated ecosystem compatibility.
- CCTV Systems:Video capture infrastructure spanning analog legacy networks to IP-based cloud architectures. EU GDPR video retention requirements are accelerating replacement cycles across Germany and France with compliant cloud-archived systems.
- Access Control:Credential verification through keycards, biometrics, or mobile credentials. Illinois BIPA and similar state-level biometric privacy statutes are imposing litigation risk on fingerprint and facial recognition deployments in United States commercial facilities.
- Intrusion Detection:Perimeter sensors, motion detectors, and glass-break monitors triggering alarm conditions. Edge computing architectures are redistributing processing to field devices for millisecond-latency response without bandwidth dependency.
- Alarm Systems:Audible deterrents and silent alert transmission to monitoring centers or law enforcement. Integration with computer vision platforms is collapsing incident response timelines from minutes to seconds.
CCTV Systems retain the largest installed base; Access Control is gaining share fastest as biometric deployments expand despite regulatory friction.
Application:
Customer type segmentation separates preventive advisory services from reactive intervention capabilities with distinct margin profiles.
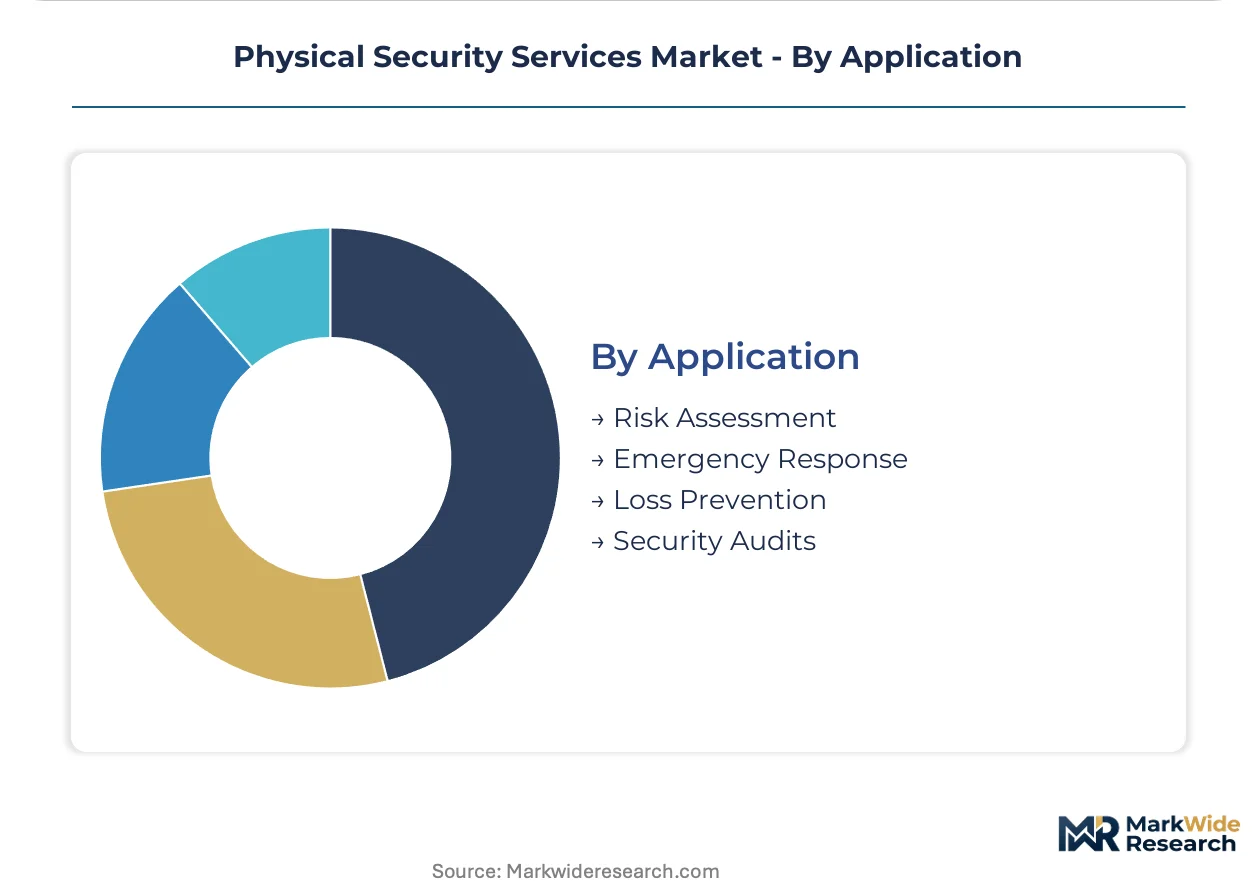
- Risk Assessment:Systematic evaluation of vulnerabilities, threat likelihood, and protective measure adequacy. Updated OSHA workplace violence prevention standards are mandating threat assessment protocols that security providers package as subscription consulting services.
- Emergency Response:Coordinated mobilization of personnel, medical aid, and law enforcement liaison during critical incidents. India's Smart City Mission is creating bundled opportunities combining electronic monitoring with emergency response infrastructure.
- Loss Prevention:Inventory protection through surveillance, access restrictions, and investigative protocols. Warehouse operators deploy GPU-accelerated computer vision at loading dock perimeters to intercept unauthorized access before breach completion.
- Security Audits:Compliance verification against regulatory frameworks and internal policy standards. EU AI Act risk classification rules are redefining audit scope for biometric deployments across member states.
Risk Assessment commands premium pricing; Loss Prevention shows the steepest expansion trajectory as retail shrinkage pressures intensify technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in physical security services remain limited given the localized nature of guarding contracts, though technology components and cross-border service contracts create measurable trade flows in surveillance hardware and integrated platform licensing.
United States
Critical infrastructure protection mandates and federal workplace violence prevention standards are expanding security service procurement across energy facilities and transportation hubs. OSHA updated guidelines require threat assessment protocols that providers package as subscription consulting offerings. Houston's energy corridor and Dallas-Fort Worth logistics clusters are driving perimeter security contract growth for pipeline and distribution center operators.
China
Smart city surveillance infrastructure buildouts under national urbanization programs are creating bundled service opportunities combining electronic monitoring with emergency response coordination. MIIT standards for IoT security devices shape procurement specifications for access control hardware. Yangtze River Delta megacities including Shanghai and Hangzhou are deploying integrated security platforms across commercial districts and industrial parks.
Germany
Critical infrastructure operators are restructuring procurement specifications under EU AI Act risk classification rules that exclude non-compliant biometric vendors. GDPR video retention requirements accelerate replacement of legacy analog CCTV with cloud-archived systems. Ruhr industrial belt facilities and Bavarian automotive manufacturing clusters are upgrading perimeter protection systems with AI-integrated manned guarding protocols.
India
Urban surveillance infrastructure expansion under the Smart City Mission is generating demand for electronic monitoring bundled with emergency response services. BIS certification requirements for security equipment create compliance thresholds for technology-integrated service offerings. Maharashtra's Mumbai-Pune corridor and Karnataka's Bengaluru tech parks are concentrating contract awards for campus security and data center protection.
United Kingdom
Commercial real estate investment trusts are unbundling security contracts from consolidated facility management agreements to retain data ownership and enable provider switching. GDPR compliance requirements shape video analytics deployment specifications across retail and office portfolios. London's Canary Wharf financial district and Manchester's logistics hubs are driving demand for API-integrated tenant experience platforms with embedded security data feeds.
Physical Security Services Market Competitive Environment
On the supply side, the industry is consolidating around technology-enabled guarding platforms that blend human capital with sensor infrastructure. Tiered competitive positioning separates multinational scale operators from regional specialists and pure-play technology integrators. Dominant competitive moves include vertical integration into remote monitoring center networks and strategic partnerships with computer vision software vendors to embed predictive analytics into service bundles.
Within the multinational guarding tier, Allied Universal and Securitas AB exemplify scale-driven consolidation strategies that combine manned personnel deployment with digital platform integration. GardaWorld Corporation occupies a specialized position in high-risk site protection. Japanese electrical conglomerate Secom Co., Ltd. and Swedish security group Securitas AB represent contrasting geographic anchoring strategies—Asia-Pacific technology-led service models versus European unionized labor management frameworks.
| Leading Market Players |
|---|
| Allied Universal |
| Securitas AB |
| Prosegur Compania de Seguridad |
| Secom Co., Ltd. |
| Brink's Company |
| GardaWorld Corporation |
| ADT Inc. |
| Johnson Controls International plc |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Taipei and Hsinchu anchor semiconductor supply for video processing chips, and their capacity constraints transmit directly into pricing power for access control hardware manufacturers serving North American and European security integrators. Guard labor markets in Houston and Dallas-Fort Worth face parallel pressure, with wage competition from logistics sectors compressing margins for manned guarding contracts while technology premiums expand for AI-integrated service bundles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by ISO 27001 certification status and after-sales service bundling. Cost compression in the economy tier intensifies because semiconductor lead time volatility forces hardware substitution, while premium buyers demonstrate low price sensitivity for biometric-integrated access systems. Retail loss prevention services exhibit highest price sensitivity due to thin merchandise margins and competing shrinkage reduction alternatives.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Taiwan, South Korea, and China-based fabrication plants shape working capital requirements for security hardware distributors. Video processing GPUs, CMOS image sensors, and edge computing modules draw from concentrated Asian manufacturing, with single-source vulnerability around Taiwan Strait logistics creating contingency planning mandates. Distribution runs through authorized security integrators and direct OEM relationships to end-user facilities, bypassing traditional IT channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physical security services constitute a defensive-moat market where regulatory entrenchment—state-by-state licensing reciprocity failures and federal compliance mandates—erects structural barriers against new entrant displacement. Switching costs accumulate through integrated technology platforms and guard training investments that penalize provider churn.
For Market Incumbents: Pre-empt margin erosion from pure-play technology entrants by embedding predictive analytics into existing guarding contracts and securing backward integration into remote monitoring center networks. Guard labor scarcity in major metropolitan markets demands accelerated sensor infrastructure deployment to rebalance cost structures. OSHA workplace violence prevention standards create certification investment opportunities that deepen client lock-in. For New Entrants and Emerging Players: Pursue white-space opportunities in India's Smart City Mission corridors and drone-based perimeter surveillance for expansive agricultural operations. Drone patrol integration for industrial sites represents the most penetrable application layer, with minimal incumbent saturation. A go-to-market angle emphasizing API-native platforms for commercial real estate investment trusts bypasses legacy system replacement friction. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate facility management divisions where security services remain non-core despite stable cash generation. Long-term viability centers on technology-enabled guarding platforms capable of margin expansion through sensor density increases rather than headcount growth. The signal to watch is biometric regulatory clarity—resolution of Illinois BIPA litigation patterns and EU AI Act enforcement consistency—as an inflection indicator for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Monitoring Center Acquisition | Captures recurring revenue streams and deepens technology integration capabilities for enterprise clients. |
| Computer Vision Platform Partnership | Embeds GPU-accelerated threat detection into service bundles, collapsing incident response timelines. |
| Biometric Compliance Certification | Addresses Illinois BIPA and EU AI Act requirements, unlocking procurement access to regulated facilities. |
| Guard Training Academy Expansion | Mitigates licensed labor shortages through captive credential pipelines, reducing mobilization delays. |
| Smart City Infrastructure Bid | Positions bundled electronic monitoring and emergency response for India's urban surveillance buildouts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with security operations directors, facility management procurement leads, guard force supervisors, and technology integration specialists. Secondary validation drew from OSHA enforcement databases, EU AI Act implementation guidance, SEC 10-K disclosures from listed security providers, and customs records for surveillance hardware imports. Bottom-up contract value aggregation and top-down market sizing triangulation reconciled segment-level estimates across the analysis window.
Calibration against historical contract award patterns and technology adoption curves shaped the analytical framework across service type, end user, technology, and application dimensions. CAGRs were derived from segment-level growth rate differentials weighted by revenue concentration, with inputs including guard wage inflation indices, semiconductor supply lead times, and regulatory compliance cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting real estate investment trust capital allocation or geopolitical disruption to Taiwan semiconductor fabrication would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Europe Cargo Inspection Market
Physical Security
Tactical Lights Market
Physical Security
North America Physical Security Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Tactical Vests Market
Physical Security
Body Armor Plates Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Physical Security Equipment Market
Physical Security
France Data Center Physical Security Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Europe Physical Security Market
Physical Security
Security Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Physical Security Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Asia-Pacific (APAC) Physical Security Market