
 France Data Center Physical Security Market | 2026-2036
France Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
France Data Center Physical Security Market Insights
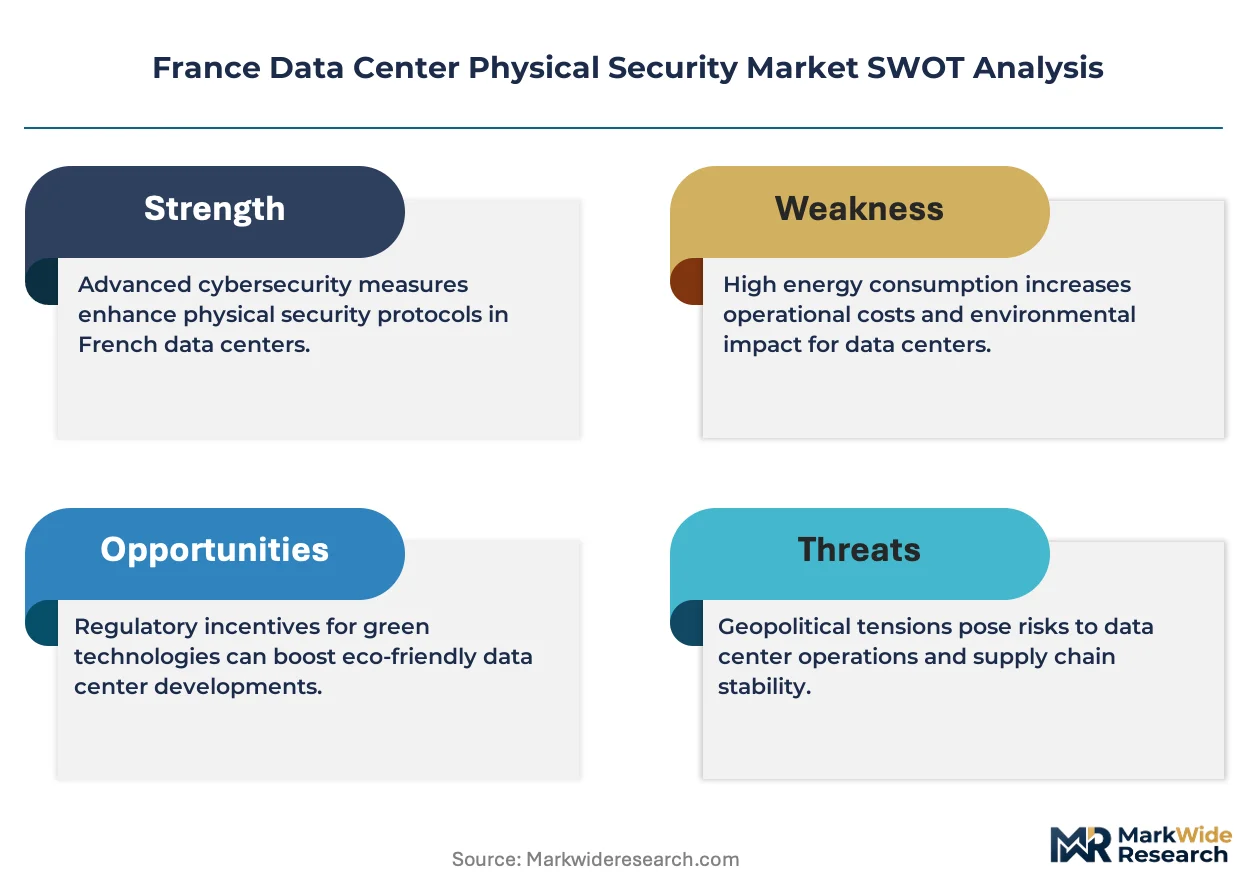
Skilled cybersecurity-physical security convergence talent is bifurcating the competitive landscape in France. Schneider Electric SE leverages its integrated building-to-IT infrastructure portfolio to anchor large enterprise deployments. Thales Group competes through its defense-grade encryption and biometric access systems, sustaining premium positioning in government-facing contracts.
France data center physical security encompasses perimeter defense, access control, surveillance, and intrusion detection systems engineered to protect critical IT infrastructure from unauthorized physical access, environmental threats, and deliberate sabotage. Biometric authentication systems now integrate multi-factor verification with iris and fingerprint recognition, achieving false acceptance rates below 0.001% in certified deployments. Video analytics dominates technology adoption as AI-powered behavior recognition replaces passive monitoring, while access control captures the largest solution margin pool due to recurring credential management revenue. Colocation facilities represent the fastest-growing end user segment as multi-tenant operators standardize on cloud-based, hybrid installation architectures to serve fragmented tenant security policies.
ANSSI, France's national cybersecurity agency, mandates security certification for operators of vital importance under the NIS2 directive transposition, directly shaping procurement specifications for critical data center assets. The country's national data center energy efficiency regulations, administered by ADEME and aligned with EU Green Deal requirements, force security system vendors to demonstrate low-power standby consumption and thermal resilience. Stakeholders must monitor how upcoming EU AI Act provisions on biometric surveillance classification will reshape video analytics deployment permissions across French hyperscale and edge facilities.
Market Dynamics
ANSSI certification mandates under France's NIS2 transposition are forcing hyperscale and colocation operators to upgrade perimeter defense, biometric access, and surveillance systems simultaneously, compressing procurement cycles and favoring integrated security portfolios over point solutions.
Growth Catalysts
- Hyperscale cluster expansion:Cloud service providers are scaling facility footprints across Greater Paris and Ile-de-France, driving concentrated demand for enterprise-grade physical security infrastructure.
- NIS2 compliance deadlines:France's transposition of the EU directive mandates security certification for operators of vital importance, creating procurement urgency among critical infrastructure operators.
- AI-powered video analytics:Behavior recognition systems are replacing passive monitoring in colocation facilities, enabling real-time threat detection and reducing security staffing requirements.
Market Restraints
- Specialized labor scarcity:Convergence expertise spanning cybersecurity and physical security commands premium compensation, inflating deployment costs for integrated systems.
- Component supply concentration:Advanced biometric sensors and edge AI processors depend on concentrated Asian manufacturing, exposing French integrators to lead time volatility.
- EU AI Act biometric restrictions:Pending classification of facial recognition as high-risk AI creates compliance uncertainty, delaying procurement decisions for video analytics upgrades.
Strategic Opportunities
- Edge facility security standardization:Distributed data centers outside Ile-de-France lack unified physical security protocols, creating white space for modular, pre-certified system packages.
- ADEME energy alignment:National data center efficiency regulations reward low-power standby consumption in security systems, favoring vendors with thermal-resilient product lines.
- Converged IT-OT security platforms:Integration of building management systems with physical access control enables unified threat response, appealing to multi-tenant colocation operators.
Industry Challenges
- Multi-tenant policy fragmentation:Colocation facilities must reconcile divergent security requirements across fragmented tenant bases, complicating system architecture standardization.
- Legacy access control retrofitting:Brownfield data centers face integration complexity when upgrading from card-based to biometric multi-factor authentication without operational disruption.
- Certification timeline compression:ANSSI evaluation cycles for critical infrastructure security products lag behind operator deployment deadlines, creating procurement bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Data Center Physical Security Market |
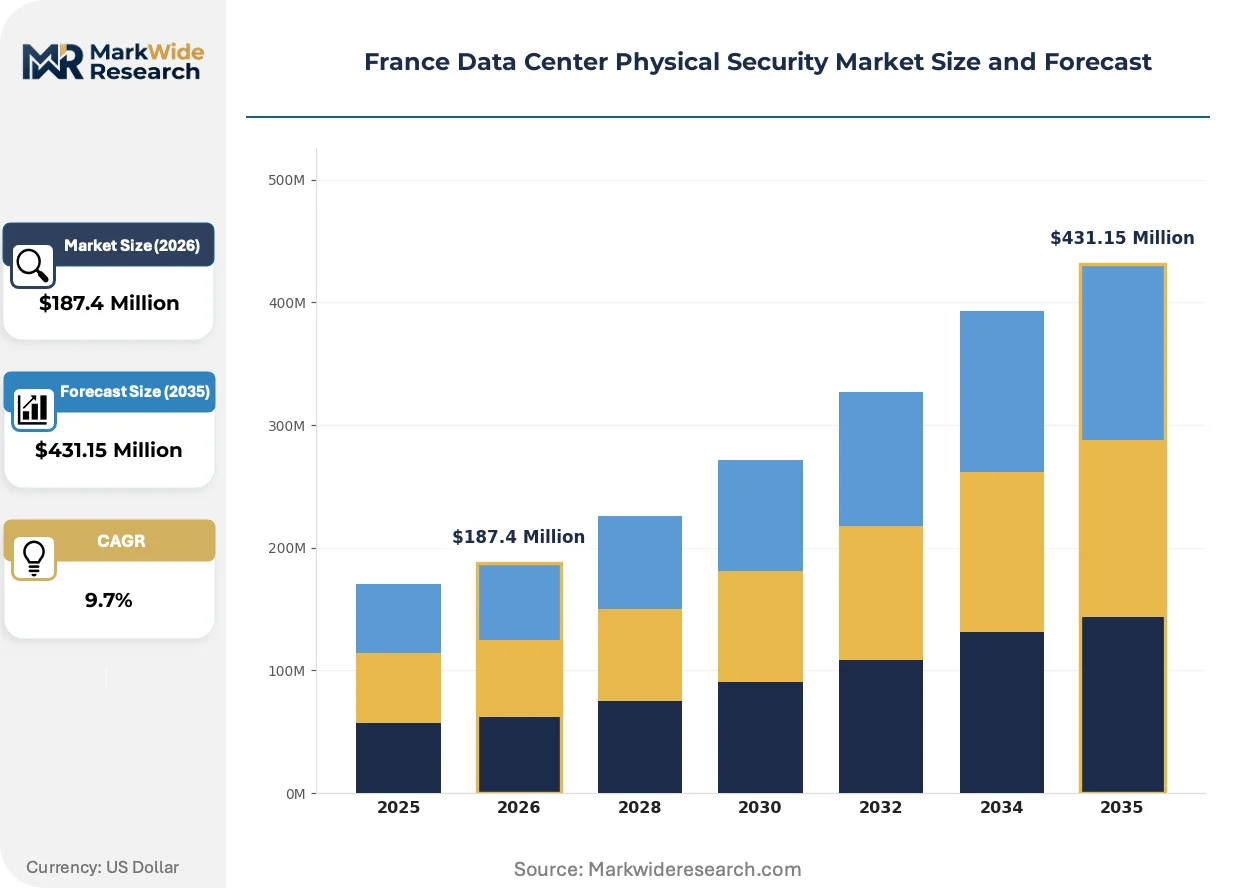
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Access Control, Surveillance Systems, Monitoring Solutions, Intrusion Detection Installation: On-Premise, Cloud-Based, Hybrid, Integrated Solutions End User: Enterprise, Government, Service Providers, Colocation Facilities Technology: Biometrics, RFID, Video Analytics, Alarm Systems |
| Companies Covered | Johnson Controls International plc, Schneider Electric SE, Axis Communications AB, Genetec Inc., Thales Group, Honeywell International, Siemens AG, Bosch Sicherheitssysteme GmbH, Securitas AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Data Center Physical Security Market Trends and Innovations
Physical security systems in French data centers are converging with IT infrastructure management, driven by regulatory pressure for unified audit trails and the operational necessity of remote facility oversight.
Multi-factor biometric authentication is miniaturizing into contactless form factors combining iris and fingerprint recognition. Hyperscale operators in Greater Paris are deploying these systems at perimeter, cage, and rack levels simultaneously. The technology is miniaturizing hardware footprints while maintaining sub-0.001% false acceptance rates, enabling denser sensor placement without structural modifications.
France's ANSSI security certification framework is tightening technical specifications for critical data center assets. Operators of vital importance must now demonstrate physical access logging integration with cybersecurity incident response systems. Government-facing contracts and financial services colocation facilities face the steepest compliance ramps, accelerating replacement of siloed security subsystems.
Colocation buyers are unbundling security system procurement from facility lease agreements. Multi-tenant operators now specify base physical security tiers while allowing enterprise tenants to overlay customized access control and surveillance configurations. This pattern concentrates in Ile-de-France hyperscale clusters, where fragmented tenant security policies previously forced expensive bespoke deployments.
France Data Center Physical Security Market Segmentation
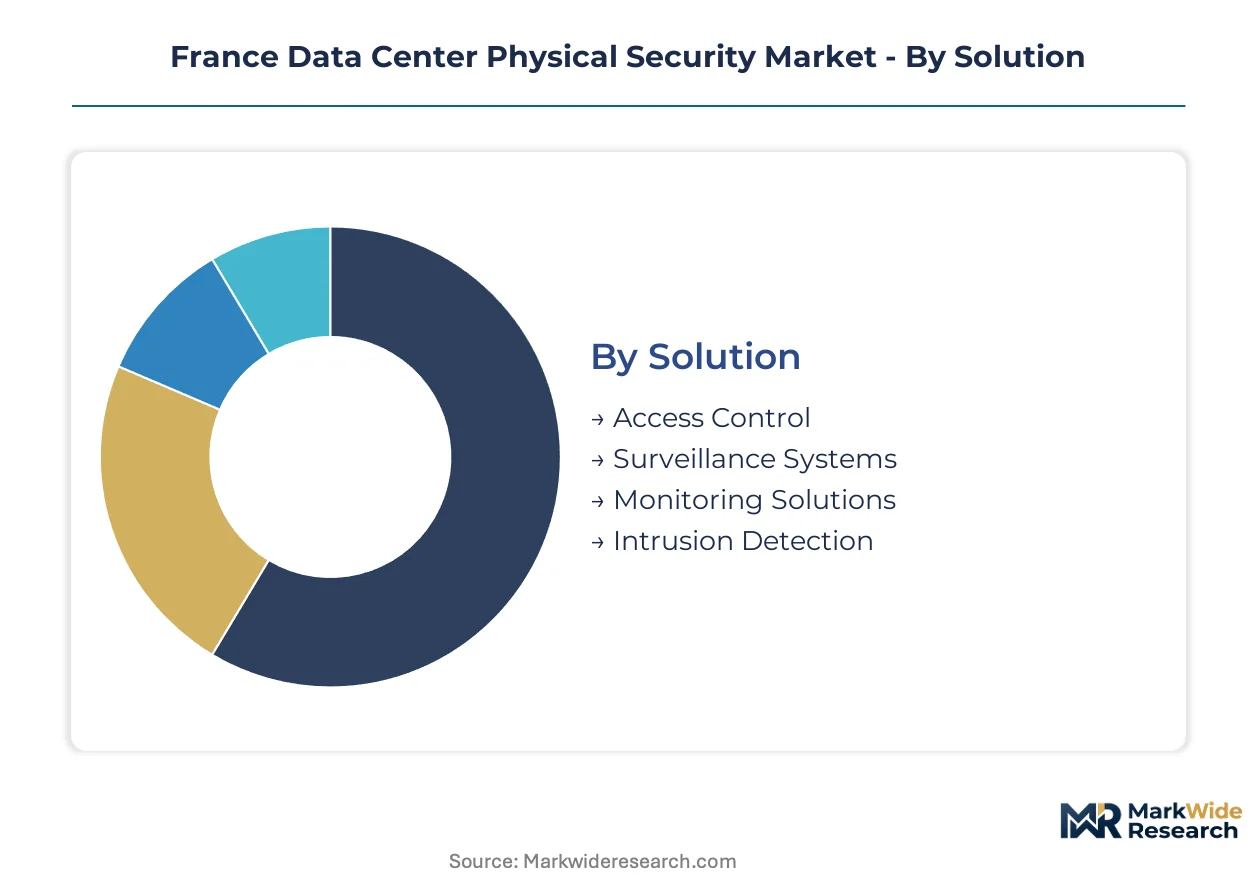
France data center physical security procurement patterns diverge sharply across solution types and installation architectures. ANSSI certification requirements and multi-tenant operational complexity create distinct margin profiles that reshape vendor prioritization.
Solution:
Access control commands the largest recurring revenue pool through credential management and firmware update subscriptions.
- Access Control:Biometric multi-factor systems with iris and fingerprint recognition achieve sub-0.001% false acceptance rates in certified deployments. Ile-de-France hyperscale clusters drive concentrated demand as operators standardize on cage-level and rack-level authentication simultaneously.
- Surveillance Systems:AI-powered video analytics with behavior recognition capabilities are displacing passive monitoring architectures. Colocation facilities in Greater Paris deploy these for real-time threat detection without proportional security staffing increases.
- Monitoring Solutions:Unified building-to-IT infrastructure platforms integrate environmental sensors with security incident logging.
- Intrusion Detection:Perimeter defense systems with thermal imaging and ground vibration sensors protect brownfield facility expansions.
Access control holds installed capacity. Video analytics is rotating up the share rankings.
Installation:
Cloud-based architectures concentrate in new-build hyperscale facilities seeking remote oversight capabilities.
- Cloud-Based:Centralized security management platforms enable multi-site policy orchestration from single control planes. Service providers expanding across Greater Paris favor these for standardized tenant onboarding.
- Hybrid:Local edge processing with cloud backup balances latency requirements against disaster recovery needs. Colocation operators deploy hybrid models to accommodate fragmented tenant data sovereignty requirements.
- On-Premise:Air-gapped systems remain mandatory for government-facing contracts under ANSSI critical infrastructure mandates.
- Integrated Solutions:Converged IT-OT security platforms unify building management with physical access control.
On-premise systems anchor government compliance. Hybrid installations are climbing the fastest.
End User:
Colocation facilities generate the steepest procurement velocity as multi-tenant complexity forces security infrastructure refresh cycles.
- Colocation Facilities:Multi-tenant operators unbundle base security tiers from customized tenant overlays. Ile-de-France hyperscale clusters standardize on modular architectures permitting rapid reconfiguration between fragmented client policies.
- Enterprise:Financial services and healthcare operators mandate defense-grade encryption integration with physical access logging. ANSSI certification timelines compress procurement decisions for critical infrastructure designations.
- Government:Defense and intelligence facilities require biometric systems with sovereign data processing guarantees.
- Service Providers:Cloud operators expanding edge footprints outside Ile-de-France seek pre-certified modular packages.
Enterprise holds legacy deployment scale. Colocation facilities are gaining share fastest.
Technology:
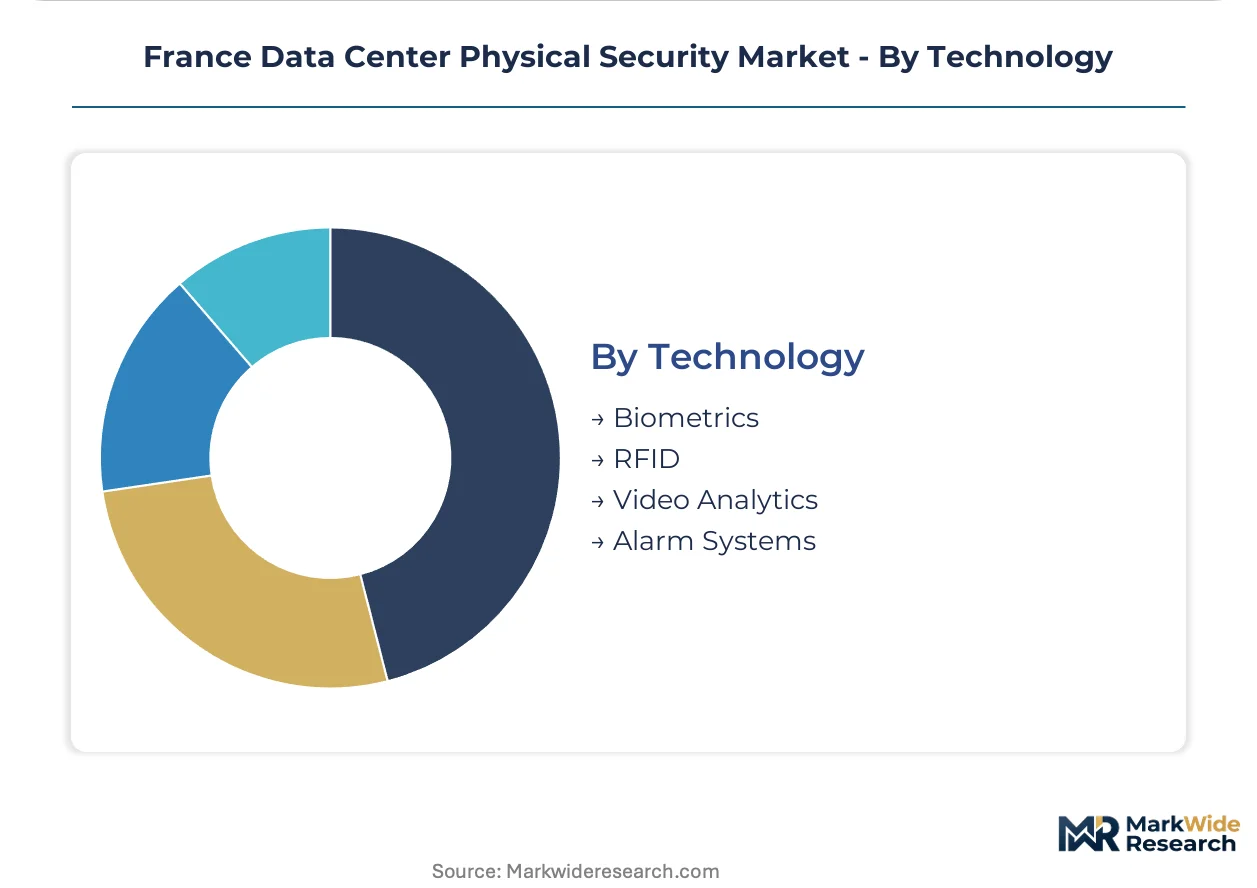
Biometric authentication captures premium pricing through defense-grade certification requirements and false acceptance rate specifications.
- Biometrics:Contactless iris and fingerprint recognition systems miniaturize hardware footprints without structural modifications. Greater Paris hyperscale deployments place sensors at perimeter, cage, and rack levels simultaneously.
- Video Analytics:AI-powered behavior recognition enables automated threat classification with reduced security operations center staffing. EU AI Act biometric surveillance classification uncertainty delays some procurement decisions.
- RFID:Legacy card-based systems persist in brownfield facilities facing operational disruption risks from authentication upgrades.
- Alarm Systems:Integrated intrusion alerts feed directly into cybersecurity incident response platforms under ANSSI logging mandates.
RFID retains brownfield installed base. Video analytics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ile-de-France consumes physical security infrastructure differently from France's peripheral regions, concentrating hyperscale demand in a tight radius while edge facilities elsewhere rely on modular pre-certified packages. Regional procurement patterns diverge sharply between the capital's multi-tenant complexity and smaller metros' standardized deployments. ANSSI certification timelines compress decisions in critical infrastructure zones while leaving secondary markets with longer evaluation cycles.
Ile-de-France
Hyperscale clusters in Greater Paris drive concentrated demand for cage-level and rack-level biometric authentication simultaneously. ANSSI security certification mandates under NIS2 transposition force operators of vital importance to upgrade perimeter defense and surveillance systems on compressed procurement cycles. Cloud service providers expanding facility footprints across Saint-Denis, Magny-les-Hameaux, and Saclay anchor the national market volume.
Auvergne-Rhône-Alpes
Enterprise data centers in Lyon and Grenoble prioritize defense-grade encryption integration with physical access logging for financial services operators. The region's cybersecurity research ecosystem, anchored by INRIA and local engineering schools, feeds specialized talent into converged IT-OT security platform development. Modular pre-certified security packages gain traction among mid-sized colocation operators serving fragmented manufacturing tenant bases.
Provence-Alpes-Côte d'Azur
Marseille's emerging submarine cable landing stations and edge facilities create demand for thermal-resilient perimeter defense systems aligned with ADEME energy efficiency regulations. The port city's strategic position in Mediterranean data traffic routes attracts service providers seeking standardized security architectures for distributed footprints. Local operators face longer ANSSI certification timelines than Ile-de-France counterparts, delaying some procurement decisions.
Hauts-de-France
Lille's proximity to Benelux markets positions brownfield facility retrofits as a distinct demand segment, with legacy card-based access control systems facing operational disruption risks during biometric upgrades. Regional colocation operators unbundle base security tiers from customized tenant overlays less frequently than Parisian competitors. The area's industrial heritage leaves fewer hyperscale developments, concentrating demand in enterprise and mid-market service provider segments.
Occitanie
Toulouse's aerospace and defense industrial base sustains demand for air-gapped, on-premise security systems mandatory under government-facing contracts. The region's smaller data center footprint relies more heavily on hybrid installation architectures balancing local edge processing against cloud backup for disaster recovery. Edge facility security standardization remains underdeveloped, creating white space for vendors offering pre-certified modular packages.
France Data Center Physical Security Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-stack building-to-IT infrastructure portfolios commanding premium positioning in large enterprise deployments. Defense-grade encryption and biometric access specialists occupy a distinct premium tier serving government-facing contracts and financial services colocation facilities. Three archetypes define competitive positioning: integrated infrastructure conglomerates with converged security offerings, defense-technology spinoffs leveraging sovereign certification advantages, and pure-play physical security vendors competing on modular scalability. M&A activity concentrates on biometric sensor capabilities and cloud-native security management platforms, while strategic partnerships between hardware manufacturers and systems integrators accelerate ANSSI certification timelines for critical infrastructure deployments.
Within the integrated infrastructure tier, Schneider Electric SE anchors large enterprise deployments through its building-to-IT convergence capabilities, while Thales Group exemplifies defense-grade positioning with sovereign biometric systems for operators of vital importance. Axis Communications AB represents the specialist archetype competing on modular video analytics scalability across multi-tenant environments. Johnson Controls International plc and Honeywell International occupy positions bridging commercial building automation with data center-specific security requirements, while Genetec Inc. and Bosch Sicherheitssysteme GmbH sit within the open-platform software and European hardware fabrication tiers respectively. Siemens AG and Securitas AB round out the competitive map across industrial automation integration and manned guarding service augmentation.
| Leading Market Players |
|---|
| Johnson Controls International plc |
| Schneider Electric SE |
| Axis Communications AB |
| Genetec Inc. |
| Thales Group |
| Honeywell International |
| Siemens AG |
| Bosch Sicherheitssysteme GmbH |
| Securitas AB |
| Others |
Pricing and Supply Chain Analysis
Cloud-native security management platforms replacing on-premise access control systems are redrawing supplier geography toward software-centric vendors while compressing hardware margins and elevating recurring revenue pricing power for integrated portfolios.
Pricing Analysis
Long-term subscription contracts with tiered SaaS pricing dominate procurement as colocation operators seek predictable security operations expenditure. Three-tier pricing structure across premium defense-grade, standard enterprise, and economy modular levels reflects ANSSI certification tier and biometric sensor density. Pricing pressure stems from Asian component cost volatility inflating hardware bill-of-materials. Enterprise financial services buyers exhibit lowest price sensitivity due to regulatory compliance mandates, while edge facility operators in secondary French regions negotiate hardest on upfront capital expenditure.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Le Havre container terminals expose French integrators to trans-Eurasian shipping lane congestion and semiconductor lead time volatility. Advanced biometric sensors and edge AI processors draw from concentrated manufacturing in Taiwan, South Korea, and mainland China. Single-source vulnerability in CMOS image sensor supply creates procurement bottlenecks for video analytics deployments. Distribution runs through certified systems integrators with ANSSI accreditation rather than direct vendor-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against modular pre-certified security packages threatening to commoditize integrated system value, as edge facility operators prioritize rapid deployment over bespoke engineering.
For Market Incumbents: Fortify ANSSI certification pipelines to compress evaluation cycles and lock out point-solution competitors. Deepen backward integration into biometric sensor firmware to capture margin pool migrating from hardware to software layers. Anchor multi-year service contracts with hyperscale operators in Ile-de-France before modular vendors establish beachheads in secondary regions.
For New Entrants and Emerging Players: Converged IT-OT security platform integration represents the most penetrable service layer where Schneider Electric and Thales Group leave mid-market colocation operators underserved. Target Occitanie and Hauts-de-France edge facilities with pre-certified modular packages that bypass lengthy ANSSI timelines. Lead with cloud-native deployment models that unbundle security procurement from facility construction contracts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European physical security specialists holding ANSSI certifications but lacking hyperscale customer concentration. Five-to-ten year viability hinges on software recurring revenue ratios overtaking hardware transaction exposure. Monitor EU AI Act biometric surveillance classification rulings as the critical inflection signal for video analytics valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| ANSSI Certification Fast-Track Investment | Compresses evaluation cycles for critical infrastructure operators under NIS2 mandates. |
| Biometric Sensor Firmware Acquisition | Captures recurring credential management revenue migrating from hardware sales. |
| Cloud-Native Security Platform Launch | Enables multi-site policy orchestration for hyperscale operators across Greater Paris. |
| Edge Facility Modular Package Rollout | Addresses standardization gaps in Occitanie and Hauts-de-France secondary markets. |
| IT-OT Convergence Partnership | Unifies building management with physical access control for colocation tenant complexity. |
Research Methodology
Initial hypotheses were tested against primary input from data center security directors, ANSSI certification officers, colocation facility operators, and systems integration engineers and refined through secondary validation against ADEME energy efficiency filings, ANSSI critical infrastructure registries, hyperscaler capex disclosures, and customs import records for biometric sensor trade flows. Bottom-up facility deployment tallies triangulated against top-down security system procurement estimates.
Variance decomposition across solution type, installation architecture, end-user segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate synthesis incorporating NIS2 compliance deadline phasing, hyperscale cluster construction pipelines, and biometric technology substitution curves. Forecast inputs included ANSSI certification queue lengths and ADEME thermal resilience compliance thresholds.
Underlying assumptions cover NIS2 transposition timing adherence, EU AI Act biometric classification stability, and Taiwan semiconductor supply continuity, with deviation risk concentrated in regulatory interpretation shifts and geopolitical logistics disruption. Practitioners should keep alternative scenarios live as ANSSI evaluation capacity and EU AI Act enforcement guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Security Guard Market
Physical Security
Body Armor Plates Market
Physical Security
Europe Physical Security Market
Physical Security
Global Wearable Security Device Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
North America Physical Security Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Body Armor Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Tactical Vests Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Security Market
Physical Security
Canada Data Center Physical Security Market
Physical Security
Europe Cargo Inspection Market