
 Tactical Vests Market | 2026-2036
Tactical Vests Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Vests Market Analytics
Multi-source procurement is expanding across defense ministries and federal law enforcement agencies as buyers diversify supplier bases beyond sole-source legacy contracts. Point Blank Enterprises leverages domestic manufacturing scale to anchor U.S. military contracts. BAE Systems competes through integrated systems engineering that extends beyond standalone vests into full soldier protection suites. Safariland differentiates via channel control across law enforcement distribution networks.
A tactical vest is a load-bearing garment engineered to carry ballistic plates, ammunition, communications equipment, and mission-essential gear, typically constructed from high-denier nylon or Cordura with MOLLE webbing for modular attachment. Plate carrier configurations dominate military procurement due to their adaptability across threat levels, while Kevlar-reinforced soft armor sustains law enforcement demand where concealability and daily wear comfort govern purchasing decisions. Load bearing vests without ballistic integration occupy the outdoor enthusiast and airsoft segments, where price sensitivity limits margin expansion compared to professional end users.
The U.S. NIJ sets ballistic resistance benchmarks that shape product certification requirements and market access for domestic suppliers, while NATO STANAG agreements create interoperability pressures for cross-border military procurement. The EU AI Act and CE marking frameworks under the Personal Protective Equipment Regulation govern European law enforcement and security personnel acquisitions. Buyers must monitor evolving NIJ standard revisions and STANAG harmonization timelines to align R&D roadmaps with compliance windows.
Market Dynamics
Modular plate carrier architectures are compressing procurement cycles as NATO militaries consolidate around interoperable load-bearing standards, forcing legacy soft armor suppliers to reengineer attachment systems or exit military contracts entirely.
Growth Catalysts
- NIJ Standard 0101.07:The updated U.S. ballistic resistance framework mandates multi-hit performance against rifle threats, compelling law enforcement agencies to refresh soft armor inventories ahead of compliance deadlines.
- Polyethylene composite plates:Ultra-high molecular weight polyethylene is displacing ceramic strike faces in maritime and airborne units where weight reduction governs operational endurance.
- NATO STANAG 4170:Harmonized fragmentation protection requirements across allied defense ministries are standardizing procurement specifications and expanding addressable contract pools for certified suppliers.
Market Restraints
- Aramid fiber concentration:DuPont and Teijin control over 70% of para-aramid global supply, exposing vest manufacturers to input cost volatility and allocation rationing during defense procurement surges.
- Ballistic testing infrastructure scarcity:Only 12 NIJ-certified laboratories operate in the United States, creating 14-18 month backlogs for new product validation and delaying market entry.
- Concealable soft armor substitution:External plate carriers are displacing under-uniform vests in federal law enforcement, collapsing the premium tier of the traditional concealable market.
Strategic Opportunities
- EU Personal Protective Equipment Regulation:CE marking mandates for private security contractors create a compliance-driven replacement cycle across Germany, France, and Poland worth an estimated 340,000 unit refreshes annually.
- Integrated power distribution:Convergence of textile-embedded conductive yarns with lithium-polymer cells enables vest-mounted soldier power networks, opening adjacent revenue in cable management and thermal regulation subsystems.
- Direct-to-unit digital channels:Specialized operators in U.S. Special Operations Command and British Special Forces are bypassing defense logistics agencies via manufacturer portals, compressing order-to-field timelines from 18 months to 90 days.
Industry Challenges
- Pattern-making and graded sizing:Female-specific ballistic protection requires anthropometric databases that most military contractors lack, forcing expensive custom fitting or abandonment of female personnel contracts.
- Multi-standard certification stacking:Vendors targeting both U.S. DoD and European defense ministries must simultaneously satisfy NIJ, STANAG, and CE marking protocols, tripling documentation burdens and test matrix costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Vests Market |
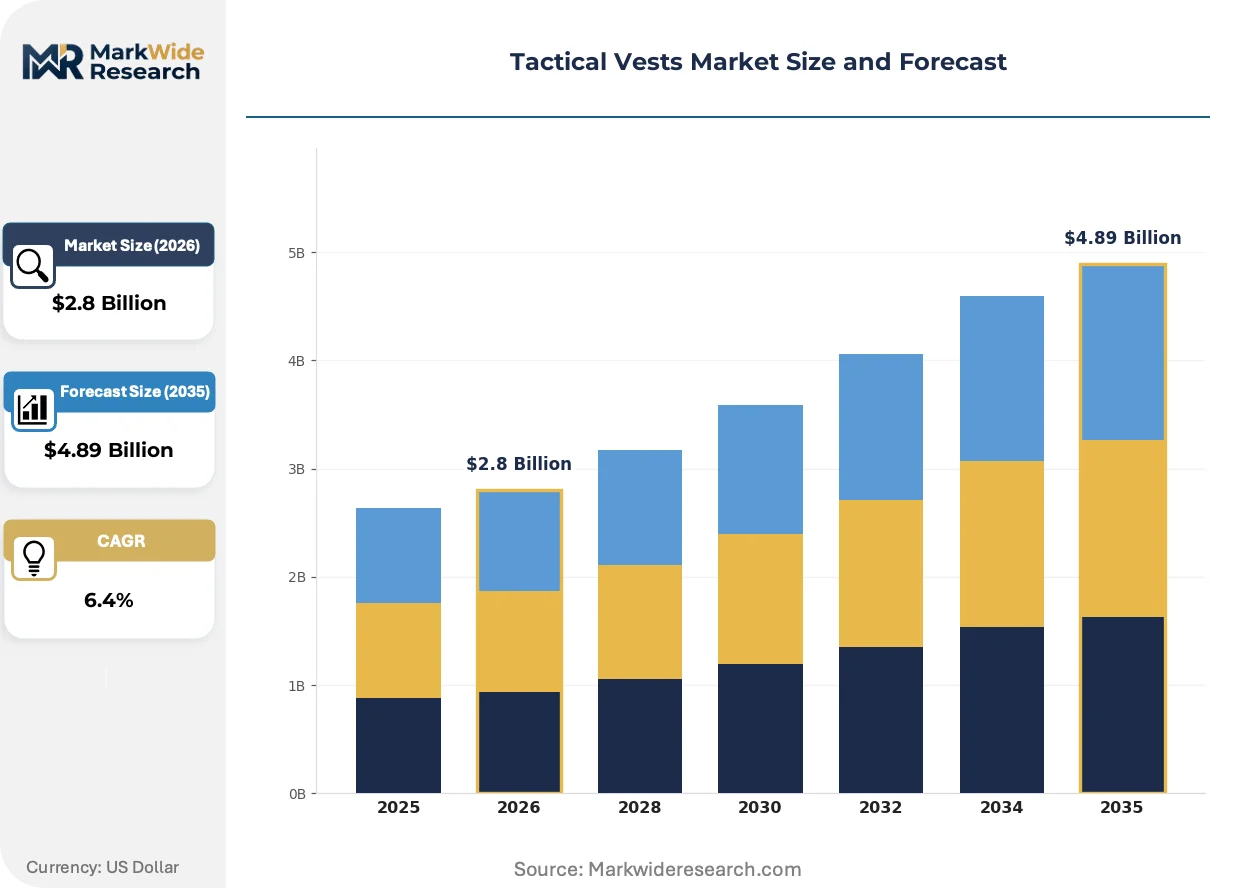
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plate Carrier, Modular Vest, Load Bearing Vest, Enhanced Tactical Vest Material: Nylon, Polyester, Cordura, Kevlar End User: Military, Law Enforcement, Security Personnel, Outdoor Enthusiasts Application: Tactical Operations, Safety Training, Outdoor Activities, Airsoft Games |
| Companies Covered | Point Blank Enterprises, BAE Systems, Safariland, 5.11 Tactical, Blackhawk, Condor Outdoor Products, Armor Express, MKU, Tactical Assault Gear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Vests Market Evolving Landscape
Active research into non-Newtonian shear-thickening fluids is compressing the performance gap between soft and hard armor, while digital manufacturing techniques are collapsing lead times for custom-fit systems.
Shear-thickening fluid (STF) treated fabrics are consolidating the intermediate threat protection segment by delivering stab and spike resistance without rigid plate insertion. U.S. federal prison systems and European riot control units are adopting STF-reinforced vests at triple-digit annual growth rates. This material convergence is compressing demand for standalone chainmail and ceramic composite overlays in corrections and public order applications.
The EU AI Act's risk classification framework is reshaping procurement documentation for smart textile-integrated vests that embed biometric monitoring. Manufacturers must now submit conformity assessments for algorithmic decision-making in casualty detection systems, adding 8-12 months to product development timelines. French and German interior ministries are delaying next-generation soldier modernization awards until vendor compliance pathways clarify.
Unit-level configuration autonomy is fragmenting traditional bulk procurement as squad leaders specify mission-specific pouch layouts and plate cut geometries. U.S. Army Security Force Assistance Brigades and British Army Ranger Regiment are procuring vests through unit discretionary funds rather than centralized PEO Soldier contracts. This decentralization is most visible in special operations and advisory force structures where rapid equipment iteration governs operational effectiveness.
Tactical Vests Market Segmentation
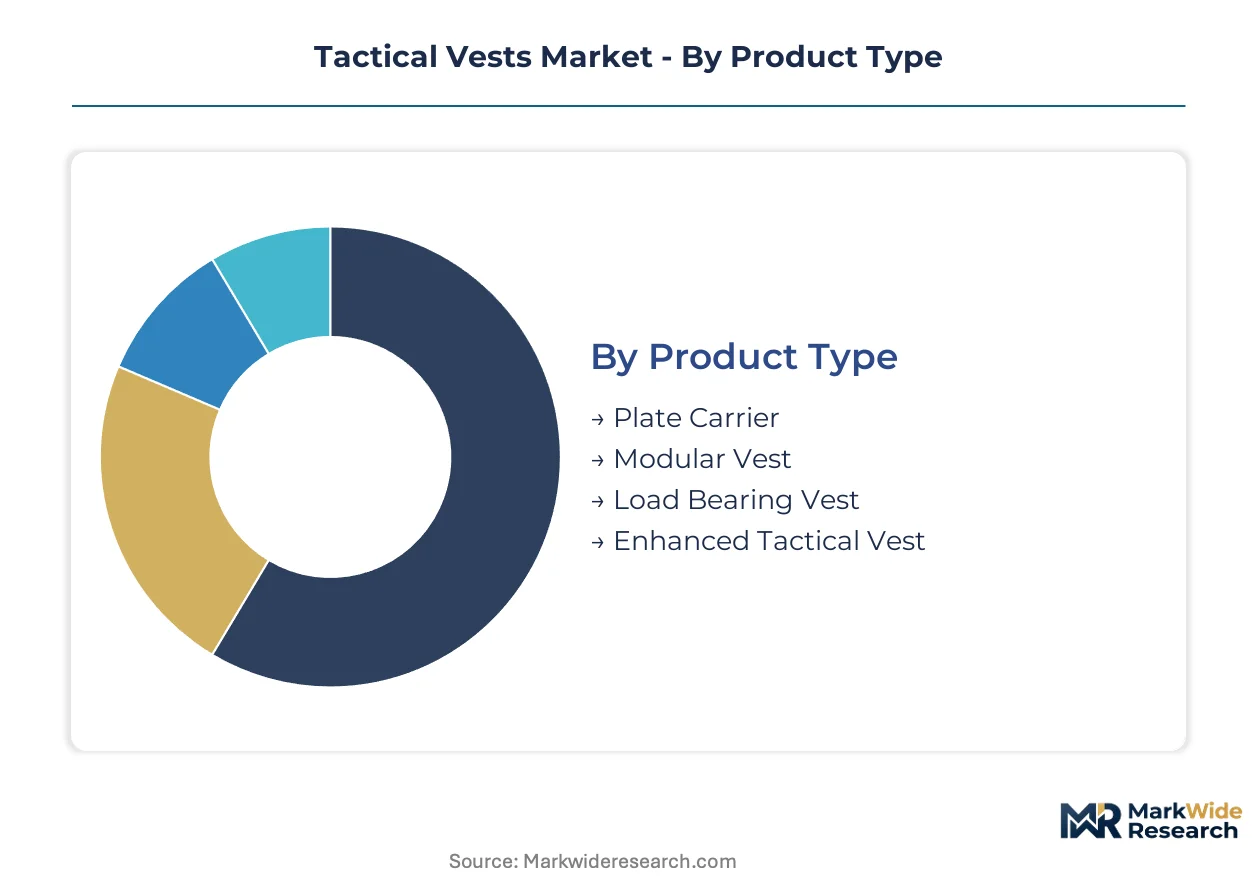
Segmentation in tactical vests reveals how procurement specifications diverge across threat environments, operational tempo, and budget authority. Military buyers prioritize modularity and ballistic integration, while commercial segments trade protection for weight and cost.
Product Type:
The customization-vs-standardization spectrum runs from mission-configurable plate carriers to fixed-configuration load bearing systems with no ballistic capability.
- Plate Carrier:Minimalist chassis accepting hard armor plates with MOLLE attachment points for scalable loadout. U.S. Army Security Force Assistance Brigades and British Army Ranger Regiment procurement through unit discretionary funds is compressing order cycles from 18 months to 90 days.
- Modular Vest:Soft armor foundation with removable plate pockets and configurable pouch geometry. NATO STANAG 4170 harmonization is standardizing fragmentation protection specifications across allied defense ministries, expanding contract pools for certified suppliers.
- Load Bearing Vest:Non-ballistic chassis designed strictly for equipment carriage. Outdoor enthusiast and airsoft demand concentrates here, where price sensitivity constrains margin expansion versus professional end users.
- Enhanced Tactical Vest:Integrated soft armor with fixed pouch layouts and side closure systems. Legacy corrections and static security posts maintain this configuration where mobility requirements remain secondary.
Leading the category by volume: Plate Carrier. Growing fastest: Modular Vest.
Material:
Cost tier stratification separates premium aramid and UHMWPE composites from commodity synthetics in non-ballistic applications.
- Nylon:High-denier woven base fabric for MOLLE webbing and chassis construction. Military specifications demand 500D-1000D ratings with IRR coatings for signature management.
- Polyester:Lower-cost alternative dominating commercial and training markets where abrasion resistance requirements moderate.
- Cordura:Solution-dyed nylon 6,6 with enhanced tear strength. U.S. DoD ground combat contracts specify Cordura for plate carrier exteriors exposed to rough terrain.
- Kevlar:Para-aramid fiber for soft armor panel construction. DuPont and Teijin control over 70% of global supply, exposing vest manufacturers to input cost volatility during defense procurement surges.
Dominating procurement value: Kevlar. Expanding most quickly: Cordura.
End User:
Customer type determines certification burden, with military and federal law enforcement requiring NIJ or STANAG validation versus self-certified commercial sales.
- Military:Plate carrier architectures with scalable protection against rifle threats. U.S. Department of Defense spending on soldier modernization programs anchors volume in this segment.
- Law Enforcement:Concealable soft armor for daily patrol wear and external plate carriers for tactical teams. NIJ Standard 0101.07 multi-hit rifle threat mandates are compelling inventory refreshes ahead of compliance deadlines.
- Security Personnel:CE marking requirements under EU Personal Protective Equipment Regulation govern private contractor acquisitions across Germany, France, and Poland.
- Outdoor Enthusiasts:Replica and functional load bearing equipment for recreational use. Price elasticity here limits supplier margin compared to institutional procurement.
Commanding revenue concentration: Military. Gaining share fastest: Security Personnel.
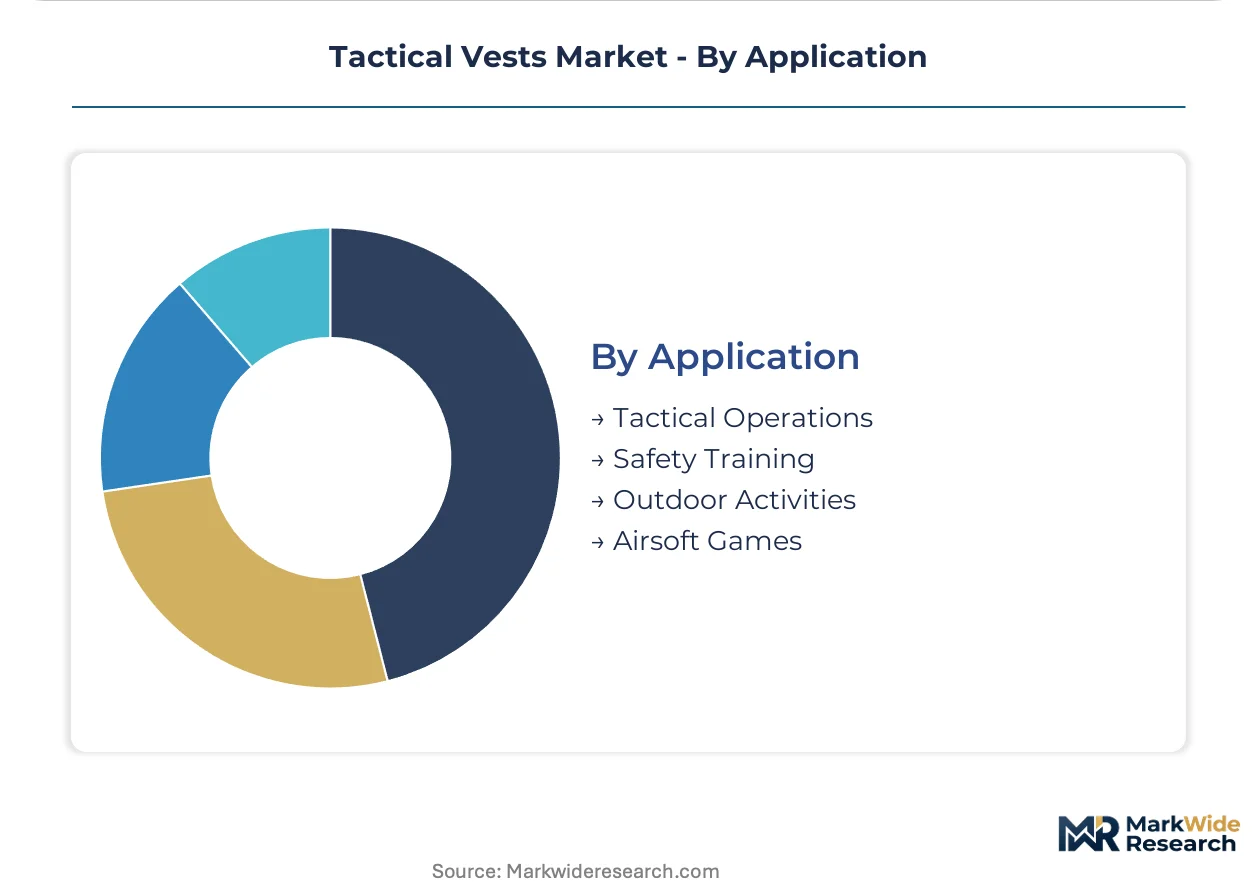
Application:
Maturity gradients separate established tactical operations demand from emerging airsoft and training segments with shorter product lifecycles.
- Tactical Operations:Combat, counter-terrorism, and high-risk warrant service requiring certified ballistic protection. Shear-thickening fluid treated fabrics are consolidating intermediate threat protection without rigid plate insertion.
- Safety Training:Force-on-force and live-fire exercise equipment. U.S. federal prison systems and European riot control units are adopting STF-reinforced vests at accelerated rates.
- Outdoor Activities:Hunting, hiking, and adventure sports using vest platforms for equipment carriage. Non-ballistic load bearing configurations dominate.
- Airsoft Games:Replica tactical gear for competitive simulation. Aesthetic fidelity to military originals drives purchasing decisions over functional specifications.
Highest specification requirements: Tactical Operations. Steepest expansion trajectory: Airsoft Games.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Para-aramid fiber production clusters in the southeastern United States anchor raw material availability for ballistic panel manufacturing. DuPont's Kevlar facilities in Virginia and Teijin's Twaron operations in South Carolina feed domestic plate carrier assembly lines. This feedstock geography shapes procurement patterns across NATO defense ministries and federal law enforcement agencies.
United States
Department of Defense soldier modernization programs drive plate carrier volume through PEO Soldier and Special Operations Command channels. NIJ Standard 0101.07 compliance deadlines are accelerating soft armor refreshes across federal law enforcement agencies. Manufacturing concentrates in Florida and North Carolina, where Point Blank Enterprises and Safariland operate vertically integrated assembly facilities serving military and police contracts.
Germany
Bundeswehr procurement through BAAINBw is consolidating fragmentation protection specifications under STANAG 4170 harmonization pressures. EU Personal Protective Equipment Regulation CE marking mandates govern private security contractor acquisitions across Berlin and Frankfurt security corridors. Industrial activity clusters in North Rhine-Westphalia, where Rheinmetall and regional textile manufacturers coordinate on soldier system integration.
France
Direction Générale de l'Armement is delaying next-generation soldier modernization awards pending EU AI Act compliance clarity for biometric-integrated vests. Interior ministry procurement for Gendarmerie and Police Nationale riot control units is adopting shear-thickening fluid reinforced configurations. Production and testing infrastructure concentrates in the Île-de-France region around Paris-Saclay defense research clusters.
United Kingdom
British Army Ranger Regiment and Special Forces procurement through unit discretionary funds is compressing order-to-field timelines from 18 months to 90 days. Ministry of Defence Defence Equipment and Support is standardizing plate carrier architectures across infantry and advisory force structures. Manufacturing and system integration activity centers in the Midlands and South East England defense corridors.
Poland
Ministry of National Defence procurement surges are driving NATO eastern flank equipment modernization ahead of STANAG interoperability deadlines. Private security contractor market expansion under EU PPE Regulation is creating CE marking-driven replacement demand estimated at substantial annual unit volume. Industrial development concentrates in the Łódź and Warsaw metropolitan areas with emerging textile-defense manufacturing linkages.
Tactical Vests Market Competitive Landscape
Global majors compete with regional champions across certification and channel access dimensions. Market structure shows moderate consolidation around defense primes with integrated soldier system capabilities, alongside specialized ballistic protection pure-plays and commercial tactical gear suppliers. Three archetypes dominate: vertically integrated defense contractors controlling full protection suites, soft armor specialists leveraging NIJ certification infrastructure, and commercial brands serving law enforcement and enthusiast channels through distribution partnerships. Competitive dynamics center on M&A activity consolidating testing laboratory access and strategic partnerships embedding power distribution and smart textile subsystems into vest platforms.
Within the defense prime tier, BAE Systems exemplifies integrated systems engineering extending beyond standalone vests into full soldier protection suites. Among U.S.-based specialists, Point Blank Enterprises occupies a position anchored in domestic manufacturing scale for military contract capture, while Safariland represents channel control archetypes across law enforcement distribution networks. These three companies illustrate the competitive spectrum from system-level integration to certification-driven specialization and retail channel dominance.
| Leading Market Players |
|---|
| Point Blank Enterprises |
| BAE Systems |
| Safariland |
| 5.11 Tactical |
| Blackhawk |
| Condor Outdoor Products |
| Armor Express |
| MKU |
| Tactical Assault Gear |
| Others |
Value Network & Pricing Analysis
Para-aramid fiber spot prices and UHMWPE resin indices cascade through three distinct pricing tiers as raw material volatility concentrates cost pressure on soft armor panel manufacturers serving federal law enforcement.
Pricing Analysis
Warranty bundling separates military contract pricing from commercial tiers, with NIJ-certified plate carriers commanding premium positioning through multi-year ballistic performance guarantees while airsoft replicas trade without after-sales support. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with law enforcement agencies facing cost compression as polyethylene composite plates displace ceramic alternatives. Price erosion runs through the outdoor enthusiast segment where unbranded load bearing vests compete on aesthetic fidelity alone. Federal procurement offices exhibit lowest price sensitivity due to soldier modernization program mandates, while private security contractors in EU member states navigate CE marking compliance costs that elevate total cost of ownership.
Supply Chain Analysis
NIJ laboratory certification gating restricts upstream supplier qualification to twelve approved testing facilities in the United States, creating validation bottlenecks that propagate through tier-one vest assemblers. Manufacturing concentrates in the United States, Germany, and Poland, with para-aramid fiber production anchored in Virginia and South Carolina feeding domestic plate carrier assembly. Raw material dependencies center on DuPont Kevlar, Teijin Twaron, and ultra-high molecular weight polyethylene resin imports. Single-source vulnerability in aramid fiber supply exposes assemblers to allocation rationing during defense procurement surges. Distribution runs through defense logistics agencies for military contracts, direct manufacturer portals for special operations units, and law enforcement distributor networks for police departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tactical vests market sits in a material-transition phase as shear-thickening fluid treated fabrics replace legacy ceramic and chainmail configurations in corrections and riot control applications.
For Market Incumbents: Lock in testing laboratory capacity through exclusive partnerships with NIJ-certified facilities to defend against 14-18 month validation backlogs threatening new product launches. Deepen backward integration into UHMWPE resin compounding or para-aramid weaving to offset DuPont-Teijin supply concentration. Prioritize female-specific anthropometric database development to capture Bundeswehr and Pentagon contracts abandoning suppliers lacking graded sizing capabilities.
For New Entrants and Emerging Players: Private security contractors in Poland, Germany, and France represent the most penetrable buyer archetype as EU Personal Protective Equipment Regulation CE marking mandates drive 340,000 annual unit refreshes. Target direct-to-unit digital channels serving British Special Forces and U.S. Army Security Force Assistance Brigades bypassing traditional defense procurement timelines. Establish STANAG 4170 certification as the primary go-to-market credential for NATO interoperability contracts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor soft armor specialists with captive NIJ laboratory relationships in the United States as validation scarcity intensifies competitive moats. Long-term viability hinges on convergence plays integrating power distribution and biometric monitoring subsystems into vest platforms. Watch EU AI Act conformity assessment timelines as the critical inflection signal for French and German interior ministry award resumption.
| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Laboratory Capacity Expansion | Secures validation throughput for STANAG 4170 dual-certification products targeting NATO procurement pools. |
| Shear-Thickening Fluid Integration | Captures corrections and riot control demand as STF fabrics displace ceramic overlays in intermediate threat protection. |
| Direct-to-Unit Digital Channel Buildout | Compresses order-to-field timelines from defense logistics agency cycles to 90-day special operations procurement windows. |
| Female-Specific Anthropometric Database Development | Unlocks Pentagon and Bundeswehr contracts abandoning suppliers lacking graded sizing for female personnel. |
| EU AI Act Compliance Pathway Investment | Positions for French Direction Générale de l'Armement and German BAAINBw biometric-vest awards pending regulatory clarity. |
Research Methodology
Defense procurement databases, NIJ compliance registries, and NATO standardization agreements formed the secondary backbone, cross-referenced with primary interviews spanning PEO Soldier program officers, Bundeswehr BAAINBw procurement leads, private security contractor equipment managers, and NIJ-certified laboratory directors. Bottom-up unit demand estimates across plate carrier, modular vest, and load bearing configurations triangulated against top-down defense budget allocation analysis.
Historical trendline analysis of Department of Defense soldier modernization spending, EU interior ministry procurement awards, and para-aramid fiber production capacity informed projection modeling across the analysis window. Segmentation dimensions included product architecture, material composition, end-user certification tier, and regional regulatory framework. CAGRs derived from weighted average of defense budget growth trajectories, equipment refresh cycle compression, and material substitution elasticity in maritime and airborne units.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NIJ standard revision timing, STANAG harmonization delays, and aramid fiber supply allocation disruptions. Forecasts reflect documented assumptions regarding defense procurement continuity and regulatory compliance pathway stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Poland Data Center Physical Security Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Security Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Bulletproof Glass Market
Physical Security
Security Guard Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Policing Technologies Market
Physical Security
Border Security Technologies Market
Physical Security
Airport Full Body Scanner Market
Physical Security
North America Physical Security Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Global Wearable Security Device Market