
 Tactical Lights Market | 2026-2036
Tactical Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Lights Market Insights
Outdoor sports and civilian preparedness is repositioning demand within the tactical lights landscape. SureFire leverages its heritage in military contracts to sustain premium positioning across weapon-mounted categories. Streamlight competes aggressively on value-engineered handheld units for law enforcement agencies. Nitecore anchors its growth on compact rechargeable head-mounted systems popular among search and rescue professionals.
Tactical lights are portable illumination devices engineered to deliver high-intensity output, typically exceeding 500 lumens, with durable aluminum or polymer housings rated for impact resistance and waterproof operation. These devices serve critical functions in low-visibility combat, law enforcement engagement, and emergency response scenarios where reliability determines operational outcomes. Weapon-mounted configurations currently lead procurement volumes among defense forces, while LED technology dominates the technology mix due to superior energy efficiency and thermal management. Handheld units retain the largest installed base across police departments, though helmet-mounted systems represent the fastest-growing configuration as integrated night-operation suites expand.
The U.S. Department of Defense and NATO standardization agreements shape product specifications for military-grade tactical lights, while the EU RoHS directive and CE marking requirements constrain material choices and electronics design for European market access. The Federal Communications Commission regulates radio-enabled smart lighting features emerging in premium tactical product lines. Stakeholders must monitor evolving energy-efficiency mandates and battery chemistry regulations that will determine next-generation product qualification timelines and geographic market eligibility.
Market Dynamics
Weapon-mounted LED systems are displacing legacy incandescent and halogen configurations across military and law enforcement procurement channels, driven by NATO standardization agreements mandating compatibility with night-vision equipment and the EU RoHS directive's hazardous substance restrictions on legacy battery chemistries.
Growth Catalysts
- Defense Modernization Budgets:The United States Department of Defense prioritizes night-operation capabilities in special operations and infantry units, accelerating procurement cycles for helmet-mounted illumination suites.
- RoHS Directive Compliance:The EU's restriction of hazardous substances in electrical equipment mandates LED transitions, eliminating mercury-based and cadmium-containing alternatives from European supply chains.
- Polymer Housing Advances:Impact-resistant polymer composites now achieve aluminum-grade durability at reduced weight, expanding adoption among search and rescue professionals requiring extended wearability.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in East Asian manufacturing clusters, creating vulnerability to export control disruptions and raw material price volatility.
- REACH Chemical Registration Burden:The EU's chemicals regulation imposes costly substance registration requirements on specialty electrolytes and thermal interface materials used in high-output LED drivers.
- Thermal Management Ceiling:Passive cooling limits sustained output in compact form factors below 1000 lumens, constraining performance scaling for handheld duty lights.
Strategic Opportunities
- Australian Defense Expansion:The Australian Defence Force's accelerated procurement timelines for special operations equipment create immediate demand for weapon-mounted systems compatible with EF88 rifles.
- Smart Lighting Convergence:Bluetooth Low Energy and visible light communication protocols are integrating with tactical illumination platforms, enabling remote activation and strobe pattern synchronization.
- Canadian Arctic Operations:Extreme cold-weather specifications for RCMP and Canadian Rangers units remain underserved, with battery chemistry and housing material gaps in current product portfolios.
Industry Challenges
- NATO Standardization Timelines:STANAG qualification protocols for weapon-mounted accessories extend development cycles 18-24 months, compressing competitive response windows.
- Optoelectronics Talent Scarcity:Thermal simulation and LED driver design expertise concentrates in consumer electronics sectors, forcing tactical manufacturers to compete for specialized engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Lights Market |
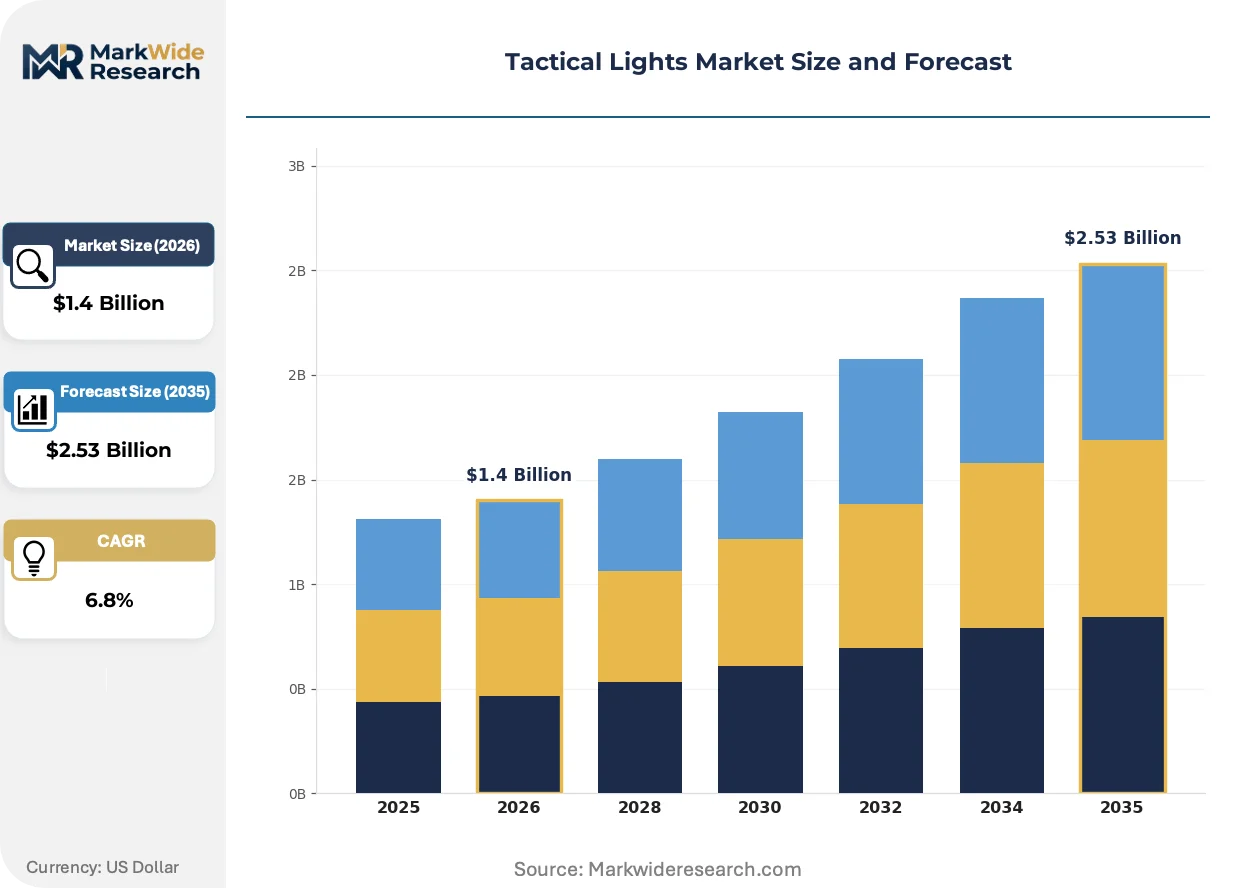
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Head-Mounted, Weapon-Mounted, Helmet-Mounted, Clip-On Technology: LED, OLED, Laser, Xenon, Incandescent Application: Military Operations, Law Enforcement, Search & Rescue, Outdoor Sports, Security Services End User: Defense Forces, Police Departments, Firefighters, Security Personnel, Outdoor Enthusiasts |
| Companies Covered | Fenix, Modlite, SureFire, Acebeam, Cloud Defensive, Streamlight, Nitecore, Armytek, Olight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Lights Market Trends and Innovations
Illumination platforms are evolving from standalone hardware into networked components of integrated soldier systems, with power management, data connectivity, and sensor fusion capabilities reshaping product architecture and procurement specifications.
Multi-spectrum LED arrays are integrating infrared, white light, and visible laser emitters within single housing configurations. Special operations units in NATO member states are adopting these consolidated platforms to reduce weapon rail congestion and power source fragmentation. This convergence is compressing supplier margins on standalone visible-light products while elevating system-level contract values.
REACH substance restrictions are forcing reformulation of potting compounds and conformal coatings used in LED driver electronics. German and French defense contractors now require full material disclosure documentation from component suppliers, extending qualification timelines but creating competitive moats for compliant manufacturers. The restriction most impacts mid-tier suppliers lacking in-house toxicology assessment capabilities.
Agency-level bulk purchasing agreements are consolidating procurement authority previously dispersed across municipal police departments. State-level cooperative contracts in the United States now capture 60% of law enforcement flashlight volume, displacing traditional distributor relationships and compressing price realization for manufacturers lacking direct government sales infrastructure. This concentration is most advanced in Texas, California, and Florida procurement systems.
Tactical Lights Market Segmentation
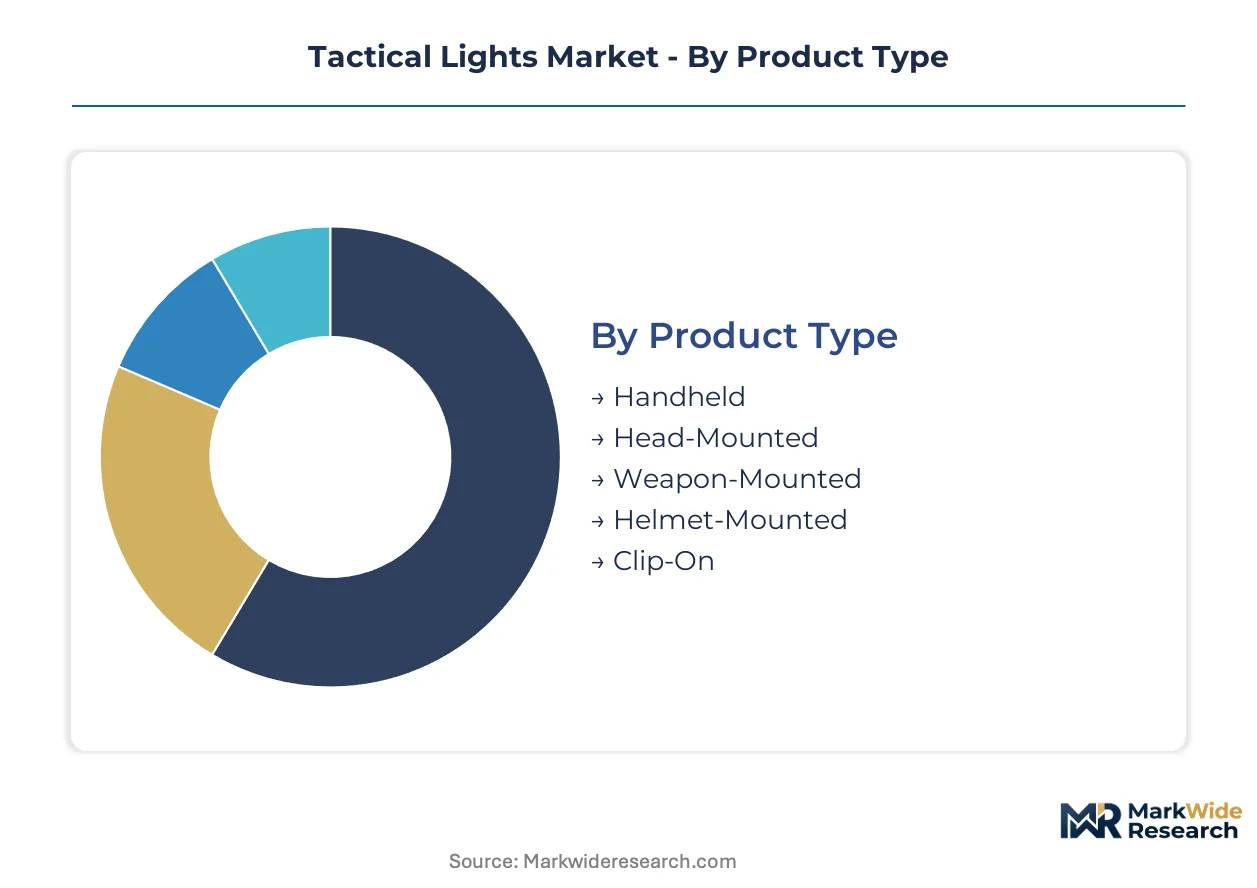
Segmentation in tactical lighting reveals how certification requirements, operational environments, and procurement channels fragment demand across distinct product architectures. Each dimension carries specific regulatory burdens that determine supplier qualification timelines and geographic market access.
Product Type:
STANAG qualification protocols apply exclusively to weapon-mounted and helmet-mounted configurations, while handheld units face lighter CE marking and FCC electromagnetic compliance burdens.
- Weapon-Mounted:Rail-integrated illumination systems engineered for Picatinny and NATO accessory interfaces, with recoil-rated electronics and shock-isolated LED emitters. Procurement concentrates in special operations units across the United States, Germany, and Australia, where NATO standardization agreements mandate night-vision compatibility and infrared co-alignment.
- Helmet-Mounted:Low-profile illumination modules with cable-routed power management and pivot-adjustable beam angles. Demand is climbing fastest among infantry modernization programs in the United States and Canada, driven by integrated soldier system architectures that consolidate power, data, and illumination on a single platform.
- Handheld:Compact duty lights with tail-cap switches and pocket-clip retention, dominating municipal police procurement in Texas, California, and Florida through state-level cooperative purchasing agreements.
- Head-Mounted:Strap-secured forehead illumination for search and rescue professionals requiring hands-free operation in confined spaces and vertical terrain.
- Clip-On:Universal-mount auxiliary lights attaching to existing equipment via MOLLE webbing or magnetic bases, popular among security personnel and outdoor enthusiasts seeking modular flexibility.
Leading the category by volume: Handheld. Growing fastest: Helmet-Mounted.
Technology:
Cost tiers separate mature LED platforms from emerging multi-spectrum arrays, with premium configurations commanding 3-4x price multiples over standard white-light emitters.
- LED:Solid-state illumination with 50,000-hour operational lifespan, thermal management via aluminum substrates, and programmable output modes. The technology anchors procurement across all defense and law enforcement channels, with RoHS compliance eliminating mercury-bearing alternatives from European supply chains.
- OLED:Organic emitter technology enabling conformal panel geometries and uniform surface illumination, currently limited to experimental pilot programs due to moisture sensitivity and output limitations below 200 lumens.
- Laser:Coherent light sources for target designation and infrared pointer functions, integrated into multi-spectrum weapon-mounted platforms alongside white-light emitters.
- Xenon:High-intensity discharge arc lamps with superior color rendering but fragile envelopes and high current draw, now restricted to legacy vehicle-mounted searchlights.
- Incandescent:Tungsten-filament technology with warm color temperature and simple electronics, retained only in budget-tier civilian markets and training-equipment procurement.
Cost structure stratifies sharply: LED occupies the standard-premium band, Laser commands specialty pricing, and Incandescent anchors the economy tier.
Application:
Customer maturity varies dramatically across use cases, with military and law enforcement buyers demanding full material disclosure and REACH documentation while outdoor sports purchasers prioritize retail availability and warranty terms.
- Military Operations:Combat-proven illumination for direct action, reconnaissance, and base security, with specifications dictated by U.S. Department of Defense and NATO standardization agreements. Volume concentrates in special operations equipment modernization budgets.
- Law Enforcement:Patrol-duty and tactical-team lighting with evidence-grade reliability documentation, procured through state-level cooperative contracts displacing traditional distributor relationships.
- Search & Rescue:Extended-runtime illumination for wilderness and urban disaster response, with waterproofing and cold-weather battery chemistry as critical selection criteria.
- Outdoor Sports:Consumer-oriented tactical styling with lower durability ratings, distributed through sporting goods retailers and e-commerce channels.
- Security Services:Private guard and facility protection lighting, price-sensitive with minimal certification requirements beyond basic CE marking.
Margins concentrate in: Military Operations. Volume concentrates in: Law Enforcement.
End User:
Supply-side concentration mirrors the geographic clustering of qualified manufacturers, with defense forces and police departments sourcing predominantly from U.S. and German suppliers while outdoor enthusiasts access broader Asian manufacturing.
- Defense Forces:National military procurement with multi-year indefinite-delivery contracts, STANAG qualification requirements, and congressional or parliamentary oversight of supplier selection.
- Police Departments:Municipal and state-level agency purchasing with cooperative contract aggregation, liability-driven reliability specifications, and training-integration requirements.
- Firefighters:Structural and wildland response units requiring intrinsically safe ratings and high-visibility beam patterns for smoke-filled environments.
- Security Personnel:Private sector guarding services with cost-optimized procurement and minimal technical specification beyond lumen output claims.
- Outdoor Enthusiasts:Individual consumers purchasing through retail and direct-to-consumer channels, responsive to brand heritage and online review sentiment.
Procurement authority centralizes in: Defense Forces. Fastest channel expansion: Outdoor Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense modernization incentives in the United States, Germany, and Australia concentrate procurement authority for tactical illumination systems, while REACH compliance costs and RoHS transitions reshape European supplier qualification timelines.
United States
Special operations equipment budgets at the Department of Defense drive volume for helmet-mounted and weapon-mounted LED systems. The FCC regulates radio-enabled smart lighting features emerging in premium tactical product lines. Manufacturing clusters in Texas and California supply state-level cooperative contracts capturing sixty percent of law enforcement flashlight procurement.
Germany
Bundeswehr infantry modernization programs prioritize night-vision compatible illumination suites for EF88 rifle platforms. The EU RoHS directive and REACH chemical registration requirements constrain material choices and extend qualification timelines for LED driver electronics. Industrial concentration in Bavaria and Baden-Württemberg hosts defense contractors demanding full material disclosure documentation from component suppliers.
Australia
Accelerated Australian Defence Force procurement timelines for special operations equipment create immediate demand for weapon-mounted systems. The country's national defense regulator mandates compatibility with EF88 rifles and NATO standardization agreements. Manufacturing activity clusters in Victoria and New South Wales, where local suppliers compete for integration into integrated soldier system architectures.
Canada
RCMP and Canadian Rangers units generate underserved demand for extreme cold-weather tactical specifications. Health Canada and national defense procurement standards govern battery chemistry and housing material requirements for Arctic operations. Industrial capacity concentrates in Ontario and Quebec, where suppliers address gaps in current product portfolios for sub-zero operational environments.
United Kingdom
Ministry of Defence special forces equipment budgets sustain demand for multi-spectrum LED arrays consolidating infrared and white-light emitters. CE marking and post-Brexit UKCA certification requirements regulate electromagnetic compliance for tactical electronics. Defense industrial activity clusters in the Midlands and South East England, where contractors integrate illumination platforms into networked soldier systems.
Tactical Lights Market Competitive Landscape
Top-tier vendors anchor military and law enforcement procurement channels, while mid-tier specialists compete on value-engineered handheld units and compact rechargeable systems. The vendor base stratifies across three tiers: legacy defense contractors with STANAG qualification heritage, consumer-electronics crossovers leveraging LED manufacturing scale, and emerging specialists in multi-spectrum and smart-connected platforms. Dominant competitive moves include backward integration into LED emitter and battery cell supply chains, plus geographic expansion into Australian and Canadian defense procurement windows.
Within the premium defense-contractor tier, SureFire and Streamlight exemplify contrasting strategic positions. SureFire occupies a heritage-anchored position sustaining military contract relationships, while Streamlight represents value-engineered competition targeting aggregated law enforcement purchasing agreements. Nitecore sits within the compact-system specialist archetype, capturing search and rescue demand through rechargeable head-mounted configurations. These three California and Pennsylvania-based entities illustrate how geographic proximity to U.S. defense procurement hubs shapes competitive access.
| Leading Market Players |
|---|
| Fenix |
| Modlite |
| SureFire |
| Acebeam |
| Cloud Defensive |
| Streamlight |
| Nitecore |
| Armytek |
| Olight |
| Others |
Pricing and Supply Chain Analysis
LED emitter miniaturization and thermal substrate manufacturing consolidation are compressing unit economics while concentrating bargaining power among Asian substrate suppliers, forcing Western assemblers to absorb margin pressure or accelerate backward integration into driver electronics.
Pricing Analysis
Lead-time premiums command substantial markups for STANAG-qualified weapon-mounted systems with sub-12-week delivery, while spot inventory of handheld duty lights trades at discounts through state cooperative contract channels. Three-tier pricing structure across premium, standard, and economy levels separates military-grade multi-spectrum arrays from law enforcement duty lights and civilian outdoor units. Cost compression in the standard tier is intensifying because polymer housing advances are eroding aluminum's durability premium. Outdoor enthusiasts exhibit highest price sensitivity, while special operations procurement shows near-zero elasticity for mission-critical illumination suites.
Supply Chain Analysis
Domestic-content mandates in Australian and Canadian defense procurement are reshaping sourcing patterns, compelling manufacturers to establish final assembly in Victoria and Ontario to qualify for EF88 rifle integration and Arctic operations contracts. LED die production concentrates in Taiwan, South Korea, and Japan, while lithium-ion cell fabrication draws from Chinese and South Korean manufacturing clusters. Battery chemistry and thermal interface materials face single-source vulnerability from East Asian electrolyte suppliers. Distribution runs through defense prime contractors for military channels and cooperative purchasing aggregators for law enforcement procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive control over LED driver design and battery pack assembly determines margin retention against polymer housing commoditization.
For Market Incumbents: Anchor military contract relationships through accelerated STANAG qualification timelines for multi-spectrum platforms, while defending law enforcement share via direct state cooperative contract participation that displaces distributor intermediaries. Threat: Mid-tier polymer housing specialists are eroding aluminum's durability premium through composite advances. Lever: Backward integration into thermal substrate sourcing from Taiwanese suppliers. For New Entrants and Emerging Players: The price-point gap between premium multi-spectrum weapon-mounted systems and economy handheld units creates immediate white-space opportunity in compact rechargeable head-mounted configurations for search and rescue professionals. Target Canadian Arctic operations with extreme cold-weather battery chemistry specifications that incumbent portfolios underserve. Go-to-market angle: Direct procurement relationships with provincial emergency response agencies bypassing federal defense qualification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime contractor acquisition of multi-spectrum platform specialists and private equity rollup of mid-tier handheld manufacturers serving cooperative contract channels. Long-term viability hinges on regulatory compliance capabilities spanning REACH substance documentation and FCC radio-enabled feature certification. Acquisition target archetype: LED driver electronics designers with in-house thermal simulation capacity. Signal to watch: Battery chemistry export control expansions from East Asian manufacturing jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG Qualification Acceleration | Compresses 18-24 month development cycles to capture Australian Defence Force procurement windows. |
| Backward Integration into LED Drivers | Captures margin from thermal substrate suppliers while meeting REACH documentation requirements. |
| Arctic Specification Development | Addresses RCMP and Canadian Rangers demand gaps with cold-weather battery chemistry. |
| State Cooperative Contract Direct Sales | Bypasses distributor compression in Texas, California, and Florida law enforcement procurement. |
| Multi-Spectrum Platform Convergence | Consolidates infrared, white-light, and laser emitters to reduce weapon rail congestion. |
Research Methodology
Multi-period observation of defense procurement award announcements, state cooperative contract aggregations, and LED component trade flows anchored the trend analysis, supplemented by interviews with special operations equipment officers, law enforcement procurement managers, polymer composite R&D directors, and thermal substrate manufacturing executives. Secondary validation drew from U.S. Department of Defense budget justification documents, NATO standardization agreement repositories, EU REACH substance registration databases, and FCC equipment authorization filings. Bottom-up segment sizing triangulated against top-down defense modernization budget allocations.
Input-output matrices modeled unit demand across product type, technology tier, application severity, and end-user procurement authority dimensions over the projection horizon. CAGRs were derived from segment-level growth rate differentials weighted by base-period revenue contributions. Industry-specific forecast inputs incorporated STANAG qualification pipeline visibility and polymer housing material substitution elasticities.
Inputs from defense procurement databases and component trade registries were available through the study window; gaps in special operations equipment deployment timelines introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions regarding NATO standardization timeline adherence and REACH substance restriction enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Smart Police Helmet Market
Physical Security
Global Wearable Security Device Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Security Market
Physical Security
Europe Physical Security Market
Physical Security
Physical Security Equipment Market
Physical Security
Security Guard Market
Physical Security
Body Armor Market
Physical Security
Body Armor Plates Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Policing Technologies Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Tactical Vests Market
Physical Security
Europe Cargo Inspection Market